
 Military Fire Control Systems Market | 2026-2036
Military Fire Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Fire Control Systems Market Foresight
Multi-source integration of sensor-to-shooter architectures is pivoting toward consolidated prime-contractor ecosystems. Lockheed Martin leverages its vertically integrated sensor production to dominate naval Aegis combat system upgrades. BAE Systems anchors European land-platform fire control through its Challenger and CV90 integration programs. Rheinmetall competes on next-generation artillery digitization, extending its footprint in NATO standardization committees.
Military fire control systems encompass electro-optical, radar, and computing subsystems that calculate ballistic solutions and command weapon release in real time. These platforms typically operate within millisecond latency requirements across infrared, millimeter-wave, and laser rangefinding modalities to ensure first-round hit probability against moving targets. Missile guidance systems and targeting systems command the deepest program budgets, with software-defined solutions representing the fastest-expanding technology layer as armed forces prioritize algorithmic retargeting and electronic counter-countermeasure resilience. Optical sensors retain entrenched positions in close-combat applications where radio-frequency emissions must remain suppressed.
The US Department of Defense mandates MIL-STD-6016 and MIL-STD-6020 interoperability protocols, while NATO STANAG 5602 shapes transatlantic data-link compatibility for coalition operations. The EU AI Act and emerging European Defence Fund requirements are beginning to constrain autonomous targeting algorithm deployments, creating compliance costs for software-intensive suppliers. Stakeholders must weigh sovereign technology access against alliance interoperability commitments when selecting development partners and export markets.
Market Dynamics
Sensor-to-shooter latency compression is forcing prime contractors to consolidate electro-optical, radar, and computing subsystems under unified architectures, eroding modular procurement preferences across naval and land-platform programs.
Growth Catalysts
- NATO STANAG 5602 Mandates:Transatlantic data-link compatibility requirements are accelerating platform modernization cycles across European member states, creating sustained retrofit demand for legacy combat systems.
- Indo-Pacific Maritime Disputes:Territorial tensions are driving procurement of over-the-horizon targeting suites by naval surface combatant fleets in Japan, Australia, and regional allies.
- Software-Defined Architectures:Algorithmic retargeting and electronic counter-countermeasure resilience are commanding expanded R&D budgets within missile guidance and targeting system programs.
Market Restraints
- Export Control Regimes:ITAR restrictions and national technology protection frameworks constrain cross-border subsystem integration, fragmenting supplier ecosystems.
- Specialized Component Scarcity:Indium gallium arsenide focal plane arrays and cryocooled infrared detectors face concentrated sourcing from limited qualified foundries.
- EU AI Act Constraints:Autonomous targeting algorithm deployments face emerging compliance burdens, extending development timelines for software-intensive fire control solutions.
Strategic Opportunities
- Unmanned Platform Integration:Crewless surface vessels and loitering munitions are creating demand for miniaturized fire control computers with reduced thermal and power signatures.
- European Defence Fund Allocation:Collaborative procurement mechanisms are channeling capital toward next-generation artillery digitization programs across NATO continental members.
- Laser Rangefinding Convergence:Coherent beam combining with machine vision is opening close-combat applications where radio-frequency emissions require suppression.
Industry Challenges
- MIL-STD-6016 Certification Burden:Interoperability protocol validation demands extended testing cycles, compressing margin for fixed-price development contracts.
- Legacy System Integration Friction:Analog-to-digital interface bridging for 1980s-era combat systems consumes engineering resources without advancing competitive differentiation.
- Secure Software Supply Chains:CMMC and equivalent cyber certification requirements are forcing subsystem vendors to rearchitect development environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Fire Control Systems Market |
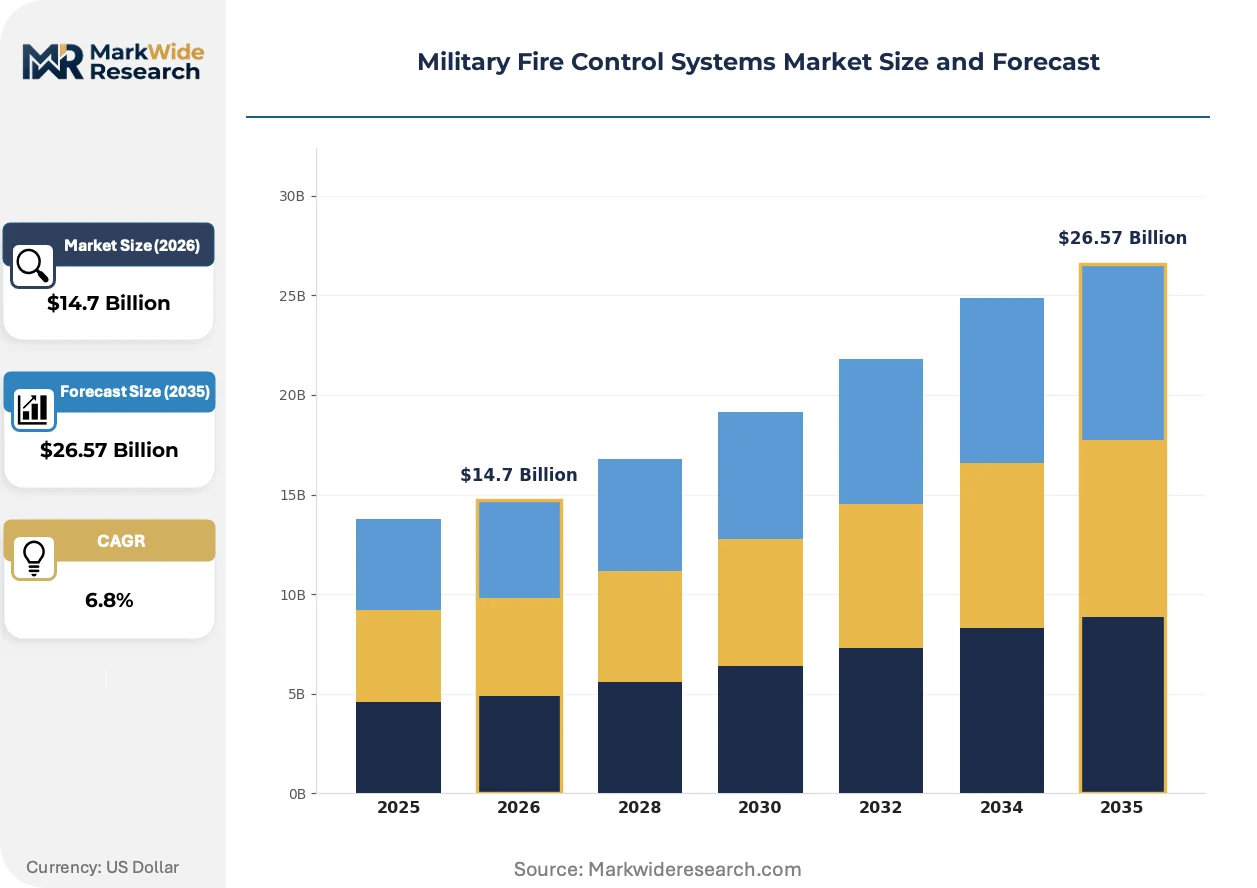
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gun Control Systems, Missile Guidance Systems, Targeting Systems, Fire Direction Systems Technology: Optical Sensors, Radar Systems, Laser Systems, Software-Defined Solutions End User: Army, Navy, Air Force, Special Operations Forces Application: Combat Operations, Training Simulators, Tactical Support, Surveillance |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems plc, Thales Group, Leonardo S.p.A., General Dynamics Corporation, Elbit Systems Ltd., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Fire Control Systems Market Shifts & Advancements
Artificial intelligence inference at the tactical edge is compressing sensor-to-shooter timelines from seconds to milliseconds, while regulatory frameworks struggle to govern autonomous decision loops.
Embedded GPU clusters running neural network-based target classification are rewriting engagement authority workflows. Naval combat system integrators are deploying these accelerators within Aegis architecture upgrades. Real-time multi-hypothesis tracking is displacing rule-based correlation algorithms in high-clutter environments.
The EU AI Act's risk classification for autonomous weapons systems is imposing documentation and human-oversight mandates on algorithm development. European prime contractors are restructuring software teams to segregate civilian from military AI pipelines. Land-platform programs in Germany and France face the steepest compliance cost escalation.
Defense ministries are unbundling hardware procurement from software sustainment, creating recurring revenue pools for algorithm update subscriptions. Traditional system integrators are responding by establishing captive software divisions. This pattern is most visible in United States Navy programs, where OTA contracting vehicles accelerate vendor rotation.
Military Fire Control Systems Market Segmentation
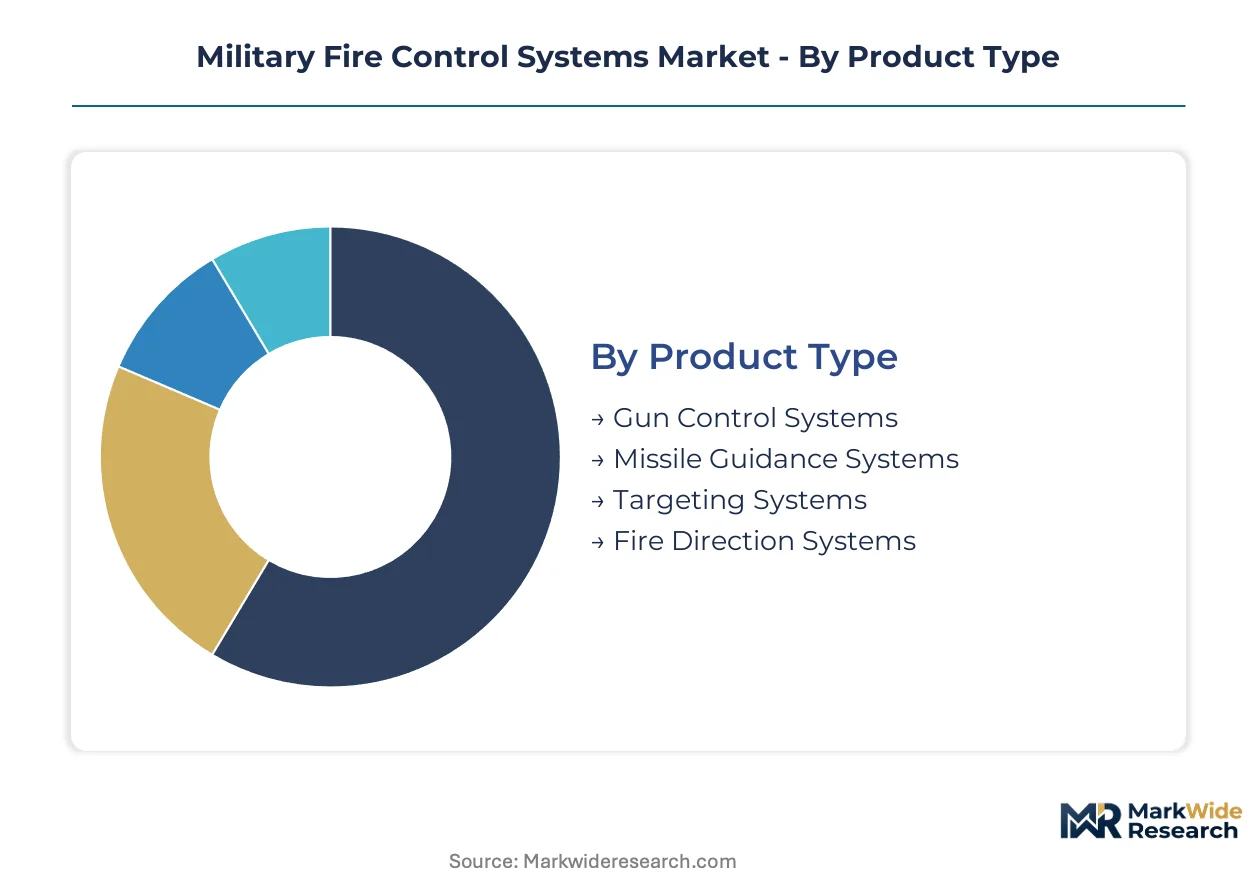
Fire control systems fragment across product architectures, sensing modalities, service branches, and operational contexts. Each dimension carries distinct procurement cycles, technical specifications, and compliance burdens that reshape supplier positioning.
Product Type:
Supply concentration tilts toward integrated platforms where prime contractors bundle hardware, software, and sustainment under single-contractor accountability.
- Missile Guidance Systems:Inertial measurement units coupled with GPS-denied navigation algorithms command program budgets across naval and air-launched platforms. The US Navy's Aegis modernization and Japan's surface combatant fleet drive sustained investment in over-the-horizon targeting suites.
- Targeting Systems:Electro-optical and laser rangefinding subsystems calculate ballistic solutions with millisecond latency for moving-target engagement. Australian naval expansion and NATO STANAG 5602 retrofit mandates concentrate demand for interoperable targeting suites.
- Gun Control Systems:Direct-fire artillery and naval gun mount servomechanisms integrate fire direction computers with stabilized platforms.
- Fire Direction Systems:Network-centric command nodes coordinate distributed battery fires through standardized data links.
Missile guidance systems absorb the bulk of installed capacity; targeting systems are expanding most quickly.
Technology:
Cost stratification separates legacy hardware procurement from software-intensive development, with algorithmic solutions commanding premium sustainment contracts.
- Software-Defined Solutions:Algorithmic retargeting and electronic counter-countermeasure resilience operate on embedded GPU clusters with neural network-based target classification. The US Department of Defense's OTA contracting vehicles accelerate vendor rotation in this layer.
- Optical Sensors:Indium gallium arsenide focal plane arrays and cryocooled infrared detectors enable passive targeting in radio-frequency-denied environments. Special Operations Forces procurement emphasizes thermal signature suppression for close-combat applications.
- Radar Systems:Millimeter-wave and active electronically scanned arrays provide all-weather target acquisition for naval and air defense platforms.
- Laser Systems:Coherent beam combining with machine vision opens precision rangefinding applications where emission control is mandatory.
Optical sensors retain entrenched positions in legacy platforms; software-defined solutions are climbing the fastest.
End User:
Volume concentration follows naval modernization cycles in the Indo-Pacific, while land-platform digitization spreads across European NATO members.
- Navy:Integrated combat system suites for surface combatants require MIL-STD-6016 interoperability certification. Fleets in the United States, Japan, and Australia anchor procurement for over-the-horizon fire control.
- Army:Next-generation artillery digitization programs in Germany and France prioritize NATO STANAG 5602 data-link compatibility. BAE Systems and Rheinmetall anchor European land-platform integration.
- Air Force:Aircraft-mounted targeting pods and precision-guided munitions integration demand compact, high-reliability computing.
- Special Operations Forces:Miniaturized fire control computers with reduced thermal and power signatures support crewless platforms and loitering munitions.
Navy programs absorb the bulk of installed capacity; Special Operations Forces applications are gaining share fastest.
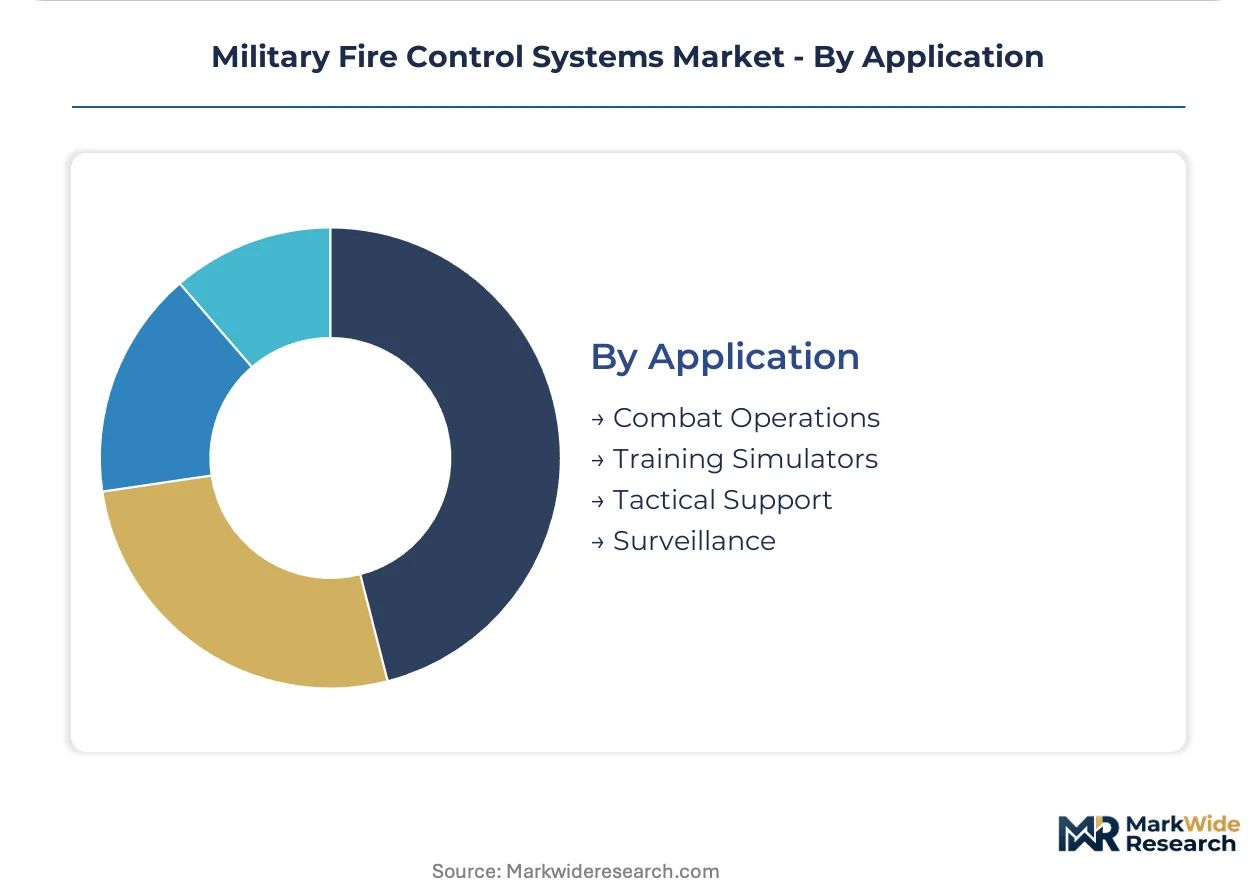
Application:
Margin differentiation separates operational deployment from training infrastructure, with combat systems commanding full certification overhead.
- Combat Operations:Real-time sensor-to-shooter architectures with algorithmic engagement authority face EU AI Act compliance burdens for autonomous targeting. European prime contractors segregate military AI pipelines to satisfy documentation and human-oversight mandates.
- Training Simulators:Synthetic environments replicate fire control workflows without live-fire certification requirements. Defense ministries unbundle hardware procurement from software sustainment, creating recurring revenue pools for algorithm update subscriptions.
- Tactical Support:Forward observer and fire direction center equipment prioritizes interoperability over standalone capability.
- Surveillance:Persistent target tracking and multi-hypothesis correlation in high-clutter environments demand edge-processing architectures.
Combat operations absorb the bulk of installed capacity; training simulators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval modernization programs in the Indo-Pacific corridor concentrate procurement volumes for integrated fire control suites, while European NATO members accelerate land-platform digitization under standardization mandates.
United States
The US Navy's Aegis combat system upgrades and surface combatant fleet expansion drive sustained demand for over-the-horizon targeting capabilities. MIL-STD-6016 and MIL-STD-6020 interoperability protocols mandate extended certification cycles for subsystem suppliers. The Washington-Baltimore defense corridor hosts prime contractors consolidating electro-optical, radar, and computing architectures under unified program accountability.
Japan
Maritime territorial disputes are accelerating procurement of integrated fire control suites for naval surface combatants. The country's defense ministry channels investment toward sensor-to-shooter latency compression for moving-target engagement. Industrial clusters in the Kanto region around Tokyo anchor subsystem integration for next-generation destroyer programs.
Australia
Naval fleet expansion under the AUKUS security pact is concentrating demand for interoperable targeting systems compatible with allied data links. The national defense strategy prioritizes over-the-horizon capabilities for Indo-Pacific operational contingencies. Shipbuilding hubs in South Australia and Western Australia are integrating foreign subsystem suppliers into domestic combat system assembly.
Germany
Next-generation artillery digitization programs prioritize NATO STANAG 5602 data-link compatibility for coalition operations. The EU AI Act imposes documentation and human-oversight mandates on autonomous targeting algorithm development. Defense industrial concentrations in Bavaria and North Rhine-Westphalia are restructuring software teams to segregate military from civilian AI pipelines.
France
Land-platform fire control modernization under the European Defence Fund is channeling capital toward collaborative procurement mechanisms. Emerging regulatory frameworks constrain autonomous targeting deployments, extending development timelines for software-intensive solutions. The Île-de-France region around Paris hosts prime contractors navigating compliance costs while advancing algorithmic retargeting capabilities.
Military Fire Control Systems Market Competitive Landscape
Consolidation of electro-optical, radar, and computing subsystems under unified architectures dominates the current landscape, eroding modular procurement preferences across naval and land-platform programs. The vendor base stratifies between vertically integrated primes controlling captive sensor production and specialized subsystem suppliers competing on certification speed. Three archetypes occupy distinct positions: naval combat system integrators leveraging Aegis upgrade cycles, European land-platform specialists anchoring NATO standardization committees, and software-defined solution vendors exploiting OTA contracting acceleration. M&A activity and strategic partnerships represent the dominant competitive moves as primes acquire algorithmic capabilities and subsystem vendors seek scale for certification overhead absorption.
Among US-based defense primes, Lockheed Martin Corporation and RTX Corporation occupy positions exemplifying vertically integrated naval combat system dominance, while BAE Systems plc represents the European land-platform integration archetype. These entities anchor the competitive structure through their control of major platform upgrade cycles and standardization committee influence, with their geographic distribution reflecting the transatlantic split in procurement concentration between Indo-Pacific naval modernization and European artillery digitization priorities.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Thales Group |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| Rheinmetall AG |
| Others |
Supply & Pricing Matrix
Captive sensor production by vertically integrated primes anchors both supply security and pricing power across naval and land-platform programs. Lockheed Martin's in-house electro-optical manufacturing and BAE Systems' controlled computing subsystem pipelines demonstrate how backward integration insulates margin positions from component scarcity while commanding premium contract terms.
Pricing Analysis
Extended software sustainment bundling now separates premium-tier contracts from unbundled hardware-only procurement. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-STD-6016 certification grade and algorithm update subscription depth. Price differentiation hinges on human-oversight documentation for EU AI Act compliance and embedded GPU cluster performance. Cost compression in economy-tier legacy retrofits is intensifying because qualified foundry capacity for cryocooled infrared detectors remains constrained. Special Operations Forces procurement exhibits highest price sensitivity due to miniaturization requirements; naval combat system integrators show lowest sensitivity given platform-critical mission profiles.
Supply Chain Analysis
Single-source vulnerability sits with United States, Germany, and Japan for qualified foundry production of indium gallium arsenide focal plane arrays and cryocooled infrared detectors. Raw material dependencies draw from gallium arsenide substrates, precision optical glass, and rare-earth magnet alloys for stabilized platform servomechanisms. Supply chain risk centers on ITAR regulatory restriction fragmenting cross-border subsystem integration. Distribution runs through prime-contractor-dominated program offices with direct military procurement authority, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where cryocooled infrared detector foundry scarcity props pricing across all tiers. Foundry qualification timelines extending beyond typical procurement cycles create structural capacity bottlenecks that incumbent primes exploit.
For Market Incumbents: Hedge against algorithmic disruption by acquiring embedded GPU cluster specialists before OTA contracting vehicles accelerate vendor rotation. Lockheed Martin's Aegis upgrade dominance and BAE Systems' Challenger integration programs illustrate how certification speed defends position against software-defined challengers. Prioritize NATO STANAG 5602 committee influence to shape interoperability mandates that favor integrated architectures over modular alternatives. For New Entrants and Emerging Players: The premium-to-economy price gap in training simulator software sustainment offers accessible entry without live-fire certification overhead. White-space targets include miniaturized fire control computers for crewless surface vessels and algorithm update subscriptions unbundled from hardware procurement. European Defence Fund collaborative mechanisms provide the most penetrable channel for continental NATO artillery digitization programs. Go-to-market positioning should emphasize EU AI Act compliance documentation as a differentiator against software-intensive incumbents restructuring pipelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated primes seeking algorithmic capabilities or scale for certification overhead absorption. Long-term viability favors subsystem vendors with demonstrated MIL-STD-6016 validation speed and captive foundry relationships. Target acquisition profile: mid-tier electro-optical specialists with indium gallium arsenide focal plane array production qualified for defense applications. Watch AUKUS procurement acceleration as the signal indicating Indo-Pacific naval modernization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Capability Acquisition | Embedded GPU cluster specialists enable neural network-based target classification for Aegis upgrades. |
| Foundry Capacity Expansion | Qualified cryocooled infrared detector production addresses single-source vulnerability in United States and Germany. |
| NATO Standardization Committee Engagement | STANAG 5602 influence shapes transatlantic data-link compatibility mandates favoring integrated architectures. |
| Software Sustainment Unbundling | Recurring revenue pools for algorithm update subscriptions separate from hardware procurement cycles. |
| EU AI Act Compliance Infrastructure | Documentation and human-oversight pipelines satisfy emerging regulatory constraints on autonomous targeting. |
Research Methodology
Defense procurement databases, NATO standardization committee filings, and SEC 10-K disclosures from listed primes formed the secondary backbone for market sizing. Primary interviews with naval combat system program managers, artillery digitization procurement officers, electro-optical subsystem engineering directors, and military AI compliance specialists validated demand assumptions. Bottom-up triangulation across platform upgrade cycles and top-down cross-check against defense budget appropriations anchored volume estimates.
Historical trendline analysis of Aegis modernization spending patterns and European artillery replacement cycles informed baseline trajectory development. Segmentation modeling spanned product architecture, sensing modality, service branch, and operational context across the projection horizon. CAGRs derived from weighted platform procurement schedules and software sustainment contract renewal rates. Forecast inputs included Indo-Pacific naval fleet expansion timelines and European Defence Fund allocation mechanisms.
Inputs from defense procurement databases and prime contractor disclosures were available through the study window; gaps in classified program budget detail introduce uncertainty bands around naval combat system estimates. Forecasts reflect assumptions regarding NATO interoperability mandate adherence and AUKUS technology transfer progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Airborne Weapon System Market