
 Rescue Hoist System Market | 2026-2036
Rescue Hoist System Market Size, Share, and Industry Trends Forecast 2026-2036
Rescue Hoist System Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts as operators seek to extend airframe life cycles. Konecranes leverages its crane service infrastructure to cross-sell hoist inspection and overhaul programs. Collins Aerospace sustains its position through proprietary cable tension monitoring systems integrated across military platforms. RUAG Group anchors European defense aftermarket share with national service agreements in Switzerland and Germany.
A rescue hoist system is a powered lifting apparatus mounted on rotary-wing aircraft, typically rated for loads exceeding 272 kg and equipped with anti-two-block devices and hydraulic or electric drive trains, designed to extract personnel from terrain inaccessible to ground vehicles. Electric hoists command the largest product type position due to their precision control during medical evacuations, while synthetic rope technology displaces wire rope in saltwater environments where corrosion resistance determines operational readiness. The military end user segment carries the deepest specification requirements, driving multi-source qualification protocols that limit supplier turnover.
The FAA mandates hoist system certification under 14 CFR Part 29 airworthiness standards, while EASA enforces CS-29 compliance across European operators, and the EU AI Act introduces algorithmic safety requirements for automated load stabilization features. These frameworks elevate barriers for unproven entrants and compel incumbents to maintain dual-certification engineering teams. Stakeholders must monitor emerging mandates for synthetic rope traceability and blockchain-based maintenance logging as regulators tighten equipment pedigree requirements.
Market Dynamics
Electric drive trains are displacing hydraulic systems across military and civilian rotorcraft fleets, forcing incumbent suppliers to re-engineer certification pathways while opening procurement to non-traditional component vendors.
Growth Catalysts
- 14 CFR Part 29 Airworthiness Standards:The FAA's updated helicopter hoist certification mandates accelerate equipment replacement cycles among US-based emergency medical service operators.
- Synthetic Rope Technology:Saltwater corrosion resistance requirements in maritime search-and-rescue operations drive specification shifts away from traditional wire rope configurations.
- NATO Fleet Modernization:Multi-source qualification protocols across member states expand addressable demand for qualified hoist system manufacturers.
Market Restraints
- Dual-Certification Engineering Burden:Simultaneous compliance with FAA Part 29 and EASA CS-29 standards inflates development overhead for platform-agnostic suppliers.
- Specialized Cable Manufacturing Concentration:High-performance synthetic rope production clusters among limited European and North American textile engineering facilities.
- Algorithmic Safety Validation Costs:The EU AI Act's requirements for automated load stabilization systems impose unproven testing protocols without established precedent.
Strategic Opportunities
- Predictive Maintenance Contracts:Airframe life extension priorities among civilian operators create recurring revenue streams independent of new equipment sales.
- Blockchain-Based Maintenance Logging:Emerging regulatory interest in equipment pedigree traceability positions early adopters for compliance advantage.
- Medical Evacuation Precision Control:Electric hoist architectures enable load stabilization features that command premium positioning in hospital helipad operations.
Industry Challenges
- Qualified Technician Scarcity:Hydraulic-to-electric transition outpaces available training infrastructure for field-level overhaul capabilities.
- Legacy Platform Integration Complexity:Retrofit certification for aging military airframes requires engineering resources that compete with new platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rescue Hoist System Market |
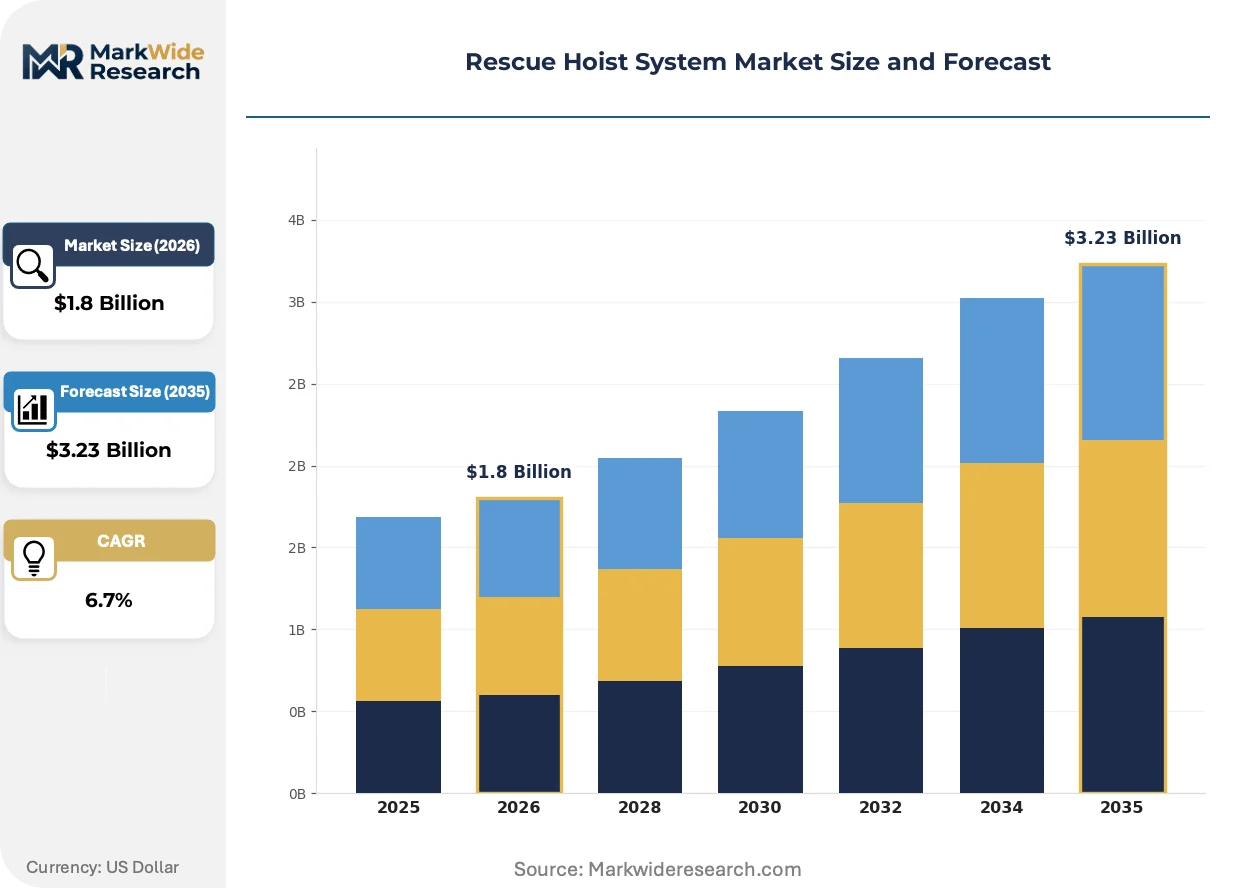
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Hoists, Electric Hoists, Pneumatic Hoists, Hydraulic Hoists End User: Military, Emergency Services, Fire Departments, Industrial Sector Technology: Wire Rope, Synthetic Rope, Chain, Webbing Application: Rescue Operations, Medical Evacuations, Firefighting, Marine Rescue |
| Companies Covered | Konecranes, KITO Corporation, Hitachi, Breeze-Eastern, RUAG Group, Ingersoll Rand, SWF Krantechnik, Collins Aerospace, Columbus McKinnon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rescue Hoist System Market Evolving Landscape
Active load monitoring and autonomous stabilization features are redefining operational safety margins. Equipment specifications now emphasize real-time data feedback over mechanical redundancy alone.
Synthetic rope construction is migrating from experimental maritime applications to mainstream military procurement. Naval aviation units in saltwater environments specify fiber-based cables for corrosion immunity. This transition compresses supplier qualification timelines as traditional wire rope manufacturers face capability gaps.
EASA's CS-29 compliance framework tightens algorithmic safety requirements for automated rescue systems. Manufacturers must demonstrate fail-safe behaviors under sensor-degradation scenarios. Military end-users in Europe absorb the longest certification delays as dual-use technology controls intersect with aviation safety mandates.
Service contract structures now unbundle predictive maintenance from traditional time-based overhaul schedules. Civilian emergency medical operators in the United States negotiate availability-based agreements that transfer operational risk to OEM service networks. This reconfiguration shifts revenue recognition patterns and capital deployment priorities across the supplier base.
Rescue Hoist System Market Segmentation
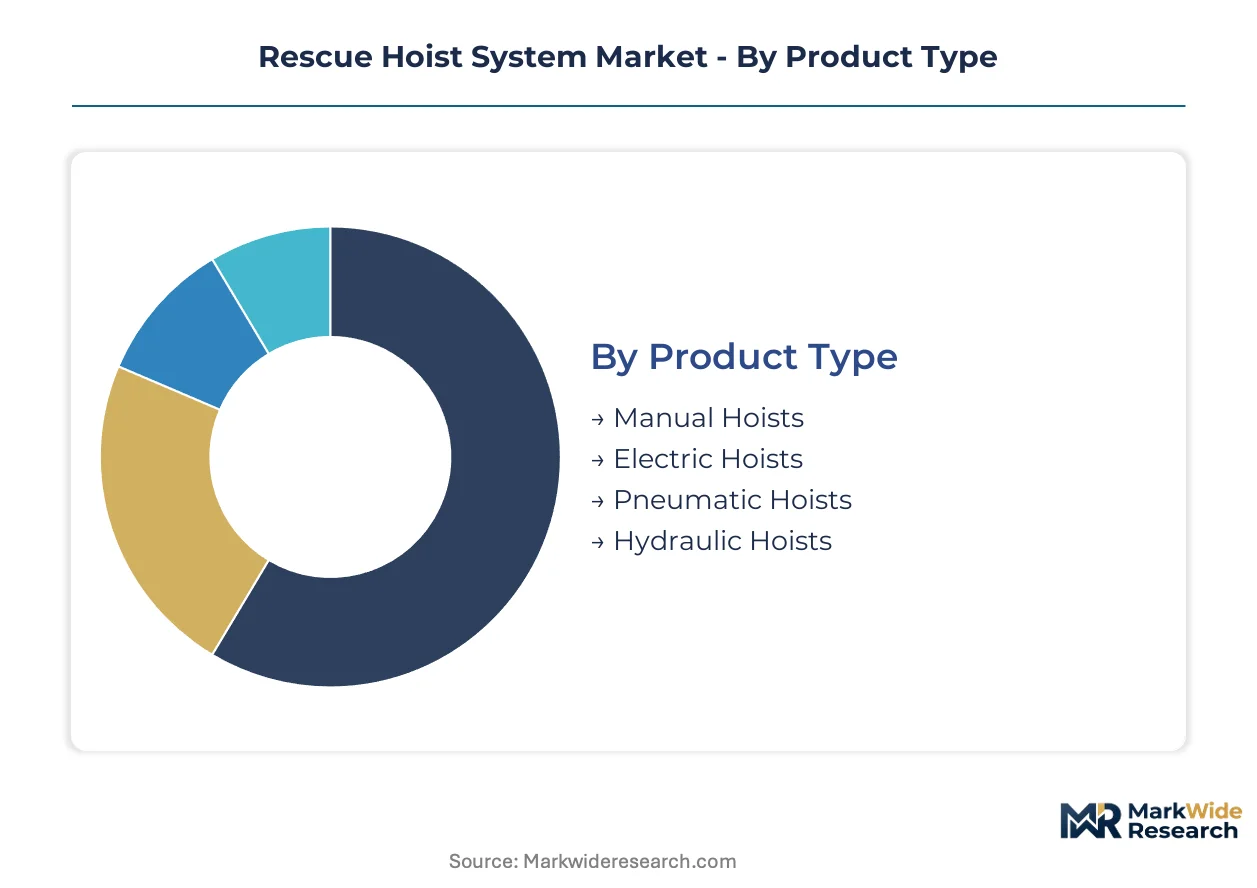
Segmentation in the rescue hoist system market reveals how procurement specifications diverge across mission profiles and operating environments. Electric drive architectures and synthetic rope materials are redefining competitive positioning within each category as operators prioritize precision control and corrosion resistance.
Product Type:
Cost tier stratification separates entry-level mechanical systems from precision-engineered electric platforms with integrated load monitoring.
- Electric Hoists:These systems deploy brushless DC motors with closed-loop feedback control, achieving positioning accuracy within centimeters during patient extraction. United States emergency medical service fleets specify electric architectures for hospital helipad operations where vibration minimization protects spinal injury patients.
- Hydraulic Hoists:Legacy military platforms continue specifying hydraulic power trains for their established reliability in extreme temperature ranges. NATO fleet modernization programs are accelerating replacement timelines as dual-certification requirements with EASA CS-29 standards inflate engineering overhead for hydraulic system redesign.
- Manual Hoists:Backup mechanical systems for equipment failure scenarios.
- Pneumatic Hoists:Compressed-air drive trains for explosion-risk industrial environments.
Electric hoists hold installed capacity. Hydraulic hoists are rotating up the share rankings as military procurement prioritizes proven reliability.
End User:
Application context determines specification stringency, with medical evacuation protocols demanding precision unavailable in industrial lifting scenarios.
- Military:Multi-source qualification protocols mandate redundant suppliers for each platform program. United States Army and Navy search-and-rescue procurement requires anti-two-block devices, synthetic rope compatibility, and electromagnetic interference shielding for joint operations with communications equipment.
- Emergency Services:Civilian helicopter emergency medical services in the United States negotiate availability-based service contracts that transfer operational risk to OEM networks. FAA Part 29 certification mandates accelerate replacement cycles among operators with aging wire rope configurations.
- Fire Departments:Urban aerial rescue from high-rise structures.
- Industrial Sector:Offshore platform personnel transfer and maintenance lifting.
Military end users hold installed capacity. Emergency services are climbing the fastest as civilian fleet electrification accelerates.
Technology:
Material science advances are displacing traditional wire rope in saltwater environments where corrosion resistance determines operational readiness.
- Synthetic Rope:High-modulus polyethylene fiber constructions achieve strength-to-weight ratios exceeding steel while eliminating corrosion in maritime search-and-rescue operations. Naval aviation units in saltwater environments now specify fiber-based cables as primary equipment, compressing supplier qualification timelines as traditional wire rope manufacturers face capability gaps.
- Wire Rope:Galvanized and stainless steel configurations retain dominance in high-heat firefighting applications where synthetic materials risk thermal degradation. European military procurement continues mandating wire rope for cargo hoisting where abrasion resistance outweighs weight penalties.
- Chain:Heavy-lift industrial applications with positive engagement requirements.
- Webbing:Lightweight patient extraction slings and temporary anchor systems.
Wire rope holds installed capacity. Synthetic rope is gaining share fastest as maritime specifications harden.
Application:
Volume concentration aligns with regulatory enforcement intensity, where airworthiness mandates drive equipment refresh cycles.
- Medical Evacuations:Hospital helipad operations demand electric hoist precision for spinal injury patient handling. United States emergency medical operators absorb premium pricing for load stabilization features that reduce secondary trauma during extraction.
- Marine Rescue:Saltwater corrosion requirements specify synthetic rope and sealed electric drive trains. Coast Guard procurement in the United States prioritizes equipment pedigree traceability as regulators tighten maintenance logging standards.
- Rescue Operations:General search-and-rescue across terrain inaccessible to ground vehicles.
- Firefighting:High-rise aerial rescue and wildfire personnel extraction.
Rescue operations hold installed capacity. Marine rescue is expanding most quickly as naval aviation procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply across geographies, with NATO members prioritizing fleet interoperability while Pacific Rim operators emphasize maritime corrosion resistance in saltwater environments.
United States
FAA Part 29 certification mandates drive replacement cycles among emergency medical service operators. The Department of Defense maintains multi-source qualification protocols for Army and Navy search-and-rescue platforms. Connecticut and Arizona host concentrated aerospace manufacturing clusters where electric hoist architectures undergo military qualification testing.
Germany
EASA CS-29 compliance requirements intersect with EU AI Act algorithmic safety mandates for automated load stabilization. The national aerospace regulator enforces dual-use technology controls that extend certification timelines for military end-users. Bavaria anchors European aftermarket service capacity through national maintenance agreements with federal defense procurement offices.
Switzerland
Alpine terrain accessibility requirements sustain demand for precision electric hoist systems in civilian mountain rescue operations. Swissmedic coordinates with EASA on equipment pedigree standards for cross-border emergency medical flights. The Zurich-Lucerne corridor concentrates textile engineering facilities producing high-modulus polyethylene synthetic rope for naval aviation specifications.
Japan
METI industrial standards govern hoist system integration with domestic rotorcraft platforms for coast guard and firefighting applications. Maritime Self-Defense Force procurement prioritizes sealed electric drive trains for saltwater corrosion immunity. The Nagoya aerospace cluster hosts qualification testing for synthetic rope configurations in humid subtropical conditions.
Australia
Coast Guard and rural fire service procurement emphasizes wire rope durability for high-heat bushfire extraction scenarios. The Therapeutic Goods Administration coordinates with civil aviation regulators on medical evacuation equipment standards. Queensland and Western Australia host concentrated offshore platform maintenance operations driving industrial hoist demand.
Rescue Hoist System Market Competitive Landscape
Capability concentration sits with defense-aerospace integrators; scale advantage sits with industrial lifting equipment manufacturers. The market structure splits between tier-one platform suppliers qualified for military multi-source protocols and tier-two component specialists serving civilian aftermarket demand. Strategic archetypes include full-system integrators, cable technology specialists, and predictive maintenance service providers. Dominant competitive moves encompass synthetic rope manufacturing partnerships and electric drive train certification investments.
Within the defense-aerospace tier, Collins Aerospace and RUAG Group exemplify platform-agnostic suppliers navigating dual-certification engineering requirements. Konecranes occupies a position bridging industrial crane service infrastructure with hoist inspection program cross-selling. These three entities represent contrasting geographic footprints and organizational structures—American, Swiss, and Finnish respectively—while each anchors distinct competitive positioning around certification depth, aftermarket reach, or integrated service networks.
| Leading Market Players |
|---|
| Konecranes |
| KITO Corporation |
| Hitachi |
| Breeze-Eastern |
| RUAG Group |
| Ingersoll Rand |
| SWF Krantechnik |
| Collins Aerospace |
| Columbus McKinnon Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in high-modulus polyethylene fiber production across the Zurich-Lucerne corridor drives both supplier allocation discipline and premium pricing for synthetic rope configurations. Electric drive train component shortages at qualified aerospace foundries compound cost pressure as military procurement timelines compress.
Pricing Analysis
Long-term offtake agreements dominate military procurement, insulating tier-one suppliers from spot volatility while civilian emergency medical operators negotiate project-based contracts tied to airframe availability. Three-tier pricing structure across military-qualified, dual-certified, and commercial-only equipment levels reflects certification depth and electromagnetic interference shielding requirements. Cost compression in hydraulic-to-electric retrofit programs intensifies as FAA Part 29 mandates accelerate replacement demand. Fire departments exhibit highest price sensitivity due to municipal budget constraints, whereas naval aviation units absorb premium positioning for saltwater corrosion immunity.
Supply Chain Analysis
Contract manufacturing for brushless DC motor assemblies concentrates in Connecticut and Arizona aerospace clusters, while high-modulus polyethylene fiber production anchors in Switzerland and Germany textile engineering facilities. Supply chains draw from rare-earth magnet suppliers, precision-machined gearbox components, and EASA-certified cable termination specialists. Single-source vulnerability in synthetic rope qualification protocols threatens equipment pedigree traceability as regulators tighten blockchain-based maintenance logging standards. Distribution runs through OEM-authorized service networks for military end-users and regional helicopter maintenance operators for civilian fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based aerial extraction systems represent a credible substitution threat that incumbent hoist manufacturers must neutralize through precision control differentiation and regulatory certification depth.
For Market Incumbents: Pre-empt drone substitution by embedding autonomous load stabilization algorithms that exceed uncrewed aerial system payload limits. Deepen backward integration into synthetic rope manufacturing to secure supply allocation during fiber production undercapacity. Accelerate EASA CS-29 dual-certification investments to extend qualification moats against emerging electric drive train specialists.
For New Entrants and Emerging Players: Civilian mountain rescue operations in Alpine jurisdictions represent the most penetrable entry point given precision electric hoist specification gaps below military qualification thresholds. Maritime coast guard maintenance contracts in humid subtropical environments offer secondary white-space with less entrenched incumbent service networks. Pursue availability-based service contract structures that transfer operational risk from cash-constrained municipal operators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric drive train certification programs as dual-certification engineering teams expand. Long-term viability favors platform-agnostic suppliers with established military multi-source qualification protocols rather than component specialists vulnerable to OEM insourcing. Acquisition target archetype: predictive maintenance service providers with captive relationships to civilian emergency medical fleets. Monitor synthetic rope qualification timeline compression as the inflection signal indicating supply-side capability gaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | EASA CS-29 compliance alongside FAA Part 29 opens NATO procurement access. |
| Synthetic Rope Manufacturing Partnership | Swiss and German fiber engineering alliances secure corrosion-resistant cable supply. |
| Predictive Maintenance Platform Launch | Availability-based contracts transfer operational risk from civilian helicopter operators. |
| Electric Drive Train Certification | Brushless DC architectures enable precision control for hospital helipad medical evacuations. |
| Blockchain Maintenance Logging Integration | Equipment pedigree traceability aligns with emerging FAA and EASA regulatory mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EASA certification databases, and NATO procurement announcements. Primary interviews encompassed military platform engineers, civilian emergency medical fleet managers, synthetic rope manufacturing technical directors, and aftermarket service contract negotiators. Secondary validation drew from Department of Defense budget justification materials, SEC filings of listed aerospace suppliers, and customs records of high-modulus polyethylene fiber trade flows. Bottom-up equipment deployment estimates triangulated against top-down defense procurement budget allocations.
Forecast inputs include electric hoist architecture penetration rates, synthetic rope specification adoption curves, and predictive maintenance contract revenue recognition patterns across the projection horizon. Segmentation modeling spans product type, end user, technology material, and application context with additional granularity on certification tier and geographic regulatory cluster. CAGRs derive from equipment replacement cycle analysis and fleet modernization program announcements. Industry-specific inputs incorporate FAA Part 29 mandate implementation timelines and EU AI Act algorithmic safety validation cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations, rare-earth magnet pricing, or helicopter OEM production rates would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and qualification protocol stability. Quarterly review of NATO fleet modernization procurement awards and synthetic rope manufacturing capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market