
 Global Aircraft Heavy Maintenance Visits Market | 2026-2036
Global Aircraft Heavy Maintenance Visits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Heavy Maintenance Visits Market Foresight
Airworthiness directive compliance tiers is collapsing the legacy cost structure of heavy maintenance scheduling. Lufthansa Technik AG leverages its Hamburg and Malta facilities to dominate European wide-body D-check capacity. ST Engineering anchors its position through Singapore-based hangar infrastructure purpose-built for next-generation narrow-body programs. Delta TechOps sustains North American competitiveness via captive maintenance of its own Boeing and Airbus fleets.
Aircraft heavy maintenance visits encompass airframe structural inspections, system overhauls, and powerplant restoration performed at fixed hourly or cyclic intervals typically ranging from 20,000 to 40,000 flight hours for C-checks and 6-10 years for D-checks, with the primary purpose of restoring type certificate compliance and extending safe operational life. Engine overhaul commands the highest margin pool within maintenance type segmentation due to specialized tooling requirements and limited OEM-certified capacity. Wide-body aircraft generate disproportionate revenue per visit within aircraft type segmentation, though narrow-body volume sustains provider utilization rates across independent repair stations and airline-owned MROs.
FAA airworthiness directives, EASA continuing airworthiness management organization requirements, and ICAO standards collectively mandate escalating documentation granularity and non-destructive testing depth for aging metal and composite structures. These frameworks compel service providers to invest in phased-array ultrasonic and thermographic inspection systems, reshaping capital allocation across independent repair stations and OEM-affiliated networks. Stakeholders must weigh the fixed-cost burden of regulatory tooling against the volume certainty of long-term airline maintenance contracts as fleet renewal cycles accelerate.
Market Dynamics
Regulatory airworthiness directive compression is forcing MRO providers to collapse traditional heavy maintenance intervals while absorbing advanced non-destructive testing capital requirements.
Growth Catalysts
- FAA Aging Aircraft Directives:The FAA's updated structural inspection mandates for metal fatigue and corrosion detection are expanding mandatory D-check frequency across US-registered wide-body fleets.
- Composite Repair Certification:Boeing 787 and Airbus A350 carbon-fiber airframe penetration is driving specialized thermographic and shearography inspection demand at Singapore and Hamburg MRO clusters.
- Southeast Asian Fleet Utilization:Low-cost carriers in Indonesia, Vietnam, and the Philippines are restoring pre-pandemic flight cycles, compressing C-check intervals and filling regional hangar capacity.
Market Restraints
- Phased-Array Ultrasonic Capital Intensity:Each automated scanning unit requires $2-4 million investment, straining independent repair stations without airline captive volume guarantees.
- OEM-Certified Engine Capacity Concentration:GE, Pratt & Whitney, and Rolls-Royce limit third-party powerplant overhaul licensing, constraining margin capture outside affiliated networks.
- EASA Documentation Granularity:Continuing Airworthiness Management Organization record-keeping requirements extend turnaround times by 15-20% for EU-registered aircraft.
Strategic Opportunities
- India MRO Infrastructure Gap:The country's nascent heavy maintenance sector offers first-mover positioning as domestic carriers expand Airbus A320neo and Boeing 737 MAX fleets.
- Predictive Maintenance Convergence:Integration of flight data monitoring with structural health sensors enables condition-based inspection intervals, reducing unnecessary downtime.
- UAE Regulatory Tailwind:GCAA bilateral agreements with EASA and FAA are positioning Dubai and Abu Dhabi as alternative hubs for Middle East and African carrier heavy checks.
Industry Challenges
- NDT Technician Certification Bottlenecks:NAS 410 and EN 4179 qualified inspectors for composite damage assessment remain scarce relative to expanding thermographic inspection requirements.
- Legacy System Integration Friction:Paper-based maintenance logs at older facilities impede real-time data exchange with airline fleet management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Heavy Maintenance Visits Market |
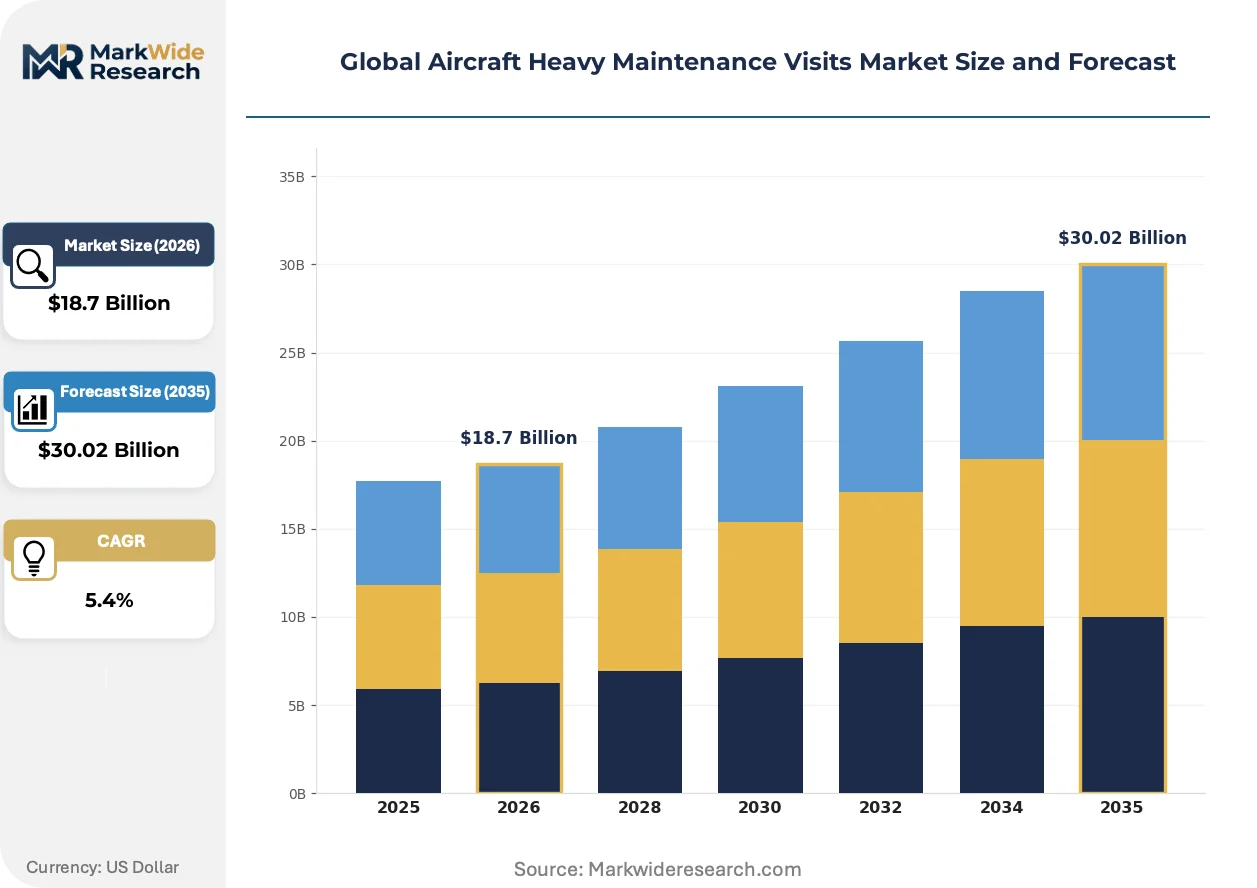
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Maintenance Type: C-Checks, D-Checks, Structural Modifications, Systems Overhaul, Engine Overhaul Aircraft Type: Narrow-body, Wide-body, Regional Jets, Cargo Aircraft, Business Jets Service Provider Type: Original Equipment Manufacturers, Independent Repair Stations, Airline-Owned MROs, Component Specialists, Third-party Providers Customer Type: Legacy Carriers, Low-Cost Carriers, Cargo Operators, Charter Operators, Government Fleets |
| Companies Covered | Lufthansa Technik AG, TU Aero Engines AG, ST Engineering, Hong Kong Aircraft Engineering Company Limited, Honeywell International Inc., Ascent Aviation Services Corporation, Boeing, Airbus, Delta TechOps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Heavy Maintenance Visits Market Shifts & Advancements
Digital thread integration across airframe lifecycle data is collapsing the information asymmetry between operators and MRO providers, reshaping how maintenance scope is negotiated and priced.
Robotic phased-array ultrasonic testing is supplanting manual eddy-current inspection for fuselage lap-joint corrosion detection. Lufthansa Technik and ST Engineering are deploying automated scanning arrays at their Hamburg and Singapore facilities. This technology is compressing structural inspection man-hours by 40% while improving flaw detection consistency across aging aluminum airframes.
EASA's revised Continuing Airworthiness Regulation (EU) 1321/2014 is mandating enhanced zonal inspection programs for electrical wiring interconnection systems in aircraft over 15 years operational age. European MRO providers are retrofitting hangars with borescope-equipped snake robots to access confined avionics bays. Wide-body operators with aging A330 and 777 fleets face the steepest compliance cost escalation.
Airlines are unbundling engine overhaul from airframe heavy maintenance contracts, fragmenting procurement decisions that historically consolidated at single MRO providers. This disintermediation is compressing contract durations from 10-year exclusive agreements to 3-5 year competitive tenders. The shift is most pronounced among US legacy carriers seeking to pit GE Aviation against Pratt & Whitney for powerplant shop visit allocation.
Global Aircraft Heavy Maintenance Visits Market Segmentation
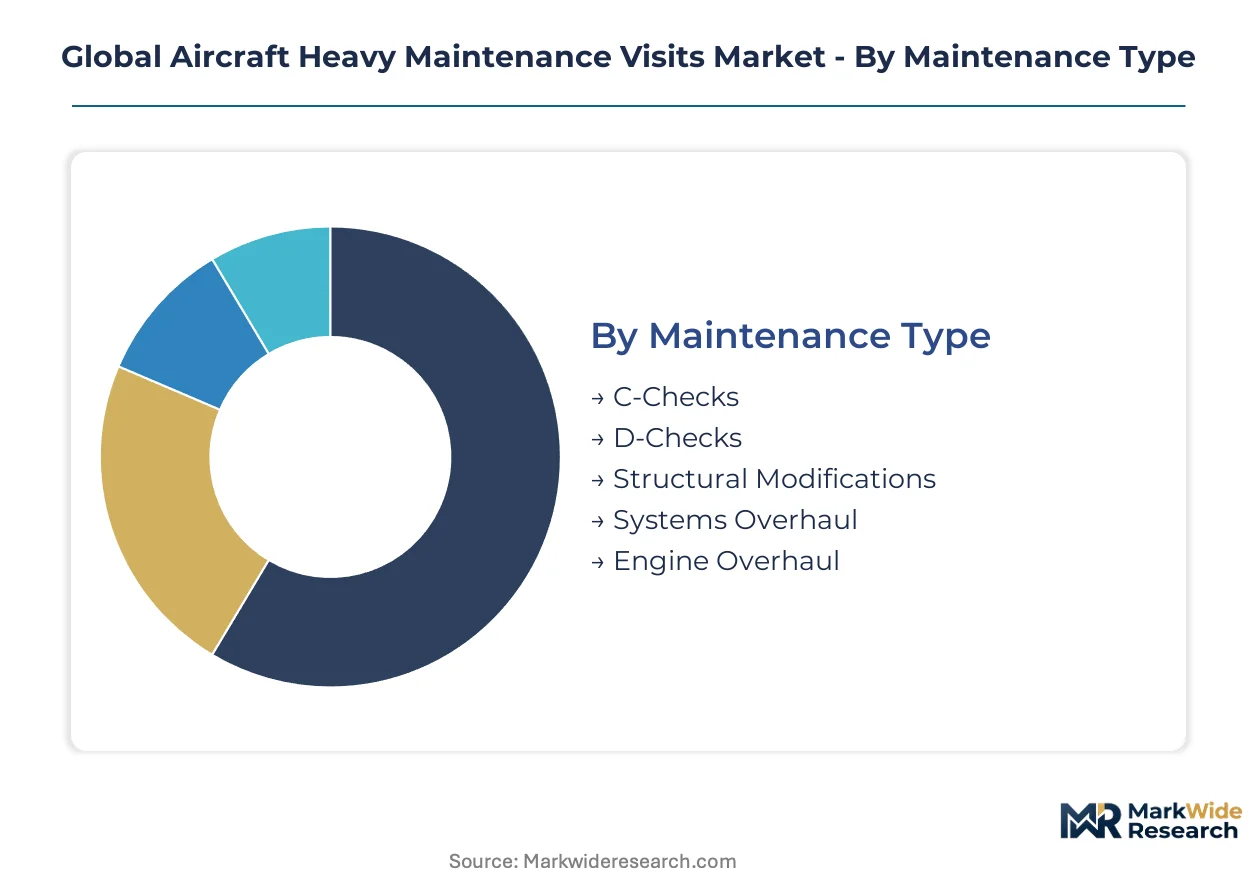
Segmentation in aircraft heavy maintenance reveals where pricing power concentrates and where commoditization threatens margins. Providers structure contracts around maintenance type hierarchies and aircraft size classes, with regulatory certification tiers creating natural price floors.
Maintenance Type:
Engine overhaul faces the weakest substitution pressure due to OEM certification lock-in, while airframe checks confront growing automation-driven price compression.
- C-Checks:Intermediate structural inspections and system servicing performed at 20,000-40,000 flight hour intervals. Demand concentrates among Southeast Asian low-cost carriers restoring post-pandemic utilization, compressing turnaround requirements at Singapore and Jakarta facilities.
- D-Checks:Comprehensive airframe teardown and restoration cycles occurring every 6-10 years. Wide-body operators in Germany and the United States drive volume as FAA aging aircraft directives expand mandatory inspection scope for corrosion-prone aluminum structures.
- Structural Modifications:Supplemental type certificate compliance and airworthiness directive retrofits.
- Systems Overhaul:Avionics, landing gear, and auxiliary power unit restoration.
- Engine Overhaul:Powerplant disassembly, component repair, and reassembly to OEM specifications.
C-Checks anchor the volume base while engine overhaul gains share at the steepest rate due to specialized tooling barriers.
Aircraft Type:
Cost tier differentiation separates narrow-body commodity pricing from wide-body premium positioning.
- Narrow-body:Single-aisle aircraft including Airbus A320 family and Boeing 737 variants. High fleet counts sustain utilization rates at independent repair stations across India and Vietnam, though per-visit margins remain compressed by competitive tendering.
- Wide-body:Twin-aisle aircraft requiring extended hangar occupancy and specialized jacking equipment. Singapore and Hamburg clusters capture disproportionate revenue per slot as 787 and A350 composite repair certification demands concentrate at purpose-built facilities.
- Regional Jets:Sub-100 seat aircraft serving thin routes.
- Cargo Aircraft:Converted freighters and purpose-built cargo fleets.
- Business Jets:Corporate and private aviation platforms.
Narrow-body maintenance anchors the volume base while wide-body work expands most quickly in revenue contribution.
Service Provider Type:
Supply concentration favors OEM-affiliated networks for engine work, while independent stations compete on airframe speed.
- Original Equipment Manufacturers:Boeing, Airbus, and engine-maker service networks. GE Aviation and Pratt & Whitney limit third-party powerplant licensing, capturing margin pools through captive overhaul capacity in the United States and United Kingdom.
- Independent Repair Stations:Third-party facilities competing on turnaround time and labor arbitrage. Malaysian and Indonesian stations undercut European pricing for C-check volume, though capital constraints limit NDT equipment investment.
- Airline-Owned MROs:Captive maintenance divisions serving parent carrier fleets.
- Component Specialists:Focused repair stations for avionics, hydraulics, or landing gear.
- Third-party Providers:Integrated maintenance contractors offering bundled services.
Independent repair stations anchor the volume base while OEM networks climb the fastest in revenue share.
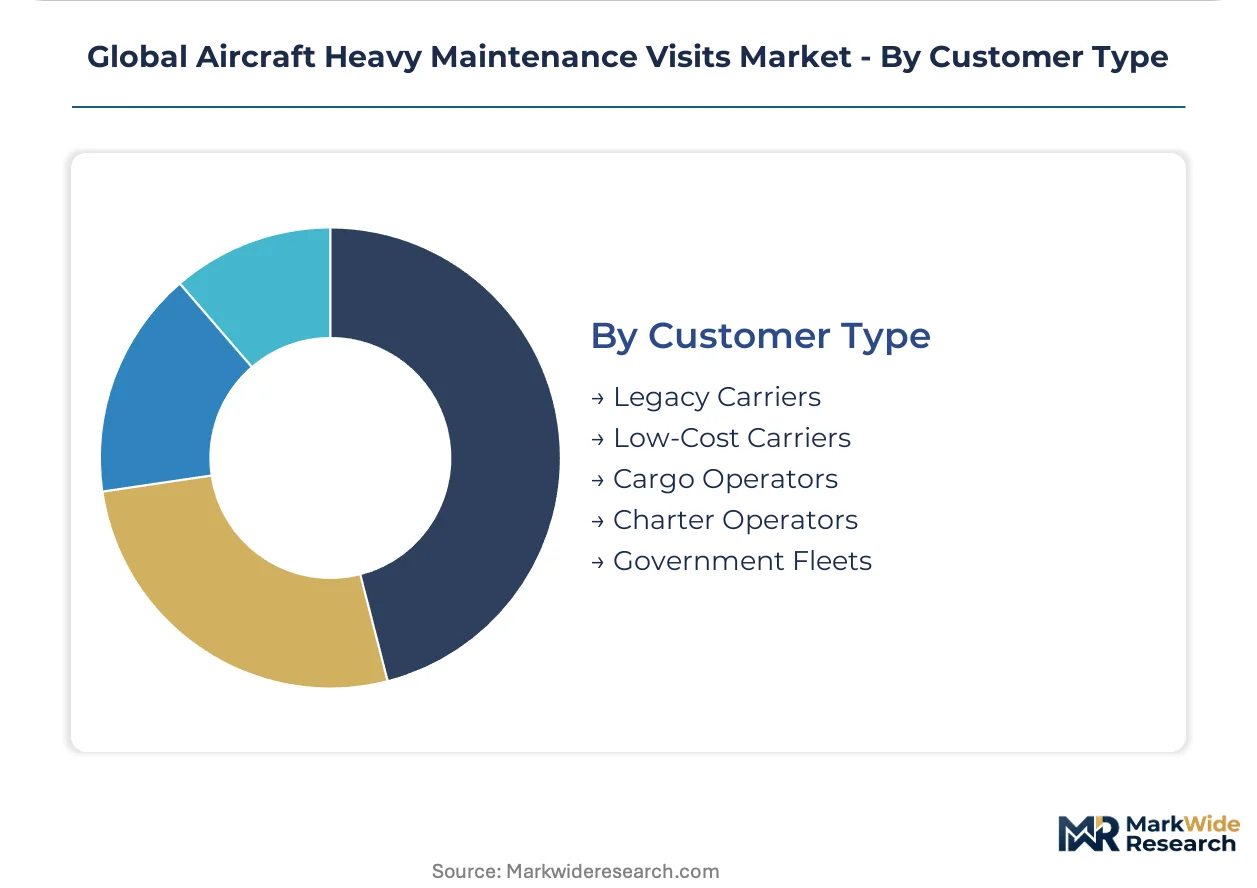
Customer Type:
Procurement sophistication varies sharply between legacy carrier long-term planning and low-cost carrier spot-market purchasing.
- Legacy Carriers:Established full-service airlines with integrated fleet management. Delta and Lufthansa sustain captive MRO investment through predictable wide-body overhaul pipelines, negotiating multi-year contracts with volume guarantees.
- Low-Cost Carriers:Price-focused operators maximizing aircraft utilization. Indonesian and Vietnamese budget airlines compress C-check intervals through high-cycle operations, filling regional hangar capacity with narrow-body volume.
- Cargo Operators:Dedicated freighter fleets and converted passenger aircraft.
- Charter Operators:Ad-hoc and seasonal capacity providers.
- Government Fleets:Military and state aviation maintenance requirements.
Legacy carriers anchor the volume base while low-cost carriers gain share fastest in Asia-Pacific maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy maintenance capacity flows toward jurisdictions with favorable labor economics and regulatory reciprocity. Singapore and Germany run structural trade surpluses in wide-body overhaul services, while the United States and India remain net importers of specialized composite repair labor.
United States
Legacy carrier fleet renewal drives D-check demand at Delta TechOps and American Airlines facilities. FAA aging aircraft directives expand mandatory inspection scope for corrosion-prone 767 and 777 airframes. Miami and Atlanta clusters process narrow-body volume for Latin American operators seeking FAA-certified work.
Germany
Lufthansa Technik anchors European wide-body capacity through Hamburg and Malta facilities. EASA continuing airworthiness regulation revisions mandate enhanced zonal inspection programs for electrical wiring interconnection systems. The Hamburg cluster captures premium pricing for 787 and A350 composite repair certification.
Singapore
ST Engineering dominates Asia-Pacific wide-body overhauls through Changi-based hangar infrastructure. The Civil Aviation Authority of Singapore maintains bilateral agreements with FAA and EASA that streamline foreign-registered aircraft acceptance. Seletar Aerospace Park concentrates next-generation narrow-body program capacity for Southeast Asian low-cost carriers.
India
Domestic A320neo and 737 MAX fleet expansion outpaces indigenous heavy maintenance infrastructure. The Directorate General of Civil Aviation struggles to certify independent repair stations for phased-array ultrasonic testing. Mumbai and Delhi facilities remain dependent on Singapore and Dubai for D-check overflow.
United Arab Emirates
GCAA regulatory alignment with EASA and FAA positions Dubai as an alternative hub for Middle East and African carriers. Emirates Engineering and Etihad Airways Engineering capture wide-body volume that bypasses European slot constraints. Al Ain and Dubai South clusters specialize in rapid-turnaround C-check programs for high-utilization fleets.
Global Aircraft Heavy Maintenance Visits Market Competitive Landscape
Concentration sits with OEM-affiliated networks and airline-captive divisions that control engine overhaul certification. The market structures around three tiers: integrated aerospace conglomerates with regulatory capture, independent repair stations competing on turnaround speed, and national champions serving domestic flag carriers. Competitive moves center on hangar capacity expansion in low-labor-cost jurisdictions and selective technology licensing for composite inspection systems.
Among European-integrated service providers, Lufthansa Technik AG exemplifies the premium-tier archetype through its Hamburg and Malta facilities. ST Engineering represents the Asia-Pacific national champion model, anchoring Singapore's Changi cluster. Delta TechOps occupies the airline-captive position, sustaining North American competitiveness through in-house Boeing and Airbus fleet maintenance.
| Leading Market Players |
|---|
| Lufthansa Technik AG |
| TU Aero Engines AG |
| ST Engineering |
| Hong Kong Aircraft Engineering Company Limited |
| Honeywell International Inc. |
| Ascent Aviation Services Corporation |
| Boeing |
| Airbus |
| Delta TechOps |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day phased-array ultrasonic equipment lead times from German and Japanese suppliers concentrate pricing power with OEM-affiliated MRO networks that can pre-position capital assets, while independent repair stations face spot-market premiums that compress bid competitiveness on narrow-body C-check contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume guarantees against fixed per-flight-hour rates. Price differentiation rests on EASA Part 145 certification tier and composite repair capability depth, with Singapore and Hamburg facilities commanding premiums over Southeast Asian independents. Cost compression in narrow-body airframe checks is intensifying because robotic inspection deployment amortizes across fewer man-hours. Low-cost carriers exhibit highest price sensitivity, while legacy carriers with captive MROs show lowest sensitivity due to internal transfer pricing.
Supply Chain Analysis
Germany and Japan anchor precision NDT equipment fabrication, while Singapore and the United Arab Emirates concentrate hangar infrastructure and skilled technician labor pools. Raw material dependencies span aerospace-grade aluminum alloys, carbon fiber prepreg systems, and specialized avionics components. Single-source vulnerability sits with OEM-certified engine overhaul capacity controlled by GE, Pratt & Whitney, and Rolls-Royce. Distribution runs through bilateral regulatory agreements that streamline cross-border aircraft acceptance between FAA, EASA, and CAAS jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Southeast Asian low-cost carrier fleets consolidate maintenance procurement under regional airline groups, fragmenting spot-market purchasing into coordinated tender pools that extract volume discounts from independent repair stations.
For Market Incumbents: Consolidate through backward integration into phased-array ultrasonic equipment leasing subsidiaries that captive independent stations as downstream customers. Expand hangar capacity in Vietnam and Indonesia to capture narrow-body volume before regional competitors secure land and regulatory approvals. Defend against emerging MRO networks in India by pre-emptive certification investment for A320neo and 737 MAX programs. For New Entrants and Emerging Players: Differentiate on rapid-turnaround C-check specialization for high-utilization low-cost carrier fleets that prioritize slot availability over per-visit margin. Target India's nascent heavy maintenance infrastructure gap where DGCA certification bottlenecks delay indigenous capacity deployment. Pursue joint venture structures with established Southeast Asian independents to access existing regulatory approvals and technician training pipelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EASA and FAA certification tiers create durable moats around specialized composite repair and engine overhaul capabilities. Acquisition focus should center on mid-scale independents with pending OEM authorization for next-generation narrow-body programs. Watch for inflection when Indian DGCA accelerates repair station certification timelines, signaling domestic capacity buildout that redirects overflow demand from Singapore.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Repair Certification Investment | EASA and FAA authorization for 787 and A350 carbon-fiber work captures premium wide-body slots at Singapore and Hamburg clusters. |
| Phased-Array Ultrasonic Deployment | Automated scanning arrays at Lufthansa Technik and ST Engineering compress structural inspection man-hours by forty percent. |
| India Hangar Infrastructure Buildout | First-mover positioning in Mumbai and Delhi addresses A320neo and 737 MAX fleet expansion outpacing indigenous MRO capacity. |
| Predictive Maintenance Platform Integration | Flight data monitoring convergence with structural health sensors enables condition-based inspection intervals reducing unnecessary downtime. |
| UAE Regulatory Hub Development | GCAA bilateral agreements with EASA and FAA position Dubai as alternative heavy check destination bypassing European slot constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MRO operations directors, airline fleet management executives, aviation regulatory compliance officers, and independent repair station owners. Secondary validation drew from FAA airworthiness directive filings, EASA continuing airworthiness regulation amendments, ICAO safety management documentation, and civil aviation authority bilateral agreement registers. Bottom-up technician labor pool assessments and top-down hangar capacity utilization estimates were triangulated against OEM shop visit forecasts.
Across the analysis window, the forecasting framework modeled maintenance type hierarchies, aircraft size classes, service provider certification tiers, and customer procurement sophistication levels. CAGRs were derived from fleet renewal cycle timing, regulatory inspection interval compression rates, and regional hangar capacity expansion pipelines. Forecast inputs incorporated post-pandemic flight hour restoration trajectories and next-generation aircraft penetration curves for composite-intensive platforms.
Decision-makers should treat outputs as directional under assumptions of stable regulatory reciprocity between FAA, EASA, and Asia-Pacific civil aviation authorities; material deviation in bilateral agreement scope or inspection mandate timing would warrant model refresh. Specific risks that could revise trajectories include accelerated OEM engine overhaul certification restrictions, sudden NDT technician labor shortages, or unilateral hangar capacity moratoria in concentrated hub jurisdictions. Recalibration cycles align with material shifts in fleet renewal timing, regulatory inspection interval revisions, and regional infrastructure investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market