
 Aircraft Brackets Market | 2026-2036
Aircraft Brackets Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Brackets Market Analysis
Additive manufacturing is narrowing the design freedom gap between forged and machined brackets, allowing lattice-optimized geometries that previously required multi-part assemblies. Triumph Group Inc leverages its integrated forging and machining footprint to compete on airframe bracket contracts for narrow-body platforms. Precision Castparts Corp sustains dominance in superalloy and titanium engine mount brackets through captive metallurgy capabilities. Spirit AeroSystems Holdings Inc anchors regional supply chains in Wichita, controlling bracket flow into its fuselage and wing assemblies.
Aircraft brackets are structural load-transfer components, typically machined from aluminum alloy 7075-T6 or titanium Ti-6Al-4V, that rigidly connect airframe panels, engine mounts, landing gear trunnions, and interior monuments to primary structure. They must survive limit loads without permanent deformation and ultimate loads without fracture, per FAR 25.305 strength and deformation requirements. Fixed brackets lead volume in commercial programs due to their repeatability across high-rate single-aisle production, while additive manufacturing represents the fastest-expanding process category as OEMs qualify laser powder bed fusion for non-flight-critical fittings. Composite brackets command premium positioning in interior applications where galvanic isolation and mass reduction justify higher unit economics.
FAA airworthiness standards under 14 CFR Part 25 and EASA CS-25 certification frameworks mandate fatigue and damage tolerance analysis for all primary structure brackets, extending development timelines but creating barriers against uncertified suppliers. REACH restrictions on hexavalent chromium surface treatments and EU Green Deal decarbonization targets are forcing bracket manufacturers toward PVD coatings and aqueous corrosion protection chemistries. Stakeholders must monitor additive manufacturing qualification progress at OEMs, as process certification unlocks redesign of legacy bracket families currently constrained by forging die economics.
Market Dynamics
Additive manufacturing qualification at airframe OEMs is compressing design-to-production cycles for legacy bracket families previously constrained by forging die economics and minimum order quantities.
Growth Catalysts
- Commercial Fleet Expansion:Narrow-body production rate increases at Boeing and Airbus final assembly lines drive bracket procurement volumes for wing-to-body and pylon attachment applications.
- FAR 25.305 Certification:FAA strength and deformation requirements for primary structure brackets create compliance barriers that favor incumbent suppliers with established fatigue test databases.
- Titanium Alloy Adoption:Ti-6Al-4V substitution in engine mount brackets delivers mass reduction and corrosion resistance for next-generation turbofan programs.
Market Restraints
- Superalloy Input Volatility:Nickel and cobalt price swings compress margins for investment-cast engine brackets where material constitutes forty percent of unit cost.
- Wichita Supplier Cluster Concentration:Spirit AeroSystems and its tier-n network control seventy percent of North American bracket flow, creating single-point vulnerability.
- REACH Hexavalent Chromium Ban:ECHA restrictions on cadmium and chromate surface treatments force process requalification and capital expenditure for corrosion protection lines.
Strategic Opportunities
- Interior Composite Brackets:Galvanic isolation requirements in cabin monument installations create premium positioning for carbon-fiber-reinforced polymer fittings in wide-body programs.
- Laser Powder Bed Fusion:OEM qualification of LPBF for non-flight-critical brackets unlocks lattice-optimized geometries that merge multi-part assemblies into single printed components.
- EU Green Deal Decarbonization:EASA environmental certification incentives reward bracket manufacturers adopting aqueous PVD coating chemistries and closed-loop material recovery.
Industry Challenges
- Additive Manufacturing Technician Scarcity:LPBF process engineers with aerospace metallurgy credentials command premium wages and constrain supplier scale-up capacity.
- Damage Tolerance Certification Timelines:FAA fatigue and crack-growth analysis requirements extend development programs by eighteen to twenty-four months for primary structure brackets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Brackets Market |
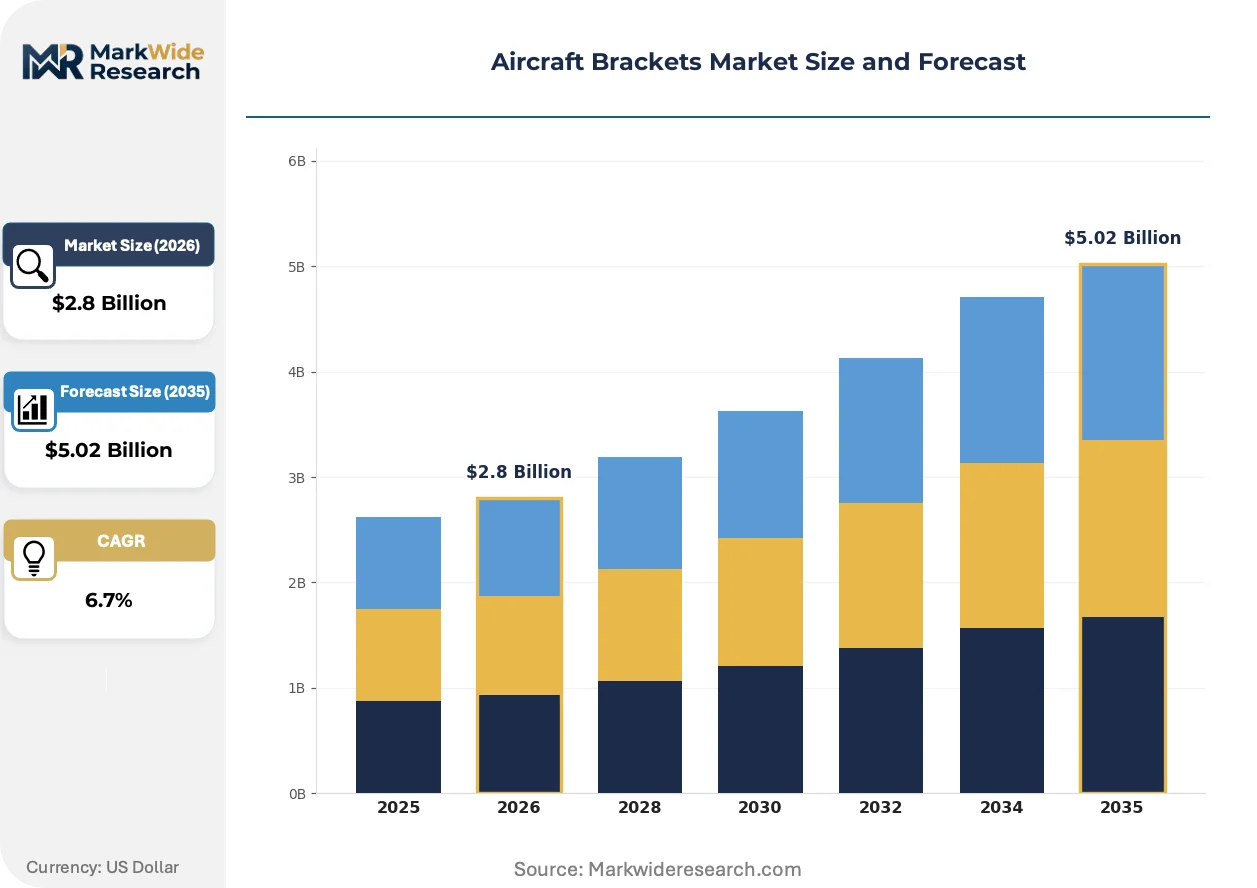
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed Brackets, Adjustable Brackets, Standard Brackets, Custom Brackets Material: Aluminum, Steel, Titanium, Composite Application: Airframe, Engine Mounts, Landing Gear, Interior Fittings Manufacturing Process: Forging, Machining, Casting, Additive Manufacturing |
| Companies Covered | Triumph Group Inc, Precision Castparts Corp, Spirit AeroSystems Holdings Inc, Arconic Corp, Hutchinson SA, Hexagon AB, Premium Aerotec GmbH, SEKISUI Aerospace, Singapore Technologies Engineering Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Brackets Market Emerging Trajectories
Digital thread integration across design, manufacturing, and quality systems is collapsing the traditional handoffs between bracket designers and production engineers.
Topology optimization software paired with generative design algorithms is migrating from concept validation to direct manufacturing input. Airframe OEMs now export lattice-optimized bracket geometries to additive suppliers without intermediate forging drawings. This shift collapses tooling lead times from sixteen weeks to seventy-two hours for non-flight-critical fittings.
EASA CS-25 certification harmonization with FAA Part 25 is tightening material traceability requirements across European supply chains. Suppliers must now maintain digital birth certificates for titanium ingots through final machining. Engine bracket manufacturers with captive melt-to-machine capabilities capture preferential sourcing status from risk-averse procurement teams.
Airline MRO procurement teams are consolidating bracket purchases under long-term framework agreements with designated tier-one distributors. This behavior compresses spot-market volumes and rewards suppliers with AS9100D certification and same-day fulfillment networks. The shift is most visible in North America, where narrow-body fleet utilization rates drive aftermarket bracket consumption for landing gear and pylon repairs.
Aircraft Brackets Market Segmentation
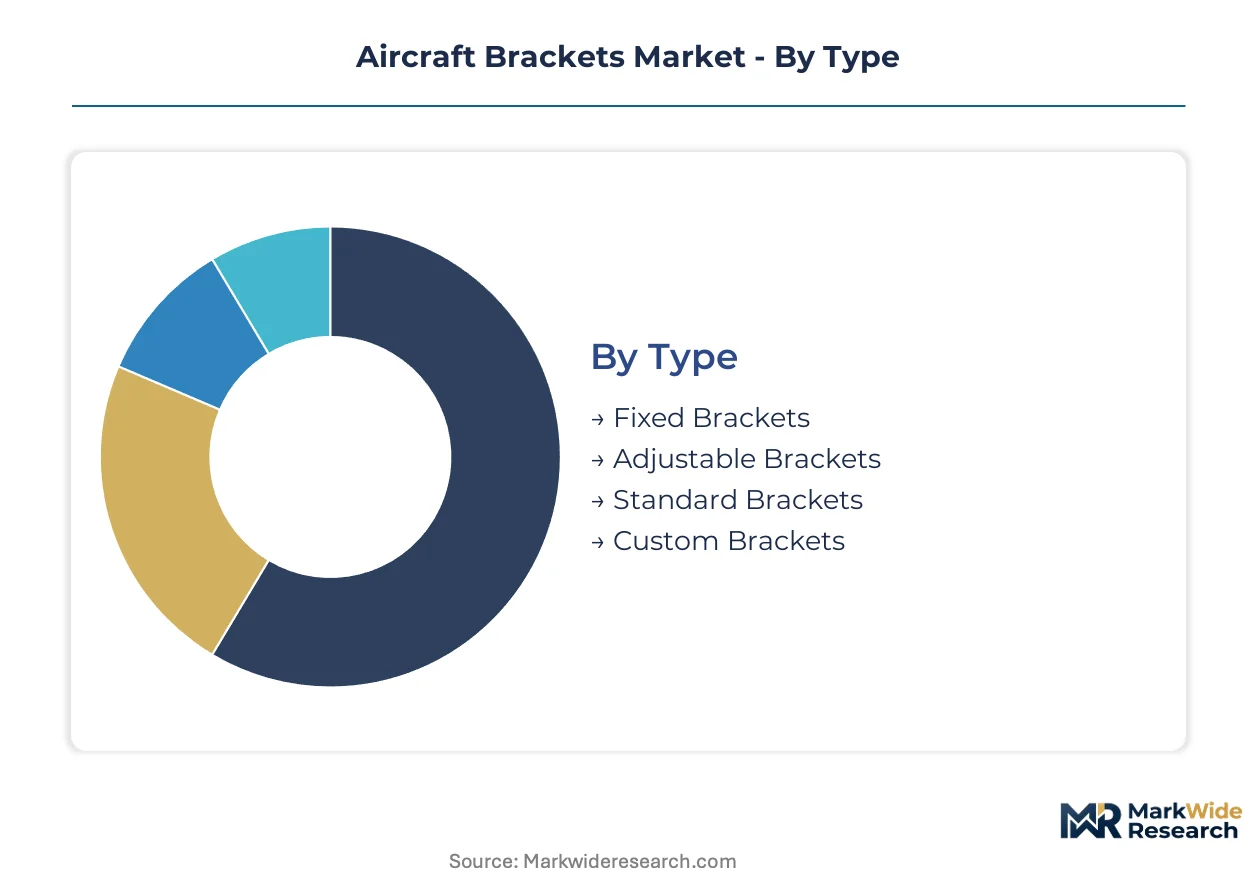
Aircraft bracket segmentation reveals how procurement priorities split between high-volume standardized hardware and low-volume engineered solutions. Understanding these divisions exposes where suppliers compete on scale versus where they capture premium through qualification barriers.
Type:
Fixed brackets dominate narrow-body production lines where repeatability drives economies of scale, while custom solutions anchor wide-body and defense programs requiring mission-specific load paths.
- Fixed Brackets:These rigid, non-adjustable components machine from aluminum 7075-T6 or titanium Ti-6Al-4V to permanent geometries. Boeing 737 MAX and Airbus A320neo wing-to-body attachments consume the highest volumes in Wichita supplier clusters, with single-aisle rate hikes pushing annual procurement into millions of units.
- Custom Brackets:Engineered to unique airframe interfaces, these demand fatigue test databases and FAA Part 25 damage tolerance certification. Defense platforms and VIP completions in the United States concentrate demand here, where development timelines stretch eighteen to twenty-four months but unit margins justify dedicated engineering teams.
- Adjustable Brackets:Slotted or hinged designs accommodate tolerance stack-up in pylon and nacelle installations where thermal expansion matters.
- Standard Brackets:Catalog hardware serving interior monuments and secondary structure where AS9100D certification satisfies procurement without custom qualification.
Established volume favors Fixed Brackets; emerging adoption favors Custom Brackets as next-generation platforms multiply unique interface requirements.
Material:
Material selection traces a direct path from legacy aluminum dominance toward titanium and composite penetration where mass reduction justifies cost premiums.
- Aluminum:Alloy 7075-T6 remains the baseline for non-critical brackets across commercial programs. Its strength-to-weight ratio and mature supply chain keep it entrenched in high-volume Wichita production feeding Boeing final assembly.
- Titanium:Ti-6Al-4V substitution accelerates in engine mounts and landing gear trunnions where corrosion resistance and elevated temperature performance outweigh raw material cost. Suppliers with captive melt-to-machine capabilities in the United States capture preferential sourcing from risk-averse OEM procurement teams.
- Steel:High-strength alloy selections persist in landing gear and cargo handling systems where ultimate load requirements exceed aluminum limits.
- Composite:Carbon-fiber-reinforced polymer brackets gain traction in cabin monument installations across wide-body programs, delivering galvanic isolation from aluminum structure and meaningful mass reduction at premium unit economics.
Aluminum retains the highest shipment volumes; composite solutions are climbing the fastest as EASA environmental certification incentives reward lightweighting.
Application:
Application segmentation maps directly onto airframe assembly sequence, with early-stage structural brackets facing stricter certification than late-stage interior hardware.
- Airframe:Primary structure brackets transferring wing, fuselage, and empennage loads demand FAR 25.305 compliance and extensive fatigue databases. Spirit AeroSystems in Wichita controls the dominant share of North American flow here, integrating brackets directly into major assemblies before delivery to Boeing.
- Engine Mounts:Pylon attachment brackets survive limit and ultimate loads under turbofan thrust vectors while managing thermal gradients. Precision Castparts Corp sustains leadership through superalloy and titanium investment casting capabilities with captive metallurgy.
- Landing Gear:Trunnion and drag brace brackets absorb ground loads and retract actuator forces, with MRO demand driving aftermarket procurement consolidation under long-term framework agreements.
- Interior Fittings:Monument and galley attachment brackets face lighter structural requirements but must satisfy flammability and smoke toxicity standards for cabin certification.
Airframe applications command the largest revenue base; interior fittings are expanding most quickly as cabin reconfiguration cycles shorten across aging narrow-body fleets.
Manufacturing Process:
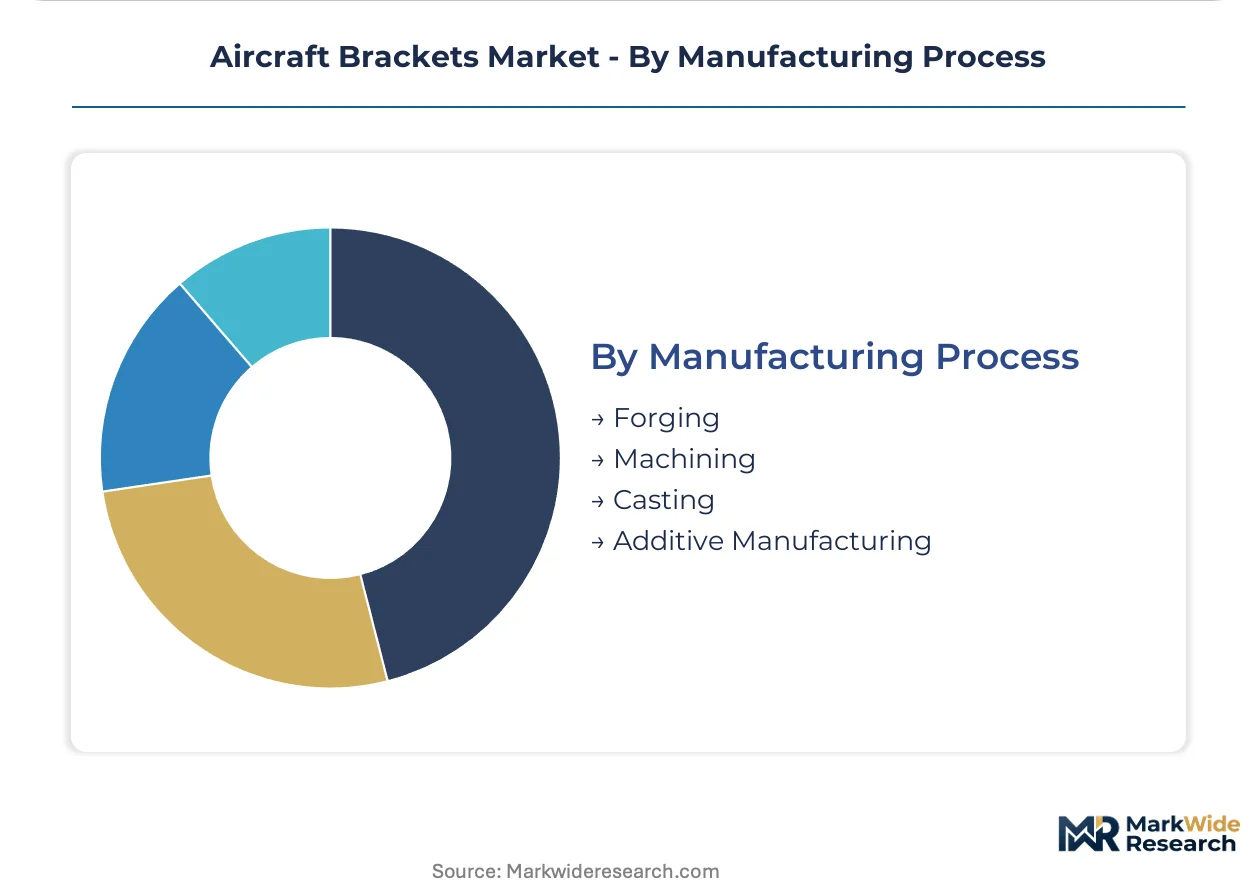
Process selection increasingly pits legacy forging economies against additive manufacturing flexibility as OEM qualification programs mature.
- Forging:Closed-die forging delivers grain flow alignment and structural integrity for primary load-bearing brackets. Triumph Group Inc competes here through integrated forging and machining footprints serving narrow-body airframe contracts.
- Additive Manufacturing:Laser powder bed fusion unlocks lattice-optimized geometries that merge multi-part assemblies into single printed components. FAA progress on non-flight-critical qualification is compressing design-to-production cycles from sixteen weeks to seventy-two hours for select fitting categories.
- Machining:CNC milling from plate and extrusion remains standard for prototype and low-rate production where forging die economics fail.
- Casting:Investment casting serves complex engine mount geometries in nickel and cobalt superalloys where near-net shaping minimizes material removal.
Forging retains volume leadership in primary structure; additive manufacturing represents the steepest expansion trajectory as technician scarcity becomes the binding constraint on supplier scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bracket procurement flows disproportionately toward nations running structural aerospace trade surpluses, with import-dependent markets sourcing through tier-one distributors rather than direct manufacturer relationships.
United States
Boeing's final assembly lines in Everett and Charleston pull bracket volumes through Wichita's dense supplier cluster. FAA airworthiness directives under 14 CFR Part 25 enforce fatigue test databases that favor incumbent domestic suppliers. Spirit AeroSystems anchors regional flow, integrating brackets directly into fuselage and wing assemblies before delivery to Boeing programs.
Germany
Airbus Hamburg and Bremen final assembly drives demand for titanium and composite brackets across A320 and A350 programs. EASA CS-25 certification harmonization with FAA standards tightens material traceability requirements through European supply chains. Premium Aerotec GmbH facilities in Augsburg and Varel control significant bracket flow into Airbus wing and fuselage structures.
France
Safran and Airbus operations in Toulouse and Nantes concentrate engine mount and pylon bracket procurement. REACH restrictions on hexavalent chromium surface treatments force process requalification for corrosion protection lines. The Toulouse aerospace cluster houses specialized suppliers serving A350 and A400M programs with damage-tolerance-certified hardware.
Japan
Boeing 787 supply chain participation and Mitsubishi Heavy Industries regional jet programs sustain bracket demand. METI industrial standards align with JIS certification requirements for structural aerospace components. The Nagoya aerospace cluster hosts tier-one suppliers feeding Boeing's Japanese industrial participation agreements.
Singapore
MRO hub status at Changi drives aftermarket bracket consumption for landing gear and engine repairs across Asia-Pacific fleets. The country's national aerospace regulator enforces CAAS certification aligned with FAA and EASA standards. Singapore Technologies Engineering anchors regional distribution, consolidating procurement under long-term framework agreements with global OEMs.
Aircraft Brackets Market Vendor Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated airframe suppliers with captive bracket production, specialized forging and casting houses with metallurgical capabilities, and emerging additive manufacturing specialists qualifying at OEMs. Strategic archetypes include scale-driven integrators, metallurgy-captive specialists, and process-innovation challengers. Dominant competitive moves span backward integration into raw material supply and strategic partnerships for additive manufacturing qualification.
Among US-based integrated suppliers, Triumph Group Inc, Spirit AeroSystems Holdings Inc, and Precision Castparts Corp exemplify distinct competitive positions. Triumph Group Inc represents the forging-machining integrator archetype, occupying a position across narrow-body airframe contracts. Spirit AeroSystems Holdings Inc anchors regional supply chain control in Wichita, sitting within the tier-one integrator tier. Precision Castparts Corp exemplifies the metallurgy-captive specialist, with its name signaling investment casting and superalloy capabilities.
| Leading Market Players |
|---|
| Triumph Group Inc |
| Precision Castparts Corp |
| Spirit AeroSystems Holdings Inc |
| Arconic Corp |
| Hutchinson SA |
| Hexagon AB |
| Premium Aerotec GmbH |
| SEKISUI Aerospace |
| Singapore Technologies Engineering Ltd |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Wichita's forging and machining cluster is pressuring utilization rates below optimal thresholds, forcing suppliers to absorb material cost volatility rather than pass through increases and reshaping procurement leverage toward Boeing and Airbus final assembly buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across bracket categories. Pricing stratifies across damage-tolerance-certified, AS9100D-standard, and catalog-economy tiers based on fatigue test database depth and material traceability grade. Cost compression in aluminum 7075-T6 brackets is intensifying because spot-market titanium ingot volatility constrains margin buffers. Narrow-body procurement teams at Boeing exhibit highest price sensitivity due to rate-driven volume scale, while defense platform buyers accept premiums for custom qualification.
Supply Chain Analysis
Spirit AeroSystems and Triumph Group facilities in Wichita, Kansas hold dominant North American bracket production capacity. Raw material flows draw from titanium sponge processing in the United States, aluminum smelting in Canada, and nickel-cobalt superalloy supply chains anchored in domestic metallurgy. Single-source vulnerability concentrates in Spirit AeroSystems' tier-n network controlling seventy percent of regional bracket flow. Distribution runs through AS9100D-certified tier-one distributors consolidating MRO procurement under long-term framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks commercial aviation production cycles, with narrow-body rate restoration at Boeing and Airbus final assembly lines driving the current recovery phase.
For Market Incumbents: Build certification moats through captive fatigue test databases and FAR 25.305 damage tolerance qualifications that emerging additive suppliers cannot replicate. Backward integration into titanium melt-to-machine capabilities captures preferential sourcing status from risk-averse OEM procurement teams facing EASA material traceability mandates. Threat substitution from laser powder bed fusion demands accelerated qualification investment to maintain primary structure bracket positioning.
For New Entrants and Emerging Players: Interior composite brackets for wide-body cabin monument installations represent the most penetrable entry point, as galvanic isolation requirements create qualification barriers lower than primary airframe applications. Additive manufacturing service bureaus with aerospace metallurgy credentials can capture non-flight-critical fitting contracts as OEM qualification programs mature. Go-to-market positioning through tier-one distributor partnerships bypasses direct OEM procurement barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing qualification programs as laser powder bed fusion equipment and technician training costs escalate. Long-term viability favors suppliers with hybrid forging-additive footprints serving both rate-driven narrow-body volume and next-generation platform customization. Acquisition targets should demonstrate captive metallurgy or integrated forging-machining capabilities. Watch FAA progress on non-flight-critical bracket qualification as the inflection signal unlocking redesign of legacy families.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | FAA certification of laser powder bed fusion unlocks lattice-optimized geometries merging multi-part assemblies. |
| Backward Integration into Titanium Metallurgy | Captive melt-to-machine capabilities satisfy EASA digital birth certificate requirements for preferential OEM sourcing. |
| Composite Bracket Development | Carbon-fiber-reinforced polymer solutions capture premium positioning in wide-body cabin monument installations. |
| Long-term Distribution Partnership | AS9100D-certified tier-one distributor networks consolidate MRO procurement under framework agreements. |
| Aqueous Coating Process Transition | PVD and aqueous corrosion protection chemistries satisfy REACH hexavalent chromium restrictions without qualification gaps. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airframe procurement directors, tier-one supplier program managers, FAA certification engineers, and MRO distribution executives. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification databases, SEC 10-K aerospace segment disclosures, and commercial aircraft production rate announcements. Bottom-up bracket volume estimates triangulated against top-down airframe assembly forecasts across the analysis window.
Calibration anchored segment-level projections to disclosed OEM production rates and supplier backlog data without year-specific binding. The modeling framework spanned type, material, application, and manufacturing process dimensions across the projection horizon. CAGRs derived from regression of historical procurement volumes against fleet expansion trajectories, incorporating titanium alloy substitution curves and additive manufacturing penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in commercial aviation traffic recovery, jet fuel price volatility, or interest rate sensitivity to aircraft financing would shift the trajectory. Forecasts embed assumptions on FAA additive qualification timelines and EASA environmental certification incentive durability. Quarterly review of Boeing and Airbus final assembly rate announcements, nickel-cobalt superalloy spot prices, and LPBF technician wage inflation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market