
 Global Aerospace Insulation Market | 2026-2036
Global Aerospace Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Insulation Market Foresight
Aerospace insulation procurement is decoupling into two distinct tiers: fire-rated advanced ceramics and aerogels command premium pricing for narrow-body and wide-body platforms, while commodity fiberglass batts face margin compression in aftermarket refurbishment. DuPont de Nemours, Inc. leverages its polyimide foam portfolio to dominate thermal protection for engine nacelles. BASF SE sustains R&D intensity in phase change material formulations for next-generation cabin systems. Zotefoams plc specializes in closed-cell nitrogen-expanded foams that compete on weight reduction for business jet interiors.
Aerospace insulation encompasses engineered materials and systems engineered to manage thermal transfer, acoustic transmission, and fire propagation across airframe structures, typically rated to withstand temperatures exceeding 1,100°C while maintaining densities below 50 kg/m³ for fuel-efficiency targets. Fiberglass retains volume leadership across cargo hold and secondary structure applications where legacy specifications dominate procurement. Aerogel segments capture the fastest expansion, driven by OEM mandates for 15-20% weight reduction in thermal protection systems. Ceramic fiber occupies the highest margin pool in military engine afterburner sections where replacement cycles remain captive to defense appropriations.
FAA Part 25.856 fire-blocking standards and EASA CS-25 certification protocols shape material qualification timelines, extending product development cycles to 4-7 years for new chemistries. REACH restrictions on formaldehyde-based binders are forcing European suppliers to reformulate mineral wool products ahead of compliance deadlines. The EU Green Deal's embodied carbon benchmarks for aviation supply chains are beginning to appear in Airbus supplier scorecards. Stakeholders must monitor how China's GB standards for civil aircraft materials converge with or diverge from FAA-EASA harmonization efforts.
Market Dynamics
OEM mandates for 15-20% weight reduction in thermal protection systems are compressing qualification timelines while forcing material substitution away from legacy fiberglass toward aerogel-ceramic hybrids. This pressure cascades through the supply chain, rewarding suppliers with captive aerospace certification capabilities and marginalizing commodity insulation producers.
Growth Catalysts
- FAA Part 25.856 fire-blocking standards:Accelerated adoption of advanced ceramic fiber blankets in engine nacelles and auxiliary power units as legacy phenolic-based materials fail new flame-penetration tests.
- China's civil aviation expansion:COMAC C919 production ramp and CR929 wide-body development are localizing demand for GB-standard certified insulation systems, creating parallel qualification pathways to FAA-EASA harmonization.
- Aerogel blanket manufacturing scale-up:Automated supercritical drying lines are reducing unit costs by half, enabling penetration into narrow-body platforms previously locked out by price premiums.
Market Restraints
- Silica precursor supply concentration:High-purity tetraethyl orthosilicate production concentrates in Germany and Japan, exposing aerogel manufacturers to input cost volatility and currency risk.
- REACH formaldehyde restrictions:European mineral wool reformulation requirements are extending product recertification cycles and forcing inventory write-downs of legacy binder systems.
- Technical limitation in cryogenic cycling:Polyimide foams suffer microcracking below -55°C, restricting their deployment in LNG-fueled aircraft fuel tank insulation despite weight advantages.
Strategic Opportunities
- Urban air mobility thermal management:Electric vertical takeoff aircraft battery compartments require novel phase-change material integration, opening a greenfield specification space outside traditional airframe procurement.
- EU Green Deal embodied carbon benchmarks:Airbus supplier scorecards now weight lifecycle emissions, creating first-mover advantage for insulation producers with verified low-carbon ceramic fiber production.
- India's defense aviation modernization:Indigenous Tejas fighter and AMCA program development is forcing HAL to qualify domestic insulation suppliers, bypassing traditional import dependence on US and European sources.
Industry Challenges
- 4-7 year FAA-EASA material qualification timelines:New chemistry introduction requires full-scale burn-through and smoke-toxicity testing, locking R&D capital in pre-revenue development phases.
- Legacy fleet retrofit specification drift:Aftermarket refurbishment contracts often default to original build standards, blocking insertion of improved insulation materials despite superior performance data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Insulation Market |
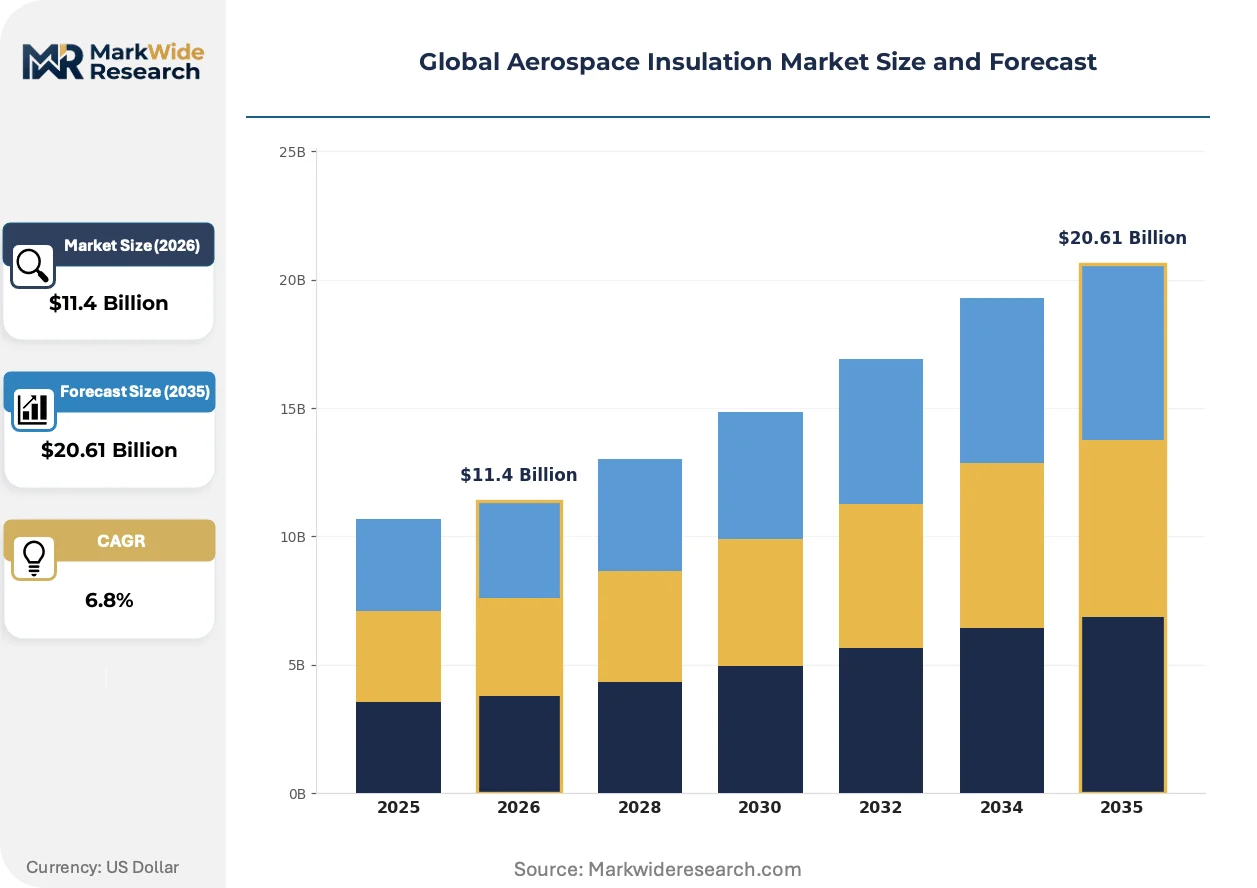
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Ceramic Fiber, Aerogel, Mineral Wool, Polyimide Foam Technology: Thermal Barrier Coatings, Vacuum Insulation Panels, Nanotechnology, Phase Change Materials, Acoustic Insulation Application: Cabin Insulation, Engine Components, Avionics, Cargo Holds, Fuel Tanks End User: Commercial Aircraft Manufacturers, Military Aviation, Spacecraft Producers, Business Jet OEMs, Helicopter Assemblers |
| Companies Covered | Duracote Corporation, Rogers Corporation, DuPont de Nemours, Inc., BASF SE, 3M Company, Triumph Group, Inc., Evonik Industries AG, Safran Group, Zotefoams plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Insulation Market Shifts & Advancements
Material science convergence is dissolving traditional boundaries between thermal, acoustic, and fire-protection functions, enabling multifunctional insulation systems that reduce part count and installation labor. This integration is reshaping supplier capabilities and procurement evaluation criteria across the value chain.
Aerogel composite blankets are expanding into narrow-body wing leading edges and empennage structures where previous density and handling constraints excluded their use. Boeing and Airbus thermal engineering teams have accelerated adoption timelines from experimental to series production within single platform generations. This expansion is compressing the addressable market for fiberglass batt suppliers in secondary structures.
REACH restrictions on formaldehyde-based mineral wool binders are forcing European suppliers to reformulate with bio-based alternatives ahead of 2025 compliance deadlines. The industrial consequence is a temporary supply squeeze as production lines retool, with qualified inventory commanding price premiums. German and French insulation manufacturers are most affected, accelerating partnerships with specialty chemical firms for compliant resin systems.
Airline procurement departments are unbundling insulation specification from airframe OEM contracts, directly qualifying alternative materials for aftermarket refurbishment. Maintenance, repair, and overhaul facilities in the United States and Germany are gaining technical authority to substitute improved materials during heavy checks. This disintermediation is most visible in cargo hold fire-blocking upgrades, where operators prioritize total cost of ownership over original equipment certification lineage.
Global Aerospace Insulation Market Segmentation
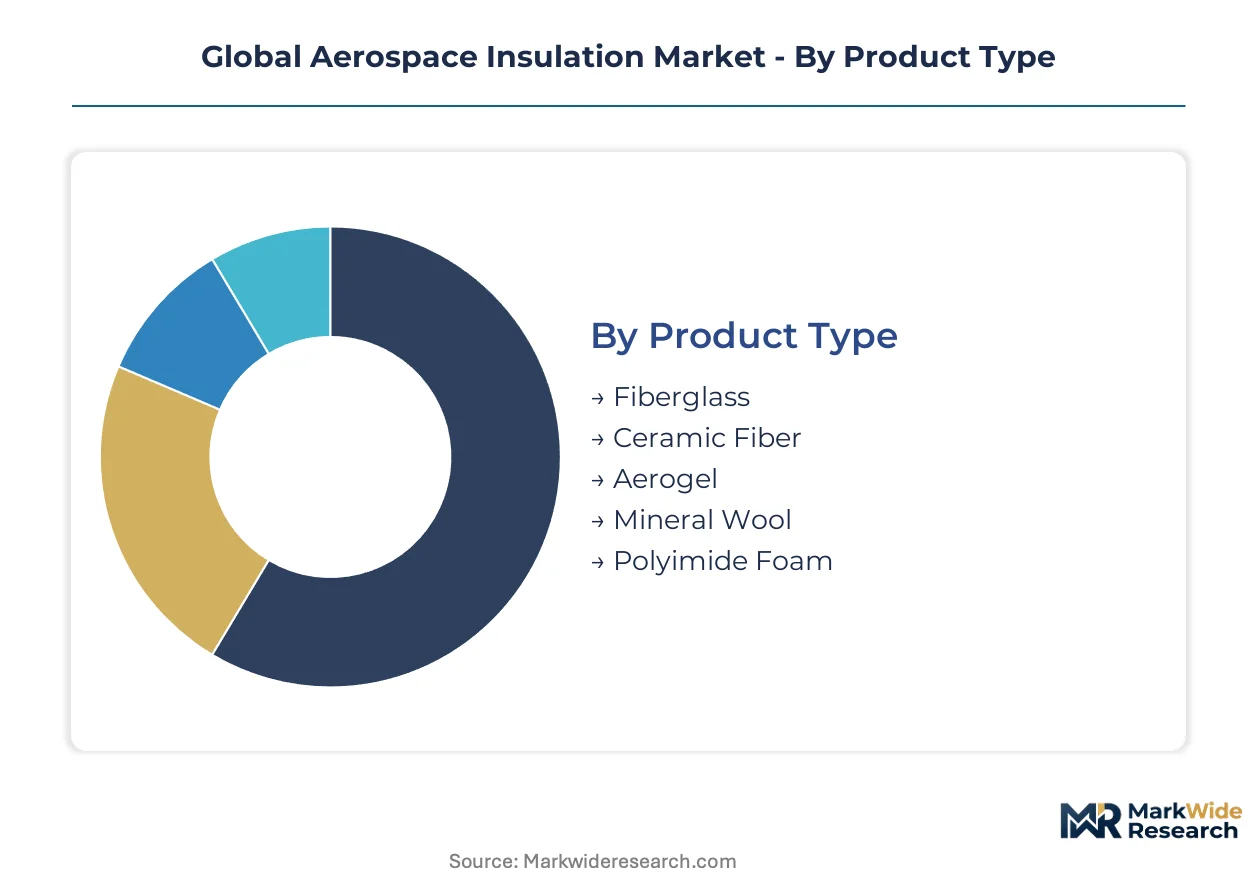
Aerospace insulation procurement operates through four intersecting classification systems that determine qualification pathways, pricing tiers, and supplier relationships. Product chemistry governs thermal performance ceilings and fire certification eligibility. Application location dictates regulatory jurisdiction and replacement cycle frequency.
Product Type:
Material composition defines the fundamental trade-off between weight, temperature tolerance, and manufacturing cost across airframe systems.
- Fiberglass:Woven silica-alumina glass fibers bound with phenolic or epoxy resins dominate cargo hold and secondary structure applications. Demand concentrates in United States-based MRO facilities performing legacy fleet refurbishment where original build specifications lock out premium alternatives.
- Aerogel:Silica-based supercritical-dried gels with densities below 150 kg/m³ command OEM adoption for wing leading edges and empennage thermal protection. Boeing and Airbus engineering mandates for 15-20% weight reduction are accelerating substitution away from fiberglass in narrow-body platforms.
- Ceramic Fiber:Alumina-silica spun blankets rated to 1,260°C anchor military engine afterburner sections and auxiliary power units.
- Mineral Wool:Slag or rock-based fibers with bio-based binders are reformulating under REACH compliance pressure in European supply chains.
- Polyimide Foam:Closed-cell aromatic polymer structures from DuPont and competitors specialize in engine nacelle thermal protection where FAA Part 25.856 fire-blocking standards apply.
Fiberglass leads on scale; aerogel leads on momentum.
Technology:
Functional engineering approaches segment by integration complexity and performance specialization rather than base chemistry alone.
- Thermal Barrier Coatings:Ceramic topcoats deposited via plasma spray or electron beam physical vapor deposition protect turbine blades and combustor liners from gas path temperatures exceeding 1,400°C. Rolls-Royce and Pratt & Whitney engine programs in the United Kingdom and United States anchor procurement volume.
- Vacuum Insulation Panels:Fumed silica or aerogel cores evacuated to sub-atmospheric pressure deliver R-values five times conventional materials for business jet galley and lavatory compartments where space constraints override cost sensitivity.
- Nanotechnology:Carbon nanotube or graphene-enhanced matrices are emerging in experimental airframe programs.
- Phase Change Materials:Paraffin or salt hydrate formulations absorb latent heat during cabin temperature excursions.
- Acoustic Insulation:Resonant chamber and damping layer composites address jet noise attenuation requirements.
Thermal barrier coatings dominate current procurement spend; vacuum insulation panels are climbing the fastest on business jet platform adoption.
Application:
Physical location within the airframe determines fire certification tier, environmental exposure severity, and accessibility for aftermarket service.
- Cabin Insulation:Multi-layer blankets combining thermal, acoustic, and fire-blocking functions line fuselage crown and sidewall panels. Airbus and Boeing final assembly lines in France, Germany, and the United States specify these systems directly.
- Engine Components:High-temperature seals, gaskets, and wrap-around insulation for nacelles, thrust reversers, and exhaust nozzles face the most stringent FAA-EASA burn-through testing protocols.
- Avionics:Conformal coatings and potting compounds protect flight control computers from thermal cycling.
- Cargo Holds:Fire-blocking liners must contain flame propagation for minimum 5 minutes per FAA Part 25.856.
- Fuel Tanks:Cryogenic-rated foams and sealants address LNG and hydrogen storage systems in development.
Cabin insulation generates the broadest supplier base; engine components concentrate margin capture among certified specialists.
End User:
Customer category shapes procurement authority structures, specification control, and contract duration horizons.
- Commercial Aircraft Manufacturers:Boeing, Airbus, and COMAC airframe programs drive 60-70% of annual insulation demand through multi-year supply agreements with technical qualification requirements. Their supplier scorecards increasingly weight EU Green Deal embodied carbon benchmarks.
- Military Aviation:Defense appropriations in the United States, United Kingdom, and India fund engine and airframe insulation with classified performance specifications and captive supply chain security requirements.
- Spacecraft Producers:Re-entry vehicle thermal protection systems and launch vehicle cryogenic tank insulation represent specialized procurement with extreme temperature gradients.
- Business Jet OEMs:Gulfstream, Bombardier, and Dassault programs prioritize weight reduction and cabin acoustic comfort over unit cost.
- Helicopter Assemblers:Turboshaft engine compartments and transmission bays require vibration-resistant insulation formats.
Commercial aircraft manufacturers command procurement volume; military aviation sustains the highest technical barriers to supplier entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's civil aviation expansion is outpacing European production rates, while the United States retains the densest concentration of certified insulation suppliers. Germany anchors specialty chemical feedstock production for advanced aerogel precursors.
United States
Boeing's final assembly lines in Everett and Charleston drive thermal protection system procurement for 737 MAX and 787 programs. FAA Part 25.856 fire-blocking standards mandate advanced ceramic fiber adoption in engine nacelles. Wichita's business jet manufacturing cluster sustains demand for lightweight acoustic insulation from Gulfstream and Bombardier programs.
China
COMAC C919 production ramp and CR929 wide-body development are localizing demand for GB-standard certified insulation systems. MIIT civil aircraft material certification creates parallel qualification pathways to FAA-EASA harmonization. Shanghai Pudong and Xi'an aircraft manufacturing bases anchor procurement for thermal protection and cabin insulation systems.
Germany
Airbus Hamburg and Bremen final assembly lines specify multi-layer thermal-acoustic blankets for A320 and A350 programs. REACH formaldehyde restrictions are forcing mineral wool reformulation ahead of compliance deadlines. Leverkusen and Ludwigshafen chemical clusters supply high-purity silica precursors for aerogel manufacturing across European aerospace supply chains.
France
Safran Group's engine programs in Villaroche and Le Creusot anchor ceramic fiber demand for LEAP and M88 powerplants. EASA CS-25 certification protocols extend material qualification timelines for new chemistries. Toulouse Airbus headquarters coordinates supplier scorecards weighting EU Green Deal embodied carbon benchmarks for insulation procurement.
India
HAL's Tejas fighter and AMCA program development is forcing qualification of domestic insulation suppliers. Defense aviation modernization appropriations bypass traditional import dependence on US and European sources. Bangalore and Hyderabad aerospace clusters are emerging as alternative procurement channels for military engine thermal protection systems.
Global Aerospace Insulation Market Competitive Landscape
Top-tier vendors anchor OEM supply agreements, while mid-scale specialists compete on aftermarket refurbishment contracts. The vendor base stratifies between multinational chemical conglomerates with captive aerospace certification and regional fabricators serving MRO facilities. Three archetypes dominate: diversified materials conglomerates, pure-play aerogel specialists, and vertically integrated textile converters. Competitive moves concentrate on strategic partnerships for supercritical drying capacity and geographic expansion into COMAC supply chains.
Among diversified materials conglomerates, DuPont de Nemours, Inc. and BASF SE exemplify the premium-tier vector through polyimide foam and phase change material portfolios. Zotefoams plc occupies a position within the specialist tier, representing nitrogen-expanded foam capabilities for weight-sensitive applications. These three anchors illustrate how certification depth and chemical feedstock access determine competitive positioning across OEM and aftermarket channels.
| Leading Market Players |
|---|
| Duracote Corporation |
| Rogers Corporation |
| DuPont de Nemours, Inc. |
| BASF SE |
| 3M Company |
| Triumph Group, Inc. |
| Evonik Industries AG |
| Safran Group |
| Zotefoams plc |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon benchmarks are gating qualified supply and premium-tier pricing access, as Airbus supplier scorecards now weight lifecycle emissions alongside FAA-EASA certification lineage. This sustainability mandate bifurcates procurement: low-carbon ceramic fiber producers command 15-25% price premiums while legacy mineral wool suppliers face margin compression during REACH-driven reformulation cycles.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for high-purity silica precursors that feed aerogel manufacturing lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale: OEM direct contracts for engine nacelle insulation anchor premium tiers, while aftermarket refurbishment contracts for cargo hold batts compete on unit cost. Cost compression in commodity fiberglass is intensifying because airline procurement departments are unbundling insulation specification from airframe OEM contracts. Maintenance, repair, and overhaul facilities demonstrate highest price sensitivity; business jet OEMs show least sensitivity due to weight-reduction mandates.
Supply Chain Analysis
FAA-EASA material qualification timelines extending to 4-7 years create formidable certification gating that concentrates qualified supply among incumbent chemical conglomerates. Germany, Japan, and the United States anchor production of high-purity tetraethyl orthosilicate, ceramic fiber precursors, and polyimide foam resin systems. Raw material dependencies rest on silica sand deposits, aromatic polymer feedstocks, and bio-based binder formulations. Single-source vulnerability concentrates in German chemical clusters supplying aerospace-grade precursors. Distribution runs through Tier 1 aerostructures suppliers with captive qualification capabilities rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Aerospace Insulation Market reads as a late-cycle quality story, as OEM mandates for 15-20% weight reduction in thermal protection systems shift procurement toward aerogel-ceramic hybrids with premium pricing durability.
For Market Incumbents: Hedge against silica precursor supply concentration by securing long-term offtake agreements with German and Japanese chemical producers before capacity constraints tighten. Deepen backward integration into supercritical drying equipment to protect margin structure as automated aerogel lines commoditize mid-tier supply. Counter the threat of COMAC localization by accelerating GB-standard certification investment ahead of CR929 program ramp. For New Entrants and Emerging Players: Launch via urban air mobility battery compartment thermal management specifications, where electric vertical takeoff aircraft create greenfield demand outside traditional airframe procurement channels. Target India's defense aviation modernization as the most penetrable geography, where HAL's Tejas and AMCA programs are forcing domestic supplier qualification. Pursue phase-change material integration partnerships with eVTOL platform developers as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialty aerogel fabricators because 4-7 year FAA-EASA qualification timelines create durable competitive moats that deter new chemistry entrants. Five-to-ten year viability hinges on supercritical drying capacity access and COMAC supply chain positioning. Watch for Airbus supplier scorecard expansion of EU Green Deal embodied carbon benchmarks as the inflection signal indicating premium-tier pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical Drying Capacity Expansion | Automated aerogel lines at BASF and Evonik halve unit costs for narrow-body penetration. |
| GB-Standard Certification Investment | MIIT alignment with FAA-EASA protocols opens COMAC C919 and CR929 supply positions. |
| Low-Carbon Ceramic Fiber Production | Verified lifecycle emissions satisfy Airbus supplier scorecards for premium-tier access. |
| Urban Air Mobility Partnership | eVTOL battery compartment specifications create thermal management demand outside legacy channels. |
| Indian Defense Supply Localization | HAL's Tejas and AMCA programs bypass import dependence for military engine insulation. |
Research Methodology
Bottom-up airframe platform modeling reconciled against top-down chemical feedstock tracking forms the analytical core of this study. Primary interviews with thermal protection system engineers, airframe procurement directors, MRO facility managers, and specialty chemical R&D leads combined with secondary validation from FAA certification databases, EASA CS-25 submission records, COMAC GB-standard filings, and EU REACH compliance registries. Trade data from German and Japanese customs authorities on tetraethyl orthosilicate flows anchored supply-side calibration.
Historical trendline analysis across installed base replacement cycles and OEM delivery schedules established baseline growth patterns. Segmentation dimensions modeled include material chemistry tier, application location within airframe, end-user category, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves reflect how weight-reduction mandates and fire-safety standard upgrades propagate through procurement channels. Industry-specific forecast inputs incorporated Boeing and Airbus thermal engineering team adoption timelines for aerogel composite blankets.
Several conditions sit outside the modeled scope, including classified military engine performance specifications, spacecraft re-entry vehicle thermal protection systems, and hydrogen-fueled aircraft cryogenic tank insulation still in experimental development. Forecasts reflect assumptions regarding FAA-EASA harmonization stability and COMAC production ramp schedules. A model refresh is warranted upon material change in EU Green Deal embodied carbon benchmark enforcement or GB-standard divergence from Western certification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market