
 Global Aircraft Nacelle and Thrust Reverser Market | 2026-2036
Global Aircraft Nacelle and Thrust Reverser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Nacelle and Thrust Reverser Market Intelligence
The market for aircraft nacelles and thrust reversers is pivoting on the divergence between advanced, integrated propulsion systems for new-generation aircraft and the standardized MRO replacement parts market. Safran specializes in highly integrated nacelle systems for new engine platforms. Collins Aerospace leverages its extensive MRO network to supply aftermarket components globally, while Spirit AeroSystems competes by manufacturing complex aerostructures like pylons for major OEMs.
An aircraft nacelle is the streamlined housing for an engine, designed to minimize aerodynamic drag and protect internal components. A thrust reverser is a critical sub-assembly within the nacelle that redirects engine exhaust forward to assist in deceleration during landing. Commercial airliners represent the largest application, driven by single-aisle aircraft production. The adoption of composite materials and advanced titanium alloys is displacing traditional aluminum alloys to reduce weight and improve fuel efficiency.
Airworthiness standards from the FAA in the United States and EASA in Europe dictate design and material requirements. These regulations, along with ICAO's noise standards, compel innovation in acoustic liners and aerodynamic efficiency. Key stakeholders must balance in-house production capabilities against reliance on specialized Tier 1 suppliers for future engine programs.
Market Dynamics
The market's structure is defined by the bifurcation between advanced, integrated propulsion systems for new aircraft and the high-volume aftermarket for legacy fleets. This dual demand model shapes supplier strategy and investment priorities across the value chain, balancing innovation with MRO support.
Growth Catalysts
- Air Traffic Expansion:Surging air passenger volumes, particularly in China and India, are compelling airlines to expand their fleets, directly increasing orders for new single-aisle and wide-body aircraft and their associated nacelle systems.
- Composite Material Adoption:The aviation industry's push for lightweighting to improve fuel efficiency and reduce emissions accelerates the use of carbon fiber reinforced polymers and ceramic matrix composites in nacelle and thrust reverser manufacturing.
- Stringent Noise Regulations:ICAO's noise certification standards, enforced by bodies like EASA and the FAA, mandate the development of advanced acoustic liners and chevrons, creating demand for innovative nacelle designs that reduce engine noise.
Market Restraints
- Titanium and Composite Costs:High price volatility and supply chain concentration for aerospace-grade titanium alloys and carbon fiber precursors create significant cost pressures for nacelle manufacturers, impacting program profitability and pricing stability.
- Propulsion System Integration Complexity:The increasing integration of the nacelle with the engine and pylon creates extreme design and engineering challenges, extending development timelines and raising non-recurring costs for new aircraft programs.
- Lengthy Certification Cycles:The rigorous and time-consuming airworthiness certification processes mandated by the FAA and EASA for new materials and designs act as a significant barrier to entry and slow the introduction of innovations.
Strategic Opportunities
- Next-Generation Propulsion:The development of hybrid-electric and hydrogen-powered aircraft presents a significant opportunity to design entirely new nacelle architectures, including those with distributed propulsion systems and advanced thermal management solutions.
- MRO Service Expansion:Expanding capabilities in Maintenance, Repair, and Overhaul for composite structures and thrust reverser actuation systems offers a recurring revenue stream, particularly for large in-service fleets.
- Emerging MRO Hubs:Establishing specialized MRO facilities in Southeast Asia and the Middle East can capture growing regional demand for nacelle component repair, reducing turnaround times and logistics costs for local airlines.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians and engineers with expertise in composite material repair and advanced non-destructive testing techniques constrains MRO capacity and inflates labor costs for specialized nacelle maintenance.
- Supply Chain Fragility:Managing a multi-tiered global supply chain with long lead times for critical components like forgings and actuators poses a constant operational risk, with disruptions directly impacting OEM production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Nacelle and Thrust Reverser Market |
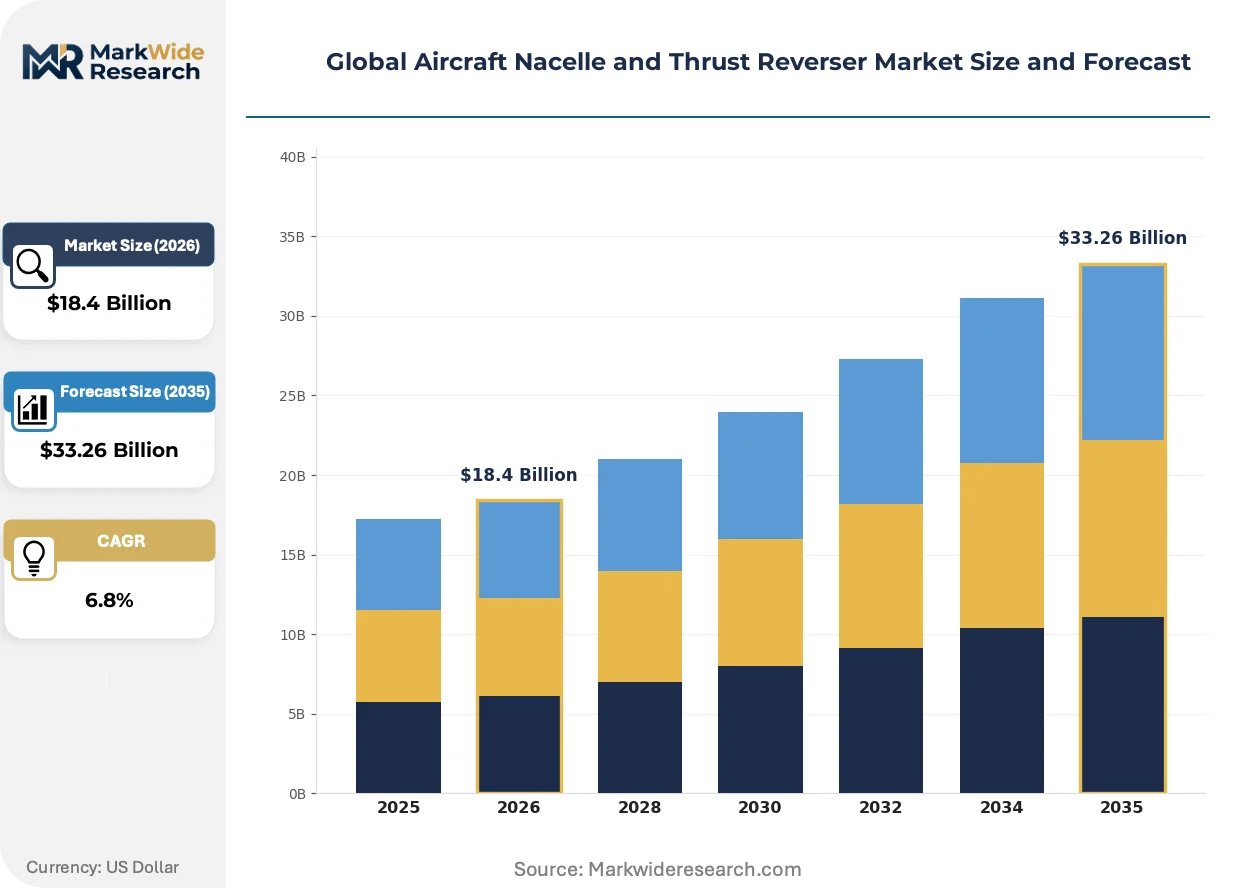
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Nacelle, Fan Cowling, Thrust Reverser Assembly, Strut, Pylon Technology: Composite Materials, Titanium Alloys, Aluminum Alloys, Carbon Fiber Reinforced Polymer, Hybrid Metal Composites Application: Commercial Airliners, Private Jets, Military Aircraft, Cargo Planes, Regional Aircraft End User: OEM Manufacturers, Maintenance Repair Organizations, Aircraft Leasing Firms, Charter Operators, Aviation Service Providers |
| Companies Covered | Safran, Collins Aerospace, Spirit AeroSystems, GKN Aerospace, The NORDAM Group, FACC AG, Aernnova Aerospace, Woodward, Magellan Aerospace Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Nacelle and Thrust Reverser Market Strategic Shifts & Innovations
A dual focus on sustainability and digitalization is fundamentally altering nacelle design and manufacturing. Innovations are increasingly driven by the need to meet stricter environmental targets and leverage data for predictive maintenance and operational efficiency across the aerospace industry.
Ultra-High Bypass Ratio (UHBR) engines require larger, more complex nacelle systems with advanced acoustic treatments. New-generation single-aisle and wide-body aircraft programs are the primary adopters of this technology. This trend is modularizing nacelle design, separating structural components from acoustic and system sub-assemblies to simplify manufacturing, maintenance, and future upgrades for engine families.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure of environmental impacts throughout the supply chain. This regulation is forcing Tier 1 suppliers and OEMs to quantify and report the carbon footprint of their manufacturing processes and materials, including nacelle components. The aerospace value chain must now invest in traceability and life-cycle assessment capabilities.
Airlines are increasingly favoring long-term, flight-hour-based service agreements for propulsion systems, bundling nacelle MRO with engine maintenance. This model shifts financial risk to the OEM and major MRO providers, displacing traditional time-and-materials repair contracts. This trend is most prominent among large fleet operators in North America and Europe who seek predictable maintenance costs.
Global Aircraft Nacelle and Thrust Reverser Market Segmentation
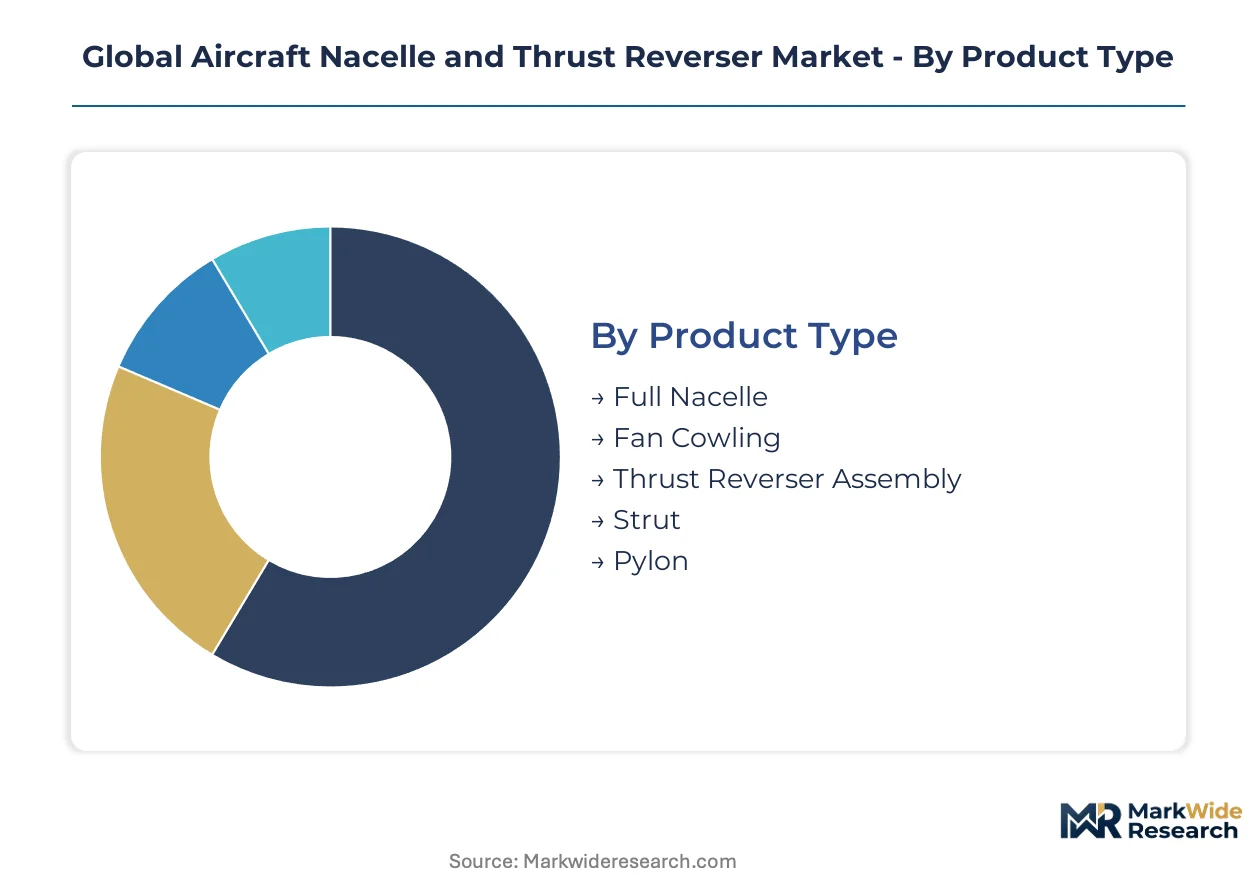
Understanding the segmentation of the global aircraft nacelle and thrust reverser market is crucial for stakeholders to identify specific demand drivers and allocate resources effectively. This detailed breakdown reveals distinct market dynamics across various product types, underlying technologies, aircraft applications, and the diverse end-user landscape.
Product Type:
Buyers in this category differentiate based on the specific structural component required for engine integration and aerodynamic performance, each serving a distinct function within the propulsion system.
- Full Nacelle:This integrated housing encases the entire aircraft engine, providing aerodynamic shaping, noise attenuation, and protection for internal components. Demand concentrates in new aircraft programs for commercial airliners, driven by the need for optimized, integrated propulsion systems.
- Thrust Reverser Assembly:A critical sub-assembly located at the rear of the nacelle, designed to redirect engine exhaust forward to aid in aircraft deceleration during landing. Demand is consistently strong in the Maintenance, Repair, and Overhaul (MRO) market for commercial airliners due to operational wear and tear.
- Fan Cowling:The outer shell covering the engine's fan section, contributing significantly to aerodynamic efficiency and engine cooling.
- Strut:This structural component connects the nacelle to the aircraft wing or fuselage, bearing the engine's weight and transmitting thrust loads.
- Pylon:A primary structural element that attaches the engine and its nacelle assembly to the airframe, ensuring secure mounting and load transfer.
Volume sits with Full Nacelle and Thrust Reverser Assembly; growth tilts toward integrated nacelle systems.
Technology:
Technology choices in nacelle and thrust reverser manufacturing are driven by performance requirements, material properties, and the constant push for weight reduction.
- Composite Materials:These advanced, lightweight, and high-strength materials, such as carbon fiber, are increasingly used to reduce overall aircraft weight. Demand concentrates in new-generation commercial airliners, driven by stringent fuel efficiency targets and emissions reduction mandates.
- Carbon Fiber Reinforced Polymer:A specific type of composite material offering exceptional strength-to-weight ratios and stiffness, crucial for modern aerospace applications. Adoption is accelerating in Ultra-High Bypass Ratio (UHBR) engine nacelles due to stringent weight reduction goals and structural integrity needs.
- Titanium Alloys:Known for high strength, excellent corrosion resistance, and ability to withstand high temperatures, titanium alloys are used in critical, high-heat sections of nacelles.
- Aluminum Alloys:Traditional aerospace materials still employed in less critical or older nacelle structures, offering a balance of cost and performance.
- Hybrid Metal Composites:These materials combine metallic and composite layers, providing enhanced fatigue resistance, damage tolerance, and specific performance characteristics.
Material innovation is pushing towards lightweight solutions, with composite adoption expanding fastest.
Application:
The operational demands and fleet sizes of different aircraft applications dictate nacelle and thrust reverser specifications and procurement patterns.
- Commercial Airliners:This segment represents the largest application, encompassing single-aisle and wide-body passenger aircraft globally. Demand concentrates in China and the United States, driven by expanding air passenger traffic and fleet modernization programs.
- Regional Aircraft:Smaller passenger planes serving shorter routes, often with specific design constraints for noise and operational efficiency. New aircraft programs in this segment require optimized nacelle designs for noise reduction and fuel efficiency.
- Private Jets:High-performance business aircraft demanding custom-engineered, aesthetically integrated nacelle solutions with advanced acoustic treatments.
- Military Aircraft:Require robust, often stealth-optimized nacelles capable of enduring extreme operational conditions and high-G maneuvers.
- Cargo Planes:Large freighter aircraft focused on payload capacity, needing durable and efficient propulsion system housings to support long-haul operations.
Commercial Airliners dominate demand, while Regional Aircraft present significant growth opportunities.
End User:
End-user categories reflect distinct purchasing patterns and service requirements for nacelle and thrust reverser components across the aerospace value chain.
- OEM Manufacturers:These companies acquire nacelle and thrust reverser systems for integration into new aircraft builds. Their demand is directly tied to new aircraft orders and production rates from airlines globally.
- Maintenance Repair Organizations:MROs provide aftermarket services, including repairing, overhauling, and replacing existing nacelle components for in-service fleets. MROs manage a substantial portion of the ongoing operational requirements for airlines.
- Aircraft Leasing Firms:These firms influence demand by specifying maintenance contracts and component standards for the aircraft they lease to various operators.
- Charter Operators:Procure components for smaller, often specialized fleets, prioritizing component reliability and quick turnaround times to minimize aircraft downtime.
- Aviation Service Providers:Offer a range of support services, including component procurement, logistics, and technical assistance for various aircraft operators and MROs.
New build demand originates from OEM Manufacturers, while aftermarket needs drive MRO and service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse, France, serves as a significant hub for aircraft manufacturing, influencing demand for integrated nacelle systems. Global air traffic expansion drives new aircraft orders across key regions. Fleet modernization programs in established markets and expanding passenger volumes in emerging economies shape regional demand patterns for nacelles and thrust reversers.
United States
New aircraft deliveries and ongoing fleet modernization programs drive demand for advanced nacelle systems in the United States. FAA airworthiness standards mandate rigorous design and material requirements for all components. Major aerospace clusters like Wichita, Kansas, and Seattle, Washington, focus on both original equipment manufacturing and MRO activities for these critical parts.
France
French aerospace manufacturing, centered around Airbus production, creates consistent demand for highly integrated nacelle and thrust reverser systems. EASA certification processes influence design and material choices for European-produced aircraft. The Toulouse region anchors significant research and development for next-generation propulsion integration, involving major Tier 1 suppliers.
Germany
German aerospace companies contribute to both new aircraft programs and the extensive MRO market for nacelles and thrust reversers. The EU Green Deal initiatives accelerate research into lightweight composite materials and advanced acoustic solutions. Hamburg remains a vital center for aircraft assembly and maintenance, supporting a robust supply chain for nacelle components.
China
Expanding air passenger traffic in China fuels substantial demand for new single-aisle and wide-body aircraft, requiring associated nacelle and thrust reverser systems. MIIT industrial policies encourage domestic aerospace manufacturing capabilities and technological advancement. Shanghai, with its COMAC final assembly lines, and Xi'an, a major aerospace manufacturing base, are key demand centers.
India
India's growing aviation sector and fleet expansion plans generate increasing demand for both new nacelles and MRO services. The PLI scheme for aerospace manufacturing aims to boost local production and reduce reliance on imports. Bengaluru, a prominent aerospace and defense hub, focuses on maintenance, repair, and overhaul activities, including for complex composite structures.
Global Aircraft Nacelle and Thrust Reverser Market Key Industry Players
Premium-margin players sit above commodity-margin players across the aircraft nacelle and thrust reverser market, reflecting varying levels of technological integration and service offerings. The market structure exhibits a tiered consolidation, with a few major players dominating integrated system supply for new aircraft programs. Strategic partnerships between engine OEMs and nacelle specialists are common, alongside targeted capacity expansion in advanced material processing.
Within the integrated systems tier, Safran and Collins Aerospace exemplify leaders providing comprehensive nacelle solutions, often bundled with engine programs. Spirit AeroSystems occupies a position as a specialized aerostructures manufacturer, supplying complex pylons and other critical components to major airframe OEMs. These companies leverage extensive engineering capabilities and global supply chains to meet stringent aerospace requirements.
| Leading Market Players |
|---|
| Safran |
| Collins Aerospace |
| Spirit AeroSystems |
| GKN Aerospace |
| The NORDAM Group |
| FACC AG |
| Aernnova Aerospace |
| Woodward |
| Magellan Aerospace Corporation |
| Others |
Cost & Logistics Intelligence
The transition to lightweight composite materials fundamentally reshapes both cost economics and supply concentration for aircraft nacelle and thrust reverser components. This shift necessitates new sourcing strategies and impacts profitability across the value chain.
Pricing Analysis
Long-term, flight-hour-based service agreements for propulsion systems anchor nacelle MRO pricing to predictable uptime and operational performance. Price differentiation stems from advanced material certification requirements and the level of customization for specific aircraft programs. Cost compression intensifies due to the high price volatility of titanium and carbon fiber precursors, impacting profitability. MRO providers exhibit high price sensitivity for legacy replacement parts, whereas OEM manufacturers prioritize integrated system performance.
Supply Chain Analysis
MIIT industrial policies in China and India's PLI scheme reshape sourcing by mandating increased domestic content for aerospace manufacturing. Supply concentrates in specialized facilities across the United States, France, and China. The industry relies heavily on carbon fiber precursors, aerospace-grade titanium alloys, and complex actuators. Single-source vulnerability for specialized forgings and acoustic liners represents a persistent structural risk. Distribution runs through direct channels to OEM final assembly lines and a global MRO network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft nacelle and thrust reverser market navigates a technology-transition phase, as advanced composite systems increasingly replace traditional aluminum alloy structures. This shift drives innovation and redefines competitive advantages for manufacturers.
For Market Incumbents:Deepen investments in research and development for next-generation propulsion integration, particularly hybrid-electric and hydrogen-powered aircraft. Expand global MRO capabilities for advanced composite structure repair to address the growing in-service fleet. This mitigates the threat from emerging specialized material suppliers and new propulsion architectures. Prioritize certification investments with FAA and EASA for novel designs and materials.
For New Entrants and Emerging Players:Specialized MRO providers can target white-space opportunities by partnering with regional airlines in Southeast Asia. Focus on niche MRO services for composite structures and advanced thermal management solutions for new propulsion architectures. The regional aircraft MRO segment in Southeast Asia remains highly penetrable for specialized providers. Offer rapid turnaround times and lower logistics costs as a primary go-to-market angle.
For Investors and Strategic Acquirers:Re-rating potential sits with vertically integrated Tier 1 suppliers given the increasing complexity of nacelle-engine integration. Long-term viability is strong, driven by global fleet expansion and sustained MRO demand for in-service aircraft. Acquisition targets include mid-cap specialists in advanced composite manufacturing or acoustic liner technology. Significant new aircraft program launches featuring novel propulsion systems serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Composite R&D | Accelerates fuel efficiency gains for commercial airliners, aligning with EU Green Deal initiatives. |
| Expand Global MRO Network | Captures recurring revenue from aging fleets and reduces turnaround times for airline operators. |
| Form Engine OEM Partnerships | Secures integrated nacelle system contracts for future Ultra-High Bypass Ratio engine platforms. |
| Develop Hydrogen Propulsion Nacelle Architectures | Positions companies for the next generation of sustainable aviation, meeting ICAO emissions targets. |
| Strengthen Supply Chain Resilience | Mitigates risks from commodity price volatility and geopolitical disruptions for critical materials. |
Research Approach
Multi-period observation of new aircraft order backlogs, MRO contract renewals, and material adoption rates anchored the trend analysis, supplemented by interviews. Primary research involved discussions with OEM executives, MRO engineers, airline procurement managers, and material scientists. Secondary data sources included air traffic statistics, FAA and EASA regulatory filings, aerospace association reports, and company financial disclosures. This approach ensured robust bottom-up and top-down triangulation.
Segment-weighting approaches informed the quantitative model, integrating historical data and projected trends across the analysis window. Segmentation dimensions included product type, underlying technology, aircraft application, end-user category, and regional demand patterns. Compound Annual Growth Rates were derived from a weighted average of individual segment growth rates. Projected aircraft deliveries and MRO service contract volumes served as key forecast inputs.
Caveats apply where geopolitical conflicts, supply chain disruptions, or new regulatory mandates could materially shift the outlook. Forecasts reflect a specific set of assumptions regarding market dynamics and technological advancements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market