
 Airborne Target Acquisition Systems Market | 2026-2036
Airborne Target Acquisition Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Target Acquisition Systems Market Analysis
Buyer concentration among national defense ministries is pivoting toward multi-year platform contracts that bundle sensors, software, and sustainment. Lockheed Martin dominates fixed-wing integration programs with sustained investment in sensor fusion architectures. BAE Systems competes through specialized electronic warfare and targeting pod portfolios across NATO customer bases.
Airborne target acquisition systems integrate radar, electro-optical, infrared, and LIDAR sensors with real-time data processing to detect, track, and designate targets for precision engagement. These platforms operate across wavelengths from millimeter-wave through short-wave infrared, with stabilization accuracies below 50 microradians to maintain lock during aircraft maneuvering. Electro-optical systems anchor current procurement volumes due to mature supply chains and broad platform compatibility, while autonomous systems represent the fastest-expanding technology category as unmanned combat aircraft gain operational clearance. Military end users command the dominant share of funded programs, though defense contractors increasingly serve as system integrators for foreign military sales.
The US Department of Defense, NATO Standardization Office, and FAA shape certification pathways and interoperability mandates for airborne targeting equipment, with the FAA governing civil airspace integration of sensor-carrying platforms. The EU AI Act and emerging autonomous weapons governance frameworks in Brussels and Geneva are forcing suppliers to document algorithmic decision boundaries and human-machine interface protocols. Stakeholders must monitor how export control expansions under the Wassenaar Arrangement affect cross-border transfers of synthetic aperture radar and automatic target recognition software modules.
Market Dynamics
Multi-sensor fusion architectures are compressing procurement cycles as defense ministries consolidate radar, electro-optical, and infrared capabilities onto unified platforms rather than acquiring discrete systems separately.
Growth Catalysts
- Joint All-Domain Command and Control:The US Department of Defense's JADC2 initiative mandates interoperable targeting data links across air, sea, and ground assets, forcing sensor standardization that benefits integrated system suppliers.
- Electro-optical supply chain maturity:Established manufacturing bases for stabilized gimbals and focal plane arrays enable faster platform certification and lower unit costs for NATO airborne ISR programs.
- Unmanned combat aircraft clearance:Operational authorization for autonomous strike platforms is expanding addressable demand beyond manned fighter and bomber fleets into attritable drone architectures.
Market Restraints
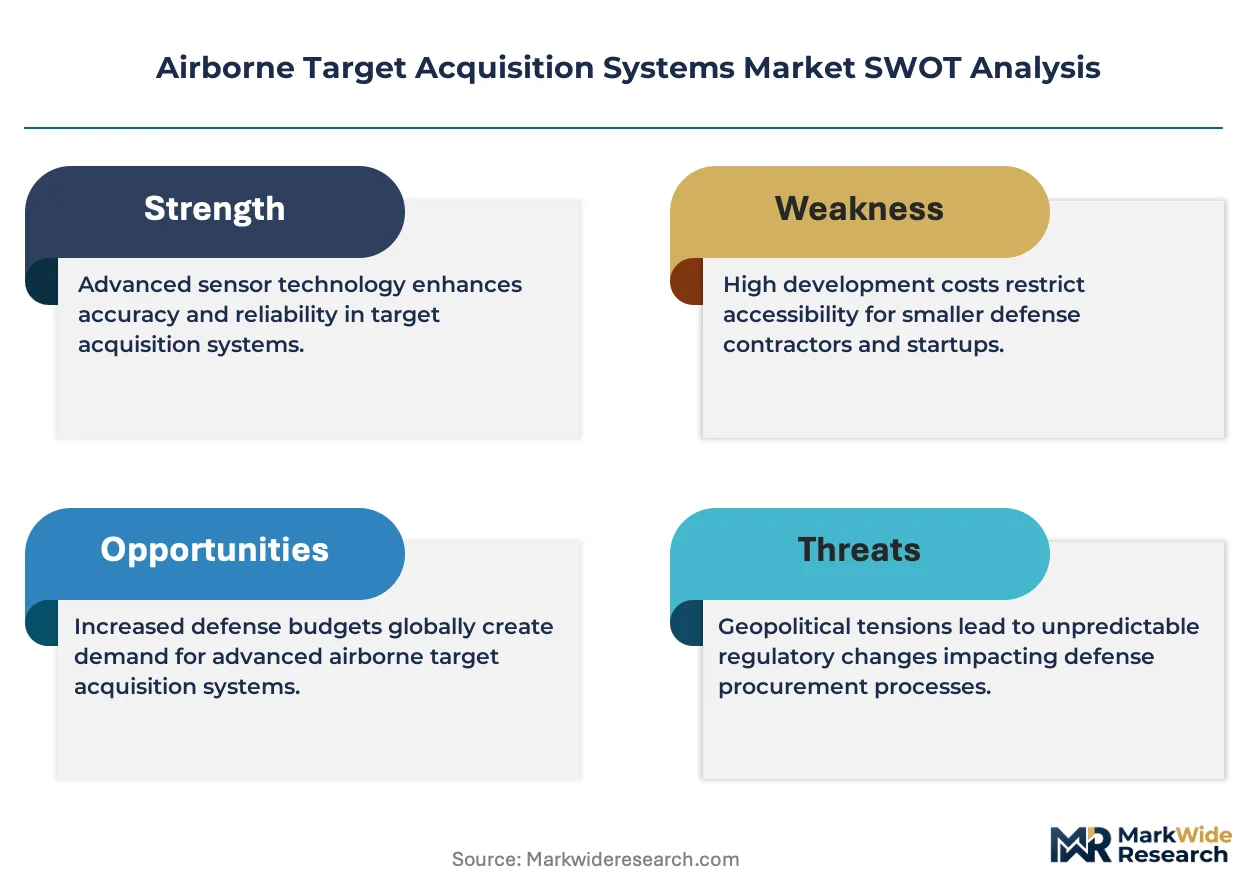
- Gallium arsenide substrate concentration:Millimeter-wave radar and infrared detector manufacturing depends on specialized semiconductor foundries concentrated in East Asia, creating single-source vulnerability for critical sensor components.
- EU AI Act algorithmic documentation:Brussels-mandated transparency requirements for autonomous target recognition systems impose development delays and compliance costs that disadvantage smaller subsystem suppliers.
- Synthetic aperture radar substitution:High-resolution commercial satellite imagery at declining price points threatens demand for airborne SAR in certain intelligence-gathering missions.
Strategic Opportunities
- India's indigenous fighter programs:The Tejas Mk2 and AMCA development timelines create openings for foreign sensor houses to partner with Hindustan Aeronautics Limited on domestic production requirements under offset agreements.
- LIDAR-radar convergence:Fusing active laser ranging with radio-frequency sensing enables all-weather target designation through obscurants, a capability gap in current electro-optical dominated inventories.
- Foreign Military Sales bundling:The US State Department's streamlined congressional notification process for allied interoperability packages allows prime contractors to attach targeting pods to fighter export contracts.
Industry Challenges
- 50-microradian stabilization engineering:Maintaining target lock during high-G maneuvering demands precision mechanical and active optical compensation expertise that resides in a narrow contractor base.
- Wassenaar Arrangement software controls:Automatic target recognition algorithms fall under dual-use export restrictions, complicating international maintenance and upgrade cycles for deployed systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Target Acquisition Systems Market |
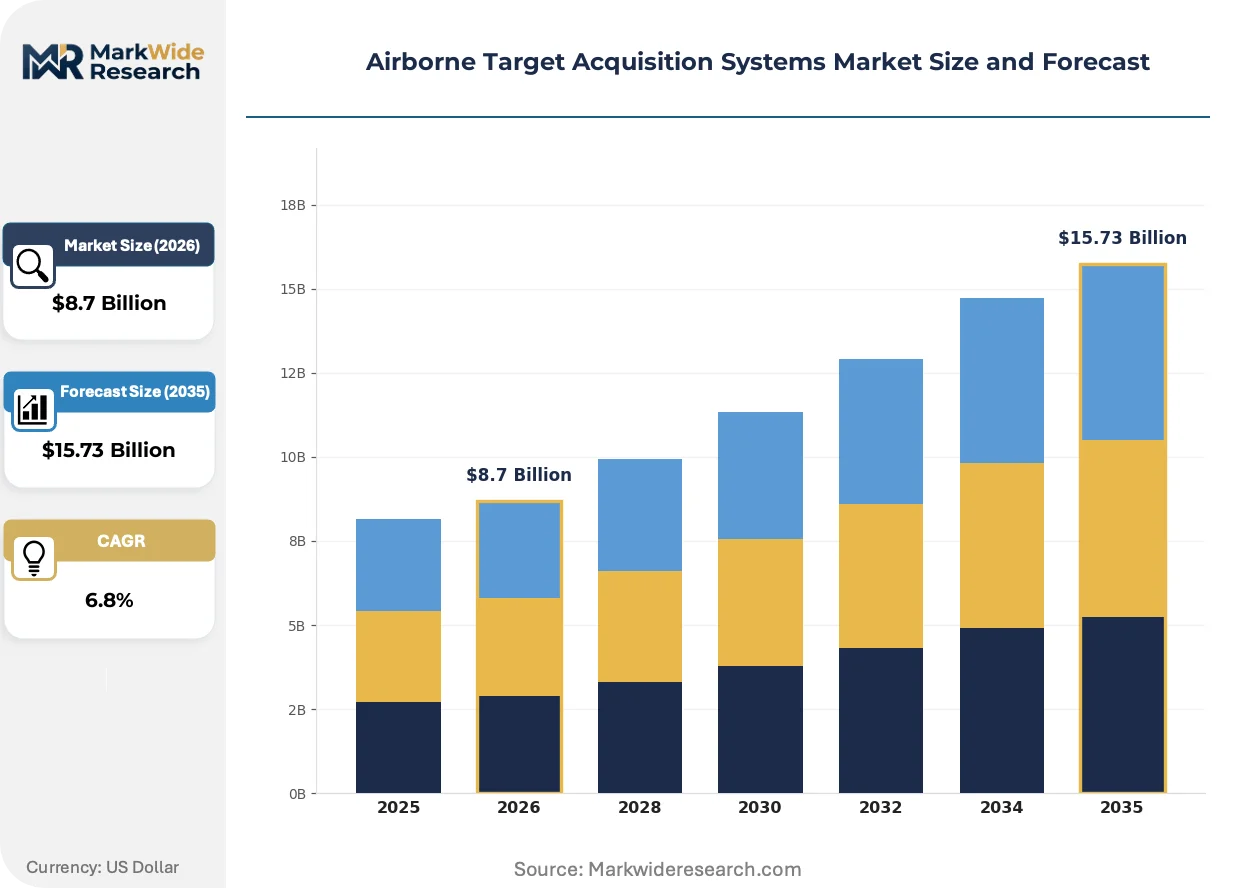
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Electro-Optical Systems, Infrared Systems, LIDAR Systems End User: Military, Defense Contractors, Law Enforcement, Civil Aviation Technology: Active Systems, Passive Systems, Hybrid Systems, Autonomous Systems Application: Surveillance, Targeting, Reconnaissance, Battle Management |
| Companies Covered | The Boeing Company, Thales Group, Raytheon Technologies Corporation, Airbus, General Dynamics Corporation, Lockheed Martin Corporation, BAE Systems plc, Hensoldt AG, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Target Acquisition Systems Market Emerging Trajectories
Algorithmic processing at the sensor edge is displacing centralized mission computer architectures, compressing kill-chain timelines while forcing hardware-software integration decisions earlier in platform development.
Multi-spectral sensor pods are expanding into unmanned combat air vehicle applications as attritable platform designers prioritize modular payload bays over fixed sensor apertures. Naval Air Systems Command programs are driving this adoption through MQ-25 and future collaborative combat aircraft specifications. The structural consequence is expanding into a two-tier supplier base where fixed-wing primes integrate pods from specialized electro-optical houses.
The EU AI Act's risk classification framework for autonomous weapons systems is mandating human-machine interface documentation that extends development timelines by 12-18 months for European suppliers. Industrial consequence includes forced architectural partitioning between target detection algorithms and firing authorization logic. Unmanned platforms with strike capability face the most severe compliance burden, pushing some development toward US or Israeli regulatory jurisdictions.
Defense ministries are consolidating multi-year platform sustainment into original equipment manufacturer contracts, displacing third-party depot maintenance for targeting pod overhaul. This behavior concentrates service revenue with Lockheed Martin and BAE Systems while reducing competition from independent repair stations. The United Kingdom and Australia demonstrate this pattern most clearly through their F-35 and Typhoon fleet management structures.
Airborne Target Acquisition Systems Market Segmentation
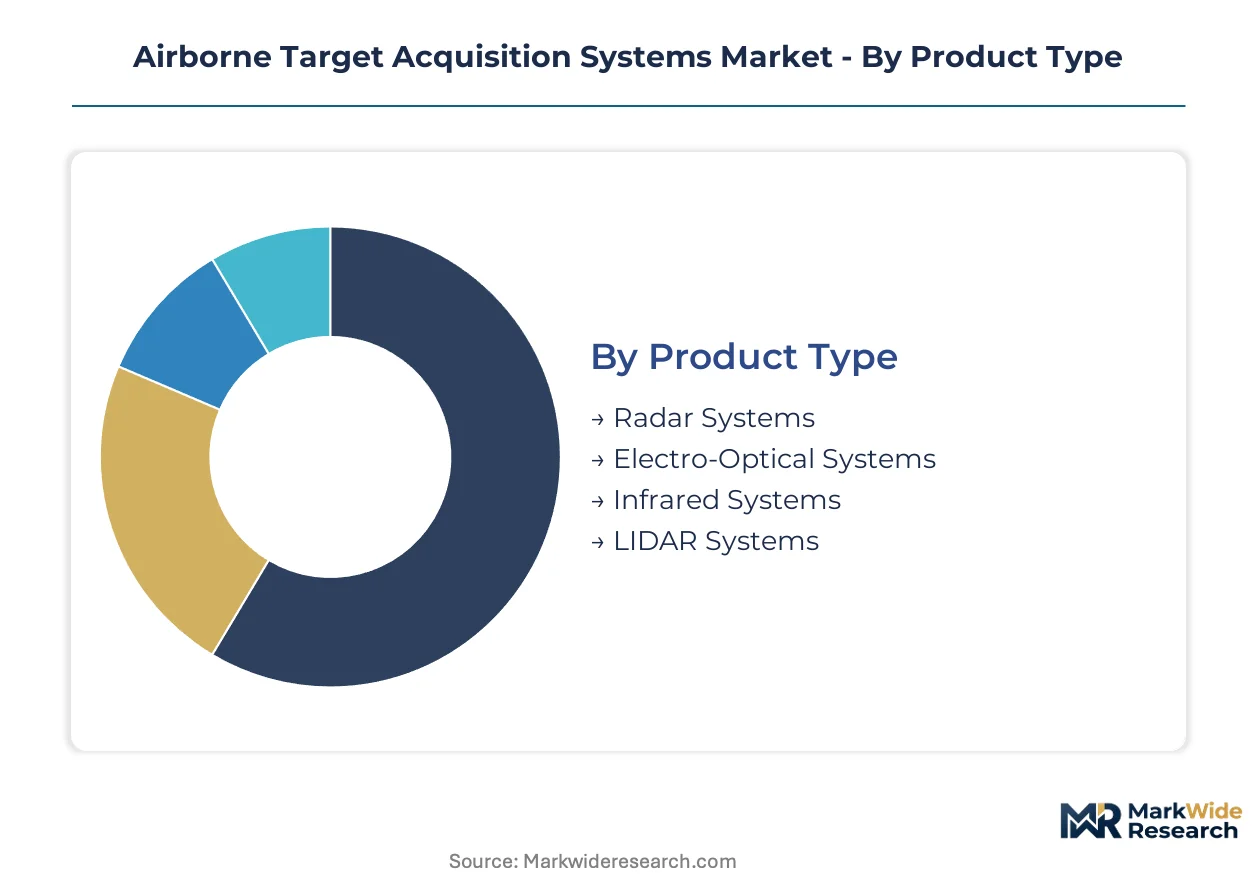
Segmentation in airborne target acquisition systems reveals how procurement priorities diverge across sensor modalities and operational contexts. Defense ministries structure acquisition around platform integration requirements, while technology choices reflect kill-chain compression demands and regulatory constraints on autonomous engagement.
Product Type:
Electro-optical systems anchor current procurement volumes through supply chain maturity, while autonomous sensor fusion platforms command premium pricing for unmanned combat applications.
- Radar Systems:Millimeter-wave and synthetic aperture radar configurations provide all-weather target detection through cloud cover and precipitation. Demand concentrates in US Navy carrier-based strike fighter programs requiring maritime surveillance capabilities, constrained by gallium arsenide substrate bottlenecks concentrated in East Asian foundries.
- Electro-Optical Systems:Stabilized gimbal-mounted visible-spectrum sensors with sub-50-microradian pointing accuracy dominate NATO airborne ISR fleet modernization. The United Kingdom and Australia prioritize these systems for F-35 and Typhoon integration, leveraging established focal plane array manufacturing bases for faster platform certification cycles.
- Infrared Systems:Short-wave and mid-wave infrared detectors enable thermal target discrimination for night operations.
- LIDAR Systems:Active laser ranging systems penetrate atmospheric obscurants where electro-optical sensors fail.
Today's leader: Electro-Optical Systems. Tomorrow's challenger: LIDAR Systems.
End User:
Military operators drive specification standards through JADC2 interoperability mandates, while defense contractors capture expanding foreign military sales bundling opportunities.
- Military:National air forces and naval aviation commands define performance requirements for integrated targeting architectures. The US Department of Defense's Joint All-Domain Command and Control initiative forces sensor standardization across air, sea, and ground assets, consolidating procurement authority with Pentagon acquisition offices.
- Defense Contractors:System integrators manage foreign military sales packaging and platform sustainment contracts. India's Tejas Mk2 and AMCA programs create partnership openings with Hindustan Aeronautics Limited under offset agreements, shifting revenue toward multi-year platform bundles.
- Law Enforcement:Border patrol and counter-narcotics aviation units require simplified targeting pods for manned surveillance platforms.
- Civil Aviation:FAA-regulated sensor carriage for infrastructure inspection and emergency response operates under restricted airspace protocols.
Military end users set technical specifications. Defense contractors capture service revenue expansion.
Technology:
Passive systems dominate current inventories through lower electromagnetic signature, while hybrid architectures gain share through multi-spectral fusion requirements.
- Active Systems:Radar and LIDAR emit energy to illuminate targets, enabling detection independent of ambient lighting conditions. US Air Force penetrating strike platforms prioritize these capabilities for contested airspace operations where passive sensors face jamming vulnerability.
- Passive Systems:Electro-optical and infrared sensors rely on ambient radiation or target emissions, preserving platform stealth. NATO airborne ISR programs favor these configurations for reduced probability of intercept, with stabilization accuracies below 50 microradians maintained through precision mechanical compensation.
- Hybrid Systems:Multi-sensor fusion architectures combine active and passive modalities for all-weather performance.
- Autonomous Systems:Algorithmic target recognition with edge processing capabilities face EU AI Act compliance burdens extending development timelines.
Passive Systems hold installed base dominance. Hybrid Systems climb the fastest on kill-chain compression demand.
Application:
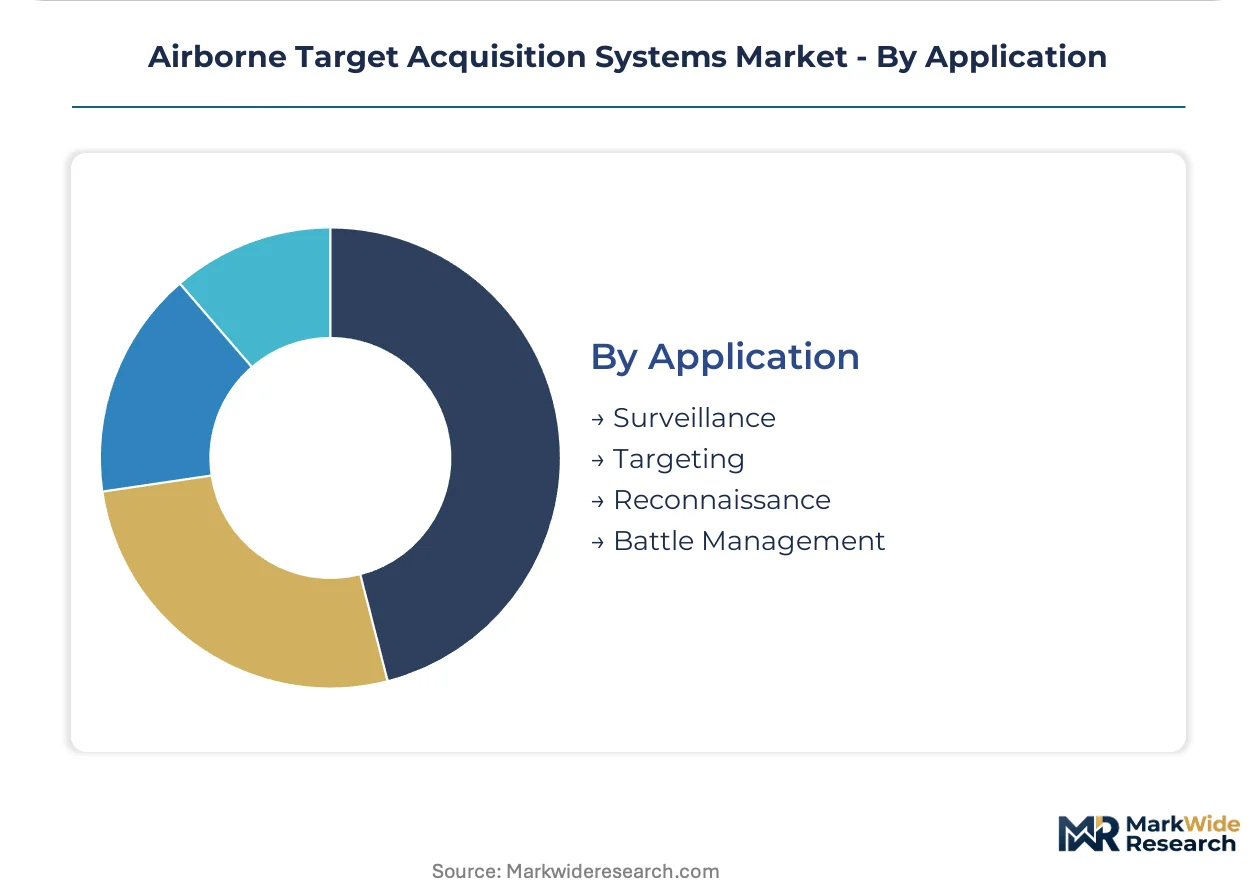
Surveillance applications generate volume through fleet-wide ISR modernization, while battle management systems capture premium positioning through JADC2 integration complexity.
- Surveillance:Wide-area persistent stare and moving target indication missions require stabilized sensor platforms with extended dwell times. US Southern Command counter-narcotics operations and European border monitoring programs drive recurring procurement for manned patrol aircraft configurations.
- Targeting:Precision designation for weapon engagement demands highest stabilization accuracy and laser rangefinder integration. Strike fighter programs in the United States, United Kingdom, and Australia consolidate these requirements through Lockheed Martin and BAE Systems platform contracts with embedded sustainment.
- Reconnaissance:Deep-penetration imagery collection prioritizes standoff range and spectral diversity.
- Battle Management:Real-time target data distribution across networked forces requires interoperable data link architectures.
Surveillance commands current procurement volume. Battle Management represents the steepest expansion trajectory on network-centric warfare mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains procurement volumes through Joint All-Domain Command and Control mandates, while Germany concentrates NATO interoperability investments in Typhoon fleet modernization. Demand patterns diverge sharply between these anchor markets.
United States
The Department of Defense drives multi-sensor fusion requirements through F-35 and collaborative combat aircraft programs. FAA regulations govern civil airspace integration of sensor-carrying platforms for infrastructure inspection missions. Lockheed Martin and Northrop Grumman anchor production clusters in Maryland and California, consolidating sustainment contracts for deployed targeting pod inventories.
Germany
The Luftwaffe prioritizes Eurofighter Typhoon targeting pod upgrades alongside Tornado replacement timelines. EU AI Act compliance burdens extend development cycles for autonomous target recognition systems by 12-18 months. Hensoldt AG anchors electro-optical manufacturing in Bavaria, partnering with Airbus Defence and Space on NATO interoperability packages.
United Kingdom
Royal Air Force F-35 and Typhoon fleet management structures concentrate multi-year sustainment with BAE Systems. The UK Ministry of Defence mandates sensor standardization across carrier strike and expeditionary air wing deployments. BAE Systems facilities in Lancashire and Bristol integrate targeting architectures for allied foreign military sales bundling.
India
Tejas Mk2 and AMCA indigenous fighter programs create partnership openings for foreign sensor houses under offset agreements. The Directorate General of Foreign Trade administers import licensing for gallium arsenide substrates and focal plane arrays. Hindustan Aeronautics Limited facilities in Bangalore and Hyderabad negotiate technology transfer arrangements for domestic production requirements.
Israel
Israeli Air Force operational experience with unmanned combat aircraft informs exportable targeting system architectures. The country's national defense export regulator coordinates Wassenaar Arrangement compliance for automatic target recognition software modules. Rafael Advanced Defense Systems and Elbit Systems anchor development clusters around Haifa and Beersheba, specializing in edge-processing targeting pods.
Airborne Target Acquisition Systems Market Vendor Landscape
United States producers anchor the prime contractor tier; European specialists hold subsystem and integration positions. The vendor base concentrates around five major defense conglomerates with sustained platform relationships, while tier-two electro-optical houses compete for pod manufacturing contracts. Three archetypes dominate: fixed-wing system integrators, specialized sensor developers, and unmanned platform specialists. Competitive moves center on multi-year sustainment bundling and foreign military sales packaging to allied air forces.
Within the fixed-wing integration tier, Lockheed Martin and BAE Systems exemplify prime contractor positioning through sustained investment in sensor fusion architectures. Raytheon Technologies Corporation occupies a position spanning both radar subsystem supply and platform integration. These three anchors demonstrate how defense ministries consolidate procurement authority with established suppliers capable of delivering bundled sensors, software, and multi-decade sustainment under single-contract structures.
| Leading Market Players |
|---|
| The Boeing Company |
| Thales Group |
| Raytheon Technologies Corporation |
| Airbus |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Hensoldt AG |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Multi-year platform bundling by US, UK, and Australian defense ministries is compressing unit economics for discrete sensor suppliers while elevating sustainment premiums for integrated system houses. This procurement consolidation forces tier-two electro-optical manufacturers to absorb certification cost spikes or exit NATO airborne ISR programs entirely.
Pricing Analysis
Capacity additions in Israel and the United States are reshaping price floors for edge-processing targeting pods. Three-tier pricing structure across fully-integrated, sensor-only, and maintenance-service levels reflects divergence in after-sales bundling intensity. Cost compression in sensor-only tiers is intensifying because Hindustan Aeronautics Limited demands offset-compliant local production. Foreign military sales channels show lowest price sensitivity; law enforcement border patrol units exhibit highest.
Supply Chain Analysis
Precision optomechanical engineering talent scarcity in Bavaria and Maryland constrains expansion timelines for stabilized gimbal production. Manufacturing concentrates in the United States, Germany, and Israel. Critical inputs draw from gallium arsenide substrates, short-wave infrared focal plane arrays, and precision-machined gyroscopic stabilizers. Single-source vulnerability in East Asian semiconductor foundries threatens millimeter-wave radar availability. Distribution runs through prime contractor platform integration contracts and foreign military sales congressional notification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU AI Act compliance burdens and US autonomous weapons governance creates cost differentials exceeding development timeline gaps. Suppliers can exploit this divergence by routing unmanned combat aircraft targeting system development through Israeli or American regulatory jurisdictions.
For Market Incumbents: Deploy multi-decade sustainment bundling to capture service revenue Lockheed Martin and BAE Systems currently dominate. Counter synthetic aperture radar substitution threat from commercial satellite imagery by integrating LIDAR-radar fusion capabilities into next-generation pods. Lock in gallium arsenide substrate supply through long-term offtake agreements with East Asian foundries before export control expansions tighten. For New Entrants and Emerging Players: Begin with India's Tejas Mk2 and AMCA offset partnership opportunities where Hindustan Aeronautics Limited actively seeks foreign sensor house collaboration. Target attritable unmanned combat air vehicle payload bay specifications Naval Air Systems Command is driving through MQ-25 programs. Pursue modular pod architectures that enable rapid reconfiguration between surveillance and targeting missions. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-two electro-optical houses possessing sub-50-microradian stabilization expertise but lacking platform integration relationships. Five-to-ten year viability hinges on successful foreign military sales packaging to allied F-35 and Typhoon operators. Watch for Wassenaar Arrangement automatic target recognition software control expansions as inflection signal for cross-border maintenance revenue disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Architecture Development | Compresses procurement cycles for US Department of Defense JADC2-compliant platforms. |
| Offset Partnership with Hindustan Aeronautics Limited | Unlocks India's Tejas Mk2 and AMCA indigenous fighter program revenue streams. |
| Gallium Arsenide Supply Security Investment | Mitigates single-source vulnerability in East Asian semiconductor foundries. |
| LIDAR-Radar Convergence Capability Integration | Addresses all-weather target designation gaps in electro-optical dominated inventories. |
| EU AI Act Compliance Architecture Partitioning | Enables European market participation without 12-18 month development timeline extensions. |
Methodological Framework
Coverage spans the United States, Germany, the United Kingdom, India, and Israel, with primary inputs from each defense procurement cluster. The research combines structured interviews with program executives at national defense ministries, platform integration leads at prime contractors, electro-optical subsystem engineering directors, foreign military sales licensing officers, and regulatory compliance specialists with secondary validation through Department of Defense budget justification documents, NATO Standardization Office technical standards, FAA certification databases, Wassenaar Arrangement control lists, and EU AI Act implementation guidance. Bottom-up segment sizing triangulates against top-down defense expenditure allocation analysis.
Rate-of-change decomposition separates volume drivers from value drivers across the projection horizon. The analytical framework models product type, end user, technology, and application dimensions alongside platform integration complexity tiers and regulatory jurisdiction clusters. CAGRs derive from segment-level growth trajectory synthesis. Forecast inputs include Joint All-Domain Command and Control deployment timelines, unmanned combat aircraft operational clearance progressions, and gallium arsenide substrate supply availability assessments.
Several conditions sit outside the modeled scope, including sudden export control regime changes, autonomous weapons governance framework revisions, and major platform program cancellations. Forecasts reflect stated procurement timelines and technology readiness assumptions. Material deviation in JADC2 funding authorization, EU AI Act enforcement intensity, or Indo-Pacific alliance structure warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Radar Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market