
 Military Radar Systems Market | 2026-2036
Military Radar Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Radar Systems Market Outlook
ISO 9001 and AS9100 certification cycles is unwinding the vendor base, forcing smaller suppliers to absorb multi-year audit costs or exit defense contracting. Lockheed Martin sustains its position through captive gallium nitride foundry capacity for active electronically scanned arrays. BAE Systems anchors European supply chains with sovereign sustainment networks across the UK and Sweden. Leonardo S.p.A. competes on dual-use radar architectures that bridge military and air-traffic-control specifications.
Military radar systems are electromagnetic detection and ranging equipment operating across L-band through W-band frequencies, generating target position, velocity, and identification data for weapon systems and command networks. Phased array technology dominates procurement budgets due to its beam-steering agility and multi-target tracking capacity, while synthetic aperture radar commands premium pricing for all-weather reconnaissance missions. Airborne deployment configurations absorb the largest share of R&D investment, though naval surface-search variants are gaining traction amid fleet modernization programs.
The U.S. Department of Defense, NATO's NIAG framework, and the EU's European Defence Fund collectively shape procurement interoperability standards and cross-border technology transfer rules. Software-defined radar architectures now face export control reclassifications under ITAR and EAR dual-use regulations, complicating supplier market access. Stakeholders must weigh sovereign capability investments against coalition interoperability mandates as procurement pools fragment along geopolitical alignment lines.
Market Dynamics
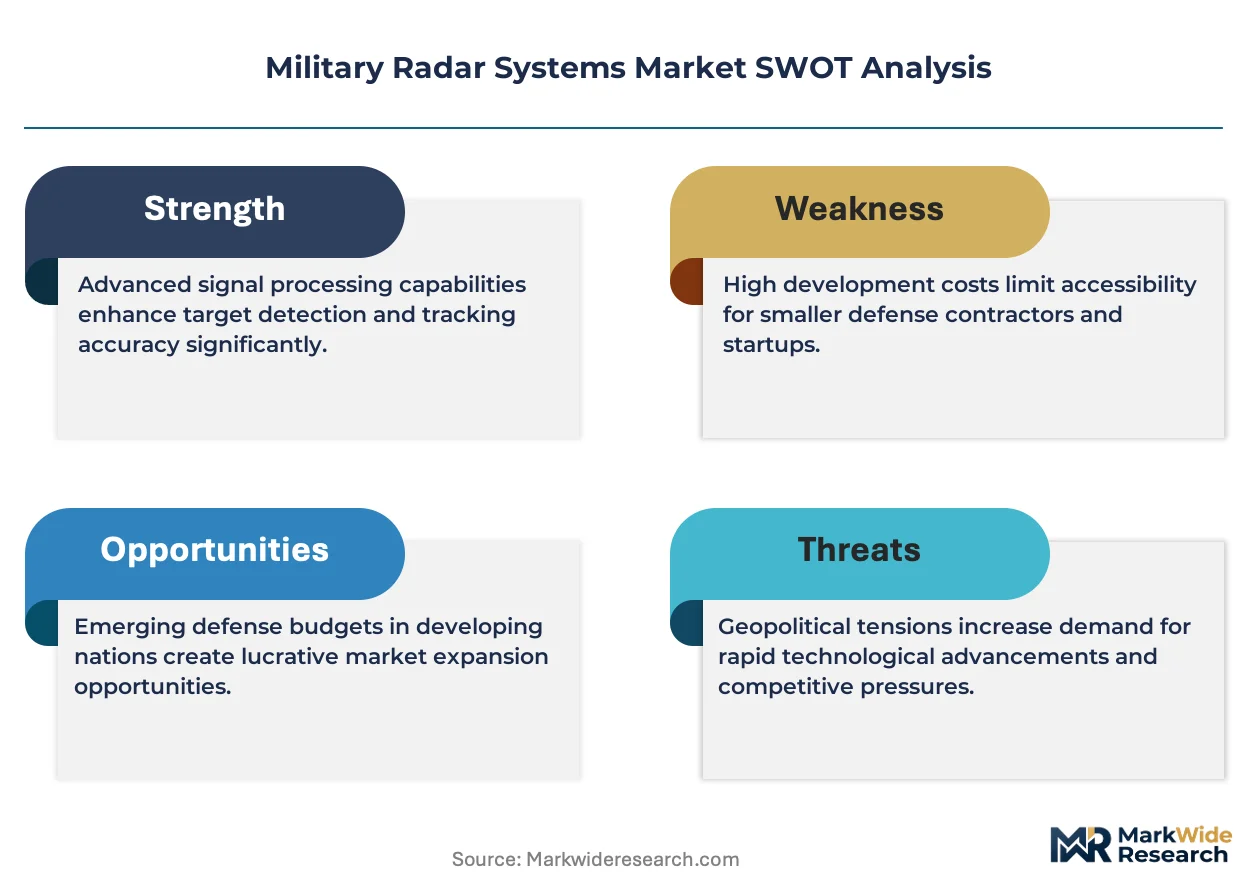
Gallium nitride foundry capacity concentration is squeezing the supplier base, as captive vertical integration at prime contractors locks out independent chip vendors from active electronically scanned array programs.
Growth Catalysts
- NATO NIAG framework:The alliance's standardization mandates accelerate cross-border procurement interoperability, forcing member air forces toward common radar architectures.
- Indo-Pacific maritime corridors:Contested waters around the South China Sea and Taiwan Strait drive naval surface-search radar modernization across regional fleets.
- Software-defined architectures:Programmable waveform generation enables rapid threat-signature updates without hardware replacement, extending platform operational relevance.
Market Restraints
- Rare earth magnet supply:Neodymium and samarium processing concentration in China's Ganzhou cluster creates chokepoint vulnerability for traveling wave tube subassemblies.
- ITAR/EAR reclassification:Dual-use software-defined radar export controls fragment supplier market access along geopolitical alignment lines.
- Thermal management limitations:Power-density ceilings in compact airborne radomes constrain transmit-receive module packing density for fighter platforms.
Strategic Opportunities
- Space-based radar constellations:Low-earth orbit synthetic aperture platforms offer persistent maritime surveillance beyond aircraft endurance limits.
- EU European Defence Fund:Cross-border R&D pooling reduces sovereign duplication in next-generation multimode radar development.
- Dual-use air-traffic integration:Military-primary radars with civilian secondary surveillance capability capture defense-civilian budget convergence.
Industry Challenges
- GaN process engineering talent:Compound semiconductor fabrication expertise resides at a handful of defense-cleared facilities, constraining workforce scaling.
- AS9100D certification timelines:Multi-year audit cycles exhaust smaller suppliers before contract award, accelerating vendor base consolidation.
- Legacy analog integration:Phased array retrofits onto 1980s airframes require waveform compatibility layers that degrade electronic protection performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Radar Systems Market |
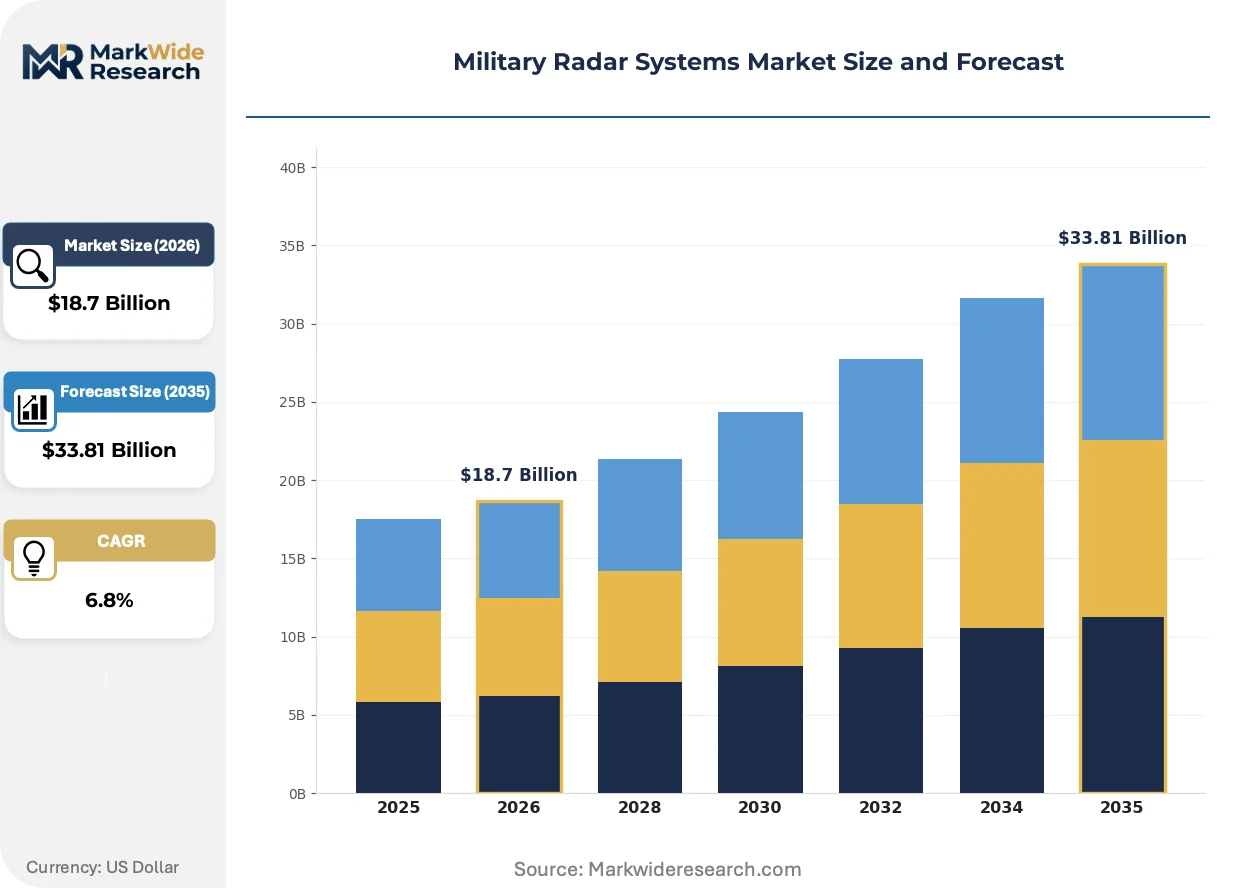
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Early Warning, Surveillance, Targeting, Fire Control Technology: Phased Array, Synthetic Aperture, Doppler, Foliage Penetration End User: Army, Navy, Air Force, Defense Contractors Deployment: Land-based, Airborne, Naval, Space-based |
| Companies Covered | Thales Group, Leonardo S.p.A., RTX Corporation, Israel Aerospace Industries, L3Harris Technologies, Inc., Lockheed Martin Corporation, BAE Systems plc, Hensoldt AG, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Radar Systems Market Strategic Shifts
Digital beamforming and open-architecture standards are dissolving traditional hardware-software boundaries, enabling rapid capability insertion through firmware rather than platform replacement.
GaN-on-diamond substrates are miniaturizing transmit-receive module thermal footprints while sustaining peak power output. Naval aviation programs are adopting these compact arrays for unmanned carrier-based platforms where radome volume is severely constrained. The technology is miniaturizing previously ground-based surveillance capabilities into tactical unmanned payloads.
REACH substance restrictions on hexavalent chromium coatings are forcing antenna manufacturer migrations to trivalent alternatives and ceramic conversion coatings. Surface-finish suppliers in Germany and Sweden are qualifying new processes under shortened defense exemption timelines. Naval radome manufacturers face the tightest compliance windows due to salt-spray performance requirements.
Performance-based logistics contracts are displacing traditional spares-and-repair arrangements for deployed radar systems. Maintenance responsibility is consolidating at original equipment manufacturers who guarantee availability metrics rather than part deliveries. The UK and Australian air forces have pioneered these arrangements for airborne early warning fleets, with payment tied to operational radar hours rather than component shipments.
Military Radar Systems Market Segmentation
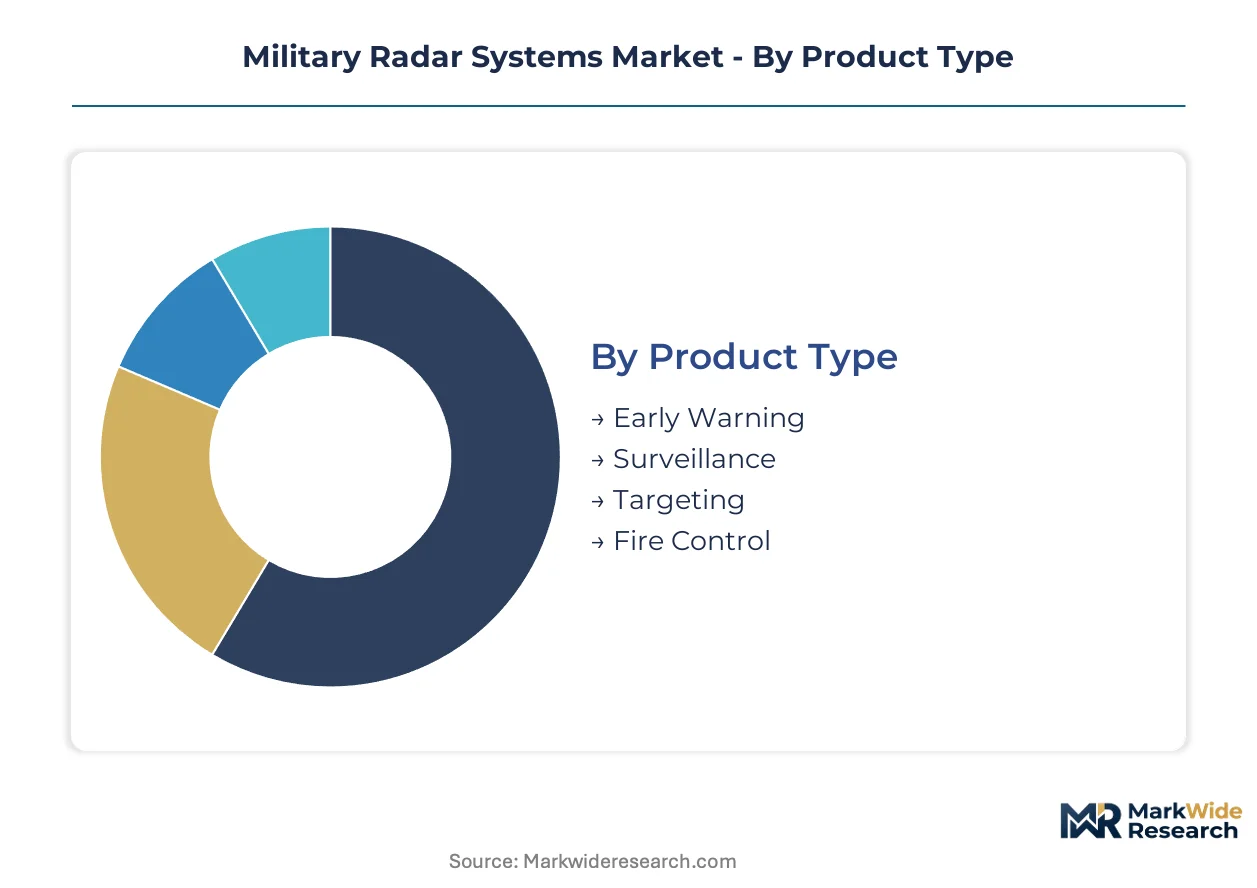
Military radar procurement fragments across mission requirements, platform constraints, and sovereign classification protocols. Each segment carries distinct ITAR/EAR exposure levels and foundry access thresholds that reshape vendor qualification pathways.
Product Type:
EAR and ITAR classifications diverge sharply by mission criticality, with fire control architectures facing the tightest dual-use scrutiny.
- Early Warning:Long-range detection arrays operating across L-band frequencies for ballistic missile and aircraft approach alerts. NATO's Integrated Air and Missile Defense system drives demand concentration across Poland, Romania, and Turkey as forward-based radar hosts.
- Surveillance:Synthetic aperture and moving target indication systems generating terrain mapping and traffic monitoring data. Indo-Pacific maritime patrol aircraft programs absorb the largest procurement volumes amid South China Sea monitoring requirements.
- Targeting:Compact multi-mode radars for precision strike coordination.
- Fire Control:High-update-rate tracking for weapon guidance with stringent latency specifications.
Surveillance handles the majority of throughput; fire control is expanding most quickly on share as precision strike platforms multiply.
Technology:
Cost tiers separate legacy tube-based systems from solid-state active arrays, with foundry economics determining accessible performance bands.
- Phased Array:Electronically steered beam architectures using gallium nitride transmit-receive modules. Captive vertical integration at prime contractors locks out independent chip vendors, consolidating procurement around cleared domestic sources.
- Synthetic Aperture:Coherent processing of radar returns to generate high-resolution imagery regardless of weather or illumination. Naval aviation and unmanned platforms drive adoption as endurance requirements exceed human crew limits.
- Doppler:Velocity measurement through frequency shift analysis for moving target discrimination.
- Foliage Penetration:Ultra-wideband or low-frequency systems for concealed target detection in dense terrain.
Phased array captures the dominant procurement value; synthetic aperture climbs the fastest as unmanned platform endurance requirements harden.
End User:
Customer type dictates security clearance thresholds and maintenance infrastructure depth, with uniformed services retaining sovereign capability while contractors absorb integration risk.
- Air Force:Airborne early warning, fighter fire control, and ground-based air defense radar portfolios. U.S. Air Force Next Generation Air Dominance program and NATO airborne warning fleet recapitalization concentrate demand.
- Navy:Surface-search, air-search, and fire control radars for fleet defense. Indo-Pacific carrier strike groups and Aegis destroyer modernization programs in Japan and Australia anchor procurement.
- Army:Counter-battery, air defense, and battlefield surveillance systems.
- Defense Contractors:Integration and sustainment responsibility for platform-embedded radar subsystems.
Air Force manages the largest procurement envelope; Navy is gaining share fastest amid fleet modernization acceleration.
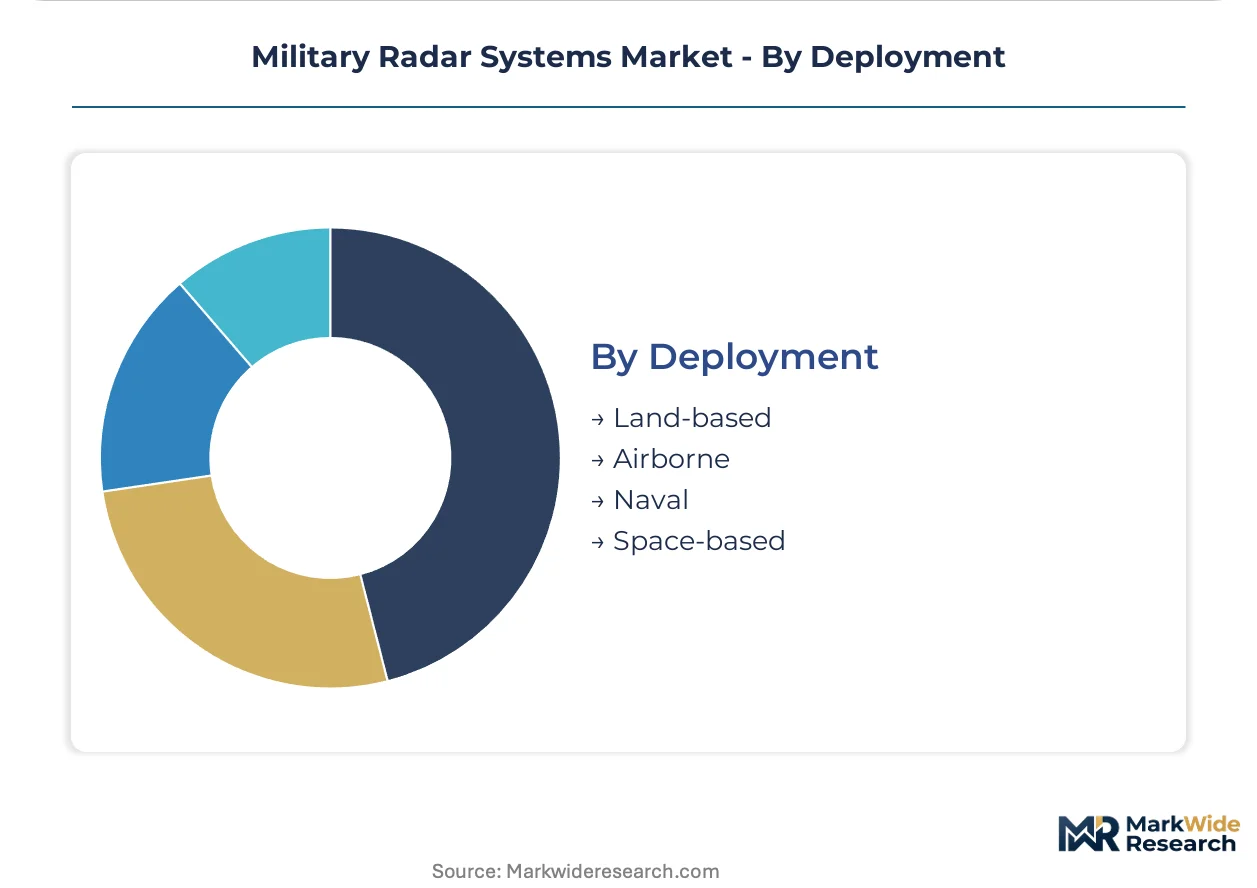
Deployment:
Platform environment determines thermal, power, and aperture constraints, with airborne and naval variants commanding premium pricing over fixed-site installations.
- Airborne:Fighter, patrol aircraft, and unmanned platform radars operating within severe volume and cooling limitations. GaN-on-diamond substrates are miniaturizing previously ground-based capabilities into tactical payloads.
- Naval:Shipboard multi-function arrays integrating air defense, surface search, and fire control. Salt-spray environmental requirements and REACH hexavalent chromium restrictions compress qualification timelines for European manufacturers.
- Land-based:Fixed and mobile ground installations for air defense and early warning.
- Space-based:Low-earth orbit synthetic aperture constellations for persistent maritime surveillance beyond aircraft endurance limits.
Airborne deployment absorbs the dominant R&D investment; space-based platforms are advancing most rapidly on capability insertion timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives are redirecting radar modernization budgets toward contested maritime theaters and forward-based NATO infrastructure. Sovereign capability mandates and coalition interoperability requirements are creating divergent qualification pathways across national supplier bases.
United States
Next Generation Air Dominance program and airborne warning fleet recapitalization absorb the dominant procurement volume. The Department of Defense's software modernization mandates reshape supplier qualification requirements through ITAR-controlled pathways. GaN foundry capacity concentrates in cleared defense facilities across Arizona and Texas, locking independent chip vendors out of active electronically scanned array programs.
United Kingdom
Sovereign sustainment networks anchor European supply chains through UK-based radar integration hubs. BAE Systems plc maintains captive gallium nitride processing relationships while qualifying alternative substrate suppliers under REACH hexavalent chromium restrictions. Performance-based logistics contracts pioneered with Australian air forces are migrating to domestic airborne early warning fleets.
Japan
Indo-Pacific carrier strike group modernization and Aegis destroyer programs drive naval surface-search radar procurement. METI coordinates dual-use technology transfers while maintaining export control alignment with US ITAR frameworks. Industrial concentration in Nagoya and Yokohama supports phased array fabrication for indigenous fighter platforms.
Australia
Maritime patrol aircraft programs absorb synthetic aperture radar volumes amid South China Sea monitoring requirements. The Department of Defence mandates sovereign industrial capability participation in AUKUS-aligned procurement. Brisbane and Adelaide host integration facilities for US-sourced fire control architectures with local thermal management adaptations.
Germany
Counter-battery and battlefield surveillance systems modernize under NATO NIAG framework standardization mandates. Hensoldt AG anchors Central European radar supply chains through AS9100D-certified facilities in Bavaria and Baden-Württemberg. REACH substance restrictions on hexavalent chromium coatings compress qualification timelines for naval radome manufacturers.
Military Radar Systems Market Competitive Environment
Player mix skews toward vertically integrated primes with captive semiconductor foundry capacity. The supplier base consolidates around cleared defense contractors possessing sovereign sustainment networks and dual-use certification pathways. Three archetypes dominate: gallium nitride foundry owners, software-defined architecture specialists, and sovereign sustainment network operators. Competitive moves center on backward integration into compound semiconductor fabrication and strategic partnerships for space-based radar constellations.
Within the captive-foundry tier, Lockheed Martin Corporation and RTX Corporation exemplify vertical control over active electronically scanned array supply chains. Leonardo S.p.A. occupies a bridging position between military and air-traffic-control specifications, while BAE Systems plc anchors European sovereign capability through UK and Swedish sustainment networks. Thales Group and L3Harris Technologies, Inc. sit within the software-defined architecture specialist tier, competing on programmable waveform generation for rapid threat-signature updates.
| Leading Market Players |
|---|
| Thales Group |
| Leonardo S.p.A. |
| RTX Corporation |
| Israel Aerospace Industries |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Hensoldt AG |
| Northrop Grumman Corporation |
| Others |
Value Chain & Pricing Dynamics
Performance-based logistics contracts lock in multi-year supply access for prime contractors while capping price visibility for downstream buyers through availability-metric payment structures rather than component-based costing. The Department of Defense's software modernization mandates and ITAR-controlled pathways compress supplier qualification timelines, forcing buyers to absorb audit costs or accept sole-source premiums.
Pricing Analysis
Certification level (AS9100D/ISO 9001 with defense clearance) creates the primary spread between cleared domestic primes and uncertified challengers. Three-tier pricing structure across ITAR-restricted, NATO-interoperable, and dual-use commercial tiers reflects compliance burden differentials. Pricing pressure stems from gallium nitride foundry capacity concentration at captive vertical integrators. Defense contractors with sovereign sustainment networks exhibit lowest price sensitivity; smaller integration shops face acute cost compression.
Supply Chain Analysis
Strategic stockpiling of rare earth magnets and compound semiconductor substrates dominates inventory strategy over just-in-time approaches given China's Ganzhou cluster chokepoint and single-source GaN fabrication. Supply concentrates in the United States, United Kingdom, and Japan for cleared defense-grade active electronically scanned arrays. Raw material dependencies center on neodymium, samarium, and high-purity gallium nitride wafers. Tariff exposure on Chinese-processed rare earths creates structural vulnerability. Distribution runs through prime contractor integration facilities with direct military program office relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN process engineering talent resides at a handful of defense-cleared facilities, constraining workforce scaling and creating acquisition premiums for compound semiconductor expertise. This scarcity dynamic favors incumbents with captive foundry investments while raising barriers for challengers lacking backward integration.
For Market Incumbents: Compound sovereign sustainment network depth with software-defined architecture roadmaps to defend against space-based radar constellation entrants. Lockheed Martin's captive gallium nitride foundry capacity and BAE Systems' UK-Sweden sustainment hubs exemplify defensible positioning. Prioritize thermal management R&D for unmanned platform radome constraints. For New Entrants and Emerging Players: Anchor in dual-use air-traffic integration segments where civilian certification requirements are lighter than pure military ITAR pathways. Leonardo S.p.A.'s bridging architecture between military and air-traffic-control specifications demonstrates viable positioning. Target European Defence Fund cross-border R&D pooling for sovereign capability participation without full prime contractor scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among performance-based logistics contract holders with airborne early warning fleet relationships. Long-term viability hinges on software-defined radar export control reclassification risk rather than hardware replacement cycles. Monitor ITAR/EAR dual-use regulation harmonization as the primary inflection signal for supplier market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Nitride Foundry Investment | Lockheed Martin's Arizona-Texas facilities lock out independent chip vendors from AESA programs. |
| Software-Defined Architecture Development | Thales Group and L3Harris compete on programmable waveform generation for rapid threat updates. |
| Sovereign Sustainment Network Expansion | BAE Systems' UK and Swedish hubs anchor European supply chains against fragmentation. |
| Space-Based Radar Constellation Partnership | Low-earth orbit synthetic aperture platforms bypass aircraft endurance limits for maritime surveillance. |
| Dual-Use Civilian-Military Certification | Leonardo S.p.A. bridges military and air-traffic-control specifications for budget convergence capture. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radar program managers at NATO air forces, GaN foundry engineering directors, defense procurement officers, and sustainment network operators. Secondary validation drew from Department of Defense budget justifications, NATO NIAG framework documentation, EU European Defence Fund award registers, and ITAR/EAR regulatory filings. Bottom-up platform deployment forecasts were triangulated against top-down national defense budget allocations across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment platform, technology architecture, mission type, and end-user service branch. CAGRs were derived from deployment pipeline visibility and sovereign capability investment trajectories. Forecast inputs incorporated gallium nitride foundry capacity expansion timelines and REACH substance restriction compliance cost curves.
Material uncertainties — gallium nitride process engineering talent migration, ITAR reclassification rulings, and rare earth magnet supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding NATO interoperability mandate continuity and Indo-Pacific fleet modernization acceleration. Revision becomes warranted when sovereign capability investment thresholds cross coalition interoperability commitment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Mmwave Radar Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Electronically Scanned Array Radar Market