
 Global Military Laser Rangefinder Market | 2026-2036
Global Military Laser Rangefinder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Laser Rangefinder Market Foresight
The EU AI Act is decoupling legacy rangefinder architectures from next-generation targeting networks by mandating algorithmic transparency in autonomous fire-control systems. Thales Group leverages its European defense electronics footprint to sustain integrated optronic solutions across Franco-German combat vehicle programs. L3Harris Technologies, Inc. anchors US special operations demand with compact handheld designs optimized for dismounted soldier systems. Lockheed Martin Corporation dominates airborne laser targeting pods through captive integration with F-35 sensor suites.
A military laser rangefinder is a pulsed or continuous-wave electro-optical instrument that measures distance to targets by calculating time-of-flight or phase-shift of emitted laser energy, typically operating at eye-safe wavelengths around 1.54 micrometers for battlefield safety compliance. These devices enable precision target engagement, ballistic computation, and sensor-to-shooter data links across ground, air, and maritime combat platforms. Handheld systems occupy the largest procurement volume among product types due to infantry squad saturation requirements, while airborne configurations command premium pricing through integration with stabilized turrets and multi-spectral targeting pods. Pulse technology leads technology segmentation for long-range artillery applications, whereas phase shift methods gain traction in naval fire control where continuous tracking supersedes single-pulse measurement.
The US Department of Defense, NATO Standardization Office, and South Korea's DAPA enforce divergent spectral safety and interoperability protocols that fragment component sourcing and test certification pathways. ESA and ISO 14255-derived standards govern European space-qualified rangefinder derivatives, creating dual-use compliance overhead for cross-Atlantic suppliers. Stakeholders must monitor evolving ITAR export control thresholds and emerging electromagnetic spectrum allocation disputes that threaten 1.5-micron transmitter supply chains.
Market Dynamics
Sensor fusion mandates from the US Department of Defense and NATO Standardization Office are compressing standalone rangefinder procurement cycles while elevating integrated targeting pod specifications across armored vehicle modernization programs.
Growth Catalysts
- Precision strike doctrine:The US DoD's emphasis on long-range target acquisition is accelerating sensor-to-shooter data link integration across ground and airborne platforms.
- Armored vehicle modernization:NATO member states are expanding procurement of vehicle-mounted systems for fleet upgrades, with Germany and South Korea prioritizing optronic suite replacements.
- Eye-safe wavelength standardization:The 1.54-micron transmitter specification is automating battlefield safety compliance across handheld and vehicle-mounted product categories.
Market Restraints
- ITAR export control thresholds:US International Traffic in Arms Regulations fragment component sourcing for cross-Atlantic suppliers, creating dual certification overhead.
- Transmitter supply concentration:1.5-micron laser diode manufacturing concentrates in East Asian foundries, exposing procurement to electromagnetic spectrum allocation disputes.
- Algorithmic transparency mandates:The EU AI Act decouples legacy rangefinder architectures from autonomous fire-control networks, forcing architecture redesigns.
Strategic Opportunities
- Naval fire control modernization:Phase-shift rangefinder technology gains traction in continuous-tracking naval applications where single-pulse measurement proves insufficient.
- Space-qualified derivatives:ESA and ISO 14255-derived standards create dual-use compliance pathways for European suppliers targeting satellite-based targeting systems.
- Dismounted soldier saturation:Infantry squad handheld system requirements in South Korea and NATO states represent underpenetrated volume expansion potential.
Industry Challenges
- Interoperability protocol fragmentation:Divergent spectral safety standards between the US DoD, NATO Standardization Office, and South Korea's DAPA force redundant test certification pathways.
- Legacy system integration complexity:Captive F-35 sensor suite architectures and proprietary vehicle bus standards complicate third-party rangefinder retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Laser Rangefinder Market |
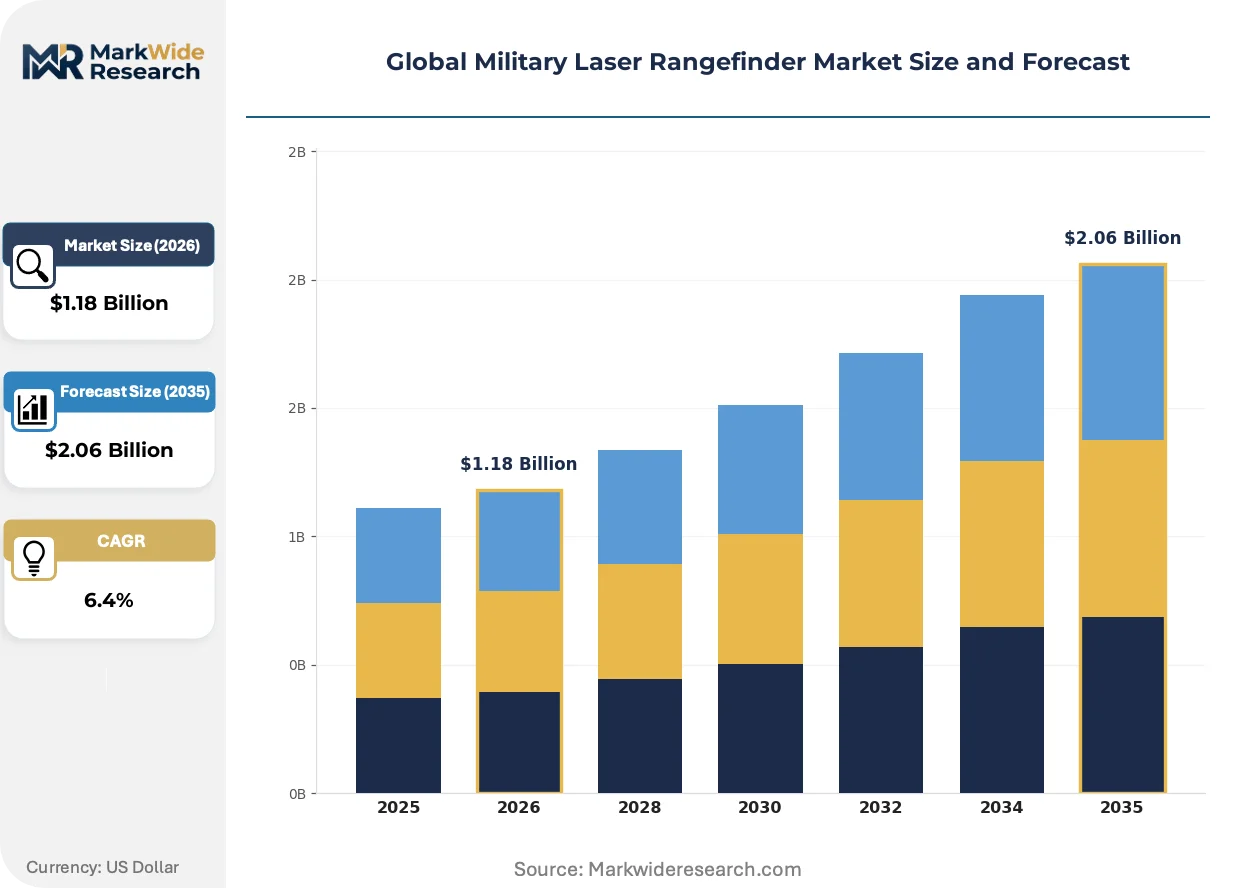
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Vehicle-Mounted, Airborne, Naval Technology: Pulse, Continuous Wave, Frequency Modulated, Phase Shift Application: Target Acquisition, Navigation Support, Surveillance, Artillery Fire Control End User: Ground Forces, Air Forces, Naval Forces, Defense Contractors |
| Companies Covered | Thales Group, L3Harris Technologies, Inc., Lockheed Martin Corporation, BAE Systems plc, RTX Corporation, Northrop Grumman Corporation, Leonardo S.p.A., Saab AB, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Laser Rangefinder Market Shifts & Advancements
Pulse-compression algorithms and solid-state transmitter advances are compressing range-gate timing precision while eye-safe wavelength standardization redefines battlefield safety compliance across procurement specifications.
Monoblock erbium-doped glass lasers are automating range-gate synchronization for artillery spotting applications. Ground-based fire direction centers in NATO member states are adopting these transmitters for counter-battery radar correlation. The technology is automating target handoff latency reduction between forward observers and strike assets.
REACH and RoHS substance restrictions are forcing lead-selenide detector material substitutions in European defense electronics supply chains. Component suppliers must reformulate infrared receiver architectures to maintain detectivity specifications. Airborne targeting pod manufacturers face the steepest reformulation timelines given captive integration with stabilized turret systems.
Long-term performance-based logistics contracts are displacing transactional spare part purchasing for vehicle-mounted rangefinder fleets. NATO maintenance depots in Germany and Poland are consolidating sensor suite overhaul responsibility with prime contractors. South Korea's DAPA is piloting similar consolidated support models for KF-21 fighter targeting pod programs.
Global Military Laser Rangefinder Market Segmentation
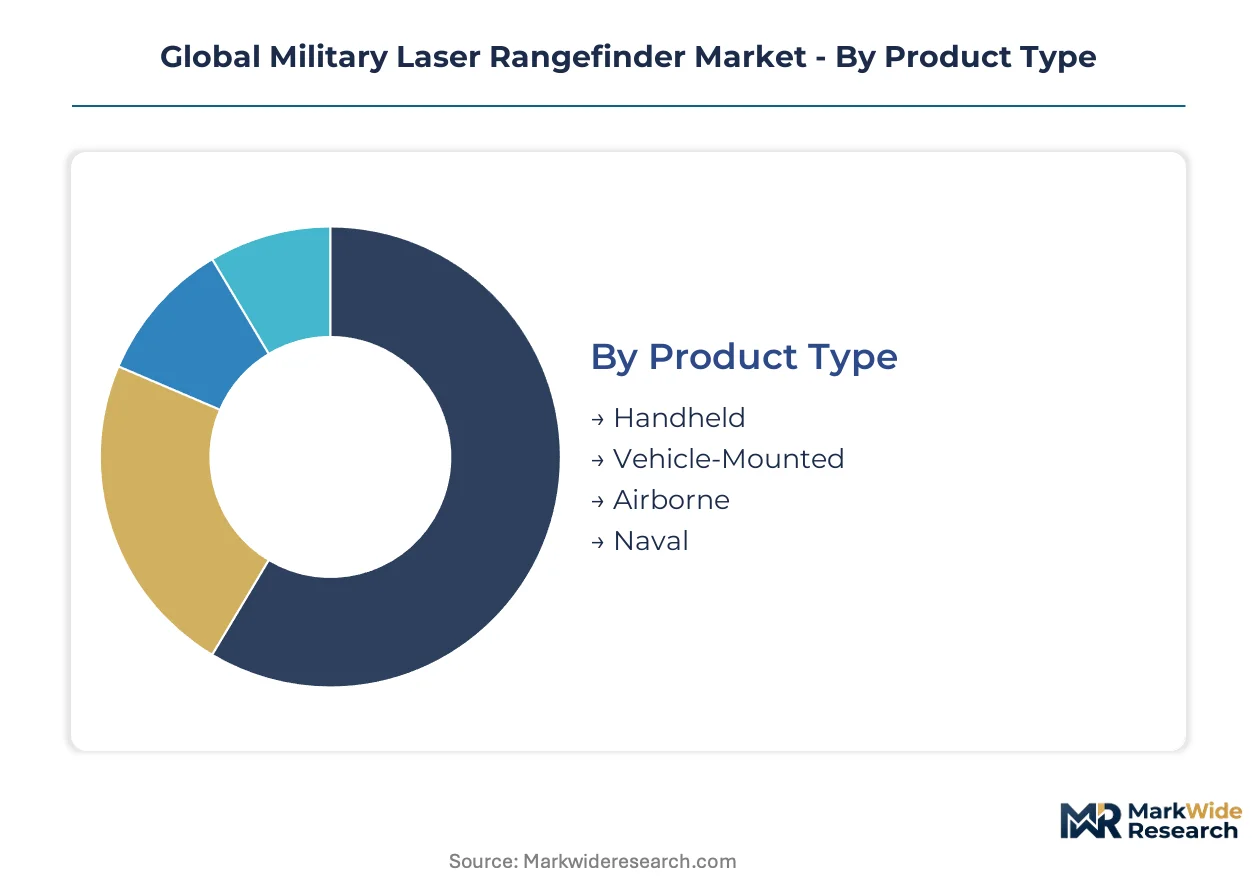
Military laser rangefinder procurement splits across platform integration levels, with handheld systems saturating infantry formations while vehicle-mounted and airborne configurations command premium pricing through multi-sensor fusion requirements. Technology choices between pulse and phase-shift methods determine range-gate precision versus continuous-tracking suitability across artillery, naval, and aerial fire-control applications.
Product Type:
Standardization dominates handheld and vehicle-mounted categories through NATO interoperability mandates, while airborne and naval systems require extensive customization for platform-specific stabilization and environmental sealing.
- Handheld:Compact diode-pumped designs operating at 1.54-micron eye-safe wavelengths equip dismounted infantry squads across South Korea and NATO states. Procurement concentrates in special operations and forward observer roles where sensor-to-shooter latency reduction drives volume saturation requirements.
- Vehicle-Mounted:Stabilized turret-integrated systems with automatic target tracking interface with armored vehicle battle management networks. Germany and South Korea prioritize optronic suite replacements in main battle tank modernization programs, compressing standalone rangefinder procurement cycles.
- Airborne:Multi-spectral targeting pod configurations demand captive integration with fighter sensor suites.
- Naval:Maritime fire control applications require enhanced environmental sealing against salt spray and vibration.
Most installed capacity flows through Handheld systems. Expansion is steepest in Vehicle-Mounted configurations.
Technology:
Cost tiers separate mature pulse architectures from emerging phase-shift and frequency-modulated approaches, with continuous-wave methods occupying a narrow middle band in naval tracking applications.
- Pulse:Time-of-flight measurement using Q-switched solid-state lasers dominates long-range artillery spotting and ground-based target acquisition. NATO counter-battery radar correlation requirements in Germany and Poland automate range-gate synchronization for forward observer-strike asset handoff.
- Phase Shift:Continuous-tracking interferometric methods measure target displacement through phase comparison of split laser beams. Naval fire control modernization in European and Indo-Pacific fleets gains traction where single-pulse measurement proves insufficient for moving maritime targets.
- Continuous Wave:Doppler-based velocity measurement supports limited tracking applications.
- Frequency Modulated:Chirped waveform compression enables simultaneous range and velocity resolution.
Pulse technology retains the largest installed base. Phase Shift methods are climbing the fastest through naval modernization budgets.
Application:
Customer type differentiation separates volume-driven navigation support from high-margin targeting pod integration, with surveillance and artillery fire control occupying intermediate positions on specification complexity.
- Target Acquisition:Integrated multi-sensor pods combining laser ranging with thermal imaging and GPS correlation equip precision strike platforms. The US Department of Defense's sensor fusion mandates elevate specifications for airborne and vehicle-mounted configurations across F-35 and armored vehicle programs.
- Artillery Fire Control:Automated ballistic computation links require sub-meter range precision for mortar and howitzer direction. NATO ground-based fire direction centers adopt monoblock erbium-doped glass transmitters for counter-battery correlation.
- Navigation Support:Terrain-referenced positioning aids dismounted operations in GPS-denied environments.
- Surveillance:Perimeter and border monitoring applications utilize tripod-mounted or fixed-site installations.
Navigation Support represents the largest volume application. Target Acquisition shows the steepest specification escalation trajectory.
End User:
Supply concentration aligns with defense procurement centralization, with ground forces fragmenting across national infantry programs while air forces consolidate through prime contractor captive integration.
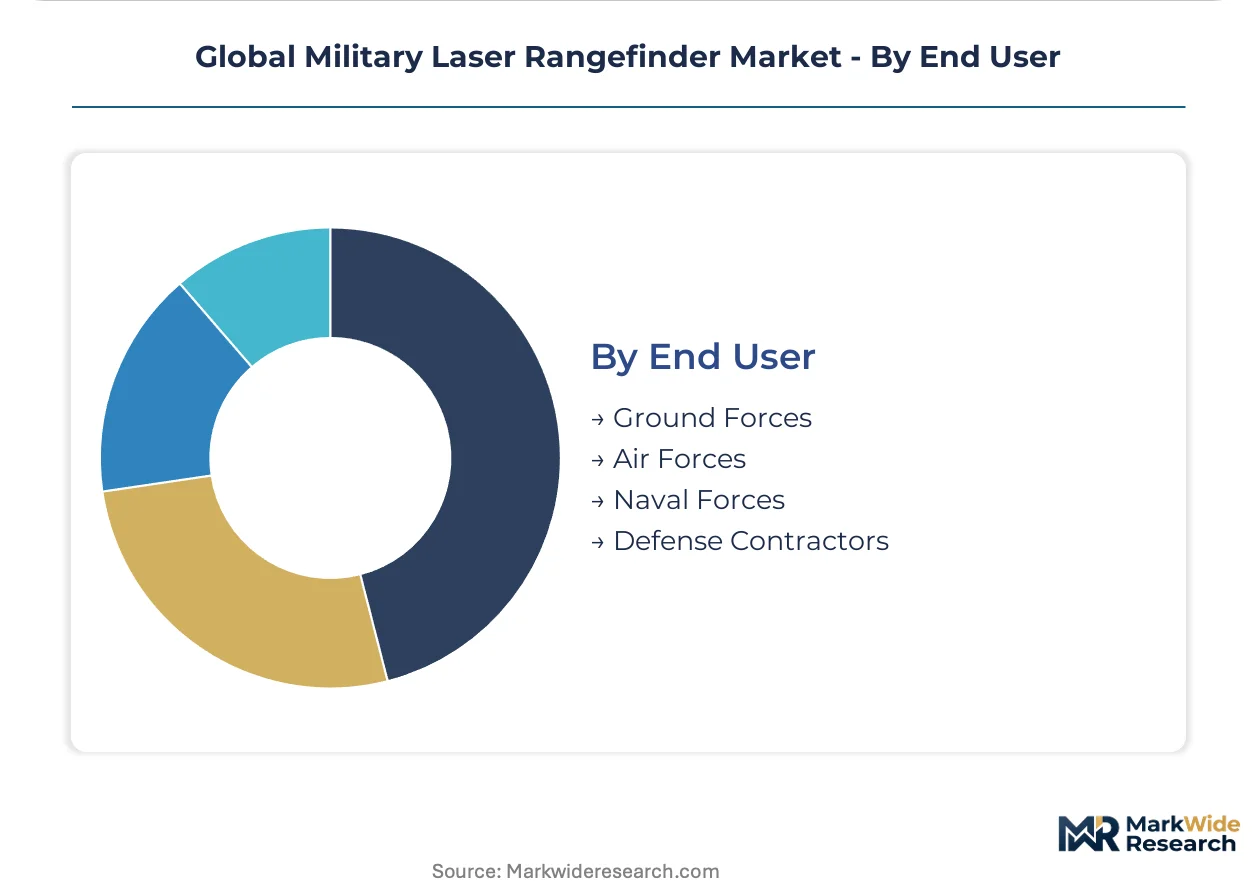
- Ground Forces:Infantry squad saturation requirements and armored vehicle modernization drive procurement across NATO and South Korea. The US Army's emphasis on dismounted soldier systems sustains demand for compact handheld designs optimized for special operations.
- Defense Contractors:Prime integration responsibility for vehicle-mounted and airborne sensor suites concentrates procurement with Thales Group and L3Harris Technologies. Performance-based logistics contracts displace transactional spare part purchasing for fleet overhaul.
- Air Forces:Fighter targeting pod programs require captive integration with stabilized turret systems.
- Naval Forces:Surface combatant fire control modernization lags ground and air procurement cycles.
Ground Forces absorb the largest procurement volume. Defense Contractors are gaining share fastest through consolidated sensor suite responsibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics engineering talent clusters in the United States, Germany, and South Korea anchor procurement decisions for precision targeting systems. These three nations concentrate military modernization budgets and drive specification standards across NATO and Indo-Pacific alliance structures.
United States
The US Department of Defense prioritizes sensor fusion mandates for F-35 targeting pods and armored vehicle networks. ITAR export controls fragment component sourcing for cross-Atlantic suppliers, creating dual certification overhead. Defense contractors in Texas and Arizona concentrate airborne laser targeting integration with multi-spectral sensor suites.
Germany
Rheinmetall and Krauss-Maffei Wegmann drive vehicle-mounted optronic suite replacements in main battle tank modernization. The EU AI Act forces algorithmic transparency redesigns for autonomous fire-control architectures. Bavarian and Lower Saxony defense electronics clusters specialize in stabilized turret integration for Leopard platform upgrades.
South Korea
DAPA accelerates KF-21 fighter targeting pod programs and infantry squad handheld saturation requirements. Domestic 1.5-micron laser diode foundry investments reduce East Asian supply chain exposure. Seoul Capital Area contractors pilot performance-based logistics contracts for consolidated sensor suite overhaul responsibility.
United Kingdom
BAE Systems anchors airborne and naval fire control procurement through the Tempest fighter and Type 26 frigate programs. UK Defence Science and Technology Laboratory enforces spectral safety protocols diverging from NATO Standardization Office benchmarks. Scottish and Southwest England clusters specialize in phase-shift interferometric methods for maritime tracking applications.
Israel
Elbit Systems drives dismounted soldier system miniaturization for special operations and border surveillance. Israeli Ministry of Defense procurement prioritizes eye-safe wavelength compliance in desert operational environments. Haifa and Tel Aviv defense electronics corridors concentrate pulse-compression algorithm development for counter-battery radar correlation.
Global Military Laser Rangefinder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across vehicle-mounted, airborne, and handheld product categories. The vendor base stratifies into three tiers: prime contractors with captive sensor suite integration, mid-tier subsystem suppliers with NATO certification depth, and niche component specialists with transmitter manufacturing expertise. Dominant competitive moves include performance-based logistics contracting displacing transactional spare part purchasing, and strategic partnerships with East Asian 1.5-micron laser diode foundries securing transmitter supply.
Among diversified defense conglomerates, Thales Group and Lockheed Martin Corporation exemplify prime contractor archetypes with captive integration into Franco-German combat vehicle programs and F-35 sensor suites respectively. L3Harris Technologies, Inc. occupies a specialist position anchoring US special operations demand with compact handheld designs.
| Leading Market Players |
|---|
| Thales Group |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| RTX Corporation |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Saab AB |
| Elbit Systems Ltd. |
| Others |
Supply & Pricing Matrix
Prime contractors with captive F-35 and armored vehicle integration responsibility command fixed-price multi-year contracts that bundle hardware, software, and logistics support. This buyer concentration shifts pricing power toward performance-based service models rather than transactional unit sales.
Pricing Analysis
Bundled performance-based logistics contracts dominate vehicle-mounted and airborne tiers, while unbundled transactional procurement persists for handheld infantry systems. Price differentiation rests on ITAR certification tier and sensor fusion integration depth. Cost compression in vehicle-mounted configurations is intensifying because NATO standardization mandates force redundant test certification overhead. Infantry procurement shows highest price sensitivity due to squad saturation volume requirements; airborne targeting pods demonstrate lowest sensitivity through captive prime contractor relationships.
Supply Chain Analysis
Dual-sourcing requirements from the US Department of Defense and NATO Standardization Office mandate multi-supplier qualification for 1.5-micron laser diode transmitters. Manufacturing concentrates in South Korea, Japan, and select European foundries. Component sourcing draws from erbium-doped glass suppliers, stabilized gimbal manufacturers, and eye-safe wavelength detector fabricators. Single-source vulnerability in East Asian transmitter foundries exposes procurement to electromagnetic spectrum allocation disputes. Distribution runs through defense prime contractor integration channels rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act algorithmic transparency mandates and ITAR export control evolution continuously reshape procurement specifications and competitive positioning.
For Market Incumbents: Extend performance-based logistics contracting scope to capture consolidated sensor suite overhaul responsibility across NATO armored vehicle fleets. Deepen backward integration into 1.54-micron transmitter manufacturing to reduce East Asian foundry dependency. Lockheed Martin's captive F-35 integration and Thales Group's Franco-German vehicle programs demonstrate the defensive value of prime contractor anchoring against mid-tier subsystem suppliers. For New Entrants and Emerging Players: Defense electronics subsystem specialists represent the most viable channel partner type for market access without prime contractor infrastructure. Naval phase-shift fire control modernization in European and Indo-Pacific fleets offers penetrable white-space where continuous-tracking requirements outpace incumbent pulse-technology portfolios. Target South Korean DAPA infantry squad handheld saturation programs through compact eye-safe wavelength designs optimized for dismounted soldier systems. For Investors and Strategic Acquirers: Tier 1 defense primes with sensor suite integration capability are the most active acquirer in this space, consolidating mid-tier optronic specialists to deepen platform captive positioning. Five-to-ten year viability hinges on EU AI Act compliance architecture and ITAR threshold navigation. Acquisition target archetype: NATO-certified subsystem suppliers with 1.5-micron transmitter manufacturing expertise. Watch electromagnetic spectrum allocation rulings in East Asian regulatory jurisdictions as supply chain inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | NATO maintenance depots in Germany and Poland consolidate sensor suite overhaul with prime contractors. |
| Backward Integration into Transmitter Manufacturing | South Korean foundry investments reduce 1.5-micron laser diode supply chain exposure for DAPA programs. |
| EU AI Act Compliance Architecture Redesign | Algorithmic transparency mandates force decoupling of legacy rangefinder systems from autonomous fire-control networks. |
| Naval Phase-Shift Technology Transition | Continuous-tracking interferometric methods displace single-pulse measurement in maritime fire control modernization. |
| ITAR Dual Certification Investment | Cross-Atlantic suppliers absorb overhead to maintain component sourcing access for NATO interoperability. |
Research Methodology
Multiple input streams — defense procurement database analysis, regulatory filing review, and technical specification benchmarking — were reconciled across primary interviews with program managers at NATO standardization offices, DAPA acquisition leads, prime contractor sensor suite engineers, and infantry equipment procurement officers. Secondary validation drew from ITAR threshold documentation, EU AI Act implementation guidance, ISO 14255 space-qualification standards, and national defense budget appropriation records. Bottom-up unit shipment estimates and top-down defense electronics market sizing were triangulated to anchor volume projections.
Historical procurement patterns were cross-referenced against expert panel assessments of technology transition timelines. The analytical framework modeled segmentation across platform integration level, measurement technology type, and end-user service branch throughout the projection horizon. CAGRs were derived from weighted scenario analysis of armored vehicle modernization cycles, fighter targeting pod deployment schedules, and infantry squad equipment refresh rates. Specific forecast inputs included NATO counter-battery radar correlation requirements and South Korean KF-21 program milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electromagnetic spectrum allocation disputes, ITAR threshold revisions, and EU AI Act enforcement evolution. Deviation in East Asian transmitter foundry regulatory posture would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
United States Defense Market