
 Asia-Pacific Satellite Attitude and Orbit Control System Market | 2026-2036
Asia-Pacific Satellite Attitude and Orbit Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite Attitude and Orbit Control System Market Insights
Buyer concentration among national space agencies and prime satellite manufacturers is hardening across the Asia-Pacific region. Thales leverages its integrated avionics heritage to anchor European-Asia-Pacific technology transfer partnerships. Lockheed Martin sustains defense-grade AOCS supply relationships with select regional governments. Airbus competes through specialized reaction wheel production scaled for commercial constellation programs.
Satellite attitude and orbit control systems comprise precision actuators, sensors, and control electronics that maintain spacecraft orientation and orbital position through closed-loop feedback algorithms operating at millidegree pointing accuracy. These systems enable payload targeting, communications beam steering, and orbital station-keeping for missions spanning single-unit cubesats to multi-ton geostationary platforms. Thruster technology dominates propulsion-intensive geostationary applications where chemical and electric systems manage orbital insertion and drift correction. Earth observation applications are expanding fastest as commercial remote sensing constellations in low Earth orbit multiply, with reaction wheels and magnetorquers forming the core attitude actuation architecture for these smaller spacecraft. Deployment across medium Earth orbit navigation constellations represents a mature segment with established supplier relationships and qualified component heritage.
China's MIIT governs satellite component certification through GB standards and national space industry regulations that restrict foreign subsystem participation in sensitive programs. Japan's METI coordinates industrial policy supporting domestic AOCS supply chain development through JIS standards alignment and space technology roadmaps. India's CEA and BIS frameworks shape power and quality requirements for satellite subsystems procured through ISRO and defense channels. Stakeholders must monitor evolving technology transfer restrictions and indigenous capability mandates as each major spacefaring nation deepens sovereign control over critical attitude determination and control component sources.
Market Dynamics
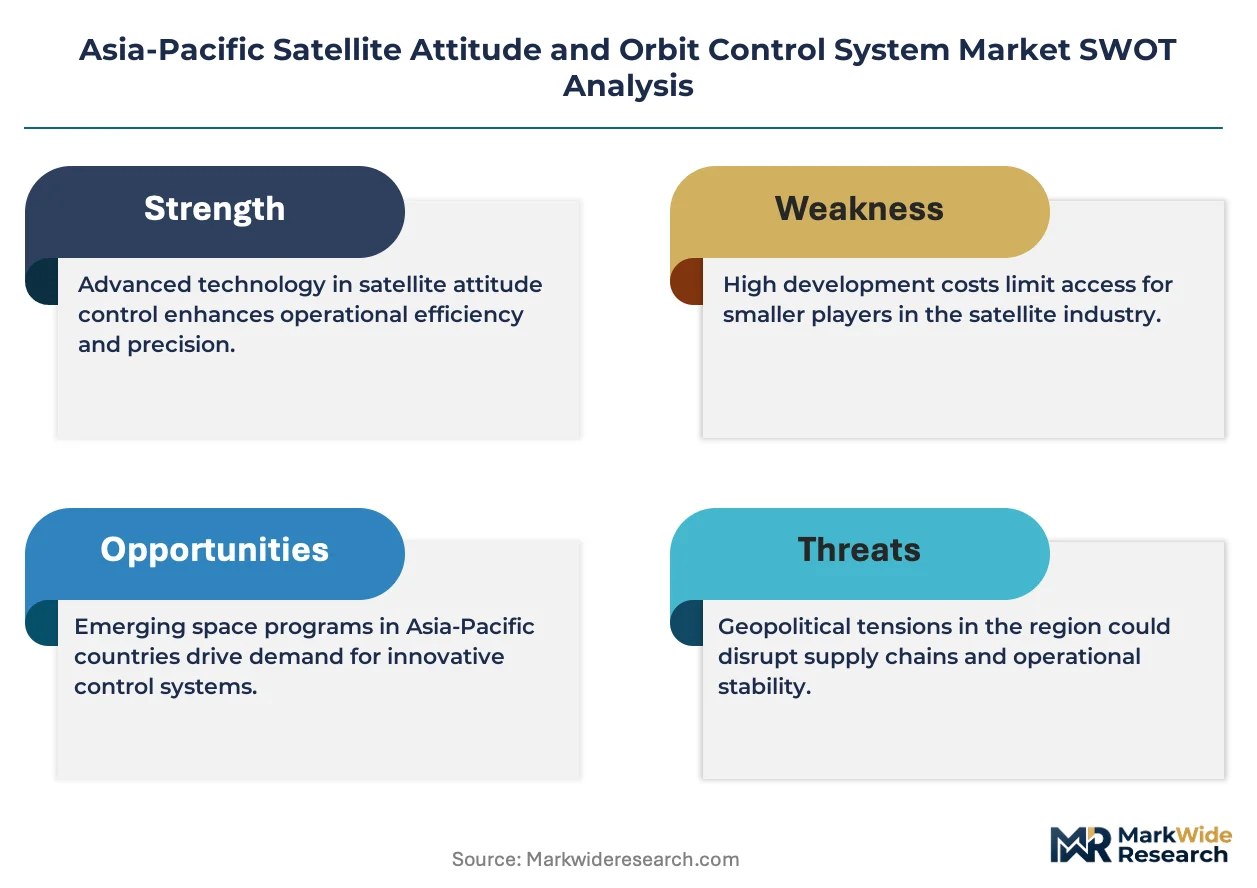
China's MIIT certification mandates for satellite subsystems are hardening sovereign supply chain requirements, forcing foreign AOCS suppliers to establish joint ventures with domestic entities or exit sensitive national security programs entirely.
Growth Catalysts
- Earth Observation Constellation Deployment:ISRO's expansion of remote sensing satellites and China's commercial LEO imaging networks are concentrating procurement of reaction wheel assemblies and star tracker units for high-revisit orbital platforms.
- Japan's Space Technology Roadmap:METI's industrial policy frameworks incentivize domestic AOCS component qualification, accelerating JIS-aligned manufacturing capacity for precision magnetorquers and fiber optic gyroscopes.
- India's Production-Linked Incentive Scheme:PLI scheme extensions into space-grade electronics are attracting component suppliers to establish BIS-certified production lines for satellite control electronics and power conditioning modules.
Market Restraints
- Rare Earth Magnet Supply Concentration:China's dominance in neodymium and dysprosium processing creates input cost volatility for reaction wheel and magnetorquer manufacturers dependent on high-grade permanent magnets.
- Technology Transfer Restrictions:CNSA and ISRO procurement channels enforce strict indigenous content mandates that block foreign participation in attitude determination algorithm development and flight software integration.
- Qualification Timeline Compression:Extended environmental testing protocols for space-grade components stretch development cycles, delaying revenue recognition for AOCS suppliers targeting operational constellation deadlines.
Strategic Opportunities
- Southeast Asian Ground Infrastructure:Vietnam and Indonesia are establishing national space agencies with initial satellite programs, creating entry points for AOCS subsystem suppliers willing to localize assembly and test capabilities.
- Electric Propulsion Convergence:Integration of Hall-effect thrusters with attitude control electronics enables unified orbit-raising and station-keeping architectures, opening bundled procurement contracts for next-generation geostationary platforms.
- Dual-Use Technology Pathways:Japan's relaxation of defense-related space component export controls under revised METI guidelines permits qualified suppliers to serve both commercial and government satellite programs through unified production lines.
Industry Challenges
- Embedded Software Talent Scarcity:Flight control algorithm development requires specialized expertise in orbital mechanics and real-time systems engineering that outpaces regional university pipeline output across India and Southeast Asia.
- Multi-Constellation Integration Complexity:AOCS suppliers must architect scalable control systems compatible with heterogeneous satellite buses ranging from 3U cubesats to 500kg commercial imaging platforms without full platform redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite Attitude and Orbit Control System Market |
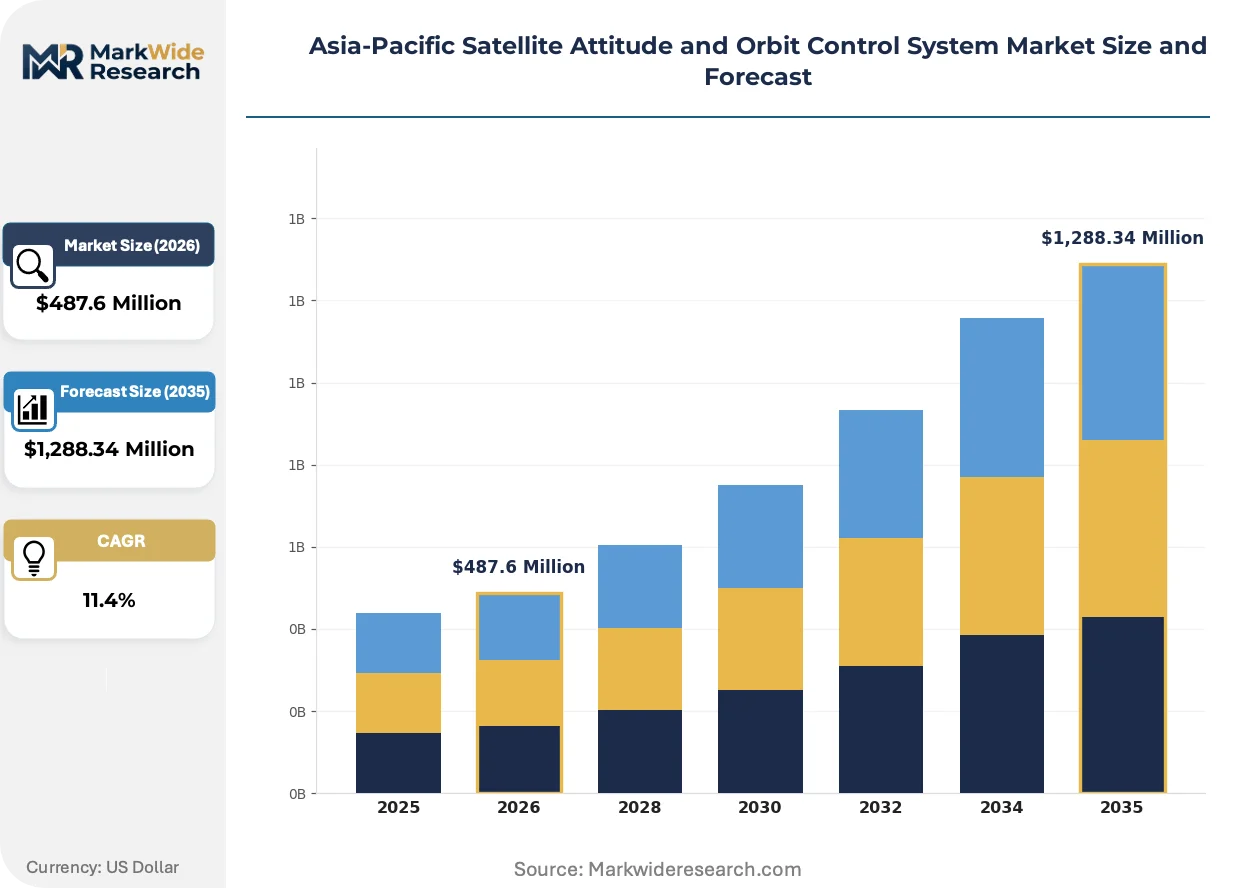
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
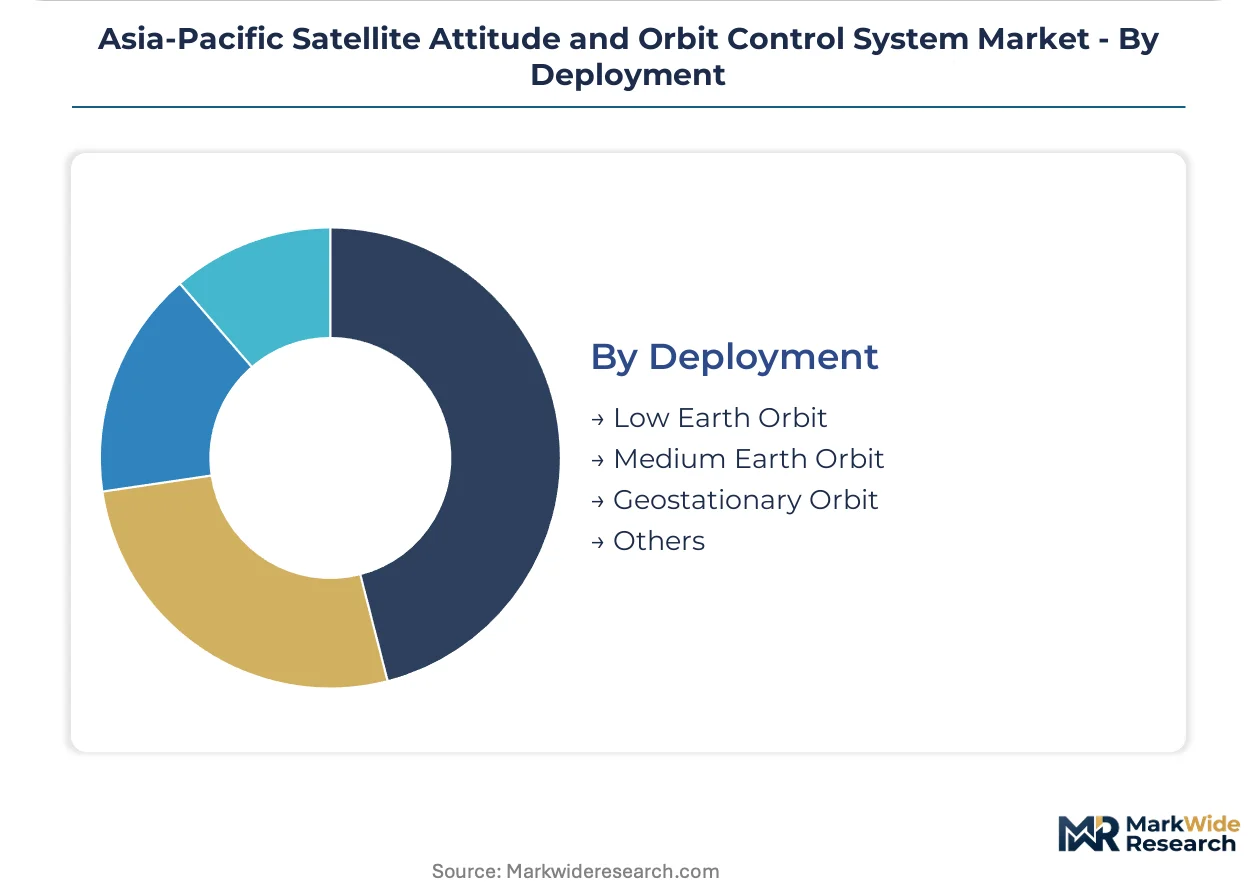
| Segmentation | Technology: Reaction Wheels, Gyroscopes, Magnetorquers, Thrusters Application: Telecommunication, Earth Observation, Scientific Research, Commercial End User: Aerospace Agencies, Satellite Manufacturers, Research Institutions, Defense Deployment: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Others |
| Companies Covered | SENER Group, NewSpace Systems, Thales, Lockheed Martin, Innovative Solutions in Space, AAC Clyde Space, Sitael S.p.A., Airbus, Jena-Optronik, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite Attitude and Orbit Control System Market Trends and Innovations
Artificial intelligence is penetrating satellite operations, compressing ground-segment dependency and enabling autonomous anomaly response that reshapes AOCS specification requirements across procurement channels.
Model predictive control algorithms are automating attitude determination workflows previously requiring continuous ground intervention. Commercial constellation operators in Australia and South Korea are adopting these architectures for LEO formations with sub-degree pointing requirements. This automation is compressing operational staffing models and shifting specification priority toward onboard processing throughput rather than ground-link bandwidth.
Japan's METI has tightened JIS Q 9100 alignment requirements for space component suppliers, mandating traceability systems that extend through three tiers of subcomponent sourcing. Domestic manufacturers are consolidating supplier bases to meet audit burden, while foreign entrants face extended qualification timelines. Small satellite integrators with limited procurement leverage are experiencing the steepest compliance cost escalation.
Consolidated subsystem procurement is displacing discrete component purchasing across Asia-Pacific satellite programs. Prime manufacturers in China and India now specify integrated AOCS modules combining sensors, actuators, and control electronics rather than sourcing elements separately. This bundling is visible most acutely in ISRO's commercial arm NSIL tendering patterns and CNSA-directed commercial satellite procurements.
Asia-Pacific Satellite Attitude and Orbit Control System Market Segmentation
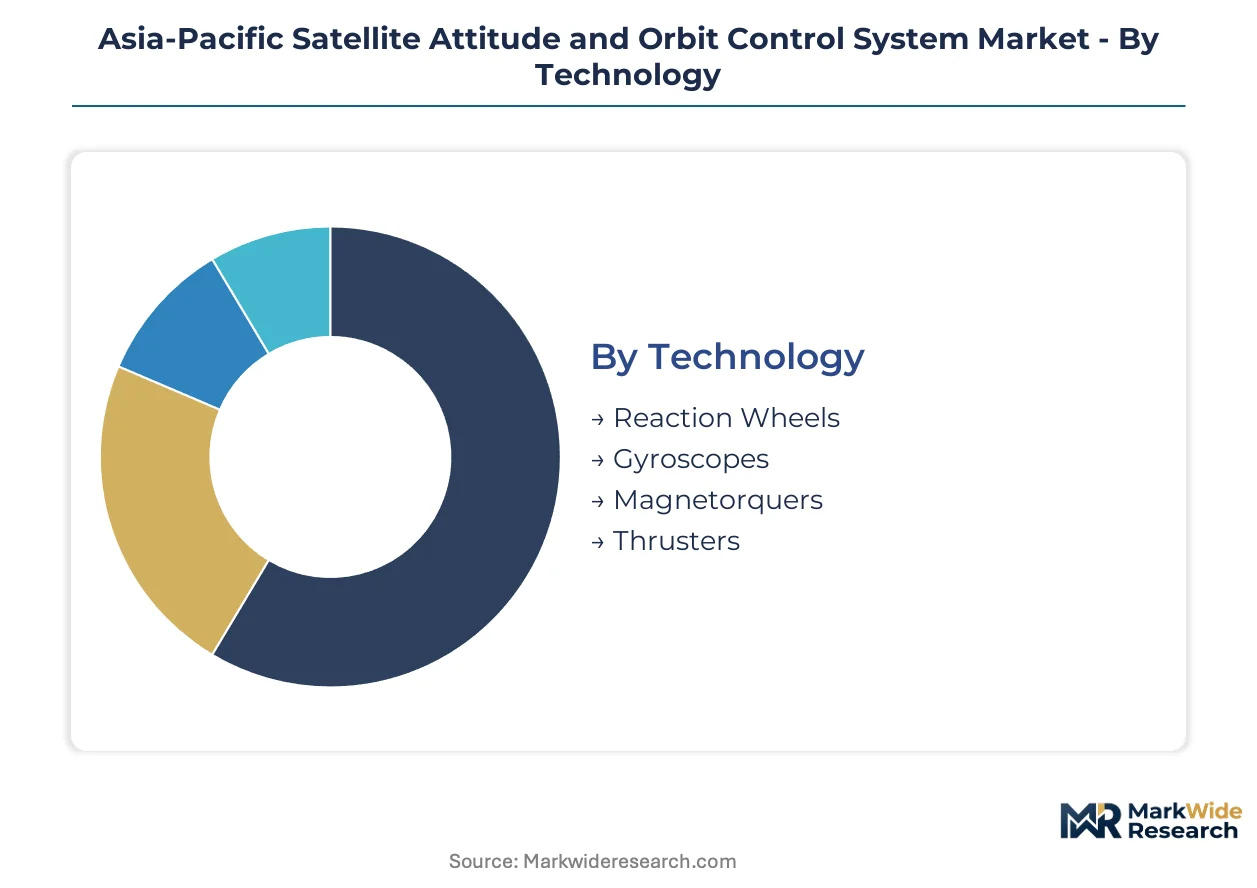
AOCS procurement patterns diverge sharply between integrated subsystem contracts and discrete component sourcing. Prime manufacturers in China and India increasingly specify bundled modules, while research institutions maintain fragmented purchasing for experimental missions.
Technology:
Reaction wheels and gyroscopes function as standalone attitude determination units, whereas magnetorquers and thrusters embed within broader propulsion architectures.
- Reaction Wheels:Momentum-exchange devices using high-speed rotors provide precise three-axis attitude control for Earth observation satellites. ISRO's remote sensing constellations and China's commercial LEO imaging networks concentrate procurement of these assemblies. Extended qualification timelines under MIIT GB standards stretch supplier development cycles for foreign entrants.
- Gyroscopes:Fiber optic and MEMS variants measure angular velocity for closed-loop feedback algorithms operating at millidegree accuracy. Japan's METI technology roadmaps prioritize domestic JIS-aligned manufacturing capacity for precision fiber optic units. Australian and South Korean constellation operators specify these for autonomous formation flying.
- Magnetorquers:Torque rods interacting with Earth's magnetic field deliver momentum dumping without propellant consumption.
- Thrusters:Chemical and electric propulsion systems manage orbital insertion, station-keeping, and end-of-life deorbiting maneuvers.
Reaction wheels lead volumes today; gyroscopes are gaining share fastest.
Application:
Cost tier separation distinguishes high-budget government programs from commercial constellation deployments with aggressive unit economics targets.
- Telecommunication:Geostationary platforms demand high-reliability AOCS with 15-year operational lifespans and redundant actuator configurations. CNSA-directed commercial satellite procurements specify integrated modules combining sensors and control electronics. India's NSIL tendering patterns show similar bundling for national communication satellites.
- Earth Observation:High-revisit LEO constellations multiply procurement of compact reaction wheel assemblies and star tracker units. China's commercial imaging networks and ISRO's expansion of remote sensing satellites drive segment concentration. Sub-degree pointing requirements compress development cycles for component suppliers.
- Scientific Research:Experimental missions prioritize precision over cost, sourcing discrete components for custom platform integration.
- Commercial:Venture-funded constellation operators impose aggressive pricing and rapid delivery schedules on AOCS suppliers.
Telecommunication retains the largest revenue base; Earth Observation shows the steepest expansion trajectory.
End User:
Customer type determines procurement leverage, with national space agencies commanding custom specifications and satellite manufacturers driving standardization.
- Aerospace Agencies:ISRO, CNSA, and JAXA specify mission-proven component heritage with extended environmental testing protocols. Indigenous content mandates block foreign participation in flight software integration for sensitive programs. Technology transfer restrictions harden sovereign supply chain requirements across procurement channels.
- Satellite Manufacturers:Prime integrators in China and India consolidate supplier bases to meet JIS Q 9100 traceability requirements. These manufacturers increasingly specify integrated AOCS modules rather than discrete components. Small satellite integrators experience compliance cost escalation due to limited procurement leverage.
- Research Institutions:Universities and laboratories source experimental-grade components with relaxed qualification requirements.
- Defense:Military satellite programs impose security-cleared supply chains and encrypted control algorithms.
Aerospace agencies dominate contract values; satellite manufacturers are expanding procurement volume most rapidly.
Deployment:
Orbital altitude correlates directly with actuator selection, propulsion intensity, and component lifetime requirements.
- Low Earth Orbit:Altitudes below 2,000 kilometers favor reaction wheels and magnetorquers for attitude control without heavy propulsion systems. Commercial remote sensing constellations in Australia and South Korea adopt model predictive control algorithms for autonomous operations. Atmospheric drag necessitates periodic orbit-raising maneuvers using electric thrusters.
- Geostationary Orbit:Station-keeping at 35,786 kilometers demands chemical and electric propulsion for orbital drift correction. Thruster technology dominates this segment with unified orbit-raising and station-keeping architectures emerging. Hall-effect thruster integration with attitude control electronics opens bundled procurement contracts.
- Medium Earth Orbit:Navigation constellations represent mature demand with established supplier relationships.
- Others:Highly elliptical and polar orbits require specialized control strategies for variable thermal and radiation environments.
Geostationary Orbit maintains premium pricing; Low Earth Orbit deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates sovereign procurement through CNSA-directed programs, while India's ISRO channels commercial demand through NSIL tendering patterns that increasingly favor integrated subsystem bundles over discrete component sourcing.
China
MIIT certification mandates harden supply chain sovereignty for satellite subsystems, forcing foreign AOCS suppliers into joint ventures or exit from national security programs. GB standards govern component qualification with extended environmental testing protocols that stretch development cycles. Shanghai and Beijing clusters host prime manufacturers consolidating supplier bases to meet traceability requirements through three tiers of subcomponent sourcing.
India
ISRO's remote sensing constellation expansion drives concentrated procurement of reaction wheel assemblies and star tracker units for high-revisit orbital platforms. CEA and BIS frameworks shape power and quality requirements for subsystems procured through defense and space channels. Bengaluru's aerospace corridor attracts component suppliers establishing BIS-certified production lines under PLI scheme extensions into space-grade electronics.
Japan
METI technology roadmaps prioritize domestic JIS-aligned manufacturing capacity for precision fiber optic gyroscopes and magnetorquers. JIS Q 9100 alignment requirements mandate traceability systems extending through three tiers of subcomponent sourcing. Nagoya and Tokyo industrial zones consolidate supplier bases to meet audit burdens, while foreign entrants face extended qualification timelines for space component certification.
South Korea
Commercial constellation operators adopt model predictive control algorithms for autonomous LEO formation flying with sub-degree pointing requirements. The country's national space agency channels procurement toward onboard processing throughput specifications rather than ground-link bandwidth. Daejeon-Sejong corridor hosts satellite integrators specifying bundled AOCS modules combining sensors, actuators, and control electronics for heterogeneous platform architectures.
Australia
Venture-funded constellation operators impose aggressive pricing and rapid delivery schedules on AOCS suppliers targeting Earth observation deployments. The national space agency coordinates initial satellite programs creating entry points for subsystem suppliers willing to localize assembly and test capabilities. Sydney and Melbourne clusters concentrate small satellite integrators experiencing compliance cost escalation due to limited procurement leverage against prime manufacturer bundling trends.
Asia-Pacific Satellite Attitude and Orbit Control System Market Competitive Landscape
European producers anchor the integrated subsystem tier; Asia-Pacific specialists hold discrete component manufacturing positions. The vendor base structures around three tiers: prime integrators bundling sensors, actuators, and control electronics; mid-scale manufacturers qualifying heritage components for constellation programs; and research-grade suppliers serving experimental missions. Consolidation concentrates through strategic partnerships and capacity expansion as sovereign content mandates harden across procurement channels.
Among European-based system integrators, Thales and Airbus occupy positions exemplifying the bundled procurement archetype, while Lockheed Martin represents defense-grade supply relationships with select regional governments. SENER Group and Sitael S.p.A. sit within the specialized actuator manufacturing tier serving both commercial and government satellite programs through unified production lines. NewSpace Systems and AAC Clyde Space exemplify the emerging small-satellite component qualification segment addressing rapid constellation deployment timelines.
| Leading Market Players |
|---|
| SENER Group |
| NewSpace Systems |
| Thales |
| Lockheed Martin |
| Innovative Solutions in Space |
| AAC Clyde Space |
| Sitael S.p.A. |
| Airbus |
| Jena-Optronik |
| Others |
Pricing and Supply Chain Analysis
Captive magnet processing in China anchors both the upstream supply position and the downstream pricing power for reaction wheel and magnetorquer manufacturers. MIIT GB standards enforce indigenous content thresholds that force foreign AOCS suppliers into joint venture structures, compressing margin capture for non-domestic entities while elevating cost pass-through leverage for qualified domestic producers.
Pricing Analysis
Capacity additions in China's rare earth processing corridors are reshaping price floors for permanent magnet-dependent actuators. Three-tier pricing structure across flight-proven, qualification-grade, and experimental-tier components separates ISRO heritage suppliers from emerging constellation vendors. Pricing pressure stems from commercial LEO operators imposing aggressive unit economics targets on reaction wheel assemblies. Small satellite integrators exhibit highest price sensitivity due to limited procurement leverage against prime manufacturer bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from China's CNSA-directed programs and India's NSIL tendering patterns. Geographic supply concentrates in China for rare earth magnet processing, Japan for precision fiber optic gyroscopes, and India for BIS-certified control electronics. Raw material dependencies draw from neodymium-dysprosium magnet alloys, high-grade optical fibers, and space-grade semiconductor substrates. Single-source vulnerability in China's magnet processing creates input cost volatility. Distribution runs through prime integrator consolidation toward bundled subsystem procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on electric propulsion-AOCS convergence creating bundled contract opportunities. Hall-effect thruster integration with attitude control electronics enables unified architecture premiums.
For Market Incumbents: Deepen JIS Q 9100 traceability compliance to defend position against METI audit burden escalation. Secure backward integration into rare earth magnet sourcing to offset China's processing dominance. Lock long-term supply agreements with ISRO and CNSA before indigenous content mandates harden further. For New Entrants and Emerging Players: Satellite integrators in Vietnam and Indonesia represent the most penetrable channel partner type for AOCS subsystem suppliers willing to localize assembly capabilities. Target Earth observation constellations in Australia and South Korea where autonomous formation flying specifications outpace incumbent response capacity. Lead with model predictive control algorithm integration as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale actuator manufacturers because METI and MIIT certification barriers fragment supplier bases into subscale entities. Five-to-ten year viability favors firms with dual-use technology pathways serving both commercial and government channels. Watch Japan's defense export control relaxation signals as inflection indicator for unified production line scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | MIIT GB compliance enables foreign supplier participation in CNSA-directed national security programs. |
| Backward Integration | Captive rare earth magnet processing insulates reaction wheel manufacturers from China's pricing volatility. |
| Certification Investment | BIS and JIS Q 9100 alignment opens ISRO and METI procurement channels for qualified entrants. |
| Technology Licensing | Model predictive control algorithm transfers accelerate Australian and South Korean constellation deployments. |
| Geographic Expansion | Localized assembly in Vietnam and Indonesia satisfies emerging national space agency sovereignty requirements. |
Research Methodology
Multiple input streams — satellite manufacturer procurement leads, aerospace agency program managers, component engineering directors, and defense channel specialists — were reconciled against customs trade records, ISRO tender databases, METI technology roadmap publications, and SEC filings from exposed suppliers. Bottom-up component demand aggregation and top-down program budget allocation were cross-validated through triangulation.
Data-stream reconciliation across the projection horizon modeled technology segmentation by actuator type, application tier, end-user procurement leverage, and orbital deployment altitude. CAGRs were derived from constituent growth rate blending across these dimensions. Electric propulsion integration timelines and sovereign content mandate enforcement trajectories served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to technology transfer restriction escalations and rare earth supply disruption scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
High-Throughput Satellite Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Europe Small Satellite Market
Satellite
India Satellite Connectivity Market
Satellite
Satellite Communication System Market
Satellite
LEO Satellite System Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Small Satellite Launch Market
Satellite
North America Satellite Bus Market
Satellite
Satellite GPS Receivers Market
Satellite
Communication Satellite Launch Services Market
Satellite
Satellite Connectivity Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Satellite Parts and Components Market