
 Target Acquisition Systems Market | 2026-2036
Target Acquisition Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Target Acquisition Systems Market Analysis
Multi-source procurement is rebalancing toward qualified dual-source arrangements for critical electro-optical subassemblies. Lockheed Martin Corporation leverages captive production of stabilized turrets to secure delivery schedules for precision-strike programs. Elbit Systems Ltd. competes through vertical integration into thermal imaging cores, while BAE Systems plc anchors European supply through sovereign sensor manufacturing in the United Kingdom.
Target acquisition systems integrate multispectral sensors, laser rangefinders, and ballistic computers to detect, identify, and prioritize threats for engagement by precision munitions or directed-energy weapons. Electro-optical systems lead product-type revenue due to maturity in daylight targeting pods, while dual-mode systems combining infrared and radar channels represent the fastest-growing configuration as operators demand all-weather, counter-jam capability. Active guidance technology dominates technology segmentation through radar-homing antiship and air-to-air applications, whereas autonomous guidance sustains premium pricing in denied-GPS environments where GPS-denied navigation algorithms prove essential.
FAA and NHTSA standards govern civilian derivative platforms, while ITAR and EAR administered by the US State and Commerce Departments control cross-border transfer of targeting software and thermal cores. EMA and EU AI Act frameworks are beginning to shape certification pathways for autonomous target-recognition algorithms in European defense procurement. Stakeholders must monitor divergence between US and European AI governance regimes as this fragmentation threatens interoperability in multinational coalition operations and supplier market access.
Market Dynamics
Dual-mode sensor procurement is compressing supplier qualification timelines as NATO members synchronize precision-strike modernization schedules. Defense contractors face simultaneous pressure to accelerate delivery while satisfying ITAR and EAR compliance for thermal core exports.
Growth Catalysts
- ITAR modernization:The US State Department's revised Category XII controls are streamlining licensing for allied nations, reducing procurement friction for integrated fire-control networks in coalition operations.
- Directed-energy weapon integration:Precision-strike platforms require upgraded acquisition suites capable of tracking high-speed targets for laser and microwave weapon engagement.
- Germany's Zeitenwende spending:Berlin's defense investment surge is accelerating orders for sovereign sensor manufacturing capacity and dual-source electro-optical subassembly arrangements.
Market Restraints
- Mercury cadmium telluride scarcity:Thermal imaging core production depends on this specialized semiconductor material, with supply concentrated among limited qualified foundries.
- EAR dual-use classification:Commerce Department export controls on ballistic computing software create licensing bottlenecks for non-NATO customers seeking integrated targeting systems.
- SWaP constraints:Size, weight, and power limitations on unmanned platforms restrict sensor payload configurations below thresholds required for full-spectrum target discrimination.
Strategic Opportunities
- Israeli counter-UAS specialization:Tel Aviv's defense ecosystem offers partnership pathways for acquisition systems optimized against drone swarm threats in contested airspace.
- EU AI Act certification:Early compliance with autonomous target-recognition algorithm standards creates preferential access to European procurement tenders requiring explainable AI.
- GPS-denied navigation convergence:Fusing visual-inertial odometry with celestial referencing opens new application spaces for denied-environment precision engagement.
Industry Challenges
- Cleared workforce scarcity:Security clearance backlogs for software engineers with machine-vision expertise delay algorithm development for classified targeting programs.
- Legacy platform integration:Retrofitting fourth-generation aircraft with open-architecture sensor suites requires extensive airframe modification and flight certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Target Acquisition Systems Market |
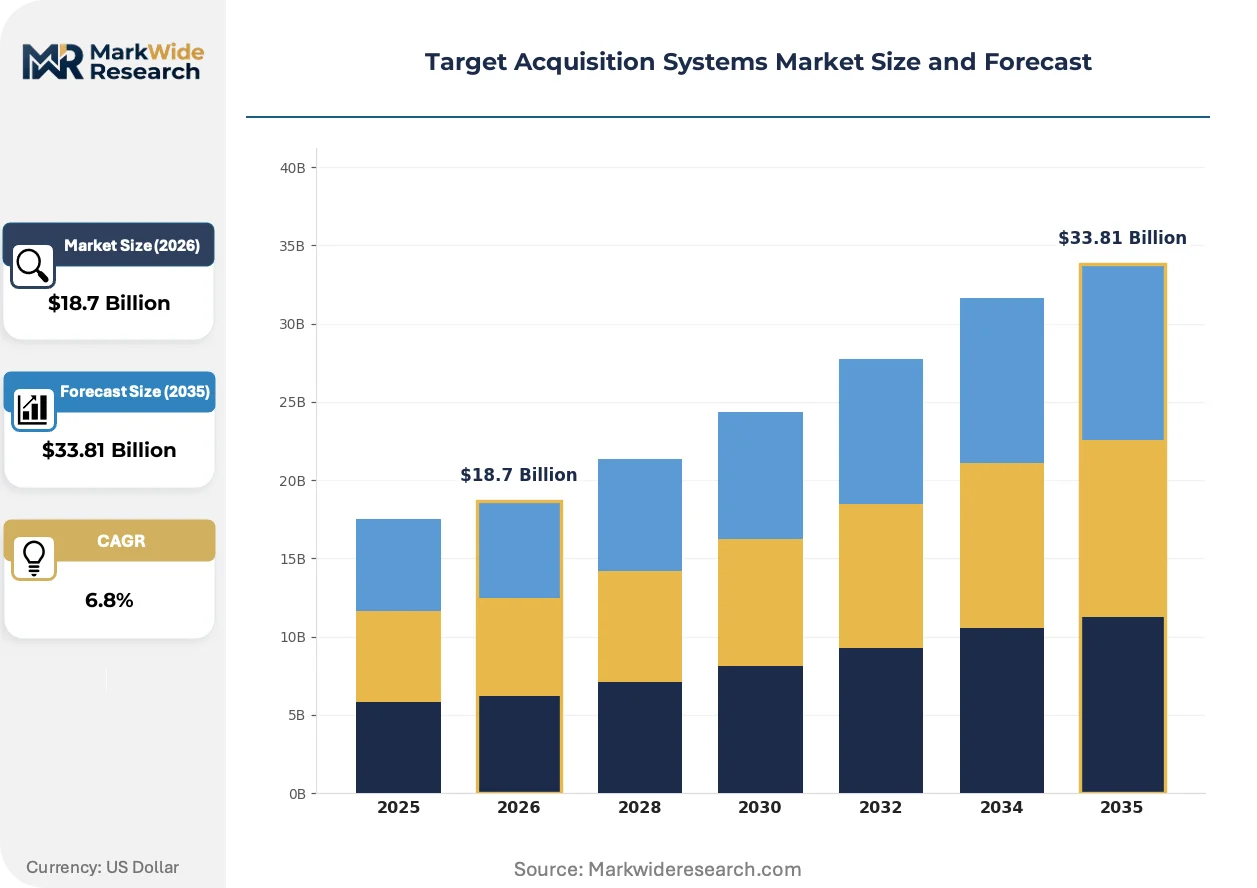
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Electro-Optical Systems, Infrared Systems, Dual-Mode Systems Technology: Active Guidance, Passive Guidance, Semi-Active Guidance, Autonomous Guidance Application: Aerospace, Military, Maritime, Ground Forces End User: Government, Defense Contractors, Research Institutions, Private Security |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Elbit Systems Ltd., BAE Systems plc, Hensoldt AG, Israel Aerospace Industries, Rheinmetall AG, Leonardo S.p.A, Aselsan A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Target Acquisition Systems Market Emerging Trajectories
Active sensor fusion is displacing single-spectrum targeting pods across fixed-wing and rotary platforms. Operators now demand seamless handoff between electro-optical, infrared, and radar channels without pilot intervention.
Multispectral sensor suites are integrating short-wave infrared with long-wave thermal channels to defeat camouflage and atmospheric obscurants. Attack helicopter operators in the United States and Germany are fielding these configurations for urban close-air-support missions. This convergence is integrating previously separate maintenance supply chains and training pipelines under unified platform contracts.
The EU AI Act's risk-classification framework for autonomous weapon systems is forcing European suppliers to document algorithmic decision pathways. BAE Systems and continental competitors must now maintain technical files demonstrating human oversight retention in target-priority logic. This regulatory architecture most affects fire-control software for ground combat vehicles, where procurement specifications increasingly mandate explainability-by-design.
Defense ministries are consolidating sensor procurement under platform-prime contracts rather than component-separate buying. The United Kingdom's integrated procurement model for the Tempest fighter program bundles acquisition, fire-control, and electronic warfare under a single delivery accountability. This pattern concentrates negotiation leverage with prime contractors while squeezing mid-tier electro-optical specialists into subcontractor roles.
Target Acquisition Systems Market Segmentation
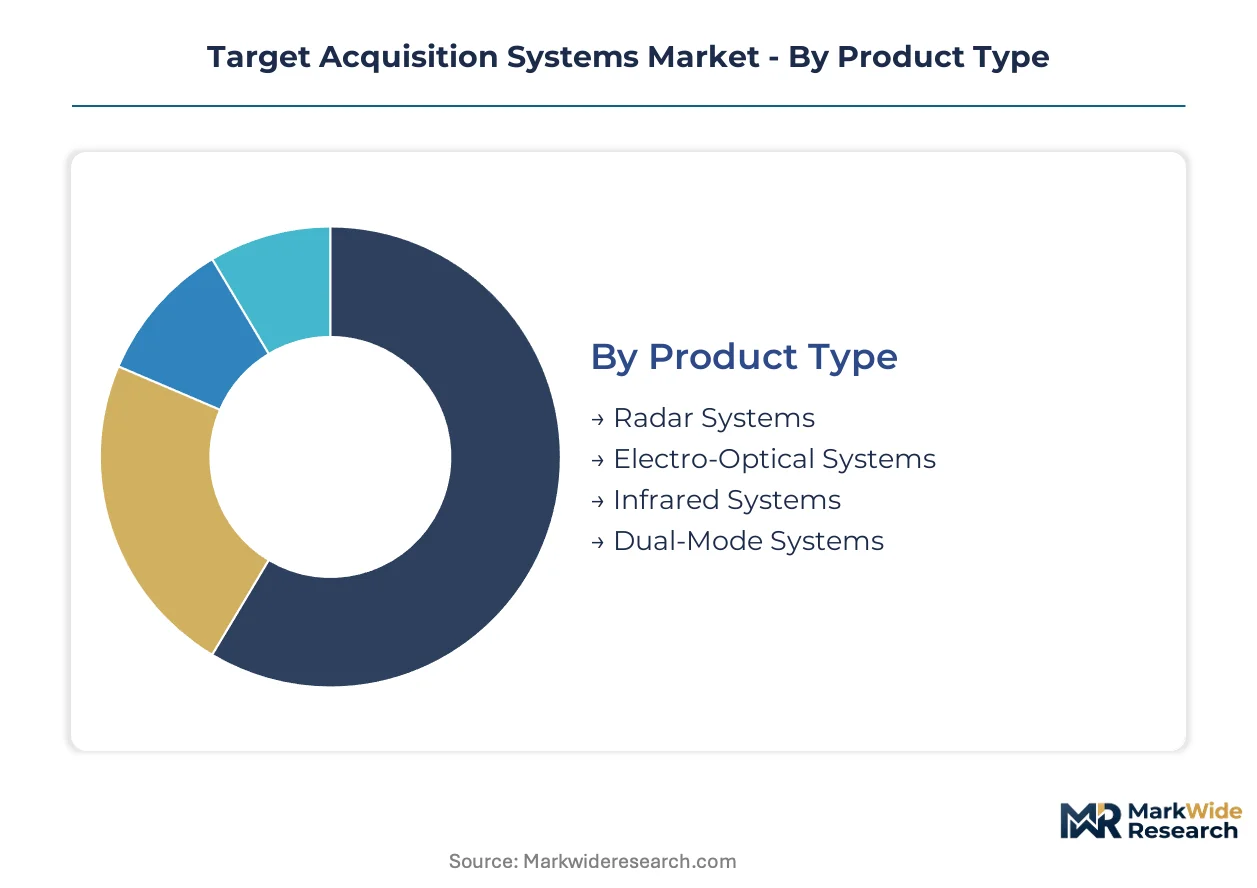
Target acquisition systems fragment across four dimensions that determine procurement pathways and supplier qualification requirements. Product type and technology choices cascade into application-specific configurations, while end-user identity governs regulatory compliance obligations.
Product Type:
Volume concentration favors mature daylight-capable hardware, while premium allocation shifts toward all-weather fusion architectures.
- Electro-Optical Systems:Daylight targeting pods with stabilized turrets and laser designation capability anchor fixed-wing precision-strike programs. United States Air Force procurement of Sniper and Litening pods sustains production lines for this segment. Maturity in airframe integration and pilot training infrastructure reinforces incumbent supplier positions.
- Dual-Mode Systems:Fused infrared and radar channels deliver counter-jam targeting in contested electromagnetic environments. German Zeitenwende spending accelerates orders for these configurations on Eurofighter and Tornado platforms. NATO interoperability standards now mandate seamless spectrum handoff as a baseline requirement.
- Radar Systems:Active electronically scanned arrays for beyond-visual-range air-to-air engagement.
- Infrared Systems:Long-wave thermal imagers for passive detection and tracking.
Mature deployment sits with electro-optical hardware. Newer deployment is concentrated in dual-mode fusion architectures.
Technology:
Active and passive modalities split the market by engagement geometry, with autonomous algorithms commanding premium positioning in denied-GPS scenarios.
- Active Guidance:Radar-homing seekers with onboard emitters dominate antiship and air-to-air applications requiring fire-and-forget autonomy. Maritime patrol aircraft and naval strike fighters in Israel and the United States field these for over-the-horizon engagements. Thermal battery constraints limit miniaturization for smaller munitions.
- Autonomous Guidance:Visual-inertial odometry and celestial referencing enable precision engagement without external signals. Israeli defense contractors specialize in these algorithms for operations in GPS-denied airspace. Procurement specifications increasingly mandate human oversight retention in target-priority logic per emerging AI governance frameworks.
- Passive Guidance:Infrared seekers tracking target thermal signatures without emission.
- Semi-Active Guidance:Laser or radar illumination requiring external designation source.
Active guidance retains the largest installed base. Autonomous guidance gains share fastest in special-mission and contested-environment procurement.
Application:
Military modernization budgets concentrate demand in precision-strike platforms, while maritime and ground domains pursue sensor commonality under platform-prime contracts.
- Military:Integrated fire-control networks for fighter aircraft, attack helicopters, and unmanned combat air vehicles consume the majority of procurement volume. Dual-source electro-optical subassembly arrangements are compressing supplier qualification timelines across NATO members. ITAR Category XII licensing reforms are streamlining allied nation access to thermal core technology.
- Ground Forces:Vehicle-mounted stabilized sights and dismounted soldier targeting systems are consolidating under open-architecture mandates. Germany's investment surge includes sovereign sensor manufacturing capacity for Leopard and Puma platforms. SWaP constraints on unmanned ground vehicles restrict full-spectrum configurations.
- Aerospace:Civilian derivative platforms governed by FAA airworthiness standards.
- Maritime:Naval fire-control for surface-to-surface and surface-to-air engagements.
Fixed-wing military applications retain mature supply chains. Ground force modernization represents the steepest expansion trajectory as armored vehicle fleets upgrade.
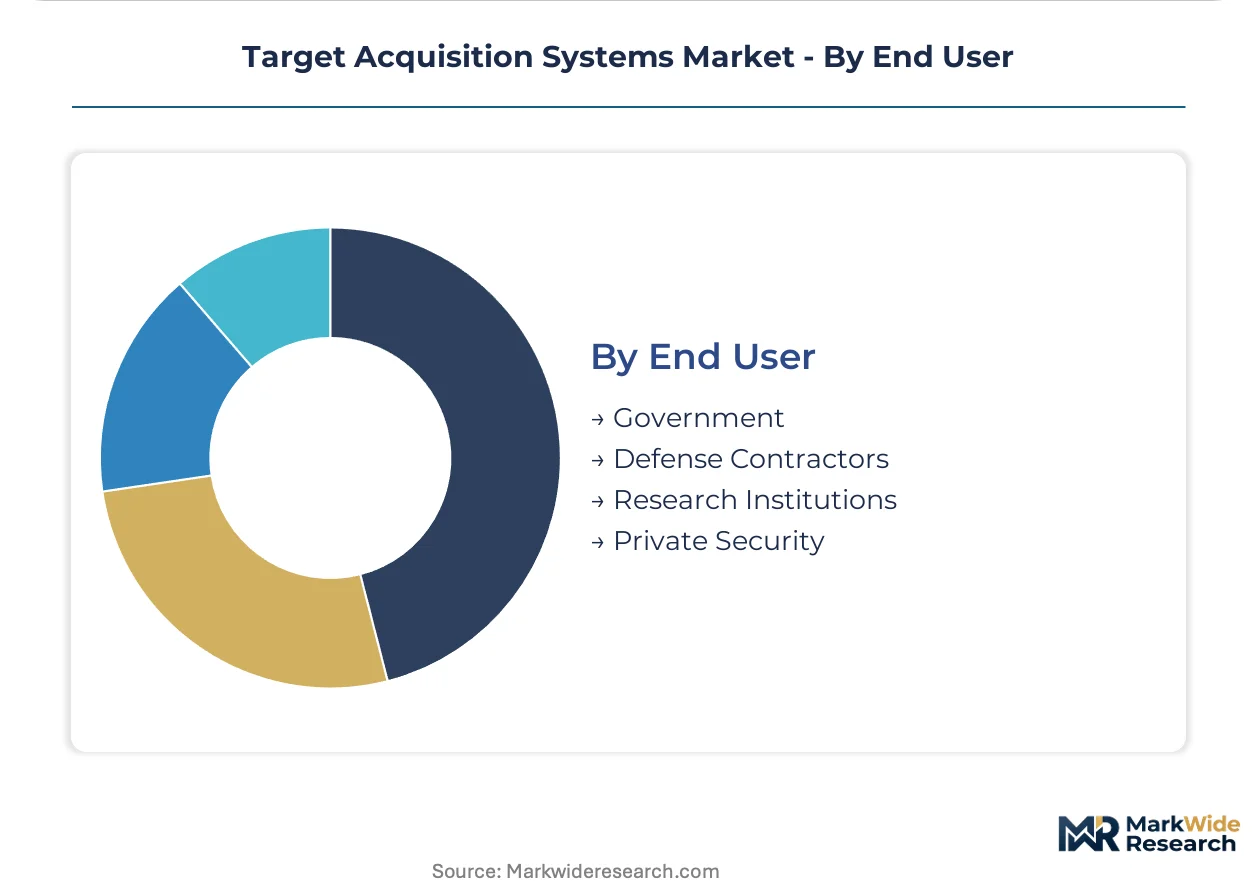
End User:
Government procurement concentration creates tiered supplier access, with defense contractors serving as gatekeepers to classified program participation.
- Defense Contractors:Lockheed Martin, BAE Systems, and Elbit Systems integrate acquisition suites under platform-prime accountability, concentrating negotiation leverage and squeezing mid-tier electro-optical specialists into subcontractor roles. The United Kingdom's Tempest program bundles acquisition, fire-control, and electronic warfare under unified delivery.
- Government:Defense ministries in the United States, Germany, and Israel directly fund research and prototype development for sovereign capability retention. ITAR and EAR compliance requirements filter supplier pools for thermal core and ballistic computing exports.
- Research Institutions:Algorithm development for autonomous target recognition.
- Private Security:Commercial derivatives with civilian sensor configurations.
Prime contractor relationships dominate mature procurement channels. Direct government research funding is concentrating in sovereign algorithm development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mercury cadmium telluride foundry capacity concentrates in the United States, Germany, and Israel, anchoring thermal core supply chains for precision-strike modernization programs. These three nations drive procurement concentration for integrated fire-control networks and dual-mode sensor suites.
United States
The US Air Force sustains production lines for Sniper and Litening targeting pods through multi-year procurement contracts. FAA and NHTSA standards govern civilian derivative platforms, while ITAR Category XII controls administered by the State Department filter supplier pools for thermal core exports. The Arizona and Florida defense corridors host prime contractor integration facilities for fighter aircraft acquisition suites.
Germany
Berlin's Zeitenwende spending surge accelerates orders for sovereign sensor manufacturing capacity on Eurofighter and Tornado platforms. EMA and EU AI Act frameworks shape certification pathways for autonomous target-recognition algorithms in European defense procurement. The Bavaria and Baden-Württemberg industrial clusters concentrate Hensoldt AG and Rheinmetall AG production for Leopard and Puma vehicle-mounted systems.
Israel
Tel Aviv's defense ecosystem specializes in GPS-denied navigation algorithms and counter-UAS acquisition systems for contested airspace operations. Israeli contractors face ITAR compliance requirements for thermal core technology transfers to allied nations. The Haifa and Beersheba metropolitan areas anchor Israel Aerospace Industries and Elbit Systems Ltd. research campuses for autonomous guidance development.
United Kingdom
The Tempest fighter program bundles acquisition, fire-control, and electronic warfare under unified platform-prime accountability. BAE Systems plc maintains sovereign sensor manufacturing capacity to satisfy UK defense procurement specifications. The Lancashire and Hampshire regions host prime contractor facilities for open-architecture sensor suite integration.
Italy
Leonardo S.p.A. leverages domestic electro-optical production for attack helicopter targeting systems in NATO coalition operations. EU AI Act risk-classification frameworks mandate explainability-by-design in fire-control software for ground combat vehicles. The Rome and Milan metropolitan clusters concentrate research funding for multispectral sensor fusion technologies.
Target Acquisition Systems Market Vendor Landscape
Platform-prime contract consolidation dominates the current landscape, compressing mid-tier electro-optical specialists into subcontractor roles. The vendor base organizes around three strategic archetypes: integrated defense conglomerates with captive sensor production, sovereign technology champions serving national procurement mandates, and regional specialists leveraging counter-UAS expertise. M&A activity and sovereign manufacturing capacity expansion represent the dominant competitive moves as nations prioritize supply chain security.
Among integrated defense conglomerates, Lockheed Martin Corporation and BAE Systems plc exemplify the platform-prime archetype through unified delivery accountability for fighter aircraft acquisition suites. Elbit Systems Ltd. occupies a specialist position within the GPS-denied navigation and thermal imaging core segment. These three entities represent contrasting geographic anchors—American, British, and Israeli—each aligned with distinct regulatory compliance frameworks governing cross-border technology transfer.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Hensoldt AG |
| Israel Aerospace Industries |
| Rheinmetall AG |
| Leonardo S.p.A |
| Aselsan A.S. |
| Others |
Supply Flow & Price Mechanics
Dual-mode sensor fusion architectures are compressing cost economics for electro-optical subassemblies while simultaneously concentrating procurement leverage with prime contractors who control stabilized turret and thermal core integration. This technology transition rewards captive production capacity and punishes component specialists lacking platform-prime relationships.
Pricing Analysis
Extended warranty and field-service bundling separate premium-tier suppliers from unbundled transactional competitors in military procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ITAR certification status and sovereign manufacturing content. Cost compression in standard-tier electro-optical pods is intensifying because German Zeitenwende spending is accelerating dual-source qualification timelines. Defense contractors show least price sensitivity for GPS-denied navigation algorithms, while private security buyers drive economy-tier demand.
Supply Chain Analysis
Mercury cadmium telluride feedstock rests on qualified foundry capacity concentrated in the United States, Germany, and Israel. Ballistic computing software and stabilized gimbal mechanics draw from aerospace-tier machine shops in these same nations. Single-source vulnerability in thermal imaging core production creates procurement risk for non-NATO customers facing EAR licensing bottlenecks. Distribution runs through defense ministry platform-prime contracts rather than component-separate purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-prime contract consolidation is accelerating as sovereign manufacturing mandates and ITAR compliance requirements force mid-tier electro-optical specialists into exit or acquisition.
For Market Incumbents:Acquire sovereign sensor manufacturing capacity in Germany or Israel to satisfy Zeitenwende and bilateral procurement specifications. Deepen backward integration into thermal imaging core production to secure mercury cadmium telluride supply against foundry bottlenecks. Counter emerging Israeli counter-UAS specialists by embedding GPS-denied algorithm development within captive research campuses.
For New Entrants and Emerging Players:EU AI Act risk-classification frameworks in Europe open a window for explainable-AI fire-control software specialists to penetrate ground combat vehicle procurement. Target German Leopard and Puma platform upgrade cycles as the most penetrable segment, leveraging algorithmic decision-pathway documentation as the go-to-market wedge. Partner with Hensoldt or Rheinmetall for sovereign manufacturing qualification rather than building independent ITAR-compliant facilities.
For Investors and Strategic Acquirers:Exit pathways concentrate in prime contractor rollup transactions as Lockheed Martin, BAE Systems, and Elbit Systems consolidate subcontractor networks. Long-term viability favors vertically integrated sensor houses with captive thermal core production and cleared algorithm development workforces. Watch ITAR Category XII licensing reform implementation as the signal for accelerated allied-nation market access and valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Sensor Manufacturing Expansion | Hensoldt and Rheinmetall capacity additions satisfy German Zeitenwende procurement mandates for Leopard platforms. |
| Dual-Mode Sensor Suite Integration | Fused infrared-radar channels meet NATO interoperability standards for Eurofighter and Tornado upgrades. |
| GPS-Denied Algorithm Development | Israeli contractors leverage visual-inertial odometry specialization for contested electromagnetic environment operations. |
| ITAR Compliance Infrastructure Investment | Cleared workforce pipelines and export licensing systems unlock allied-nation thermal core procurement. |
| EU AI Act Certification Pathway | Explainable-AI documentation enables BAE Systems and continental competitors to access European ground vehicle tenders. |
Methodological Framework
Defense procurement databases, ITAR licensing records, and EMA regulatory filings formed the secondary backbone for this analysis. Primary interviews with platform integration engineers, thermal imaging core procurement leads, and defense ministry acquisition officers triangulated against customs data and prime contractor SEC disclosures. Bottom-up segment sizing across electro-optical, dual-mode, radar, and infrared product types converged with top-down military modernization budget analysis.
Historical trendline analysis of Sniper and Litening pod production rates established baseline demand patterns across the analysis window. Segmentation modeling incorporated product type, technology modality, application domain, and end-user procurement channel dimensions. CAGRs derived from fitted growth curves applied to sovereign spending trajectories in the United States, Germany, and Israel, with algorithm development investment and directed-energy weapon integration serving as key forecast inputs.
Caveats apply where ITAR modernization implementation delays or mercury cadmium telluride supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding NATO interoperability standard adoption and EU AI Act enforcement timelines. A small set of named triggers—EAR reclassification, Zeitenwende spending authorization shifts, and cleared workforce availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market