
 Tactical Scope Market | 2026-2036
Tactical Scope Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Scope Market Analytics
Law enforcement agencies is rotating toward higher-specification variable optics as military procurement cycles elongate. Trijicon, Inc. leverages its dual-use manufacturing base to serve both defense and civilian channels. Leupold & Stevens, Inc. anchors its position through captive glass production and domestic U.S. forging operations. Nightforce Optics, Inc. specializes in extreme long-range precision platforms that command premium positioning among competitive shooters.
A tactical scope is an optoelectronic sighting device mounted on firearms, combining precision-ground lenses with adjustable reticle illumination and parallax correction to enable accurate target engagement across varying distances and lighting conditions. Fixed-power scopes retain utility in close-quarters military applications where mechanical simplicity reduces failure modes, while thermal and night vision segments capture the fastest expansion as sensor fusion architectures proliferate. The 4-12x magnification band occupies the broadest commercial footprint, spanning designated marksman rifles and hunting platforms where versatility outweighs extreme-range specialization.
ITAR regulations in the United States restrict cross-border transfer of advanced optical systems, fragmenting supplier access and compelling non-U.S. manufacturers to develop independent thermal core technologies. The EU Firearms Directive harmonizes marking and traceability standards across member states, raising compliance costs for importers while creating preference for CE-marked European producers. Schmidt & Bender GmbH & Co. KG navigates these requirements through Bundeswehr certification pathways that validate civilian product lines. Stakeholders must monitor divergence between U.S. export control stringency and European defense procurement autonomy as dual-use classification debates reshape market access rules.
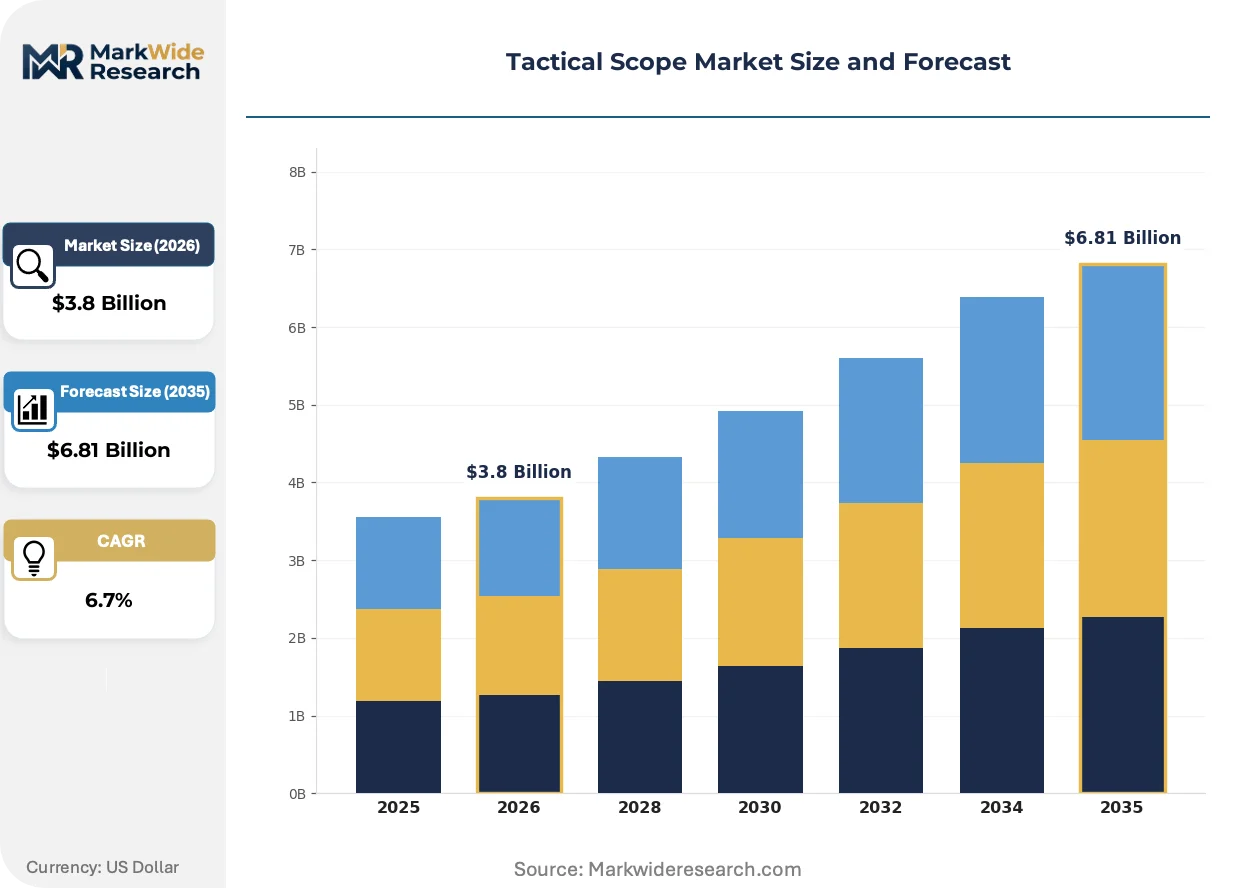
Market Dynamics
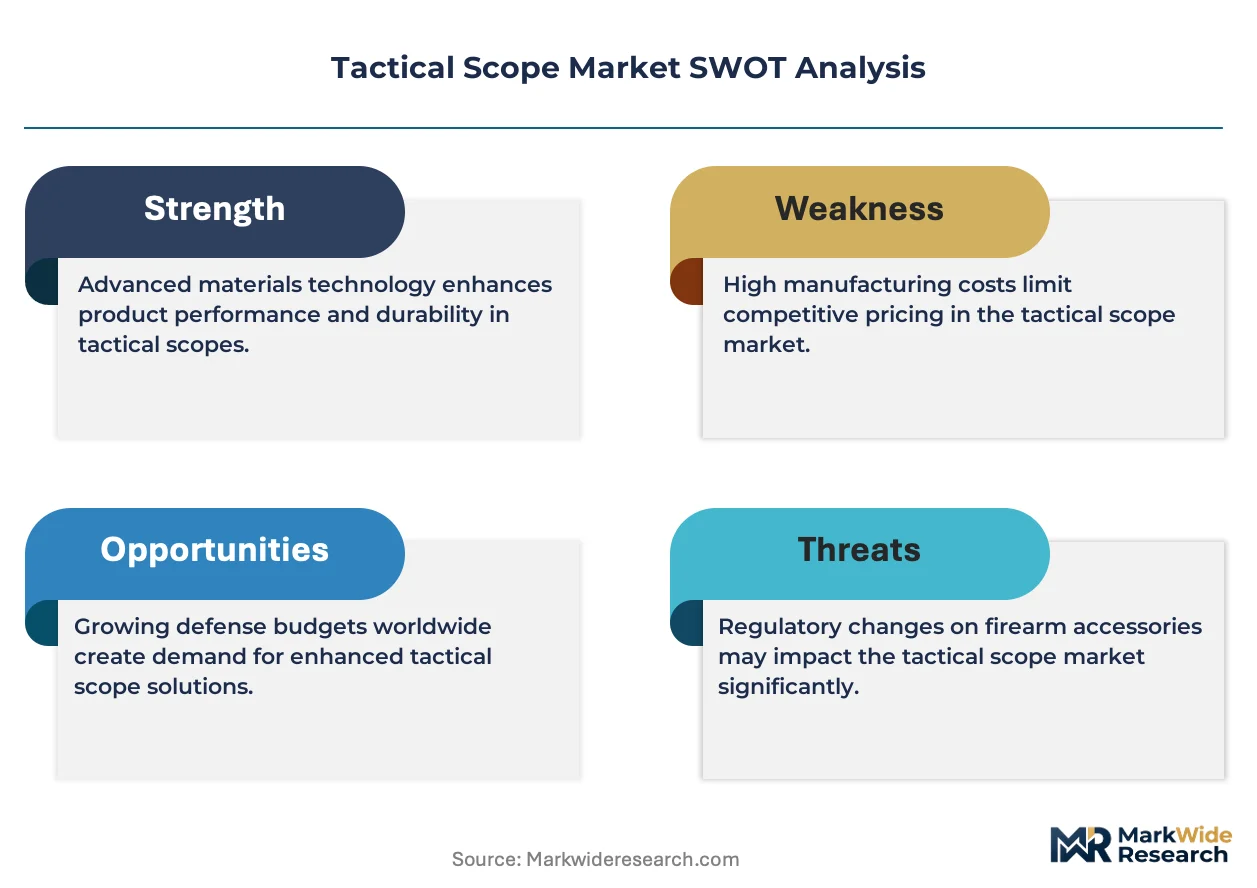
Sensor fusion architectures are compressing procurement cycles as defense agencies demand unified thermal-daylight systems rather than discrete sighting modules. Bundeswehr modernization programs in Germany and parallel U.S. Army next-generation squad weapon initiatives are forcing suppliers to certify multi-spectrum platforms under divergent export control regimes.
Growth Catalysts
- ITAR-controlled thermal core proliferation:U.S. defense procurement is accelerating domestic production of uncooled microbolometers, creating spillover capacity for law enforcement variable optics.
- EU Firearms Directive harmonization:CE-marking requirements are consolidating importer networks, favoring Oberndorf am Neckar precision manufacturing clusters with existing Bundeswehr certification pathways.
- Designated marksman rifle expansion:Military end-users are fielding 4-12x magnification platforms at platoon level, pulling mid-range variable optics into standard issue.
Market Restraints
- Germanium substrate concentration:Thermal lens production depends on Chinese rare earth processing, exposing cost volatility to PRC export quota adjustments.
- ITAR fragmentation:U.S. State Department classification disputes are blocking allied access to advanced reticle illumination systems, forcing redundant European development.
- Fixed-power substitution:Close-quarters military units retain mechanical simplicity preferences, capping variable optic penetration in urban warfare applications.
Strategic Opportunities
- Polish defense procurement autonomy:Warsaw's accelerated NATO interoperability spending is creating demand for non-U.S. thermal cores outside ITAR jurisdiction.
- Sensor fusion convergence:Overlay of ballistic calculators with laser rangefinders is opening premium pricing tiers for integrated fire control ecosystems.
- Direct-to-contractor channels:Bypassing traditional distributor networks, manufacturers are establishing Bundeswehr sole-source agreements that validate civilian product lines.
Industry Challenges
- Optical engineer scarcity:Precision grinding expertise concentrates in Thuringia and Baden-Württemberg, constraining capacity expansion outside established clusters.
- Dual-use certification timelines:ITAR commodity jurisdiction determinations and EU dual-use export authorizations are extending product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Scope Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Variable, Thermal, Night Vision End User: Military, Law Enforcement, Sports Enthusiasts, Hunters Mount Type: Rail, Quick Release, Direct Attach, Clamp Magnification Level: 1-4x, 4-12x, 10-40x, Others |
| Companies Covered | Trijicon, Inc., Leupold & Stevens, Inc., Nightforce Optics, Inc., EOTech, LLC, Vortex Optics, Inc., Sig Sauer, Inc., Elbit Systems Ltd., BAE Systems plc, Schmidt & Bender GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Scope Market Evolving Landscape
Active matrix organic LED microdisplays are redefining reticle presentation, compressing the gap between daylight clarity and low-light performance. Manufacturers are racing to integrate these emitters with existing tube architectures without triggering ITAR reclassification.
Uncooled vanadium oxide microbolometers are displacing legacy cooled indium antimonide detectors in thermal clip-on systems. U.S. Army PEO Soldier is fielding these platforms at squad level, compressing unit costs and forcing premium European suppliers to match price-performance ratios or retreat to extreme long-range niches.
EU Firearms Directive Article 5 traceability mandates are restructuring importer liability frameworks. CE-marked producers now bear serialized component tracking obligations, raising compliance costs for Asian contract manufacturers while validating vertically integrated Oberndorf operations with existing Bundeswehr audit trails.
Law enforcement agencies are consolidating procurement through state-level cooperative purchasing agreements. California POST and Texas Commission on Law Enforcement are negotiating multi-year variable optics frameworks, displacing municipal-level fragmented buying and compressing distributor margins while favoring manufacturers with domestic U.S. forging and glass production.
Tactical Scope Market Segmentation
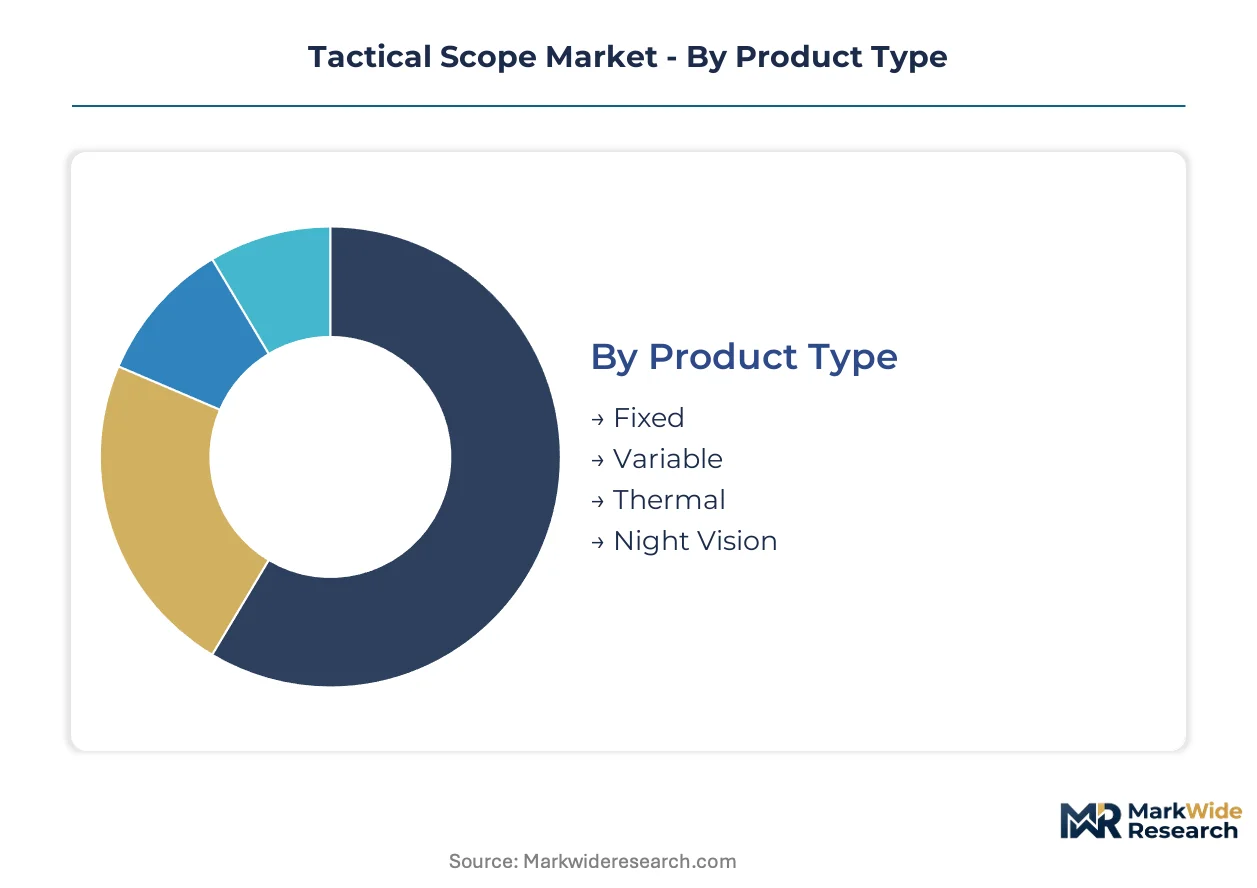
Tactical scope segmentation reveals divergent margin structures across optical architectures and end-use certifications. Product type and magnification level concentrate premium pricing power, while mount type and end user categories fragment procurement channels and compliance burdens.
Product Type:
Margin pools concentrate in thermal and night vision segments where sensor fusion architectures command five-figure unit pricing, while variable optics capture volume-driven aftermarket replacement cycles.
- Variable:Adjustable magnification optics spanning 1-8x to 6-24x configurations dominate law enforcement procurement through California POST and Texas Commission on Law Enforcement cooperative purchasing agreements. Military designated marksman rifle programs at platoon level are pulling 4-12x platforms into standard issue, compressing replacement cycles.
- Thermal:Uncooled vanadium oxide microbolometer clip-on systems are displacing legacy cooled indium antimonide detectors in U.S. Army PEO Soldier fielding at squad level. ITAR-controlled thermal core proliferation is accelerating domestic U.S. production capacity with spillover into law enforcement channels.
- Fixed:Mechanical simplicity retains utility in close-quarters military applications where failure mode reduction outweighs optical versatility.
- Night Vision:Image intensifier tube architectures face pricing pressure from thermal convergence but maintain dominance in pilot and vehicle crew applications.
The dominant share belongs to Variable, while Thermal is closing the gap fastest.
End User:
Volume concentration shifts toward law enforcement as military procurement cycles elongate and state-level cooperative purchasing consolidates fragmented municipal buying.
- Law Enforcement:State-level cooperative purchasing agreements in California and Texas are displacing municipal-level fragmented procurement, compressing distributor margins while validating manufacturers with domestic U.S. forging and glass production. Variable optics rotation toward higher-specification platforms is accelerating as agency budgets shift from firearms to sighting systems.
- Military:Bundeswehr modernization programs and parallel U.S. Army next-generation squad weapon initiatives are forcing multi-spectrum platform certification under divergent ITAR and EU dual-use regimes. Sensor fusion architectures are compressing procurement cycles toward unified thermal-daylight systems.
- Hunters:The 4-12x magnification band occupies the broadest commercial footprint where versatility outweighs extreme-range specialization.
- Sports Enthusiasts:Competitive shooting disciplines drive premium positioning for extreme long-range precision platforms with integrated ballistic calculators.
Military retains the largest installed base, though Law Enforcement is expanding procurement most rapidly.
Mount Type:
Precision manufacturing clusters around Oberndorf am Neckar concentrate quick release mechanism production, while rail mount standardization fragments across NATO STANAG and proprietary commercial patterns.
- Rail:NATO STANAG 4694 and MIL-STD-1913 Picatinny patterns dominate military procurement, though commercial KeyMod and M-LOK slot systems fragment aftermarket demand.
- Quick Release:Bundeswehr-certified lever mechanisms from Oberndorf precision manufacturing clusters command premium positioning through dual-use civilian-military validation pathways.
- Direct Attach:Integral receiver mounting eliminates interface tolerance stack-up for extreme long-range precision applications.
- Clamp:Barrel and receiver clamp configurations retain niche utility in legacy platform retrofits and non-standard firearm architectures.
Rail configurations hold the dominant position, yet Quick Release is gaining share fastest through law enforcement duty-grade specifications.
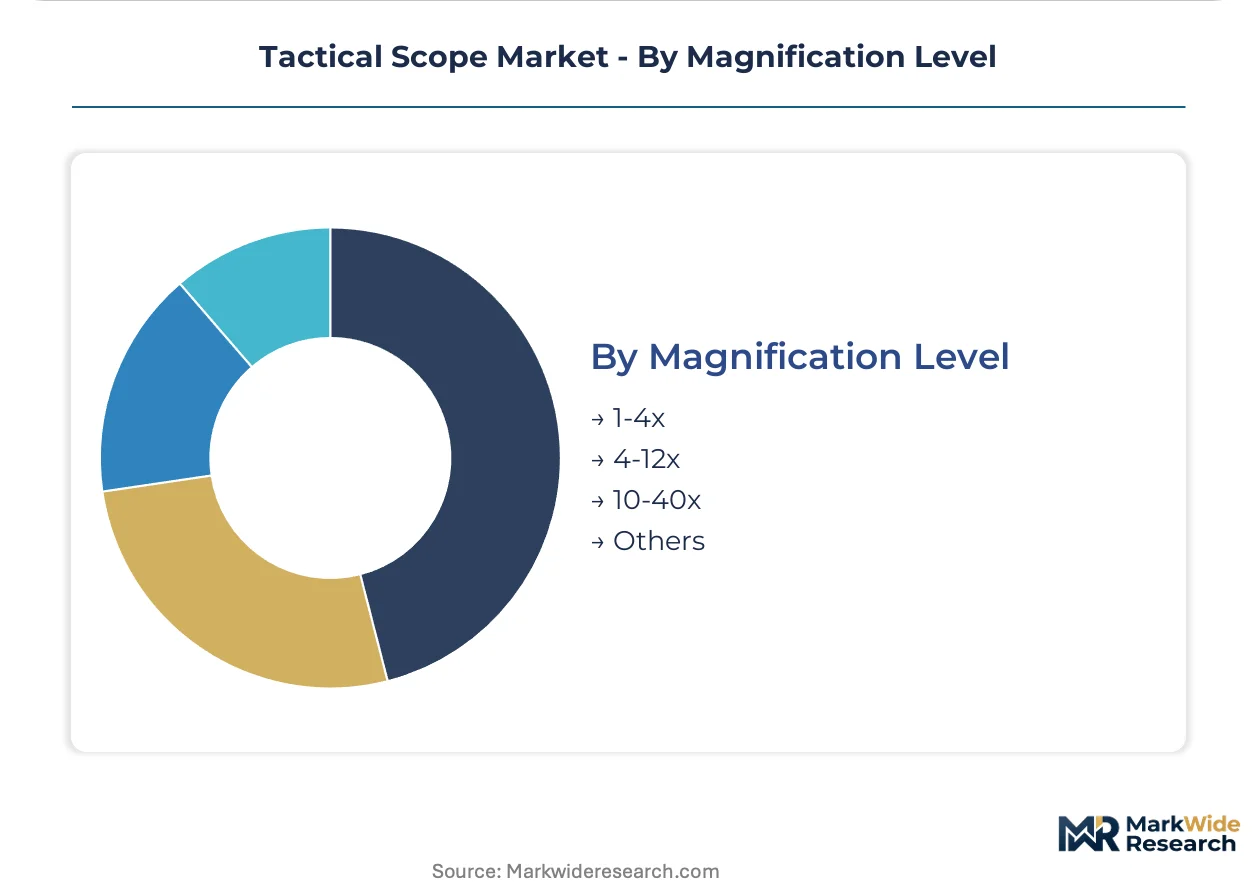
Magnification Level:
Application-driven tiering separates close-quarters mechanical simplicity from extreme long-range sensor fusion integration, with mid-range versatility capturing broadest commercial penetration.
- 4-12x:The broadest commercial footprint spans designated marksman rifles and hunting platforms where versatility outweighs extreme-range specialization. Military end-users are fielding these platforms at platoon level, pulling mid-range variable optics into standard issue and compressing procurement timelines.
- 1-4x:Low-power variable optics bridge close-quarters speed with precision engagement to 300 meters, dominating urban warfare and competitive multi-gun applications.
- 10-40x:Extreme long-range precision platforms command premium positioning among competitive shooters and specialized military sniper applications.
- Others:Fixed 10x and 25x benchrest configurations retain dedicated followings in F-Class and benchrest competition disciplines.
The 4-12x band commands the dominant share, while 1-4x platforms are climbing fastest through law enforcement patrol rifle adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing clusters in southern Germany concentrate high-end optical grinding expertise, while U.S. defense procurement drives thermal core development. Regulatory divergence between ITAR-controlled American exports and EU defense autonomy is fragmenting supplier access across national boundaries.
United States
Domestic defense procurement accelerates uncooled microbolometer production with spillover into law enforcement channels. ITAR export controls administered by the U.S. State Department block allied access to advanced reticle illumination, fragmenting supplier networks. Oregon and Arizona host precision forging and glass production operations serving California POST cooperative purchasing agreements.
Germany
Bundeswehr modernization programs pull 4-12x variable optics into standard platoon-level issue, compressing procurement timelines. The EU Firearms Directive harmonizes CE-marking requirements that validate Oberndorf am Neckar manufacturing clusters through existing military certification pathways. Thuringia and Baden-Württemberg concentrate optical engineer expertise for precision grinding operations.
Poland
Accelerated NATO interoperability spending creates demand for thermal cores outside ITAR jurisdiction. The country's national defense procurement agency prioritizes non-U.S. sensor fusion architectures for next-generation squad weapons. Warsaw and Łódź industrial zones attract European optic manufacturers seeking EU-only supply chains.
Israel
Defense export autonomy supports independent thermal core development for Middle Eastern and Asian markets. The national defense regulator maintains parallel certification frameworks outside both ITAR and EU dual-use regimes. Tel Aviv and Haifa metropolitan areas concentrate electro-optics engineering talent for sensor fusion integration.
United Kingdom
Specialized sniper platform requirements sustain demand for extreme long-range precision optics. Ministry of Defence procurement operates under divergent export control interpretations post-Brexit, complicating transatlantic supplier access. Midlands and South East England retain precision engineering capabilities for military optical systems.
Tactical Scope Market Competitive Landscape
Concentration sits with dual-use manufacturers possessing captive defense certification pathways. The vendor base stratifies across three tiers: Bundeswehr-validated European specialists, ITAR-cleared U.S. defense contractors, and Asian contract assemblers facing CE-marking compliance barriers. Strategic moves center on backward integration into thermal core production and sole-source military agreements that validate civilian product lines.
Within the defense-contractor tier, Trijicon, Inc. and Leupold & Stevens, Inc. represent U.S.-based archetypes with domestic forging and glass production capabilities. Schmidt & Bender GmbH & Co. KG exemplifies the European specialist model leveraging Oberndorf precision manufacturing clusters. Nightforce Optics, Inc. occupies a position among extreme long-range precision specialists serving competitive shooting and specialized military applications.
| Leading Market Players |
|---|
| Trijicon, Inc. |
| Leupold & Stevens, Inc. |
| Nightforce Optics, Inc. |
| EOTech, LLC |
| Vortex Optics, Inc. |
| Sig Sauer, Inc. |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Schmidt & Bender GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month dual-use certification timelines concentrate pricing power with incumbent manufacturers possessing established Bundeswehr and ITAR validation pathways. This lead-time compression favors Oberndorf am Neckar precision clusters and domestic U.S. forging operations while forcing Asian contract assemblers into economy-tier positioning.
Pricing Analysis
ITAR commodity jurisdiction determinations dictate the pricing tier structure across the tactical scope market. Three-tier pricing structure across premium, standard, and economy levels separates Bundeswehr-certified sensor fusion platforms from law enforcement variable optics and Asian contract-manufactured fixed-power alternatives. Price differentiation rests on certification grade and captive thermal core production. Cost compression in standard-tier variable optics is intensifying because uncooled vanadium oxide microbolometer proliferation erodes premium thermal positioning. Law enforcement procurement through California POST cooperative agreements exhibits highest price sensitivity, while military sensor fusion programs demonstrate lowest sensitivity due to sole-source validation requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose germanium substrate dependencies to Chinese rare earth processing quota volatility. Optical engineer expertise concentrates in Germany, the United States, and Israel, with precision grinding operations anchored in Thuringia and Baden-Württemberg. Raw material inputs draw from germanium substrates, precision-ground optical glass, and uncooled microbolometer cores. Single-source vulnerability in Chinese rare earth processing creates structural supply risk. Distribution runs through Bundeswehr sole-source agreements and state-level law enforcement cooperative purchasing frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor fusion architecture convergence is transforming tactical optics from discrete component procurement into integrated fire control platform economics. Interoperability demands between thermal-daylight systems and ballistic calculator overlay are consolidating vendor ecosystems around certified dual-use manufacturers.
For Market Incumbents: Shield market position through backward integration into uncooled thermal core production and accelerated Bundeswehr certification pathway investment. Emerging Polish defense procurement autonomy and Warsaw's NATO interoperability spending threaten established ITAR-cleared supplier access. Captive vanadium oxide microbolometer fabrication and Oberndorf precision manufacturing cluster expansion represent priority defensive levers.
For New Entrants and Emerging Players: Differentiate on non-ITAR thermal core architectures for Polish and broader European defense procurement. The most penetrable white-space sits in 4-12x variable optics for law enforcement patrol rifle adoption outside established cooperative purchasing agreements. Target direct-to-contractor channels bypassing traditional distributor networks through CE-marking compliance investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates seeking to divest non-core electro-optics divisions amid sensor fusion consolidation. Long-term viability favors vertically integrated manufacturers with captive glass production and established military certification pathways. Watch divergence between U.S. State Department export control stringency and European defense procurement autonomy as inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Core Backward Integration | Captive vanadium oxide microbolometer production insulates margins from Chinese germanium substrate volatility. |
| Bundeswehr Sole-Source Agreement | Military certification validates civilian product lines through dual-use pathway convergence. |
| Sensor Fusion Platform Development | Integrated thermal-daylight-overlay systems command premium positioning in next-generation squad weapons. |
| CE-Marking Compliance Investment | EU Firearms Directive traceability mandates raise barriers against Asian contract manufacturers. |
| Direct-to-Contractor Channel Establishment | Bypassing distributor networks captures margin compression from state-level cooperative purchasing consolidation. |
Research Methodology
A standing panel of defense procurement officers, optical systems engineers, law enforcement firearms instructors, and thermal imaging specialists provided ongoing calibration throughout primary fieldwork. This practitioner input combined with secondary validation from U.S. Army PEO Soldier fielding disclosures, EU Firearms Directive implementation guidance, Bundeswehr modernization program documentation, and customs trade data for precision optical components. Bottom-up unit shipment modeling across magnification bands and thermal-night vision segments triangulated against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, magnification level, mount configuration, and end-user certification tier as primary segmentation dimensions. CAGRs derived from shipment trajectory analysis and pricing band migration patterns incorporated ITAR-controlled thermal core proliferation rates and designated marksman rifle fielding schedules as industry-specific forecast inputs.
Material uncertainties — regulatory reclassification of sensor fusion architectures, Chinese rare earth export quota adjustments, and Bundeswehr procurement timeline acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around continued ITAR-EU dual-use regime divergence and law enforcement budget rotation toward sighting systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Global Radar Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Global Airborne Warning and Control System Market