
 Missile Seeker Detector Market | 2026-2036
Missile Seeker Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Missile Seeker Detector Market Insights
AS9100D aerospace quality certification is bifurcating the supplier landscape into qualified primes and aspirant subsystem vendors. Raytheon Technologies leverages captive semiconductor foundry access to sustain imaging infrared detector output for tactical missile programs. Northrop Grumman Corporation anchors US naval combat seeker supply through long-running shipboard radar programs. BAE Systems competes across European electro-optical seeker bids with sovereign UK supply chain credentials.
A missile seeker detector converts electromagnetic radiation into discriminable electrical signals that guidance computers process for target tracking, typically operating across infrared wavelengths from one to fourteen micrometers or radar bands from X through Ku. These detectors employ mercury cadmium telluride focal plane arrays or indium antimonide photodiodes cooled by sterling engines to achieve the sensitivity required for beyond-visual-range engagements. Infrared seeker demand leads product type revenue owing to passive tracking advantages in contested electromagnetic environments, while multi-sensor fusion technology commands premium positioning as forces integrate ultraviolet detection with imaging infrared for countermeasure resistance. Electro-optical seeker applications in ground surveillance mature slowly with stable replacement cycles, whereas tactical missile guidance drives fastest growth as loitering munitions proliferate.
The US Department of Defense enforces MIL-STD-810H environmental qualification and ITAR export controls that restrict foreign access to focal plane array technology, while NATO STANAG standards harmonize interoperability requirements across allied defense procurement. The EU Green Deal's fluorinated gas restrictions indirectly pressure cooling system design for European-sourced detectors. Stakeholders must monitor divergence between US ITAR-controlled supply and European sovereignty initiatives as France, Germany, and Italy accelerate domestic seeker manufacturing capacity.
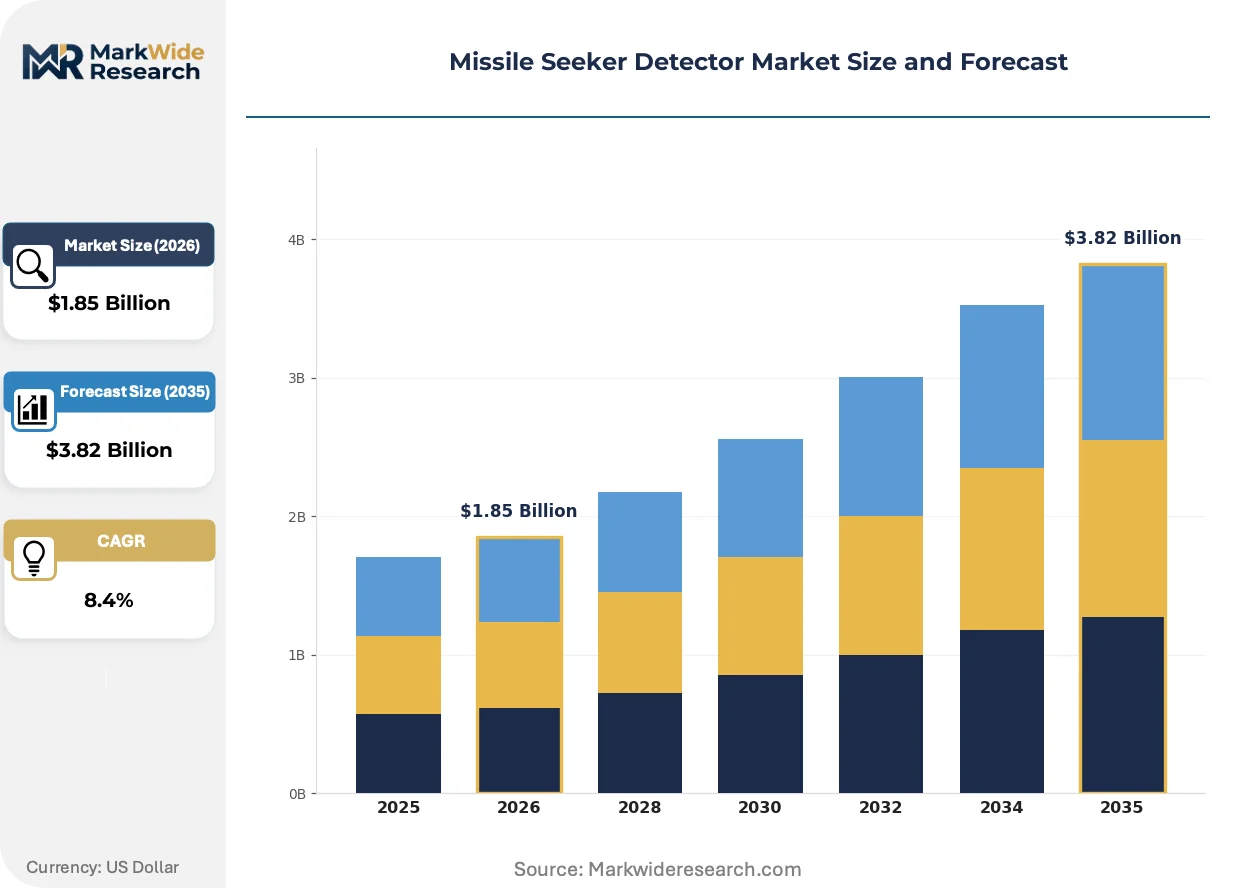
Market Dynamics
Layered air defense modernization across NATO member states is compressing qualification timelines for focal plane array suppliers, while US ITAR controls and European sovereignty initiatives create divergent sourcing requirements for mercury cadmium telluride detectors.
Growth Catalysts
- MIL-STD-810H Environmental Testing:The US Department of Defense's updated qualification requirements accelerate new entrant validation cycles for tactical missile programs.
- Loitering Munition Proliferation:Tactical missile guidance applications drive fastest demand expansion as armed forces field expendable precision strike systems.
- Multi-Sensor Fusion:Integration of ultraviolet detection with imaging infrared creates countermeasure-resistant seekers commanding premium positioning.
Market Restraints
- Mercury Cadmium Telluride Supply Concentration:US-based semiconductor foundries dominate high-performance focal plane array substrate production under ITAR restriction.
- Sterling Engine Cooling Costs:Cryogenic cooling systems for indium antimonide photodiodes impose recurring maintenance burdens on operational budgets.
- EU F-Gas Regulation:The European Union's fluorinated gas restrictions pressure cooling system redesign for continental defense procurement.
Strategic Opportunities
- AS9100D Certification Gap:Uncertified subsystem vendors face exclusion from prime contractor supply chains, creating acquisition targets for qualified players.
- Naval Combat Seeker Modernization:Shipboard radar program refresh cycles offer entry points for electro-optical detector suppliers.
- Indo-Pacific Theater Positioning:Sovereign manufacturing initiatives in France, Germany, and Italy seek domestic focal plane array capability.
Industry Challenges
- ITAR Compliance Talent Scarcity:Export-controlled technology handling requires cleared personnel pools that defense contractors struggle to staff.
- Dual-Use Classification Complexity:Civilian infrared applications trigger licensing review delays that extend program schedules.
- Legacy System Integration:New detector formats must interface with existing guidance computer architectures without full platform redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missile Seeker Detector Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Seeker, Infrared Seeker, Electro-Optical Seeker, Laser Seeker, Passive Seeker Technology: Active Radar, Imaging Infrared, Semi-Active Laser, Ultraviolet Detection, Multi-Sensor Fusion Application: Air Defense Systems, Naval Combat, Ground Surveillance, Tactical Missile Guidance, Electronic Warfare End User: Defense Forces, Security Agencies, Missile Manufacturers, Aerospace Contractors, Research Labs |
| Companies Covered | Raytheon Technologies, Northrop Grumman Corporation, Leonardo S.p.A., BAE Systems, L3Harris Technologies, Inc., Thales, Safran, ASELSAN A.S., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missile Seeker Detector Market Trends and Innovations
Detector technology evolution is fragmenting along cooling methodology lines while regulatory divergence between US and European frameworks forces parallel qualification tracks. Procurement behavior is compressing as defense primes consolidate supplier bases.
Mercury cadmium telluride focal plane array technology is fragmenting the competitive landscape between cooled and uncooled detector architectures. Tactical missile primes are adopting Type-II superlattice alternatives for reduced logistics burden. This technology diffusion is fragmenting established supply relationships as primes qualify second-source indium antimonide vendors.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing Sterling engine cooling system redesigns for European defense procurement. Detector suppliers must validate alternative cryogenic approaches or absorb compliance engineering costs. Naval surface combatant programs in France and Germany face extended qualification schedules as cooling architectures adapt.
Defense procurement consolidation is compressing supplier qualification cycles as primes reduce approved vendor lists. Long-term framework agreements are displacing transactional purchasing for focal plane array supply. The United States exhibits most pronounced concentration, with congressional appropriations tied to domestic content requirements.
Missile Seeker Detector Market Segmentation
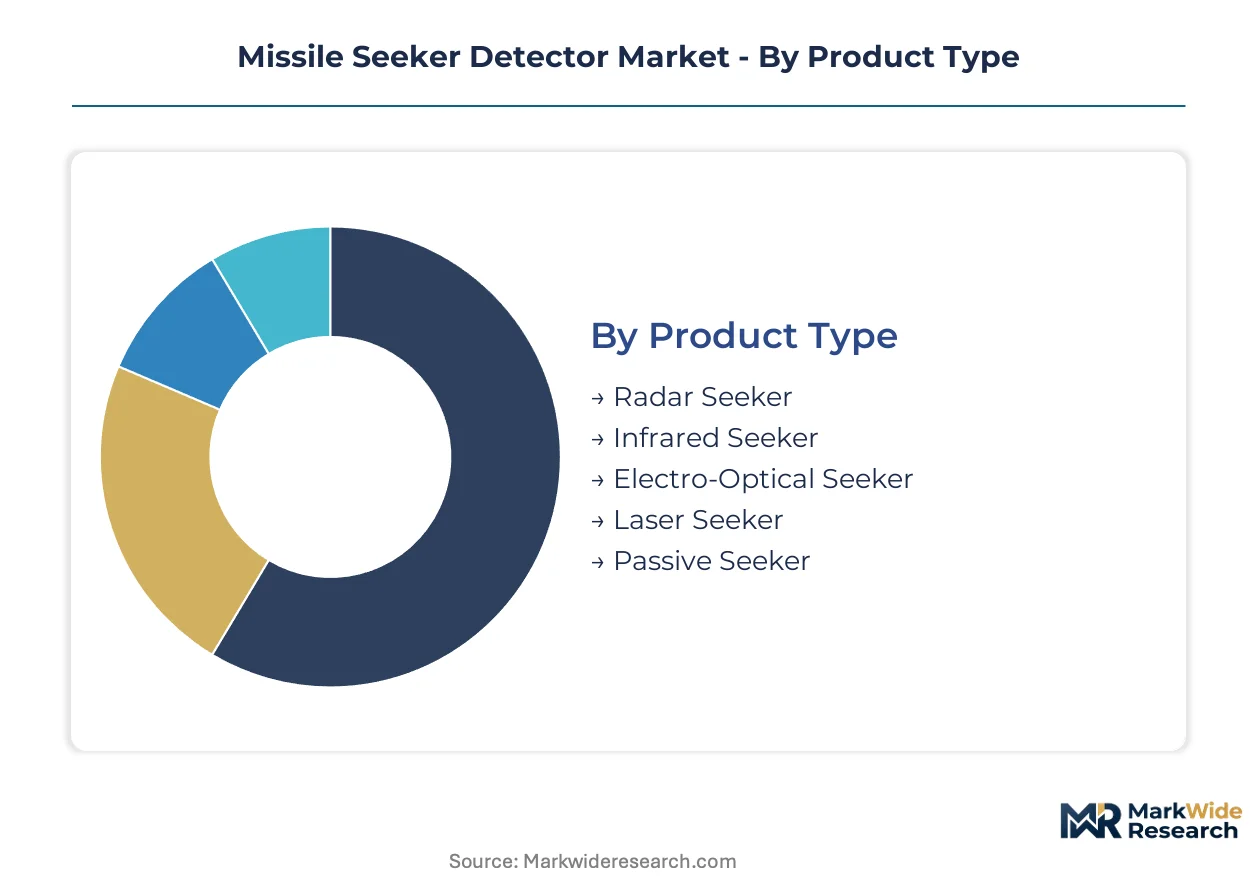
Segmentation in missile seeker detectors reveals divergent margin structures across cooling architectures and qualification tiers. Procurement concentration in tactical missile programs creates asymmetric returns between infrared focal plane arrays and legacy radar seekers.
Product Type:
Margin pools concentrate in cooled infrared architectures where ITAR-controlled substrate access limits supplier entry.
- Infrared Seeker:Mercury cadmium telluride focal plane arrays and indium antimonide photodiodes deliver passive tracking capability for beyond-visual-range engagements. NATO layered air defense modernization concentrates procurement in cooled imaging infrared detectors with sterling engine cryogenics.
- Radar Seeker:Active and semi-active radar seekers operate across X through Ku bands for all-weather target acquisition. US naval combat programs sustain demand for shipboard radar seekers with multi-target tracking firmware.
- Electro-Optical Seeker:Visible and near-infrared sensors support ground surveillance with stable replacement cycles in legacy platforms.
- Laser Seeker:Semi-active laser guidance enables precision strike against designated targets with compact detector footprints.
- Passive Seeker:Emissions-free detection systems reduce platform signature for survivability in contested electromagnetic environments.
Infrared Seeker holds installed capacity. Passive Seeker is rotating up the share rankings.
Technology:
Application intensity varies sharply between mature radar architectures and emerging multi-sensor fusion platforms commanding premium positioning.
- Multi-Sensor Fusion:Integration of ultraviolet detection with imaging infrared creates countermeasure-resistant seekers for contested environments. Congressional appropriations for next-generation seekers concentrate procurement in fused-sensor architectures.
- Imaging Infrared:Staring focal plane arrays provide high-resolution thermal imagery for target discrimination at extended ranges. Raytheon Technologies leverages captive semiconductor foundry access to sustain output for tactical missile programs.
- Active Radar:Transmit-receive modules enable autonomous target acquisition without external illumination sources.
- Semi-Active Laser:Laser spot tracking receivers guide precision munitions with minimal onboard complexity.
- Ultraviolet Detection:Solar-blind sensors discriminate missile exhaust plumes against cluttered backgrounds.
Imaging Infrared holds installed capacity. Multi-Sensor Fusion is climbing the fastest.
Application:
Volume concentration follows divergent procurement cycles between expeditionary tactical systems and stationary air defense networks.
- Tactical Missile Guidance:Loitering munitions and precision strike systems demand compact, expendable-grade detectors with reduced logistics burden. Loitering munition proliferation drives fastest demand expansion across NATO member states.
- Air Defense Systems:Layered architectures integrate short-range and medium-range interceptors with complementary seeker technologies. Northrop Grumman Corporation anchors supply through long-running shipboard radar programs.
- Naval Combat:Shipboard missile systems require salt-spray hardened detectors with MIL-STD-810H environmental qualification.
- Ground Surveillance:Electro-optical targeting pods mature slowly with stable replacement cycles in armored vehicle programs.
- Electronic Warfare:Threat warning receivers employ broadband detectors for emitter identification and geolocation.
Air Defense Systems holds installed capacity. Tactical Missile Guidance is gaining share fastest.
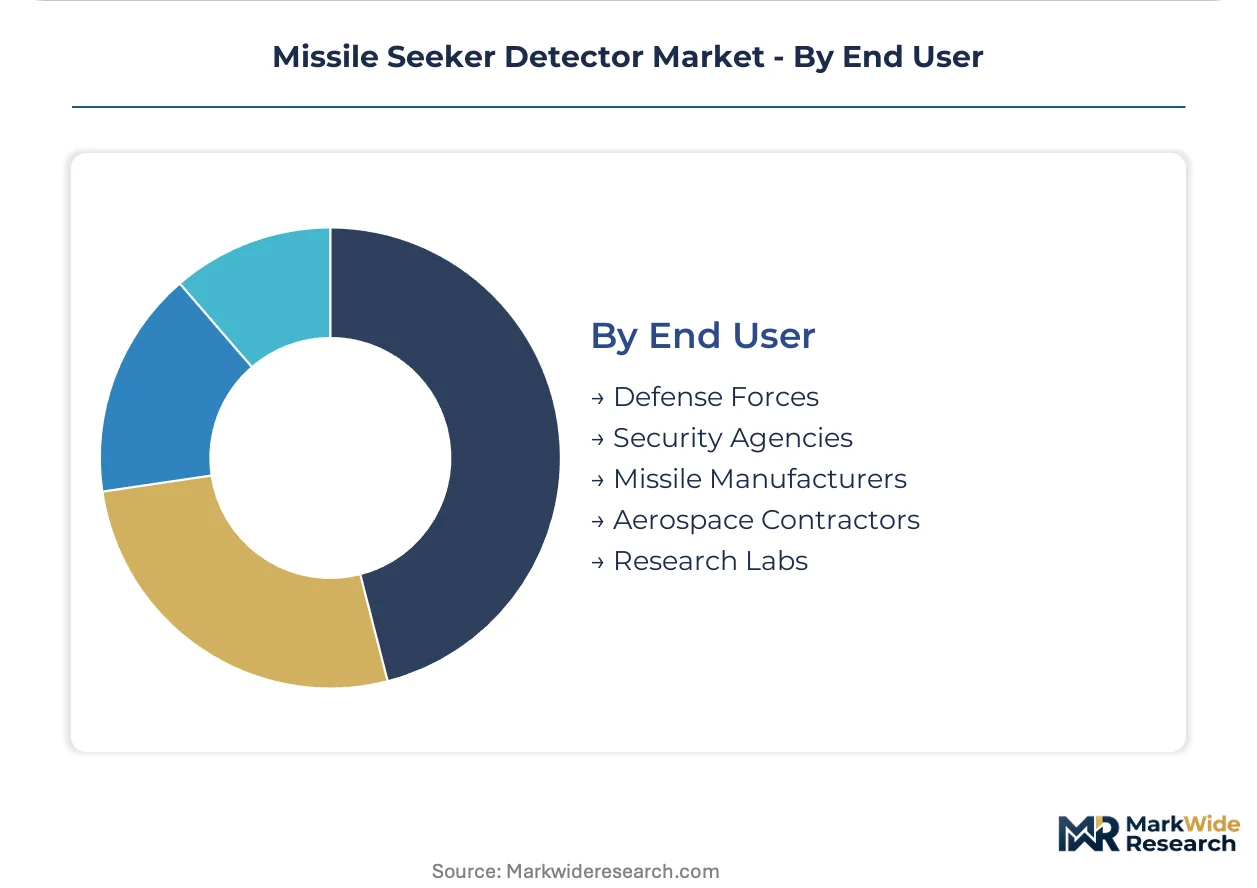
End User:
Customer concentration reflects divergent technical specifications between operational defense forces and subsystem integrators.
- Defense Forces:National military procurement drives volume demand with sovereign content requirements and ITAR compliance mandates. The US Department of Defense's MIL-STD-810H requirements accelerate qualification cycles for new detector entrants.
- Missile Manufacturers:Prime contractors consolidate supplier bases through AS9100D-certified long-term framework agreements.
- Aerospace Contractors:Platform integrators specify detector interfaces for guidance computer architectures.
- Security Agencies:Border surveillance and counter-drone applications employ adapted seeker technologies.
- Research Labs:National laboratories develop advanced focal plane array substrates under government contract.
Defense Forces holds installed capacity. Missile Manufacturers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Congressional appropriations for next-generation seekers and NATO layered air defense modernization are redirecting procurement flows toward domestic manufacturing hubs. Sovereign content requirements and ITAR export controls are fragmenting supply chain geography across major defense economies.
United States
Modernization of tactical missile guidance systems and loitering munition procurement drive detector demand. The Department of Defense enforces MIL-STD-810H environmental qualification and ITAR controls that restrict foreign access to focal plane array technology. Arizona and Massachusetts host concentrated prime contractor operations for imaging infrared production.
France
Sovereign manufacturing initiatives accelerate domestic focal plane array capability for naval combat seekers. The EU Green Deal's fluorinated gas restrictions pressure cooling system redesign for defense procurement. Paris and Toulouse anchor electro-optical research clusters developing countermeasure-resistant multi-sensor architectures.
Germany
Layered air defense architectures integrate short-range and medium-range interceptors with complementary seeker technologies. EU F-Gas Regulation compliance extends qualification schedules for Sterling engine cooling adaptations. Bavaria and Baden-Württemberg concentrate subsystem vendor operations serving European missile programs.
United Kingdom
Sovereign supply chain credentials support competitive positioning across European electro-optical seeker bids. AS9100D aerospace quality certification bifurcates qualified primes from aspirant subsystem vendors. Stevenage and Bristol house established detector integration facilities for tactical missile guidance.
Italy
Domestic focal plane array manufacturing capacity expansion responds to NATO interoperability requirements under STANAG standards. Congressional-equivalent defense appropriations in Rome prioritize infrared seeker procurement for expeditionary forces. Lombardy and Lazio regions develop electro-optical component supply bases.
Missile Seeker Detector Market Competitive Landscape
Player mix skews toward vertically integrated defense primes with captive semiconductor foundry access. The supplier landscape bifurcates sharply between AS9100D-certified primes and uncertified aspirants. Strategic archetypes include captive foundry operators, long-running naval program anchors, and sovereign supply chain specialists. Competitive moves concentrate on second-source vendor qualification and framework agreement consolidation.
Among US-based primes, Raytheon Technologies and Northrop Grumman Corporation exemplify divergent positioning strategies. Raytheon Technologies occupies the captive foundry archetype with sustained imaging infrared output for tactical missile programs. Northrop Grumman Corporation anchors the naval combat segment through shipboard radar program continuity. BAE Systems represents the sovereign credential specialist competing across European bids with UK supply chain verification.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| BAE Systems |
| L3Harris Technologies, Inc. |
| Thales |
| Safran |
| ASELSAN A.S. |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at ITAR-controlled semiconductor foundries in the United States determines price floors for mercury cadmium telluride focal plane arrays, concentrating supply-side leverage among qualified primes while compressing margins for aspirant subsystem vendors seeking AS9100D certification.
Pricing Analysis
Certification level (AS9100D aerospace quality standard) creates the primary spread between qualified primes and uncertified aspirants. The market operates on long-term framework agreements with transactional spot purchasing for emergency requirements. Price differentiation hinges on ITAR compliance tier and captive foundry access, with US domestic content mandates from congressional appropriations intensifying cost compression for foreign-sourced alternatives. Defense forces exhibit lowest price sensitivity due to sovereign content requirements, while security agencies and research labs face budget constraints that elevate price sensitivity.
Supply Chain Analysis
Strategic stockpiling of mercury cadmium telluride substrates and indium antimonide wafers dominates inventory strategy as primes buffer against ITAR-controlled supply interruptions. Geographic supply concentration centers on the United States, France, and Germany, with raw material dependencies on tellurium, cadmium, and indium feedstocks. Single-source vulnerability at US-based semiconductor foundries poses structural risk given export control restrictions. Distribution runs through prime contractor integration facilities rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Type-II superlattice detector alternatives threaten incumbent mercury cadmium telluride architectures by offering reduced logistics burden without cryogenic cooling, forcing established suppliers to defend substitution risk through performance differentiation.
For Market Incumbents: Fortify captive foundry capacity in Arizona and Massachusetts to maintain ITAR-controlled substrate supply advantage against emerging Type-II superlattice vendors. Deepen backward integration into tellurium refining to secure raw material access as congressional domestic content requirements tighten. Certification investment in EU F-Gas-compliant cooling architectures defends European procurement access against regulatory exclusion. For New Entrants and Emerging Players: Aftermarket service gaps in Sterling engine cooling maintenance for legacy indium antimonide detectors present accessible entry points where primes under-serve operational support contracts. Target naval combat seeker modernization programs in France and Germany as the most penetrable segment given extended qualification schedules and second-source vendor demand. Pursue qualification partnerships with established aerospace contractors rather than direct prime competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AS9100D-certified subsystem vendors with long-term framework agreements tied to tactical missile program cycles. Five-to-ten year viability favors suppliers with dual US-European regulatory compliance pathways rather than single-jurisdiction exposure. Monitor divergence between US ITAR enforcement and European sovereignty initiatives as the critical inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Qualifies subsystem vendors for prime contractor framework agreements under US Department of Defense sourcing mandates. |
| EU F-Gas Cooling Redesign | Enables European defense procurement access as fluorinated gas restrictions pressure Sterling engine alternatives. |
| Second-Source Vendor Qualification | Reduces single-source dependency for mercury cadmium telluride focal plane arrays in tactical missile programs. |
| Type-II Superlattice Adoption | Addresses logistics burden reduction demand from loitering munition proliferation across NATO member states. |
| Domestic Foundry Capacity Expansion | Aligns with congressional appropriations requiring ITAR-controlled domestic content for next-generation seekers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of US Department of Defense procurement databases, NATO STANAG documentation, and EU regulatory filings. Primary interviews engaged missile program managers, focal plane array engineering directors, defense procurement officers, and Sterling engine cooling system specialists. Secondary sources included congressional appropriations records, ITAR compliance guidance, and aerospace contractor SEC filings. Bottom-up unit demand modeling triangulates against top-down defense budget allocation analysis.
Segmentation dimensions modeled span seeker type (infrared, radar, electro-optical, laser, passive), cooling architecture (cooled versus uncooled), application intensity (tactical missile guidance, air defense, naval combat), and end-user procurement tier (defense forces, prime contractors, subsystem integrators). CAGRs derive from installed base replacement cycles, modernization program timelines, and technology substitution elasticities. Forecast inputs incorporate loitering munition procurement trajectories and layered air defense architecture deployment schedules.
Forecasts assume regulatory continuity in US ITAR export controls and EU F-Gas restrictions; material policy shifts would require re-modeling. Technology disruption from Type-II superlattice maturation or quantum detector emergence could accelerate substitution beyond baseline projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
UXO Detection Market
Military Surveillance
Global Radar Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Drone Surveillance Platform Market