
 Manportable Surveillance and Target Acquisition Radar Market | 2026-2036
Manportable Surveillance and Target Acquisition Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Manportable Surveillance and Target Acquisition Radar Market Insights
Defense procurement channels is rewriting how manportable radar systems reach end users, with national security agencies now favoring direct vendor contracts over layered distributor networks. FLIR Systems leverages its thermal-imaging heritage to bundle multi-sensor packages that reduce integration costs for military buyers. ASELSAN anchors its competitive stance through captive manufacturing in Turkey, controlling component supply for NATO-compatible units. Thales Group competes across European defense frameworks with software-defined architectures that ease field upgrades.
Manportable surveillance and target acquisition radar denotes compact, soldier-transportable sensor systems operating in X-band or Ku-band frequencies with detection ranges from hundreds of meters to over ten kilometers, designed to detect, track, and designate ground or low-altitude aerial targets for fire control or intelligence fusion. Pulse-Doppler technology dominates current military procurements due to its clutter rejection in complex terrain, while phased-array variants represent the fastest-growing segment as gallium-nitride transmit-receive modules shrink weight and power budgets for dismounted operations. Homeland security agencies now drive parallel demand for portable counter-UAV radar configurations at border checkpoints, creating a secondary margin pool distinct from traditional military channels.
FAA coordination requirements shape domestic airspace integration tests for counter-drone radar deployments in the United States, while ITAR regulations govern export licensing for all U.S.-origin transmitters and signal processors. European Union member states reference CE marking and specific national defense procurement codes when qualifying manportable systems for joint rapid-response units. Stakeholders must monitor evolving spectrum allocation decisions by national regulators, as 5G expansion and radar operations increasingly contest identical frequency bands near urban perimeters.
Market Dynamics
Gallium-nitride transmit-receive modules are compressing weight and power budgets for dismounted radar operations, forcing incumbents to redesign thermal management architectures and triggering qualification delays for legacy silicon-based suppliers.
Growth Catalysts
- Counter-UAV mission expansion:Homeland security agencies at border checkpoints in the United States now mandate portable radar configurations, creating procurement velocity distinct from military channels.
- REACH substance restrictions:European defense procurement codes now reference hazardous material exclusions, accelerating supplier transitions to lead-free solder and compliant substrate materials.
- ITAR license streamlining:The United States has established expedited pathways for NATO member nations, reducing vendor qualification timelines for allied infantry modernization programs.
Market Restraints
- GaN substrate supply concentration:Epitaxial wafer production clusters in Japan and the United States create chokepoints for transmit-receive module fabrication.
- FAA airspace coordination:Domestic counter-drone radar deployments in the United States require multi-agency clearance, extending field trial durations.
- Phased-array cost premiums:Active electronically scanned arrays carry three to four times the unit cost of mechanically scanned alternatives, constraining procurement volumes for dismounted formations.
Strategic Opportunities
- Software-defined architectures:Field-programmable gate arrays and open standards enable post-deployment waveform upgrades, extending platform service life for European rapid-response units.
- Indo-Pacific territorial disputes:Island defense formations in the Philippines and Vietnam require manportable sensors for coastal surveillance, opening new demand corridors.
- 5G spectrum reallocation:National regulators in Germany and South Korea are designating protected radar bands near urban perimeters, creating preferential licensing windows for compliant systems.
Industry Challenges
- RF engineer scarcity:Gallium-nitride circuit design and thermal packaging expertise concentrates within aerospace hubs, limiting supplier scaling.
- Multi-intelligence fusion integration:Radar-to-electro-optical data correlation requires new software stacks that legacy fire-control networks cannot ingest without middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manportable Surveillance and Target Acquisition Radar Market |
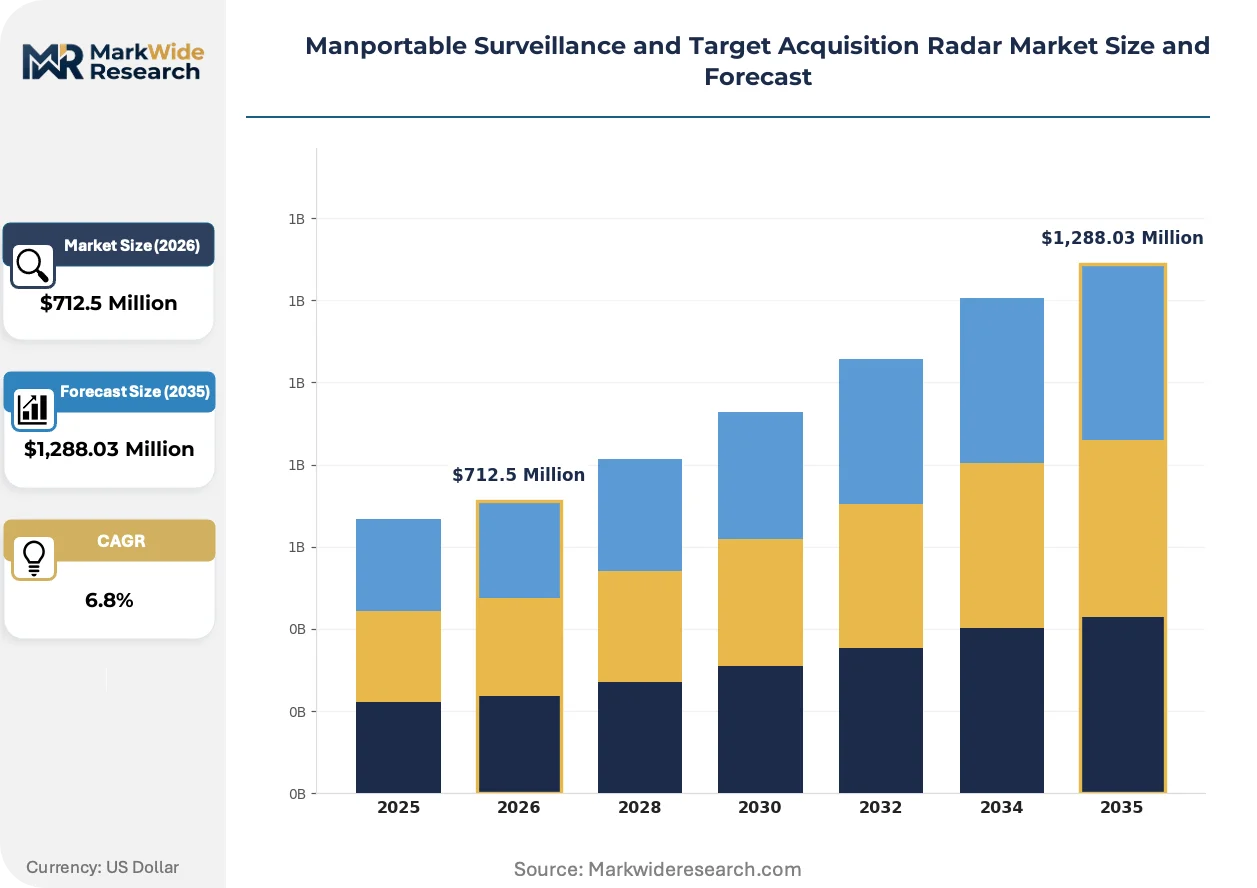
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,288.03 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Surveillance Radar, Airborne Target Acquisition Radar, Handheld Radar Systems, Portable Counter-UAV Radar Technology: Pulse-Doppler, FMCW, Phased Array, Synthetic Aperture Radar, Continuous Wave Application: Border Monitoring, Perimeter Security, Counter-Drone Operations, Tactical Reconnaissance End User: Military Forces, Defense Contractors, Homeland Security Agencies, Private Security Firms |
| Companies Covered | FLIR Systems, ASELSAN, Leonardo, Lockheed Martin Corporation, BAE Systems, Thales Group, Elbit Systems, Northrop Grumman Corporation, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manportable Surveillance and Target Acquisition Radar Market Trends and Innovations
Active electronically scanned arrays are hybridizing with legacy mechanical platforms, creating transitional procurement categories that reward suppliers capable of dual-mode operation. This convergence is compressing development cycles and reshaping vendor qualification criteria.
Gallium-nitride monolithic microwave integrated circuits are hybridizing silicon carbide substrates with diamond heat spreaders to manage thermal dissipation in dismounted enclosures. Special operations commands in Australia and the United Kingdom are field-testing these configurations for extended dwell missions. The technology is hybridizing procurement specifications, merging traditional peak-power metrics with sustained-duty-cycle requirements that disqualify older tube-based designs.
EU AI Act risk classification rules now capture autonomous target-recognition algorithms deployed in manportable systems, mandating human-in-the-loop validation for lethal engagement pathways. European defense procurement frameworks are incorporating these compliance checkpoints into tender evaluations. Vendors supplying NATO-compatible units are restructuring software architectures to segregate sensor processing from fire-control decision nodes.
Direct vendor contracting is displacing layered distributor networks for classified program deliveries, with national security agencies in France and Norway establishing sole-source frameworks for rapid sensor deployment. Military buyers now bundle training and field service into multi-year availability contracts rather than discrete hardware purchases. This pattern concentrates most visibly in Nordic joint procurement initiatives, where cross-border interoperability requirements favor unified supplier relationships over fragmented national sourcing.
Manportable Surveillance and Target Acquisition Radar Market Segmentation
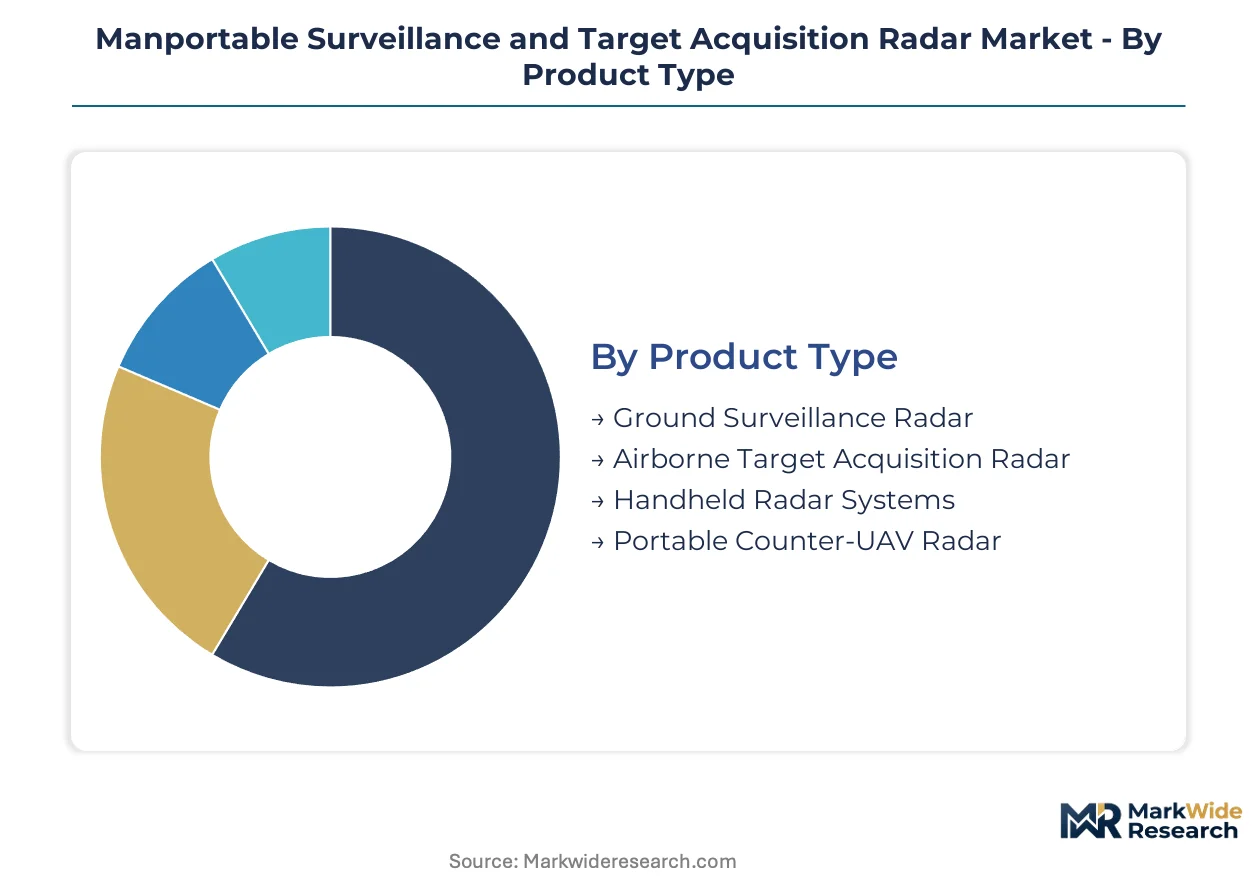
Segmentation in manportable radar markets reveals how procurement priorities diverge across mission profiles and end-user funding streams. Technology choices cascade into weight, power, and thermal constraints that reshape vendor qualification pathways.
Product Type:
Cost tier differentiation separates battlefield-proven configurations from emerging counter-drone variants, with procurement budgets clustering around distinct performance thresholds.
- Ground Surveillance Radar:Pulse-Doppler architectures dominate this segment, offering clutter rejection in complex terrain for infantry units conducting dismounted operations. NATO rapid-response formations in Poland and Romania prioritize these units for forward observation posts, though mechanical scanning limits simultaneous multi-target tracking.
- Portable Counter-UAV Radar:Active electronically scanned arrays with gallium-nitride modules are compressing weight below 15 kilograms for single-soldier transport. U.S. Customs and Border Protection procurement at southwest checkpoints is accelerating field trials, creating a secondary demand corridor distinct from military channels.
- Airborne Target Acquisition Radar:Ku-band configurations with lightweight gimbals serve helicopter-mounted forward air controller missions.
- Handheld Radar Systems:Ultra-compact X-band units with reduced detection ranges suit special operations direct action teams.
Ground Surveillance Radar holds installed capacity. Portable Counter-UAV Radar is rotating up the share rankings.
Technology:
Application requirements determine waveform selection, with mission duration and target density driving trade-offs between power efficiency and electronic protection.
- Pulse-Doppler:Dominant in current military procurements due to proven clutter rejection and fire-control network compatibility. French Army infantry modernization programs specify these units for brigade-level target designation, though tube-based transmitters impose thermal management burdens in tropical deployments.
- Phased Array:Active electronically scanned architectures with software-defined waveforms enable post-deployment upgrades through field-programmable gate arrays. Australian Special Operations Command field trials are validating sustained-duty-cycle performance for extended coastal surveillance missions.
- FMCW:Frequency-modulated continuous wave offers low probability of intercept for covert observation posts.
- Synthetic Aperture Radar:Processing-intensive imaging modes require external computing support, limiting true manportable deployment.
- Continuous Wave:Simple architectures suit short-range perimeter applications with predictable target kinematics.
Pulse-Doppler maintains procurement volume leadership. Phased Array is climbing the fastest as gallium-nitride costs decline.
Application:
Customer type fragmentation splits demand between sovereign defense budgets and homeland security appropriations with distinct contracting timelines.
- Counter-Drone Operations:Portable radar configurations now integrate with kinetic and electronic defeat systems at critical infrastructure sites. German federal police procurement for airport perimeters references EU AI Act risk classifications for autonomous target recognition, mandating human-in-the-loop validation.
- Border Monitoring:Long-endurance deployments in the Philippines and Vietnam require solar-compatible power budgets and satellite backhaul for island defense formations. These specifications disqualify standard military variants optimized for vehicle-mounted power.
- Perimeter Security:Fixed-site installations at energy facilities favor tripod-mounted units with 360-degree coverage.
- Tactical Reconnaissance:Dismounted special operations missions prioritize rapid emplacement and silent operation.
Border Monitoring anchors legacy procurement volumes. Counter-Drone Operations is gaining share fastest through dual-use infrastructure spending.
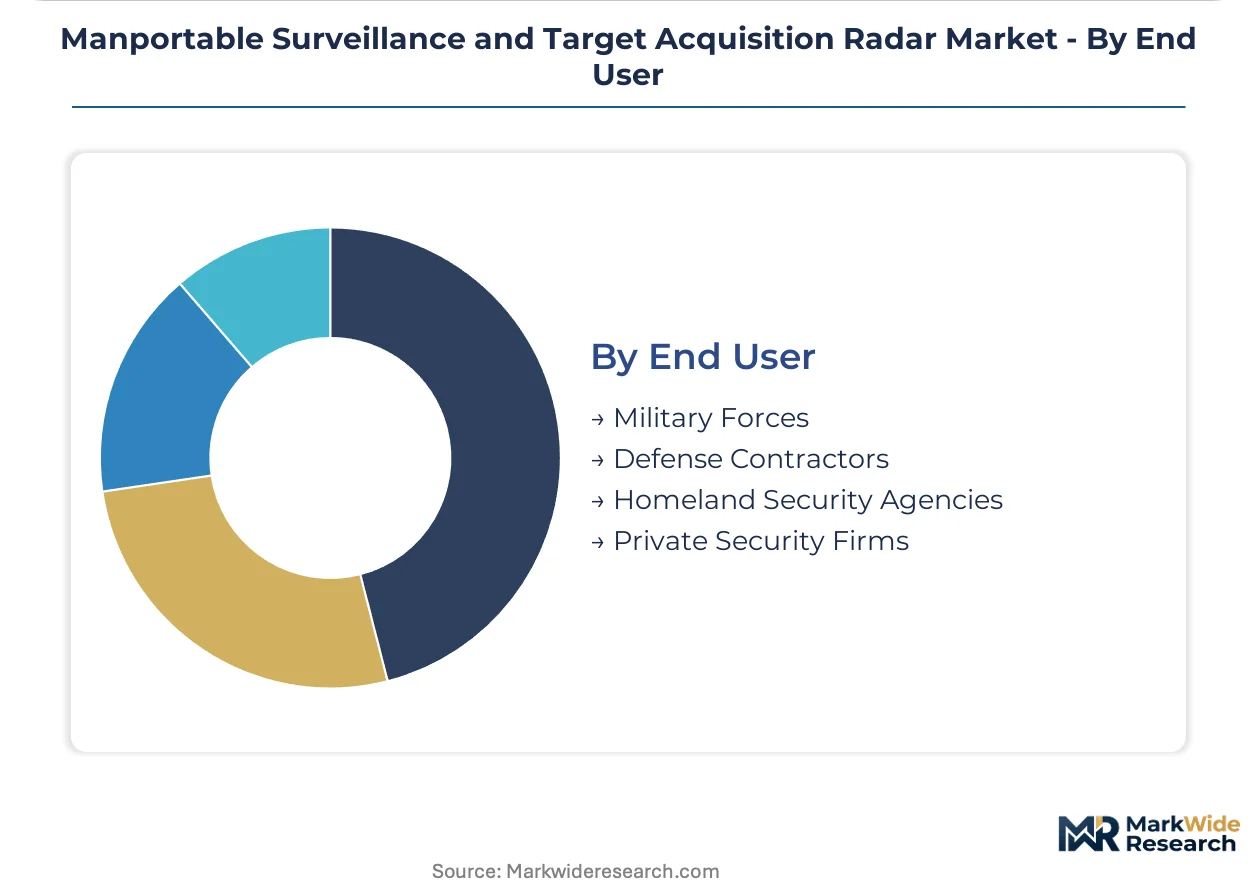
End User:
Volume concentration varies by funding authority, with classified program channels favoring direct vendor relationships over competitive tender processes.
- Military Forces:Brigade-level procurement through NATO frameworks prioritizes interoperability standards and multi-year availability contracts. Norwegian and Swedish joint initiatives specify unified supplier relationships for cross-border rapid response, consolidating vendor qualification pathways.
- Homeland Security Agencies:U.S. CBP and comparable agencies in Germany and South Korea drive counter-UAV demand with civilian airspace coordination requirements. FAA clearance processes extend field trial durations but open protected spectrum allocations near urban perimeters.
- Defense Contractors:Prime integrators source subsystems for platform-embedded applications with customized form factors.
- Private Security Firms:Commercial guarding operations at mining and energy sites adopt de-militarized variants with reduced range specifications.
Military Forces retain contract value leadership. Homeland Security Agencies is rotating up the share rankings through infrastructure protection budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States defense procurement channels, while Turkish and Polish buyers extract cost concessions through NATO framework aggregation. This asymmetry reshapes vendor qualification pathways across theater-specific deployments.
United States
ITAR licensing reforms have established expedited pathways for allied infantry modernization programs. FAA coordination requirements govern domestic counter-drone radar deployments near urban perimeters, extending field trial durations for checkpoint configurations. Defense procurement in Washington and Virginia clusters favors direct vendor contracts over layered distributor networks for classified program deliveries.
Germany
EU AI Act risk classifications now mandate human-in-the-loop validation for autonomous target-recognition algorithms in federal police procurement. REACH substance restrictions accelerate supplier transitions to lead-free solder and compliant substrate materials for Bundeswehr rapid-response units. Industrial activity concentrates in Bavaria and Baden-Württemberg, where software-defined architectures ease field upgrades for NATO-compatible systems.
Turkey
ASELSAN anchors regional supply through captive manufacturing controlling component flow for NATO-compatible units. National defense procurement codes prioritize indigenous content thresholds for manportable radar acquisitions. Ankara-based production clusters serve both domestic formations and export markets across the Middle East and Central Asia.
Australia
Special Operations Command field trials validate gallium-nitride configurations for extended coastal surveillance missions in the Indo-Pacific theater. Spectrum allocation decisions by national regulators designate protected radar bands near urban perimeters, creating preferential licensing windows. Procurement activity clusters in Canberra and Melbourne, where joint programs with the United Kingdom test sustained-duty-cycle performance.
Poland
Brigade-level procurement through NATO frameworks prioritizes interoperability standards for forward observation posts along eastern borders. Rapid-response formations specify pulse-Doppler units for clutter rejection in complex terrain. Defense modernization in Warsaw and Krakow accelerates lightweight radar acquisition for dismounted infantry operations.
Manportable Surveillance and Target Acquisition Radar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in transmit-receive module fabrication and thermal management subsystems. The vendor base stratifies between consolidated prime contractors holding multi-year availability contracts and mid-tier suppliers competing on qualification velocity. Three archetypes dominate: thermal-imaging heritage players bundling multi-sensor packages, captive manufacturers controlling vertical supply chains, and software-defined architects enabling post-deployment waveform upgrades. Competitive moves center on M&A for GaN circuit design talent and strategic partnerships for FAA airspace coordination capabilities.
Within the platform integrator tier, FLIR Systems and Lockheed Martin Corporation exemplify divergent heritage strategies—thermal fusion versus aerospace systems integration—while ASELSAN represents the captive manufacturing archetype controlling component supply for NATO-compatible units. Thales Group occupies a position bridging European defense frameworks with software-defined architectures that ease field upgrades. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific procurement outcomes.
| Leading Market Players |
|---|
| FLIR Systems |
| ASELSAN |
| Leonardo |
| Lockheed Martin Corporation |
| BAE Systems |
| Thales Group |
| Elbit Systems |
| Northrop Grumman Corporation |
| Saab AB |
| Others |
Pricing and Supply Chain Analysis
The Yokohama-Long Beach transpacific corridor compresses logistics costs for gallium-nitride substrate shipments from Japanese epitaxial wafer foundries, concentrating pricing power with transmit-receive module fabricators while forcing downstream tier differentiation based on thermal management sophistication and NATO qualification status.
Pricing Analysis
The customization-premium spread separates mechanically scanned pulse-Doppler configurations from software-defined phased-array units, with active electronically scanned arrays commanding three-to-four-fold premiums over legacy alternatives. Price differentiation hinges on gallium-nitride module certification grade and bundled multi-year availability contracts with field service integration. Cost compression in mechanically scanned tiers is intensifying because REACH-compliant substrate transitions and lead-free solder conversions raise qualified supplier counts. Homeland security agencies exhibit highest price sensitivity due to civilian budget appropriations, while classified military channels absorb premium positioning for rapid-deployment specifications.
Supply Chain Analysis
ITAR export controls and EU dual-use technology restrictions limit gallium-nitride monolithic microwave integrated circuit flows from United States and Japanese fabrication facilities to non-allied end users. Geographic supply concentration centers on Japan, the United States, and Turkey for epitaxial wafer growth and transmit-receive module assembly. Raw material dependencies encompass high-purity gallium metal, silicon carbide substrates, and synthetic diamond heat spreaders. Single-source vulnerability pervades qualified GaN circuit design talent pools concentrated in aerospace hubs. Distribution runs through direct vendor contracts with national security agencies displacing layered distributor networks for classified program deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through NATO framework aggregation and Nordic joint procurement initiatives, fragmenting vendor access for non-preferred suppliers while rewarding unified supplier relationships with multi-year availability commitments.
For Market Incumbents: Entrench competitive position through captive gallium-nitride circuit design talent acquisition and FAA airspace coordination partnership investments. ASELSAN's vertical integration model demonstrates how component supply control insulates against substrate supply concentration risks. Prioritize software-defined architecture roadmaps that enable post-deployment waveform upgrades for European rapid-response units.
For New Entrants and Emerging Players: Establish a beachhead in portable counter-UAV radar configurations for homeland security agencies, where FAA clearance capabilities and civilian airspace coordination expertise create qualification barriers favoring specialist entrants. Target German federal police and U.S. Customs and Border Protection procurement channels with EU AI Act-compliant human-in-the-loop validation architectures. Pursue strategic partnerships with established thermal-imaging heritage players for multi-sensor bundling.
For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by mandating segregated sensor-processing and fire-control decision nodes in autonomous target-recognition systems. Long-term viability centers on software-defined radar architects with field-programmable gate array upgrade pathways and established NATO qualification status. Acquisition target archetypes include gallium-nitride thermal packaging specialists with diamond heat spreader integration capabilities. Watch for spectrum reallocation decisions by German and South Korean regulators designating protected radar bands near urban perimeters as inflection indicators for preferential licensing windows.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Module Certification Investment | REACH-compliant substrate transitions by Japanese suppliers accelerate qualified vendor pool expansion for NATO-compatible units. |
| Software-Defined Architecture Development | Field-programmable gate array integration enables Australian Special Operations Command extended coastal surveillance mission validation. |
| FAA Coordination Partnership | Multi-agency clearance capabilities compress field trial durations for U.S. Customs and Border Protection checkpoint deployments. |
| Multi-Sensor Bundling Agreement | Thermal-imaging heritage integration reduces procurement friction for infantry modernization programs in Poland and Romania. |
| Direct Vendor Contracting Framework | Norwegian and Swedish joint initiatives consolidate cross-border interoperability requirements through unified supplier relationships. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with radar systems program managers, GaN module procurement leads at defense primes, thermal packaging engineers, and NATO framework contracting officers; alongside secondary validation through ITAR license filing databases, FAA airspace coordination records, EU defense procurement tender archives, and national spectrum allocation decisions. Bottom-up unit shipment estimates triangulated against top-down defense budget appropriation analysis across military and homeland security channels.
Forecast inputs encompassed technology segmentation by waveform architecture, application mission profiles spanning counter-drone to border monitoring, end-user funding authority differentiation, and regional regulatory cluster variations. CAGRs derived from deployment timeline modeling across the analysis window, incorporating gallium-nitride cost decline curves and phased-array adoption elasticity. Industry-specific inputs included ITAR license streamlining pathway utilization rates and EU AI Act compliance checkpoint integration timelines.
Sensitivities concentrate around gallium-nitride substrate supply disruptions, FAA airspace coordination timeline extensions, and 5G spectrum reallocation decisions affecting radar band availability. Forecasts reflect documented assumptions regarding NATO member defense modernization commitment continuity and REACH substance restriction enforcement consistency. Material shifts in Indo-Pacific territorial dispute escalation patterns or ITAR licensing policy reversals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
UXO Detection Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Tactical Optics Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Global Airborne Surveillance Market