
 Asia-Pacific Hydrographic Survey Equipment Market | 2026-2036
Asia-Pacific Hydrographic Survey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hydrographic Survey Equipment Market Insights
Market Context with Strategic Players
Synthetic aperture sonar is consolidating around multi-beam echo sounder architectures as the default hull-mounted configuration for deep-water pipeline surveys. Kongsberg Maritime leverages its integrated Seapath and SIS software ecosystem to dominate turnkey vessel deliveries across Southeast Asian fleets. Teledyne Technologies sustains a dual-channel position through its combined acoustic imaging and underwater vehicle payload lines. Fugro competes on deployment scale, operating permanently stationed survey vessels from Perth to Yokohama under long-term offshore energy contracts.
Technical Definition and Structural Segments
Asia-Pacific hydrographic survey equipment encompasses acoustic and optical instrumentation used to measure water depth, seabed topography, and sub-bottom stratigraphy with centimetric positional accuracy tied to GNSS correction networks. The primary commercial purpose spans nautical charting for safe navigation, offshore construction support, and environmental baseline studies preceding marine infrastructure development. Multi-beam systems capture the dominant share of capital expenditure owing to their swath coverage efficiency in corridor mapping for submarine cable routes. Acoustic technology leads unit shipments while remote sensing grows fastest from satellite-derived bathymetry contracts awarded to coastal administrations with limited vessel access. Government agencies anchor the end-user base through recurring national hydrographic service budgets, though offshore oil and gas commands the highest per-project equipment specification tiers.
Regulatory Framework and Forward Outlook
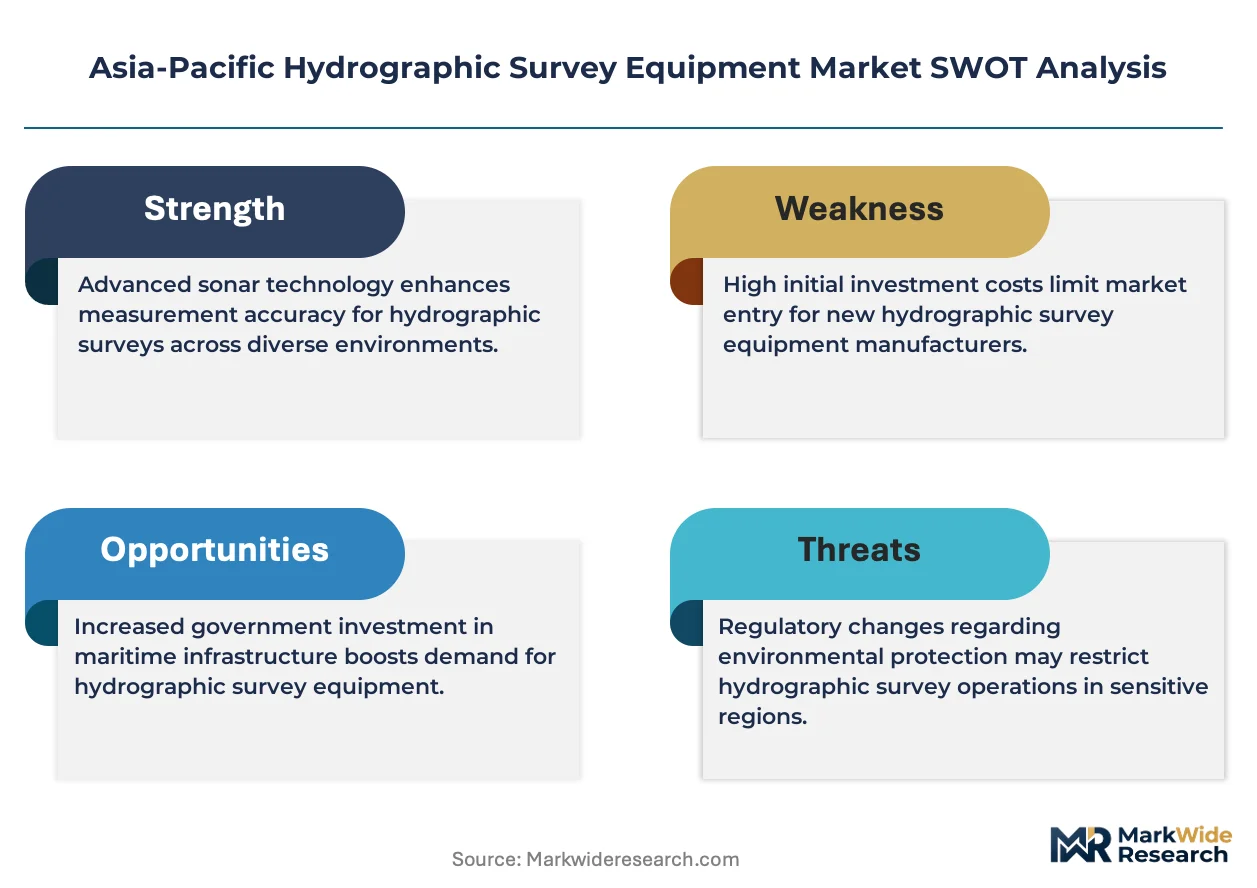
China's MEE enforces marine environmental impact assessment protocols that mandate pre- and post-construction seabed surveys for all offshore wind lease areas, directly expanding multi-beam system procurement. Japan's MLIT coordinates nautical charting standards with the Japan Coast Guard, while Australia's AMSA regulates undersea pipeline route surveys through its offshore safety regime. India's CEA and MoES have begun requiring hydrographic baseline data for all coastal thermal and desalination outfall permits. Stakeholders must monitor how bilateral maritime boundary delimitation disputes between Indonesia, Vietnam, and the Philippines redirect government survey vessel procurement toward dual-use defense-compatible platforms.
Market Dynamics
China's dual carbon goals are forcing replacement of diesel-powered survey vessels with hybrid-electric platforms, reshaping procurement specifications across coastal administrations and offshore energy operators throughout the region.
Growth Catalysts
- Offshore wind lease mandates:China's MEE requires pre-construction seabed surveys for all offshore wind zones, directly expanding multi-beam echo sounder procurement from state hydrographic services.
- Submarine cable corridor mapping:Australia's offshore energy corridors are driving demand for synthetic aperture sonar integrated with multi-beam architectures for deep-water route surveys.
- Port modernization directives:Japan's MLIT coordinates nautical charting standards with the Japan Coast Guard, accelerating replacement cycles for aging hull-mounted survey systems in Yokohama and Osaka Bay.
Market Restraints
- Sensor supply concentration:High-precision acoustic transducer manufacturing concentrates in European and North American specialist suppliers, exposing Asia-Pacific integrators to extended lead times and currency volatility.
- GNSS correction dependency:Centimetric positional accuracy requirements tie survey operations to regional satellite augmentation networks, creating coverage gaps in Indonesia's eastern archipelago and Papua New Guinea waters.
- Diesel-electric platform obsolescence:China's dual carbon timeline compresses residual value for conventional survey vessels, stranding capital in fleets operated by smaller coastal administrations.
Strategic Opportunities
- Philippines maritime boundary surveys:Bilateral delimitation disputes with Indonesia and Vietnam are redirecting government procurement toward dual-use defense-compatible platforms with enhanced acoustic capabilities.
- Satellite-derived bathymetry contracts:Remote sensing growth accelerates as coastal administrations with limited vessel access award contracts for shallow-water charting in Vietnam's Mekong Delta and Bangladesh's Sundarbans.
- India coastal infrastructure baseline:The CEA and MoES now require hydrographic data for all thermal and desalination outfall permits, opening recurring revenue streams for survey contractors in Gujarat and Tamil Nadu.
Industry Challenges
- Acoustic data processing expertise:Shortages in synthetic aperture sonar algorithm specialists and multi-beam patch test engineers constrain fleet expansion timelines for Southeast Asian operators.
- ISO certification complexity:Survey contractors face extended timelines achieving ISO 9001 and ISO 14001 accreditation required for Australia's AMSA-regulated pipeline route contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hydrographic Survey Equipment Market |
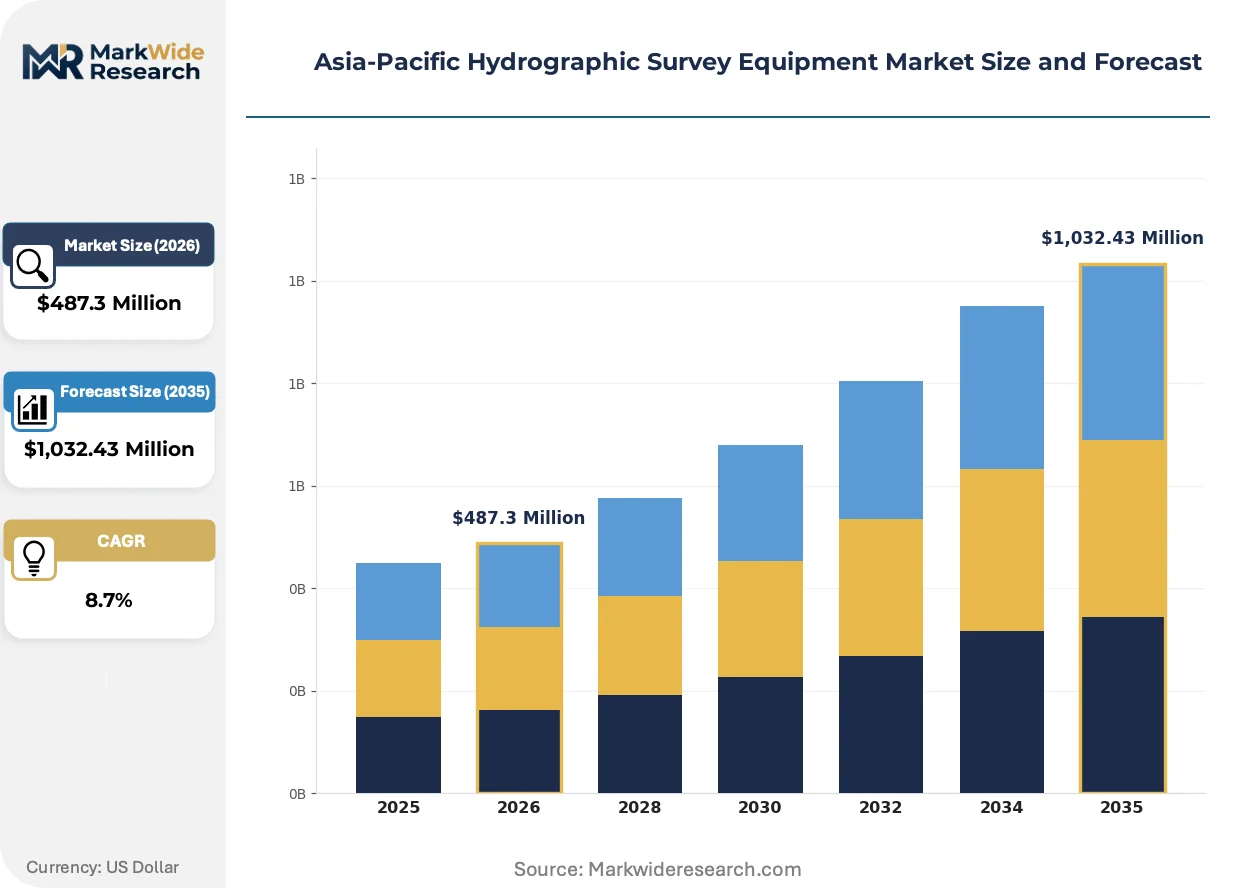
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Echo Sounders, Multi Beam Systems, GNSS Equipment, Surveys Technology: Acoustic, Optical, Laser, Remote Sensing End User: Government Agencies, Marine Research Institutes, Environmental Organizations, Offshore Oil & Gas Application: Coastal Mapping, Marine Engineering, Environmental Monitoring, Nautical Charting |
| Companies Covered | Kongsberg Maritime, Teledyne Technologies, iXblue SAS, Fugro, EdgeTech, Innomar Technologie GmbH, Sonardyne International Ltd., SyQwest Inc., Valeport Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hydrographic Survey Equipment Market Trends and Innovations
Acoustic imaging architectures are converging with autonomous underwater vehicle payloads, compressing survey timelines while elevating data resolution standards across offshore energy and coastal administration contracts.
Synthetic aperture sonar is unifying with multi-beam echo sounder hull-mounted configurations to create single-pass seabed mapping systems. Offshore oil and gas operators in Australia's North West Shelf are adopting these integrated architectures for pipeline inspection surveys. This convergence is unifying previously separate procurement streams for wide-area swath coverage and high-resolution target detection into single-vessel deployments.
China's MEE marine environmental impact assessment protocols now mandate pre- and post-construction seabed surveys for all offshore wind lease areas. These requirements are forcing survey contractors to maintain permanently mobilized multi-beam systems with real-time data transmission capabilities. Offshore wind developers in Jiangsu and Guangdong provinces are responding by contracting long-term vessel charters rather than project-specific deployments.
Equipment leasing models are displacing capital purchase for coastal administrations with constrained budgets. Vietnam's Hydrographic Survey Department and Indonesia's Bakorkamla are accessing Kongsberg and Teledyne systems through operational lease structures with embedded maintenance and software update provisions. This shift is most visible in Southeast Asian markets where national hydrographic service budgets face competing infrastructure priorities.
Asia-Pacific Hydrographic Survey Equipment Market Segmentation
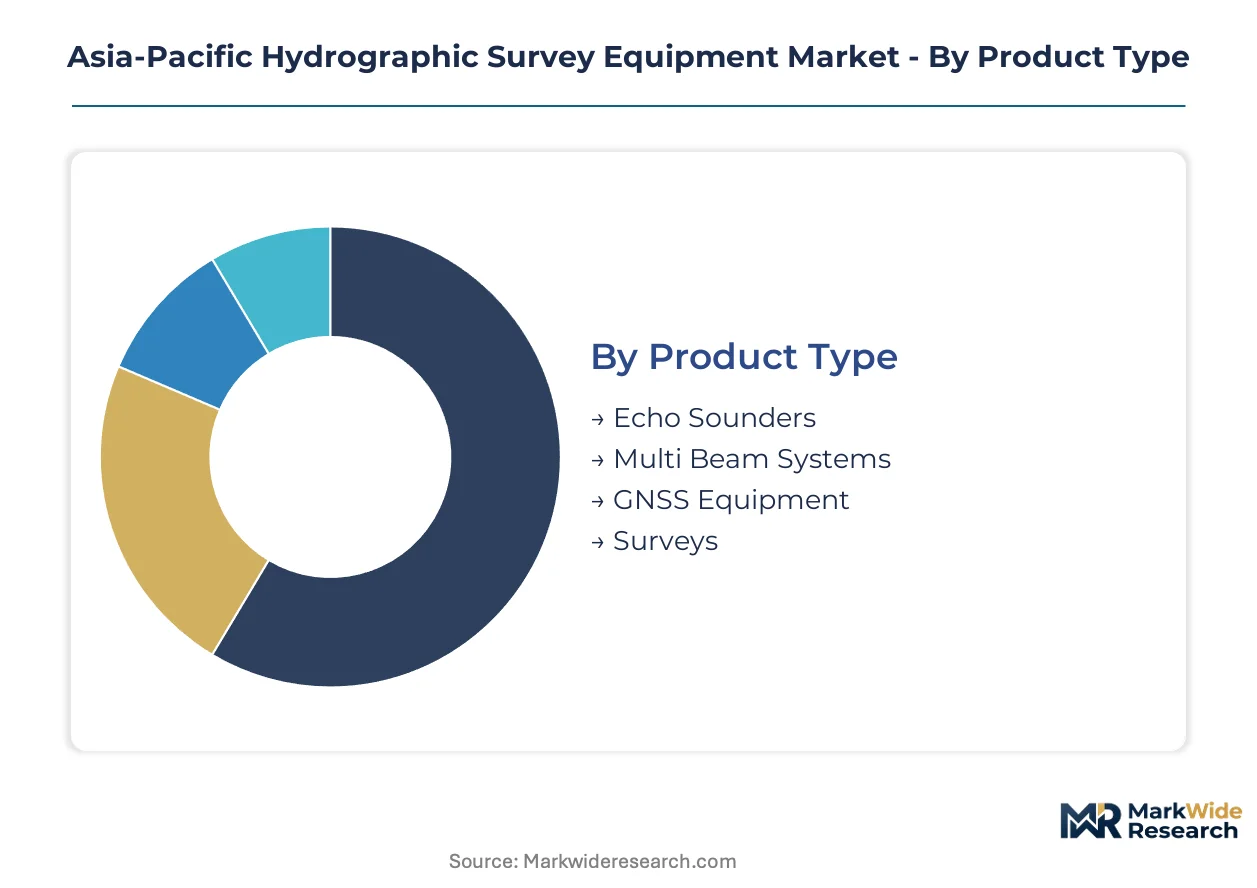
Equipment specification tiers diverge sharply between offshore energy contractors requiring centimetric accuracy and coastal administrations prioritizing swath coverage efficiency. Procurement patterns across the Asia-Pacific region cluster around four structural dimensions that determine sensor architecture, software integration depth, and vessel platform requirements.
Product Type:
Capital allocation intensity drives platform selection, with offshore operators prioritizing integrated sensor suites over standalone instruments.
- Echo Sounders:Single and dual-frequency units provide depth measurement for routine nautical charting and inland waterway surveys. Coastal administrations in Vietnam and Bangladesh deploy these systems for shallow-water corridor mapping where budget constraints limit multi-beam adoption.
- Multi Beam Systems:Swath coverage architectures capture seabed topography across corridor widths exceeding ten times water depth. Australia's North West Shelf operators specify these systems for pipeline route surveys, with China's MEE mandates accelerating procurement for offshore wind baseline studies in Jiangsu and Guangdong provinces.
- GNSS Equipment:Real-time kinematic correction receivers deliver positional accuracy to centimetric tolerances for hydrographic survey vessels.
- Surveys:Integrated service packages bundle vessel charter, sensor operation, and data processing under single-contractor responsibility.
Volume sits with echo sounders; growth tilts toward multi-beam systems.
Technology:
Measurement modality selection depends on water column clarity, target detection resolution requirements, and deployment platform constraints.
- Acoustic:Multi-beam echo sounders and synthetic aperture sonar dominate deep-water applications through sound propagation independent of optical visibility. Japan's MLIT-coordinated port modernization programs specify acoustic hull-mounted systems for Yokohama Bay and Osaka Harbor seabed monitoring.
- Optical:Underwater cameras and photogrammetry systems capture high-resolution imagery for marine engineering inspection tasks in clear-water environments. Environmental monitoring contractors in Australia's Great Barrier Reef Marine Park deploy optical payloads for benthic habitat classification where water clarity permits.
- Laser:Airborne lidar bathymetry penetrates shallow water columns for rapid coastline mapping.
- Remote Sensing:Satellite-derived bathymetry contracts are expanding most quickly across coastal administrations with limited vessel access, including Vietnam's Mekong Delta and Bangladesh's Sundarbans regions.
Acoustic platforms dominate current procurement volumes; remote sensing claims the steepest expansion trajectory.
End User:
Budget cycle predictability and project scale determine whether equipment procurement favors capital purchase or operational lease structures.
- Government Agencies:National hydrographic services maintain recurring equipment replacement budgets tied to nautical charting obligations. Indonesia's Bakorkamla and Vietnam's Hydrographic Survey Department are shifting toward lease models with embedded maintenance provisions.
- Marine Research Institutes:Academic and government research facilities require specialized sub-bottom profiling capabilities for sediment stratigraphy studies. Japan's JAMSTEC and Australia's CSIRO operate dedicated research vessels with multi-sensor payloads for deep-ocean mapping programs.
- Environmental Organizations:Non-governmental monitoring groups prioritize portable, shallow-water systems for rapid deployment.
- Offshore Oil & Gas:Energy operators command the highest per-project specification tiers, contracting permanently mobilized survey vessels under multi-year charters.
Procurement volume concentrates in government agencies; offshore oil and gas generates the highest equipment specification premiums.
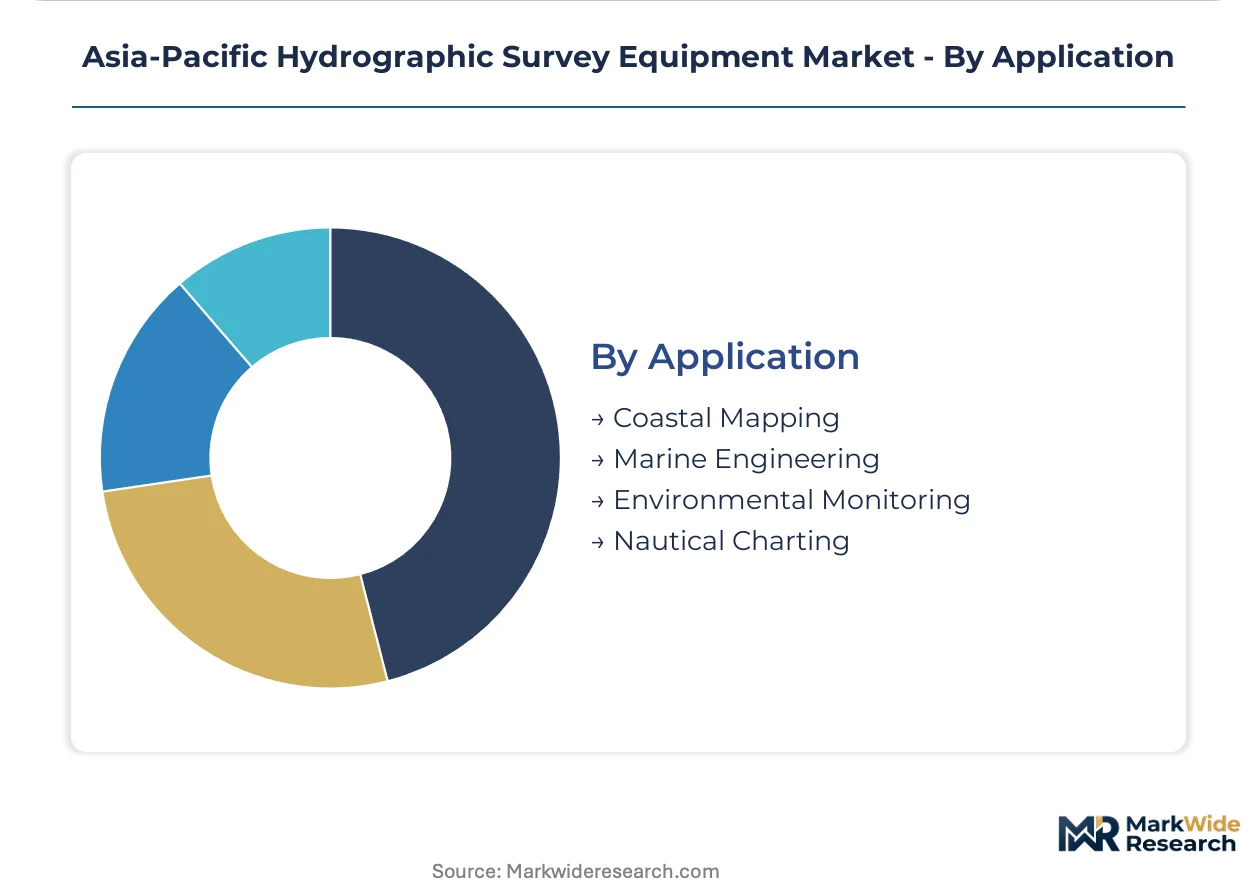
Application:
Regulatory mandate intensity varies across application areas, directly influencing survey frequency and data resolution requirements.
- Coastal Mapping:Shoreline change detection and shallow-water bathymetry support maritime boundary delimitation and flood risk assessment. The Philippines government is redirecting procurement toward defense-compatible platforms amid bilateral disputes with Indonesia and Vietnam.
- Marine Engineering:Subsea construction support demands real-time seabed monitoring for pipeline laying and platform installation. India's CEA now requires hydrographic baseline data for all coastal thermal and desalination outfall permits in Gujarat and Tamil Nadu.
- Environmental Monitoring:Pre- and post-construction seabed surveys track disturbance recovery and habitat condition.
- Nautical Charting:Safety-of-navigation data production remains the statutory core function for national hydrographic services throughout the region.
Nautical charting anchors steady procurement volumes; environmental monitoring is gaining share fastest under expanding MEE and CEA regulatory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in China's offshore wind zones and Australia's energy corridors, with Japan's port zones and India's coastal infrastructure emerging as secondary demand poles. The region's regulatory fragmentation creates divergent specification tiers across national hydrographic services.
China
Offshore wind developers in Jiangsu and Guangdong provinces are contracting long-term vessel charters under MEE marine environmental impact assessment mandates. The country's dual carbon goals compress replacement timelines for diesel-powered survey fleets. State hydrographic services are accelerating multi-beam echo sounder procurement for seabed baseline studies preceding construction.
Australia
North West Shelf operators specify synthetic aperture sonar integrated with multi-beam architectures for deep-water pipeline route surveys. AMSA regulates undersea pipeline surveys through offshore safety regimes that demand ISO-certified contractors. Perth anchors permanently stationed survey vessels under multi-year offshore energy contracts.
Japan
MLIT-coordinated port modernization programs are accelerating replacement cycles for aging hull-mounted systems in Yokohama Bay and Osaka Harbor. The Japan Coast Guard maintains recurring nautical charting obligations that sustain equipment replacement budgets. Kansai and Kanto regions concentrate survey vessel procurement for seabed monitoring.
India
CEA and MoES now require hydrographic baseline data for all coastal thermal and desalination outfall permits in Gujarat and Tamil Nadu. Marine engineering contractors are mobilizing permanently stationed systems for real-time construction support. Mumbai and Chennai clusters are emerging as procurement hubs for subsea construction monitoring.
Vietnam
The Hydrographic Survey Department is accessing multi-beam systems through operational lease structures with embedded maintenance provisions. Bilateral maritime boundary delimitation disputes are redirecting government procurement toward dual-use defense-compatible platforms. Mekong Delta coastal administrations are awarding satellite-derived bathymetry contracts for shallow-water charting.
Asia-Pacific Hydrographic Survey Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding premium positioning in offshore energy while component suppliers serve coastal administrations through lease models. The vendor base organizes around three archetypes: full-stack platform integrators, acoustic sensor specialists, and survey service operators bundling equipment with vessel charter. Consolidation pressure is elevating M&A activity among mid-scale sensor manufacturers, while technology licensing agreements are proliferating between European transducer suppliers and Asia-Pacific vessel integrators.
Among the integrated platform tier, Kongsberg Maritime and Teledyne Technologies occupy positions spanning software-defined survey architectures and combined acoustic imaging payloads. Fugro exemplifies the service-operator archetype, anchoring a model built on permanently mobilized vessel fleets under long-term energy contracts. These three entities represent distinct competitive vectors: turnkey system delivery, dual-channel technology supply, and deployment-scale service bundling.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| Teledyne Technologies |
| iXblue SAS |
| Fugro |
| EdgeTech |
| Innomar Technologie GmbH |
| Sonardyne International Ltd. |
| SyQwest Inc. |
| Valeport Ltd. |
| Others |
Pricing and Supply Chain Analysis
European family-owned acoustic transducer specialists anchor supply-side concentration, compressing procurement timelines for Asia-Pacific vessel integrators while elevating pricing power for precision sensor tiers.
Pricing Analysis
Volume sits with single-beam echo sounders for coastal administrations; margins concentrate in integrated multi-beam suites for offshore energy contractors. Price differentiation hinges on ISO 14001 certification tier and real-time data transmission capability. Cost compression in standard sensor tiers is intensifying because Vietnamese and Indonesian lease models embed maintenance provisions that flatten upfront capital recovery. Government hydrographic services exhibit highest price sensitivity; Australia's North West Shelf operators accept premium positioning for synthetic aperture sonar integration.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-scale demand from China's state hydrographic services and Japan's MLIT-coordinated programs. High-precision acoustic transducer manufacturing draws from Norway, France, and the United States, exposing Asia-Pacific integrators to euro-dollar volatility. Piezoelectric ceramics, precision-machined transducer housings, and GNSS correction receivers constitute critical input dependencies. Single-source vulnerability concentrates in synthetic aperture sonar algorithm licensing from European specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: China's MEE marine environmental impact assessment protocols erect certification barriers that strand non-compliant competitors while rewarding players with permanently mobilized multi-beam fleets.
For Market Incumbents: Lock in long-term vessel charter relationships with Jiangsu and Guangdong offshore wind developers before lease market saturation. Deepen backward integration into real-time data transmission software to defend against Teledyne's dual-channel payload bundling. Prioritize ISO 14001 accreditation investment to capture Australia's AMSA-regulated pipeline route contracts. For New Entrants and Emerging Players: Satellite-derived bathymetry platforms offer the most penetrable white-space entry, particularly for Vietnam's Mekong Delta and Bangladesh's Sundarbans coastal administrations lacking vessel access. Target India's CEA-mandated thermal outfall baseline surveys in Gujarat and Tamil Nadu as anchor contracts. Pursue operational lease structures with embedded maintenance to bypass capital-intensive fleet ownership. For Investors and Strategic Acquirers: China's dual carbon vessel replacement timeline is the leading indicator that hybrid-electric platform demand will reshape procurement specifications across coastal administrations. Position for mid-scale acoustic sensor manufacturers facing consolidation pressure from Kongsberg and Teledyne ecosystem expansion. Monitor Indonesia-Vietnam-Philippines maritime boundary delimitation disputes as the signal for defense-compatible dual-use platform procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Vessel Fleet Conversion | China's dual carbon goals compress diesel platform residual values while elevating lease demand. |
| Real-Time Data Transmission Integration | MEE offshore wind mandates force permanently mobilized systems with shore-side connectivity. |
| Synthetic Aperture Sonar Licensing | European algorithm specialists control target detection resolution for pipeline inspection tiers. |
| Operational Lease Model Expansion | Vietnam's Hydrographic Survey Department and Indonesia's Bakorkamla shift from capital purchase. |
| Defense-Compatible Platform Certification | Philippines maritime boundary disputes redirect procurement toward dual-use acoustic capabilities. |
Research Methodology
Industry association publications, customs trade records for acoustic sensor imports, and national hydrographic service budget disclosures formed the secondary backbone. Primary fieldwork encompassed survey vessel operators, offshore wind project developers, marine environmental consultants, and port authority engineering directors across China, Australia, Japan, India, and Vietnam. Bottom-up equipment procurement tallies were cross-validated against top-down national infrastructure spending plans.
Bottom-up modeling tracked sensor unit shipments by specification tier across the projection horizon; top-down validation anchored against offshore energy capital expenditure and coastal administration budget trajectories. Segmentation dimensions spanned product architecture, measurement modality, end-user procurement structure, and regulatory mandate intensity. CAGRs were derived from equipment replacement cycle compression and lease model penetration curves.
The model holds under stable MEE and CEA regulatory enforcement; deviation in bilateral maritime boundary dispute resolution or GNSS augmentation network expansion would shift procurement timing. Forecasts reflect documented assumptions regarding hybrid vessel adoption rates and synthetic aperture sonar integration timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
North America Passive Radar Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Tactical Optics Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Military Radar Systems Market