
 Global Radar Market | 2026-2036
Global Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radar Market Outlook
Japan is rewriting competitive dynamics in radar component fabrication through gallium nitride foundry investments and precision manufacturing scale. Raytheon Technologies leverages captive semiconductor supply chains to sustain margins on phased array systems for missile defense. Thales Group anchors European naval radar modernization through sovereign manufacturing bases in France and the Netherlands. Lockheed Martin dominates long-range surveillance contracts with integrated command-and-control architectures that competitors struggle to replicate.
Radar systems detect, locate, and track objects by transmitting radio frequency pulses and analyzing reflected echo signals, with modern implementations operating across X-band, S-band, and millimeter-wave frequencies for resolution precision. These systems serve defense early warning, civilian air navigation, meteorological observation, and autonomous vehicle perception. Imaging radar and phased array technologies command premium positioning due to software-defined beam steering and synthetic aperture resolution gains that legacy mechanically scanned systems cannot match. Doppler radar segments retain volume leadership in weather and aviation applications where proven reliability outweighs upgrade urgency.
FAA NextGen mandates, EU Green Deal aviation efficiency standards, and China's MIIT spectrum allocation frameworks collectively reshape product certification timelines and export compliance burdens. NHTSA automatic emergency braking requirements and equivalent UN ECE regulations are accelerating automotive radar adoption with strict electromagnetic compatibility testing. Stakeholders must monitor gallium nitride substrate supply concentration and cross-border technology transfer controls as determinants of manufacturing cost trajectories and market access viability.
Market Dynamics
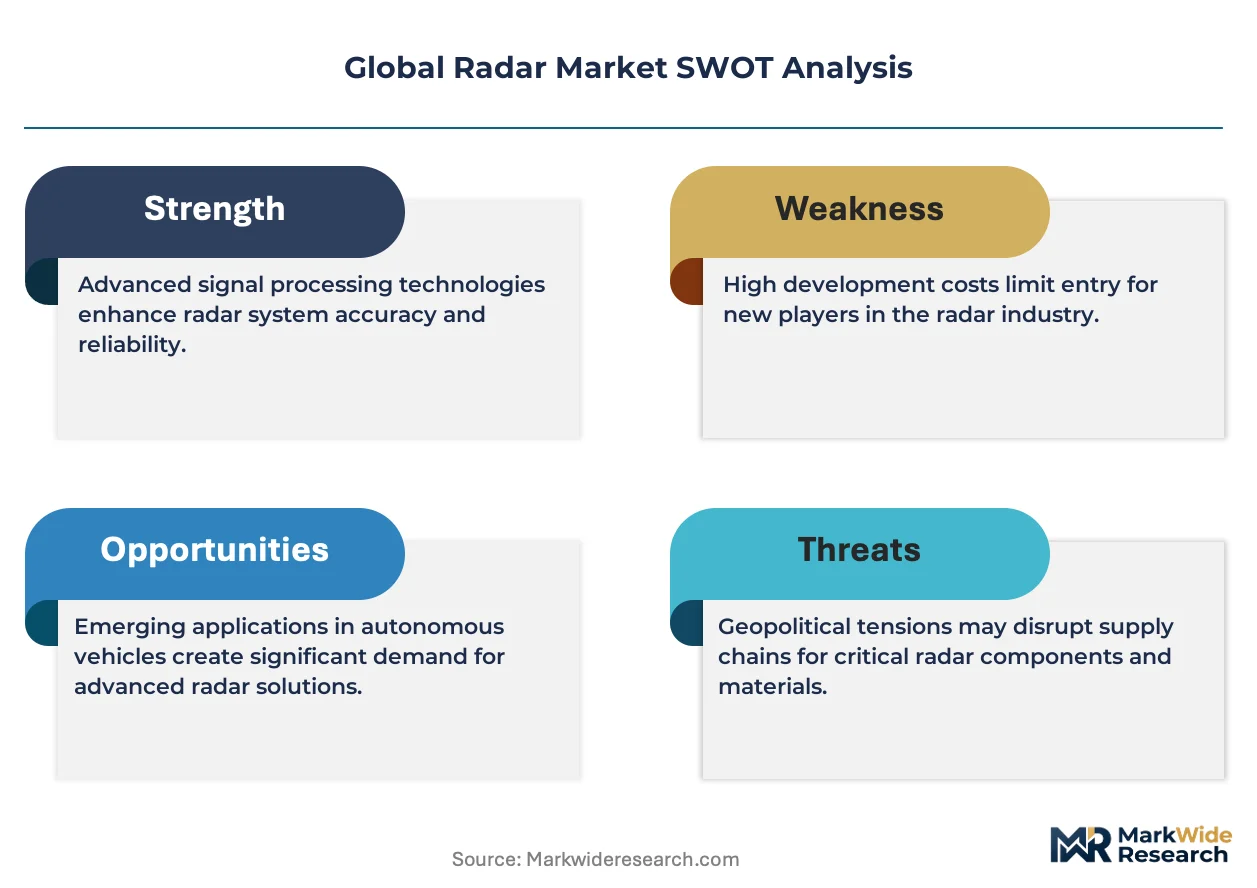
Gallium nitride substrate concentration in Japanese and US foundries is compressing cost curves for active electronically scanned arrays while fragmenting supply security for European and Chinese system integrators.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandates:US vehicle safety rules now require radar-equipped AEB on all light vehicles, forcing sensor procurement at 100% penetration rates across OEM production lines.
- Frequency Modulated Continuous Wave Radar:Automotive Tier-1 suppliers are embedding 4D imaging FMCW chips into highway autopilot stacks, replacing legacy corner radars with elevation-capable units.
- China MIIT Spectrum Allocation:Dedicated 76-81 GHz bands for vehicular radar eliminate interference disputes and accelerate homologation timelines for domestic suppliers.
Market Restraints
- Gallium Nitride Substrate Bottleneck:Six-inch GaN-on-SiC wafer supply concentrates in two Japanese foundries, exposing phased array manufacturers to 18-month order backlogs.
- US Export Administration Regulations:Dual-use radar technology controls block transfer of synthetic aperture processing algorithms to specified entities, freezing market access for non-aligned system vendors.
- Mechanical Scan Radar Obsolescence:Legacy rotating antenna architectures face spare parts scarcity as semiconductor suppliers discontinue driver chip families.
Strategic Opportunities
- Urban Air Mobility Sensor Suites:eVTOL developers in Germany and China specify compact solid-state radars for detect-and-avoid systems, opening a greenfield avionics category absent incumbent lock-in.
- Software-Defined Radar Architectures:Open RAN principles applied to radar back-ends allow third-party waveform apps, disintermediating proprietary stack vendors.
- India Defence Procurement Procedures:Indigenization mandates under Make-in-India frameworks create joint venture slots for foreign GaN foundries to localize TR module production.
Industry Challenges
- RF Engineer Scarcity:Millimeter-wave circuit design expertise concentrates in aerospace hubs around Tucson, Munich, and Beijing, leaving secondary markets talent-starved.
- Environmental Stress Screening Costs:Military qualification cycles demand 1000-hour thermal vacuum testing per lot, consuming 14-18 months before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radar Market |
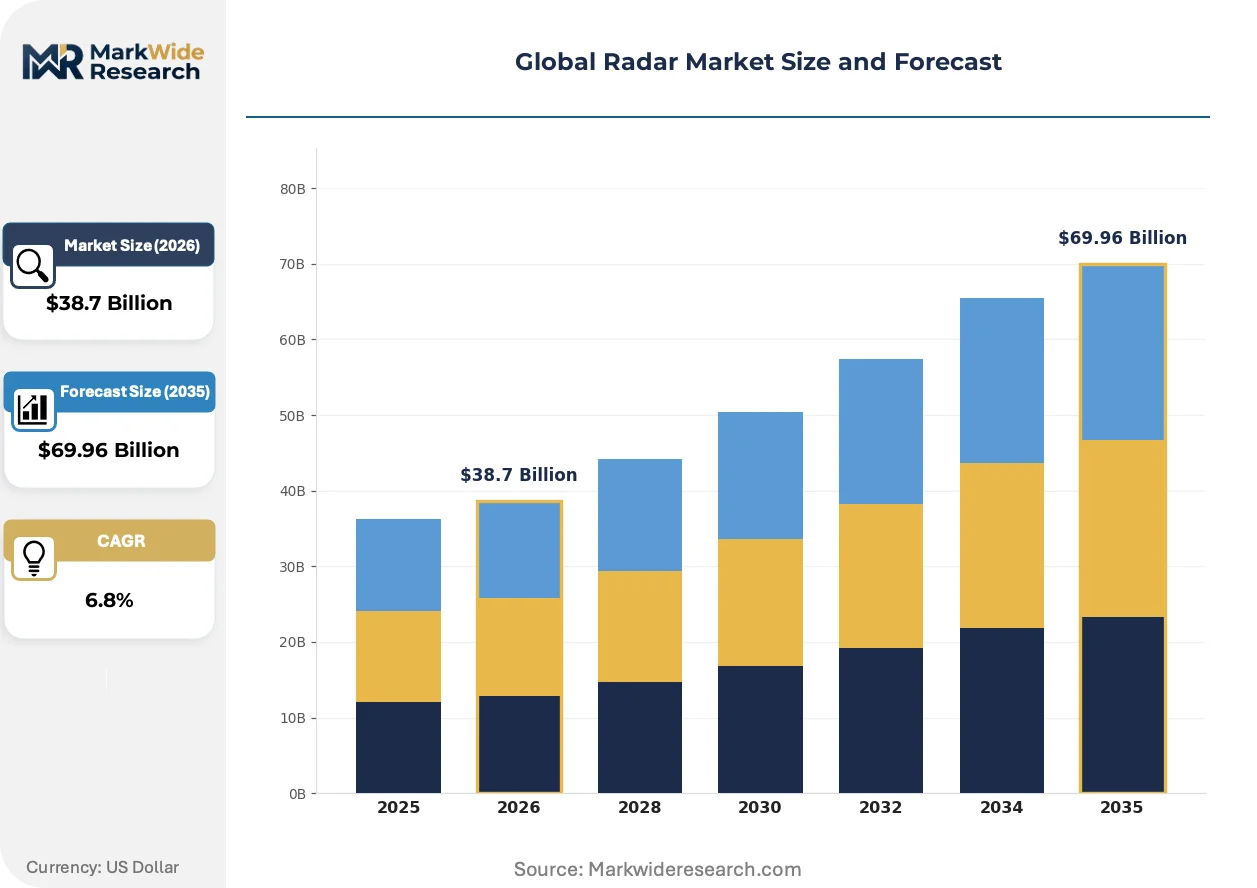
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Radar, Ground Surveillance Radar, Air Traffic Control Radar, Imaging Radar Technology: Phased Array, Frequency Modulated Continuous Wave, Pulsed Wave, Doppler Radar Application: Aerospace, Defense, Environmental Monitoring, Automotive End User: Government, Private Sector, Research Institutions, Military |
| Companies Covered | Raytheon Technologies Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, BAE Systems plc, Leonardo S.p.A., Saab AB, L3Harris Technologies, Inc., Israel Aerospace Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radar Market Strategic Shifts
Digital beamforming is collapsing the hardware-software boundary in radar systems, enabling post-deployment performance upgrades that were impossible under analog architectures.
Synthetic aperture radar processing is virtualizing the distinction between hardware antennas and computational imaging. Satellite operators in Finland and Israel now deploy 10-kilogram CubeSAR units that outperform 500-kilogram legacy platforms through onboard GPU clusters. Defense procurement offices in the US and UK are rewriting specifications to reward software-defined resolution metrics over physical aperture size.
EU Green Deal aviation efficiency standards are forcing airport surveillance radar upgrades before mechanical end-of-life. Secondary surveillance radar replacements must demonstrate 40% power consumption reductions to qualify for slot allocation incentives. Thales and Indra are retrofitting existing sites with GaN transmit chains rather than full antenna replacements to meet 2027 compliance deadlines.
Consolidated fleet management contracts are displacing unit sales in maritime radar. Greek and Singaporean container lines now procure navigation sensor packages as hourly service subscriptions, transferring obsolescence risk to integrators. This compresses upfront equipment margins while extending revenue recognition across 10-year operating leases.
Global Radar Market Segmentation
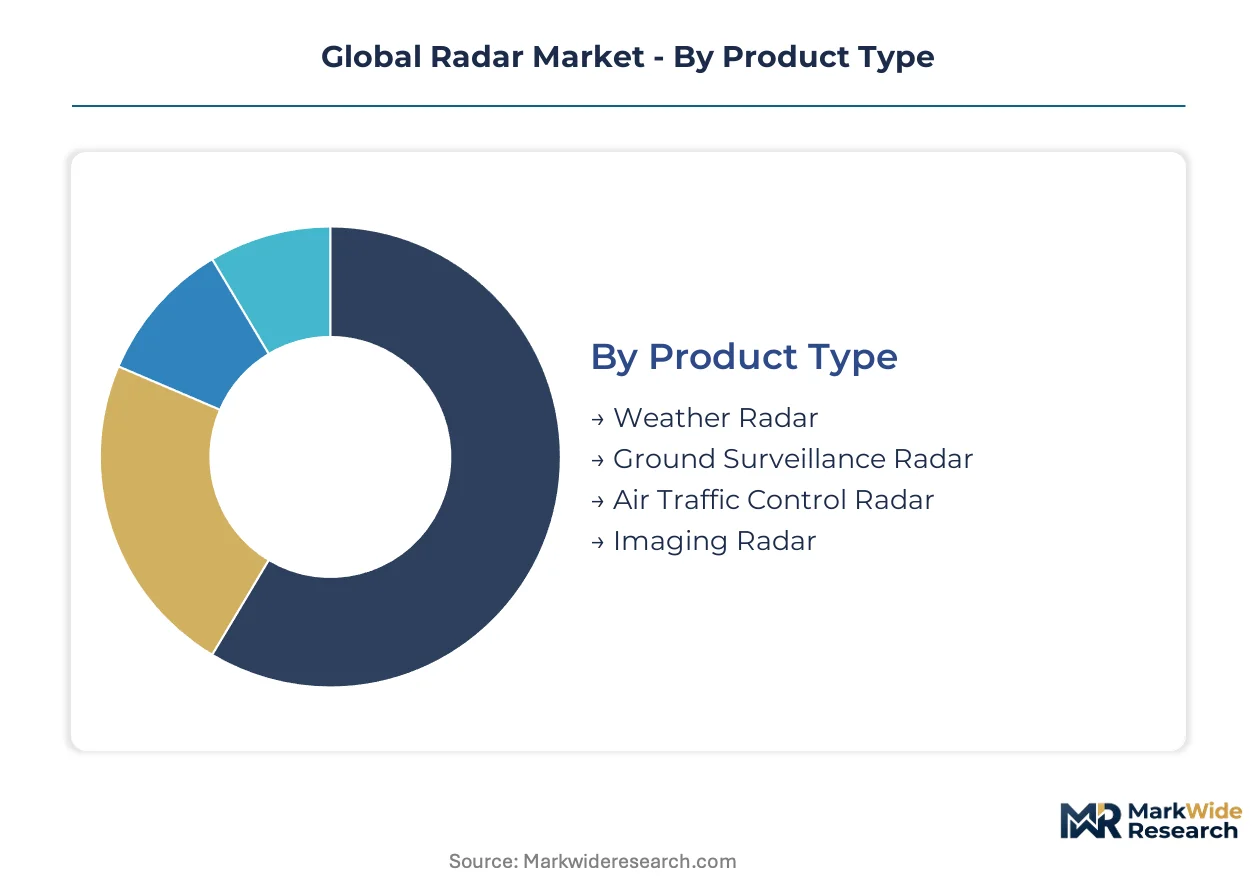
Radar market segmentation reveals how technology maturity, procurement authority, and application criticality partition revenue streams. Product architectures diverge sharply between cost-optimized automotive units and sovereign-class defense systems. Procurement channels further bifurcate the landscape between classified military programs and commercial aviation tenders governed by FAA and EASA certification timelines.
Product Type:
Cost tier separates legacy mechanical systems from premium solid-state architectures with software-defined upgrade paths.
- Weather Radar:Doppler-enabled precipitation detection systems integrate dual-polarization transmitters for hydrometeor classification. Demand concentrates in NOAA modernization and European meteorological consortium upgrades where supercomputing back-ends process terabyte-scale reflectivity datasets.
- Imaging Radar:Synthetic aperture processing enables centimeter-resolution terrain mapping through computational beam synthesis rather than physical aperture expansion. Military reconnaissance contracts in the United States and satellite operators in Germany drive procurement of lightweight SAR payloads for unmanned platforms.
- Ground Surveillance Radar:Portable units with staring-array architectures detect personnel and vehicle movement across perimeter zones.
- Air Traffic Control Radar:Monopulse secondary surveillance systems interrogate transponder-equipped aircraft for identity and altitude verification.
Air traffic control radar commands the established base. The steepest expansion runs through imaging radar.
Technology:
Application requirements dictate the trade-off between resolution precision and processing latency across waveform architectures.
- Phased Array:Active electronically scanned arrays steer beams through phase-shifted TR modules without mechanical inertia, enabling track-while-scan engagement of multiple targets. Missile defense programs in the United States and naval modernization in France sustain demand for gallium nitride-backed AESA implementations.
- Frequency Modulated Continuous Wave:Continuous transmission with linear frequency chirps enables simultaneous range and velocity measurement through beat frequency analysis. Automotive Tier-1 suppliers in Germany embed 4D FMCW chips into highway autopilot stacks, replacing legacy corner radars with elevation-capable units.
- Doppler Radar:Frequency shift measurement from moving targets dominates weather and aviation velocity sensing where proven reliability outweighs upgrade urgency.
- Pulsed Wave:Discrete transmission bursts with inter-pulse listening periods maximize detection range for long-horizon surveillance missions.
Doppler radar retains volume leadership across installed aviation and meteorological infrastructure. FMCW technology is climbing the fastest as NHTSA mandates and UN ECE regulations force 100% automotive radar penetration.
Application:
Customer type determines specification stringency, with defense procurement demanding environmental stress screening that commercial aviation avoids.
- Defense:Integrated command-and-control architectures link radar cueing with interceptor fire control for layered air defense. Sovereign manufacturing requirements in India and technology transfer restrictions under US Export Administration Regulations fragment vendor access across national procurement silos.
- Automotive:Compact solid-state units for automatic emergency braking and adaptive cruise control operate in 76-81 GHz bands allocated by MIIT in China and harmonized by ETSI in Europe.
- Aerospace:Terrain avoidance and weather penetration systems for commercial transport aircraft must demonstrate mean-time-between-failure metrics exceeding 50,000 flight hours.
- Environmental Monitoring:Precipitation radar networks for flood prediction and climate modeling require dual-polarization upgrade paths.
Defense applications absorb the highest unit values. Automotive volume is expanding most quickly as OEMs integrate radar across all vehicle classes.
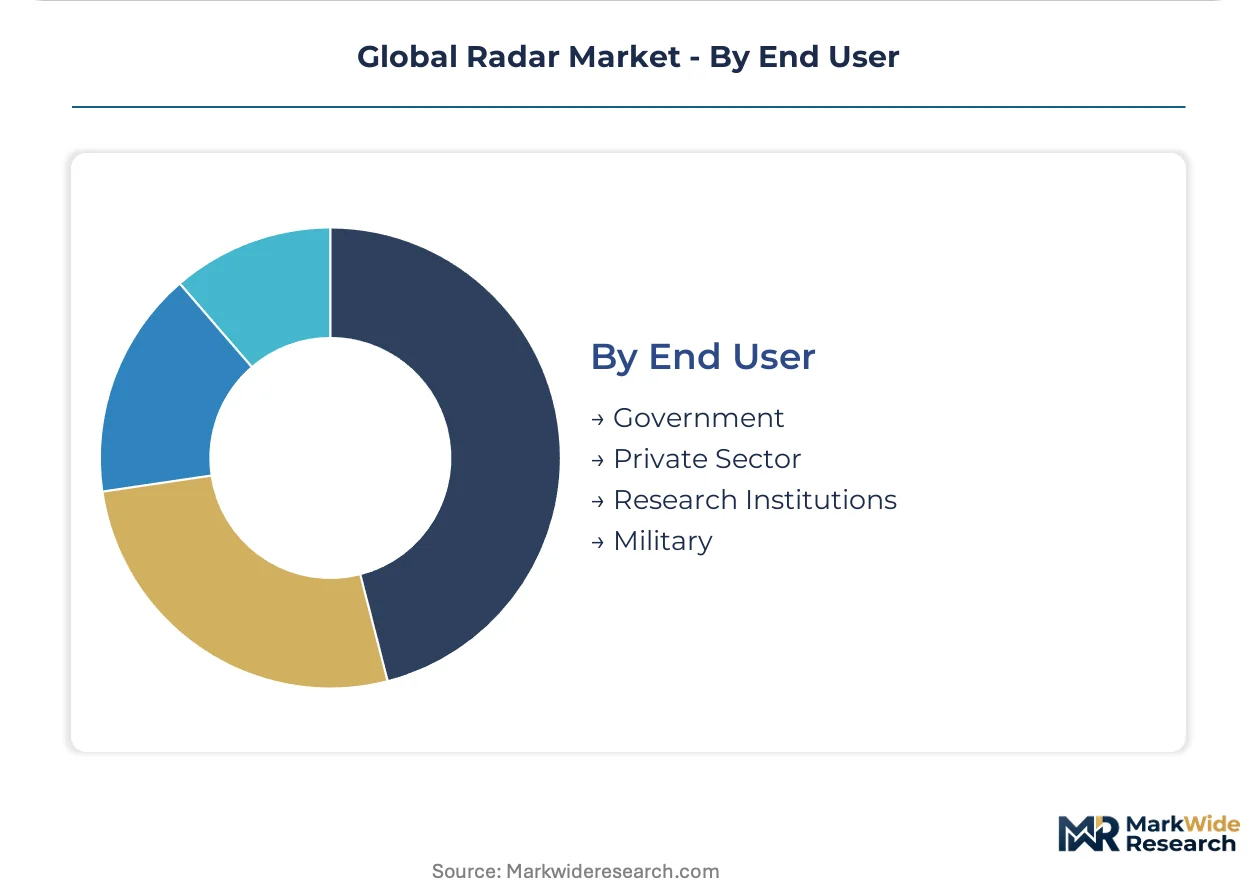
End User:
Procurement authority shapes contract structures, with government tenders favoring cost-plus development and military programs mandating security-cleared supply chains.
- Military:Classified requirements for electronic protection and low-probability-of-intercept waveforms restrict vendor pools to cleared contractors with captive semiconductor fabrication.
- Government:Civil aviation authorities in the United States, Germany, and Japan fund NextGen and equivalent modernization through regulated cost recovery on airport fees.
- Private Sector:Container lines in Greece and Singapore procure navigation sensor packages as hourly service subscriptions, transferring obsolescence risk to integrators.
- Research Institutions:University-led atmospheric science programs operate legacy magnetron systems with limited upgrade budgets.
Military end users dominate value concentration. Private sector procurement is gaining share fastest as maritime operators shift to leased sensor services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA mandates in the United States anchor procurement volume for automotive radar integration, while defense modernization programs and civilian aviation expansion across multiple geographies reshape component supply chains.
United States
Missile defense programs and FAA NextGen mandates drive AESA procurement for military and civilian applications. NHTSA automatic emergency braking requirements force 100% radar penetration across light vehicle production lines. Tucson, Arizona hosts concentrated millimeter-wave engineering talent pools serving both defense primes and automotive Tier-1 suppliers.
China
Domestic automotive production scale and MIIT 76-81 GHz spectrum allocation accelerate homologation for local radar suppliers. Civil aviation expansion through state-owned airport operators sustains secondary surveillance radar demand. Yangtze River Delta clusters in Shanghai and Suzhou concentrate FMCW chip packaging and test capabilities.
Germany
Automotive OEM integration of 4D imaging radar and naval modernization programs sustain dual-use component demand. EU Green Deal aviation efficiency standards compel airport surveillance radar upgrades with 40% power reduction targets. Munich anchors RF engineering expertise for both automotive Tier-1 suppliers and defense electronics divisions.
Japan
Gallium nitride foundry investments in six-inch GaN-on-SiC wafer production compress cost curves for phased array transmit-receive modules. METI industrial policy supports precision manufacturing scale for defense and satellite applications. Nagoya and Osaka industrial corridors concentrate substrate fabrication and radar component assembly operations.
India
Make-in-India indigenization mandates under Defence Procurement Procedures create joint venture slots for foreign GaN foundries to localize TR module production. CEA grid modernization and airport authority expansion drive civil radar procurement. Bengaluru and Hyderabad clusters host defense electronics research institutions and emerging private sector radar integrators.
Global Radar Market Competitive Environment
Capability concentration sits with sovereign defense contractors possessing cleared semiconductor supply chains; scale advantage sits with diversified aerospace conglomerates serving multiple radar technology verticals. The vendor base structures around three tiers: captive foundry operators, software-defined architecture specialists, and platform-agnostic component suppliers. Dominant competitive moves include strategic partnerships for GaN substrate access and geographic expansion through local production mandates in India and Middle Eastern markets.
Within the sovereign defense contractor tier, Raytheon Technologies Corporation and Lockheed Martin Corporation exemplify the capability-concentrated model through captive supply chain control over phased array system production. Thales Group occupies a position bridging European naval modernization programs with dual-use automotive radar component supply. These three entities represent distinct archetypes: the integrated defense prime with semiconductor backward integration, the multi-domain systems integrator with sovereign manufacturing bases, and the transnational electronics house spanning military and civilian certification regimes.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| BAE Systems plc |
| Leonardo S.p.A. |
| Saab AB |
| L3Harris Technologies, Inc. |
| Israel Aerospace Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Nagoya's six-inch GaN-on-SiC wafer fabrication capacity directly determines pricing power for active electronically scanned array manufacturers, with order backlogs extending eighteen months compressing margins for European and Chinese system integrators unable to secure substrate allocations.
Pricing Analysis
Geographic price spreads of thirty to fifty percent separate Japanese-sourced phased array modules from legacy mechanical radar systems procured through secondary markets. Three-tier pricing structure across sovereign-class defense, dual-use commercial aviation, and cost-optimized automotive levels reflects certification grade and environmental stress screening intensity. Pricing pressure stems from NHTSA mandates forcing hundred-percent automotive radar penetration without corresponding component supply elasticity. Tier-1 automotive suppliers exhibit highest price sensitivity due to OEM cost-down targets, while missile defense programs absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
US Export Administration Regulations on synthetic aperture processing algorithms and dual-use radar technology fragment cross-border component flows, forcing non-aligned system vendors toward indigenous development paths. Gallium nitride substrate supply concentrates in Japan and the United States, with silicon carbide wafer blanks drawing from specialty ceramic producers in Germany and the United States. Single-source vulnerability in six-inch GaN-on-SiC wafer supply exposes phased array manufacturers to allocation rationing during demand surges. Distribution runs through cleared defense procurement channels for military applications and Tier-1 supplier direct contracts for automotive integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as NHTSA automatic emergency braking mandates and equivalent UN ECE regulations force sensor penetration rates toward complete OEM coverage across light vehicle production lines.
For Market Incumbents: Entrench through captive gallium nitride foundry investments and software-defined architecture roadmaps that emerging competitors cannot replicate without semiconductor backward integration. Lockheed Martin and Raytheon Technologies demonstrate this model through in-house TR module production insulating margins from substrate supply shocks. Priority lever centers on urban air mobility sensor suite pre-qualification before eVTOL platform standardization freezes vendor selection.
For New Entrants and Emerging Players: India's underpenetrated defense electronics manufacturing base offers joint venture slots under Make-in-India indigenization mandates for foreign GaN foundries seeking localized TR module production. White-space targets include compact solid-state radars for detect-and-avoid systems in German and Chinese eVTOL development programs, plus open RAN-inspired radar back-end architectures enabling third-party waveform application deployment. Go-to-market angle emphasizes software-defined resolution metrics over physical aperture specifications to bypass incumbent hardware advantages.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified aerospace conglomerates with multi-vertical radar exposure spanning defense, automotive, and satellite applications rather than single-domain specialists facing demand cyclicality. Long-term viability rests on gallium nitride substrate supply security and cross-certification across FAA, EASA, and MIIT regulatory regimes. Signal to watch: eighteen-month order backlog duration at Japanese foundries as inflection indicator for supply-constrained pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Joint Venture | Localizes TR module production under India's Defence Procurement Procedures indigenization mandates. |
| Software-Defined Radar Architecture | Enables post-deployment performance upgrades through computational beam synthesis rather than hardware replacement. |
| eVTOL Sensor Suite Pre-Qualification | Captures greenfield avionics category before detect-and-avoid system standardization locks vendor positions. |
| Open RAN Backend Integration | Disintermediates proprietary stack vendors through third-party waveform application marketplaces. |
| Dual-Use Certification Investment | Spans military and civilian aviation regimes to diversify revenue across defense procurement cycles. |
Study Parameters
A spread of perspectives from radar system procurement officers at defense primes, GaN foundry operations managers, automotive Tier-1 supplier platform engineers, and FAA certification leads converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, defense contract award databases, and MIIT spectrum allocation notices. Bottom-up triangulation across product type, technology architecture, application vertical, and end-user procurement authority anchored the segmentation framework.
Demand-supply balance modeling across the analysis window integrated automotive OEM production schedules, defense modernization program timelines, and gallium nitride substrate capacity expansion plans. Segmentation dimensions included product architecture maturity, waveform technology, application criticality, and regional regulatory cluster. CAGRs derived from slope analysis of adoption curves and procurement velocity patterns, with specific inputs from NHTSA mandate compliance deadlines and EU Green Deal aviation efficiency standard implementation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed radar integrators or unexpected relaxation of US Export Administration Regulations would shift outcomes. Material shifts in gallium nitride substrate supply concentration or cross-border technology transfer control stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Radar Market