
 Hydrographic Survey Equipment Market | 2026-2036
Hydrographic Survey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrographic Survey Equipment Market Intelligence
Software-defined beamforming and subscription-based hydrographic processing suites are pivoting how survey contractors monetize their capabilities. Kongsberg Gruppen ASA leverages its integrated platform spanning sonar hardware to cloud analytics, sustaining pricing power across full project lifecycles. Teledyne Technologies Inc. competes through dense R&D allocation toward autonomous underwater vehicle payloads. Sonardyne International Ltd. anchors its position in underwater positioning through tight integration with offshore energy installation workflows.
Hydrographic survey equipment encompasses acoustic, optical, and satellite-linked instrumentation engineered to measure water depth, seabed topography, and submerged object detection—typically resolving bathymetric features to centimeter-scale accuracy using multibeam echo sounders operating across 12 kHz to 400 kHz frequency bands. The equipment serves commercial navigation safety, offshore resource extraction planning, and marine infrastructure engineering. Multibeam echo sounders command the largest product type share due to their sweep efficiency in port development and coastal mapping assignments. Acoustic sensing technology leads the technology dimension while hydrographic software captures expanding margin pools as vessel operators seek post-processing automation. Marine construction and oil & gas end users drive replacement cycles tied to project sanctioning timelines.
The International Hydrographic Organization coordinates national standards for nautical chart accuracy that directly shape equipment procurement specifications among government hydrographic offices. The EPA enforces coastal zone management requirements in the United States that mandate pre-construction seabed surveys for dredging permits and marine infrastructure approvals. ISO 9001 and IEC 60945 certification frameworks govern product quality and electromagnetic compatibility for marine electronics, filtering market access for non-compliant suppliers. Stakeholders must monitor how autonomous vessel classification societies adapt certification rules for unmanned survey platforms, as this will determine which sensor manufacturers capture emerging naval and commercial fleet retrofit demand.
Market Dynamics
Software-defined beamforming architectures are compressing hardware refresh cycles while forcing legacy analog system obsolescence across government hydrographic offices and commercial survey contractors.
Growth Catalysts
- Offshore wind seabed characterization mandates:Developers in the North Sea and US Atlantic coast require multibeam systems for foundation planning, creating sustained equipment procurement pipelines.
- IHO S-102 bathymetric surface standards:The International Hydrographic Organization's tightening accuracy specifications for electronic navigational charts force national hydrographic services into sensor upgrades.
- Cloud-native processing subscriptions:Survey contractors monetize post-processing capabilities through recurring revenue models rather than perpetual license sales.
Market Restraints
- Transducer ceramic supply concentration:Piezoelectric material sourcing clusters in East Asian manufacturing hubs, exposing lead times to geopolitical friction.
- High-frequency acoustic attenuation limits:Multibeam systems above 200 kHz suffer rapid signal degradation in turbid coastal waters, constraining certain port survey applications.
- Specialized vessel charter costs:Mobilization expenses for dynamically positioned survey ships consume 40-60% of project budgets, squeezing equipment procurement margins.
Strategic Opportunities
- Autonomous surface vehicle integration:Uncrewed platforms reduce day-rate exposure while expanding survey coverage in hazardous or remote maritime zones.
- Marine mineral exploration licensing:Pacific island nations and the International Seabed Authority are issuing seabed mining exploration contracts requiring baseline bathymetric mapping.
- Subscription-based fleet analytics:Equipment manufacturers can capture recurring revenue through vessel performance optimization software layered atop sensor hardware.
Industry Challenges
- Multibeam data processor talent scarcity:Specialized hydrographers capable of quality-assuring S-44 compliant surveys command premium compensation, constraining contractor scaling.
- IEC 60945 electromagnetic compatibility certification timelines:Marine electronics approval processes extend 12-18 months, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrographic Survey Equipment Market |
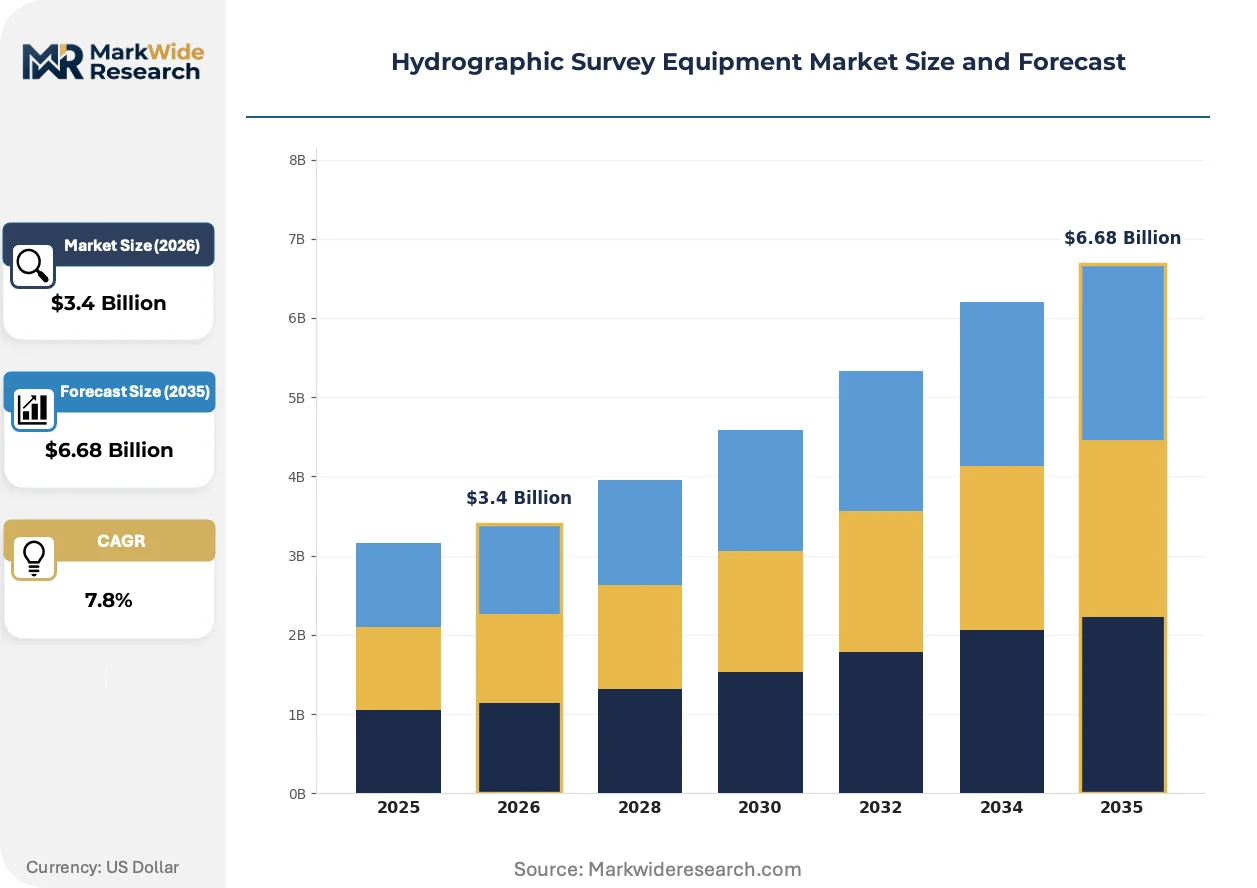
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multibeam Echo Sounders, Single Beam Echo Sounders, GNSS Equipment, Underwater Positioning Systems Technology: Acoustic Sensing, Laser Scanning, Magnetometer, Hydrographic Software End User: Governments, Environmental Agencies, Marine Construction, Oil & Gas Application: Coastal Mapping, Dredging Operations, Marine Research, Port Development |
| Companies Covered | Sonardyne International Ltd., Innomar Technologie GmbH, Kongsberg Gruppen ASA, Tritech International Ltd., Syqwest Inc., Teledyne Technologies Inc., iXblue SAS, Valeport Ltd., EdgeTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrographic Survey Equipment Market Strategic Shifts & Innovations
Acoustic sensing architectures are fragmenting into modular, software-configurable platforms that decouple hardware from processing workflows. This shift compresses innovation cycles while opening entry points for specialized subsystem suppliers.
Multibeam echo sounders with frequency-agile transmission are expanding into shallow-water renewable energy site surveys. Offshore wind developers in the Baltic Sea and US Northeast deploy these systems for cable route engineering. The technology is expanding into territories previously served by single-beam equipment, compressing the addressable market for legacy analog sonar.
The EPA's coastal zone management enforcement in the United States mandates pre-construction seabed surveys for dredging permits and marine infrastructure approvals. This regulatory pressure forces port authorities and energy developers into compliant multibeam procurement. Civil engineering contractors now embed hydrographic survey specifications directly into project tender documents.
Equipment-as-a-service contracting is displacing capital purchase models among mid-size survey operators. Norwegian and UK-based contractors now lease integrated sensor packages with bundled cloud processing. This pattern concentrates most visibly in the North Sea offshore wind supply chain, where project-based financing favors operational expenditure structures over asset ownership.
Hydrographic Survey Equipment Market Segmentation
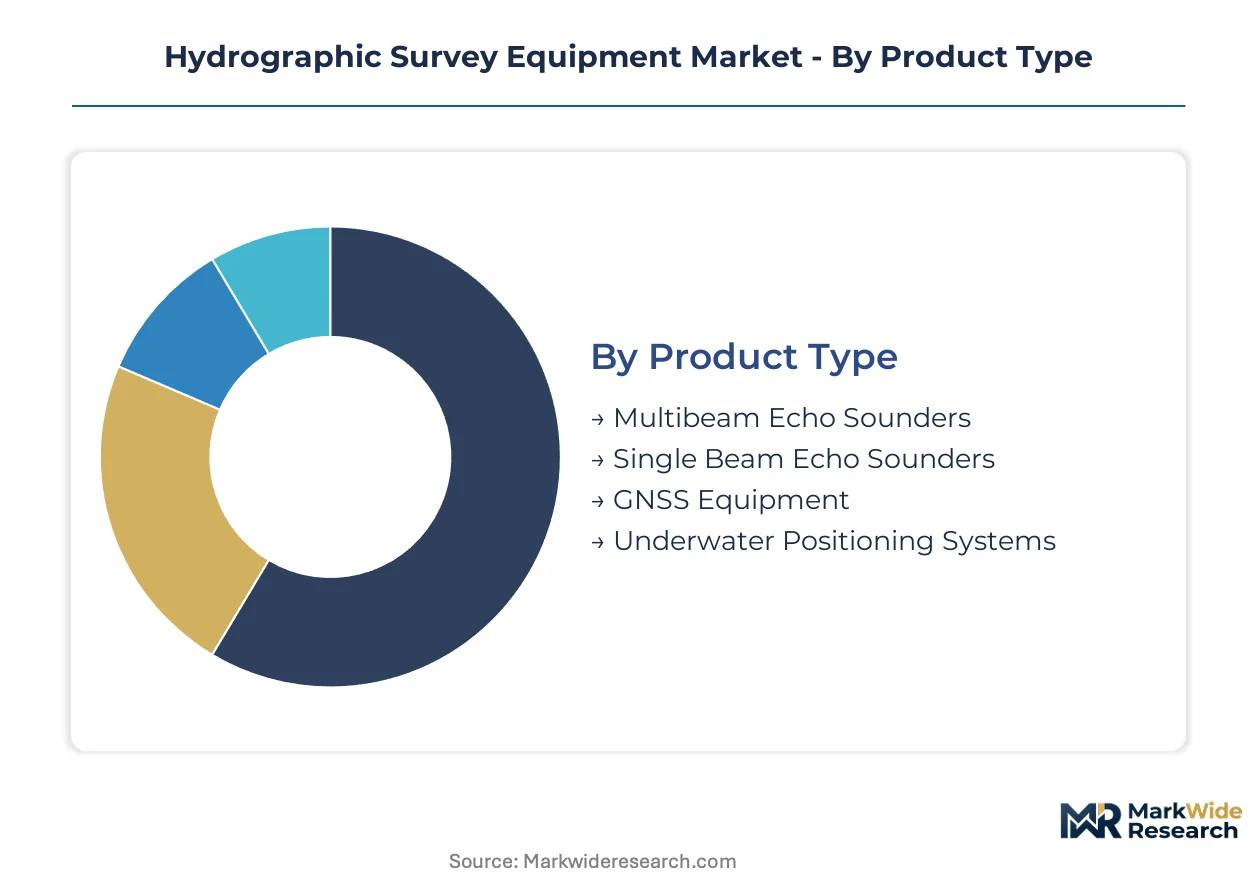
Equipment segmentation in hydrographic surveying reflects divergent capital deployment strategies across project types. Contractors prioritize sweep efficiency and data density when allocating procurement budgets across sensor categories.
Product Type:
Multibeam echo sounders demand the heaviest upfront capital outlay due to transducer array complexity and vessel integration requirements.
- Multibeam Echo Sounders:Frequency-agile systems operating across 12 kHz to 400 kHz bands deliver centimeter-scale bathymetric resolution through electronically steered beam arrays. Norwegian offshore wind developers in the North Sea anchor procurement volumes as foundation planning mandates intensify seabed characterization requirements.
- Single Beam Echo Sounders:Narrow-beam analog systems persist in shallow-water reconnaissance and riverine surveys where sweep density requirements remain modest. Demand concentrates among government hydrographic offices in the United States and United Kingdom maintaining legacy vessel fleets.
- GNSS Equipment:Differential satellite positioning hardware enables georeferenced survey tracks with sub-decimeter accuracy.
- Underwater Positioning Systems:Acoustic transponder networks establish three-dimensional reference frames for subsea construction monitoring.
Most installed capacity flows through multibeam echo sounders. Expansion is steepest in underwater positioning systems as autonomous platform deployment accelerates.
Technology:
Technology selection tracks the trade-off between penetration depth and spatial resolution in target water columns.
- Acoustic Sensing:Sonar-based measurement dominates commercial applications through proven performance in turbid conditions. Oil and gas operators in the US Gulf of Mexico and Brazil's Santos Basin drive replacement cycles tied to subsea infrastructure inspection schedules.
- Laser Scanning:Airborne and vessel-mounted lidar systems capture shoreline topography and near-surface bathymetry in clear water conditions. Baltic Sea coastal mapping programs in Denmark and Germany absorb specialized airborne units for intertidal zone surveys.
- Magnetometer:Magnetic anomaly detection locates submerged ferrous objects including pipelines and unexploded ordnance.
- Hydrographic Software:Cloud-native processing suites monetize post-processing automation through recurring subscription structures.
Acoustic sensing carries the largest installed base. Hydrographic software is gaining share fastest as contractors shift from perpetual licenses to operational expenditure models.
End User:
End user segmentation correlates with procurement authority centralization and project financing structures.
- Governments:National hydrographic services maintain fleet-wide sensor inventories subject to IHO S-102 compliance mandates. The United Kingdom Hydrographic Office and NOAA's Office of Coast Survey in the United States anchor institutional demand through mandated chart modernization programs.
- Environmental Agencies:Regulatory bodies commission baseline surveys for marine protected area designation and pollution monitoring. The EPA's coastal zone management enforcement in the United States mandates pre-construction seabed assessments for dredging permit approvals.
- Marine Construction:Civil engineering contractors embed survey specifications directly into project tender documents.
- Oil & Gas:Offshore operators require bathymetric data for pipeline route engineering and platform site selection.
Government procurement dominates unit volumes. Environmental agencies are expanding fastest as regulatory survey mandates proliferate.
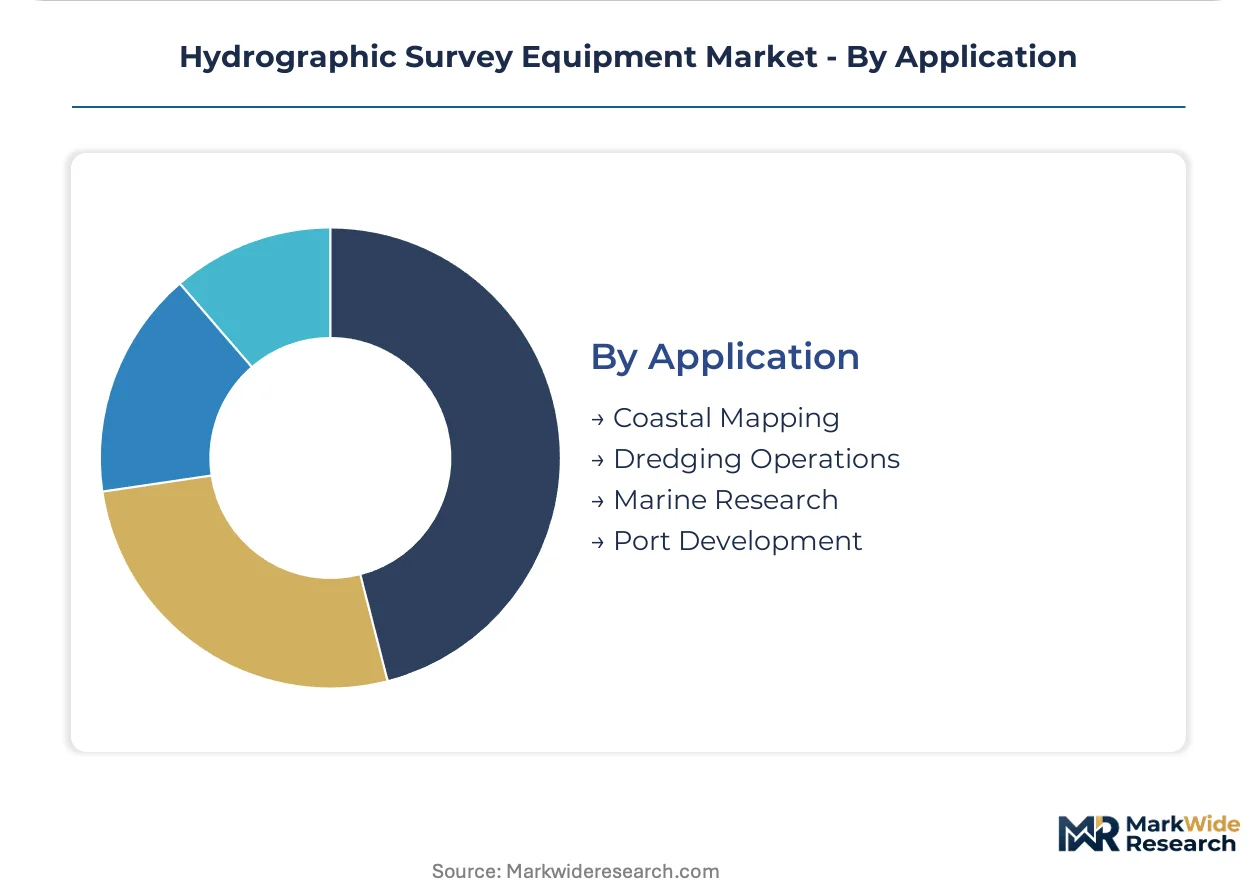
Application:
Application segmentation reflects water depth regimes and regulatory oversight intensity.
- Coastal Mapping:Nearshore bathymetric surveys support nautical chart updates and storm surge modeling. The International Hydrographic Organization's tightening accuracy specifications force national services into sensor refresh cycles.
- Port Development:Harbor deepening and expansion projects require high-density multibeam coverage for dredge volume calculations. Rotterdam and Singapore port authorities maintain dedicated survey vessels with integrated sensor packages.
- Dredging Operations:Pre- and post-dredge surveys verify contract fulfillment and environmental compliance.
- Marine Research:Academic institutions deploy portable systems for habitat mapping and geological sampling.
Port development absorbs the largest equipment budgets. Coastal mapping is climbing the fastest as IHO standards tighten worldwide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands premium equipment procurement through its offshore wind cluster, while the United States channels demand through regulatory enforcement and port modernization mandates. Equipment flows concentrate where seabed characterization requirements intersect with project financing availability.
Norway
North Sea offshore wind developers drive multibeam system procurement for foundation planning and cable route surveys. The Norwegian Maritime Authority enforces strict electronic navigational chart standards aligned with IHO S-102 specifications. Kongsberg's headquarters near Oslo anchors a dense supplier network spanning transducer manufacturing to cloud analytics integration.
United States
Atlantic coast offshore wind leasing and Gulf of Mexico subsea infrastructure inspection sustain equipment replacement cycles. EPA coastal zone management enforcement mandates pre-construction seabed surveys for dredging permits and marine infrastructure approvals. Houston and New Orleans harbor specialized survey vessel operators serving oil and gas route engineering contracts.
United Kingdom
The UK Hydrographic Office maintains fleet-wide sensor inventories subject to mandated chart modernization programs. Maritime and Coastguard Agency regulations tighten accuracy specifications for port approach surveys. Aberdeen and Southampton concentrate survey contractors serving North Sea decommissioning and English Channel port expansion projects.
Germany
Baltic Sea offshore wind site characterization and coastal mapping programs absorb specialized airborne lidar and multibeam units. Federal Maritime and Hydrographic Agency standards enforce IHO-compliant bathymetric surface requirements for commercial navigation safety. Rostock and Hamburg host integrated vessel-sensor packages dedicated to harbor deepening and intertidal zone surveys.
China
South China Sea marine infrastructure development and port expansion projects drive acoustic sensing procurement. Ministry of Natural Resources regulations govern seabed survey standards for coastal engineering approvals. Shanghai and Tianjin concentrate state-owned survey fleets serving Yangtze River Delta port modernization and submarine cable installation workflows.
Hydrographic Survey Equipment Market Key Industry Players
Top-tier vendors anchor integrated platform strategies, while mid-scale specialists compete through subsystem modularity and regional service density. The vendor base stratifies across full-stack hardware-to-software providers, autonomous vehicle payload developers, and underwater positioning specialists. Three archetypes dominate: integrated maritime technology conglomerates, precision acoustic sensor fabricators, and cloud-native processing suite operators. Competitive moves concentrate on strategic partnerships for uncrewed platform integration and geographic expansion through local survey contractor alliances.
Among European maritime technology groups, Kongsberg Gruppen ASA, Sonardyne International Ltd., and Innomar Technologie GmbH exemplify differentiated positioning archetypes. Kongsberg Gruppen ASA occupies the integrated platform tier spanning sonar hardware through analytics. Sonardyne International Ltd. anchors underwater positioning specialization tied to offshore energy installation workflows. Innomar Technologie GmbH represents the precision acoustic fabricator archetype with focused parametric sub-bottom profiler engineering. Teledyne Technologies Inc. and iXblue SAS sit within the autonomous and precision navigation tier respectively, while Tritech International Ltd., Syqwest Inc., Valeport Ltd., and EdgeTech populate specialized sensor and software subsegments.
| Leading Market Players |
|---|
| Sonardyne International Ltd. |
| Innomar Technologie GmbH |
| Kongsberg Gruppen ASA |
| Tritech International Ltd. |
| Syqwest Inc. |
| Teledyne Technologies Inc. |
| iXblue SAS |
| Valeport Ltd. |
| EdgeTech |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between IHO S-102 compliant multibeam systems and legacy analog equipment manifests in procurement budgets and supplier network configurations. Norwegian offshore wind developers pay substantial premiums for Kongsberg-integrated packages with cloud analytics, while government hydrographic offices in the United States and United Kingdom stretch replacement cycles on non-compliant single-beam inventories. This bifurcation concentrates margin capture among full-stack platform vendors while compressing pricing power for subsystem specialists lacking vessel integration capabilities.
Pricing Analysis
Capacity additions in China's transducer manufacturing hubs are reshaping price floors for mid-frequency multibeam arrays. Equipment-as-a-service contracting now dominates among North Sea survey contractors, converting capital expenditure into operational expenditure with bundled processing subscriptions. Price differentiation hinges on IEC 60945 certification tier and software-defined beamforming capability. Cost compression in standard-grade single-beam systems is intensifying because of software-defined obsolescence, while government hydrographic offices remain least price-sensitive due to mandated compliance timelines.
Supply Chain Analysis
Specialized hydrographer scarcity in Norway and the United Kingdom constrains transducer calibration and vessel integration throughput. Piezoelectric ceramic sourcing draws from East Asian manufacturing clusters, with final assembly concentrated in Norway, the United Kingdom, and Germany. Magnetometer sensors and GNSS receivers feed from United States and Swiss precision electronics suppliers. Single-source vulnerability in high-purity piezoelectric materials exposes lead times to geopolitical friction. Distribution runs through authorized marine electronics distributors serving port authorities and offshore energy contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrographic survey equipment market compounds steadily through regulatory ratchet effects. IHO S-102 mandates force recurring sensor refresh cycles regardless of commodity cycles, embedding predictable replacement demand.
For Market Incumbents: Deploy software-defined platform roadmaps to accelerate hardware obsolescence among analog system competitors. Capture recurring revenue through cloud-native processing subscriptions layered atop sensor hardware. Backward integration into transducer ceramic supply buffers East Asian sourcing concentration. Defend against autonomous vehicle payload specialists by pre-integrating sensor packages with uncrewed surface vessel control architectures.
For New Entrants and Emerging Players: Frequency-agile shallow-water multibeam architectures offer entry points into Baltic Sea and US Atlantic offshore wind site surveys previously served by single-beam equipment. Marine mineral exploration licensing in Pacific island jurisdictions presents white-space demand for portable seabed mapping packages. Target environmental agencies with subscription-based fleet analytics for vessel performance optimization, bypassing capital-intensive vessel integration requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized hydrographer talent scarcity constrains contractor scaling. The market supports 5-10 year compound growth through regulatory compliance mandates independent of energy price volatility. Acquisition targets should display underwater positioning specialization with tight offshore energy workflow integration or cloud-native processing suites with recurring revenue structures. Monitor autonomous vessel classification society rulemaking as inflection signal for naval and commercial fleet retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Beamforming Platform | Kongsberg and Teledyne accelerate hardware refresh cycles through configurable acoustic architectures. |
| Autonomous Surface Vehicle Integration | Uncrewed platforms reduce day-rate exposure while expanding survey coverage in hazardous maritime zones. |
| Cloud-Native Processing Subscription | Recurring revenue models displace perpetual licenses among North Sea and UK-based survey contractors. |
| Marine Mineral Exploration Licensing | Pacific island nations and International Seabed Authority contracts require baseline bathymetric mapping equipment. |
| IHO S-102 Certification Investment | National hydrographic services in the United Kingdom and United States face mandated sensor upgrade timelines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged hydrographic survey contractors, national hydrographic office procurement directors, offshore wind project developers, marine electronics distributors, and autonomous vessel classification specialists. Secondary validation drew from IHO S-102 and S-44 standard documentation, EPA coastal zone management enforcement records, IEC 60945 certification registries, and Norwegian Maritime Authority equipment approval databases. Bottom-up vessel fleet sensor inventories were triangulated against top-down market size estimates from government chart modernization program budgets.
Segment-weighting approaches distributed value across product type, technology, end user, and application dimensions. Multibeam echo sounder, single-beam, and underwater positioning system categories were modeled separately with technology splits across acoustic sensing, laser scanning, and hydrographic software. End-user weights reflected government, environmental agency, marine construction, and oil and gas procurement authority structures. CAGRs were derived from project sanctioning timelines and regulatory compliance cycle analysis. Forecast inputs incorporated offshore wind foundation planning mandates and autonomous platform deployment acceleration curves.
The model holds under steady IHO standard enforcement and continued offshore wind leasing velocity; deviation in autonomous vessel classification timelines or transducer ceramic supply disruption would shift equipment procurement patterns. Practitioners should monitor International Seabed Authority exploration contract issuance and Baltic Sea cable route engineering commencements for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
UXO Detection Market
Military Surveillance
Global Military Thermal Imaging Market