
 Asia Pacific Electrically Powered Hydraulic Steering Market | 2026-2036
Asia Pacific Electrically Powered Hydraulic Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electrically Powered Hydraulic Steering Market Outlook
China's MIIT dual carbon goals is hardening emission benchmarks for automotive suppliers across the Asia Pacific region. JTEKT Corporation leverages its integrated manufacturing base in Japan to sustain precision steering output for regional OEM programs. Hyundai Mobis anchors its competitive position through captive supply relationships with Korean vehicle assemblers. ZF Friedrichshafen AG differentiates via advanced electromechanical architectures serving premium vehicle platforms.
Electrically powered hydraulic steering combines an electric motor-driven pump with conventional hydraulic actuation, typically operating at voltages between 12V and 48V to reduce parasitic engine load versus traditional belt-driven pumps. The system modulates hydraulic pressure on demand, cutting fuel consumption in commercial and passenger vehicle applications. EPS technology dominates current installations across passenger cars and light commercial vehicles, while hybrid EPS configurations capture expanding share in heavy trucks where load-bearing requirements persist. OEMs represent the primary demand channel, with vehicle assemblers in China and India driving volume procurement for compact cars and crossovers.
Japan's METI enforces stringent efficiency standards that shape product certification requirements for steering system suppliers. India's BIS mandates compliance with automotive component energy ratings, while China's SAMR oversees GB standards for electromechanical safety in vehicle subsystems. Regulatory divergence across these frameworks compels manufacturers to maintain multiple certification pathways. Stakeholders must monitor how China's evolving GB standards for intelligent connected vehicles integrate steering system cybersecurity protocols.
Market Dynamics
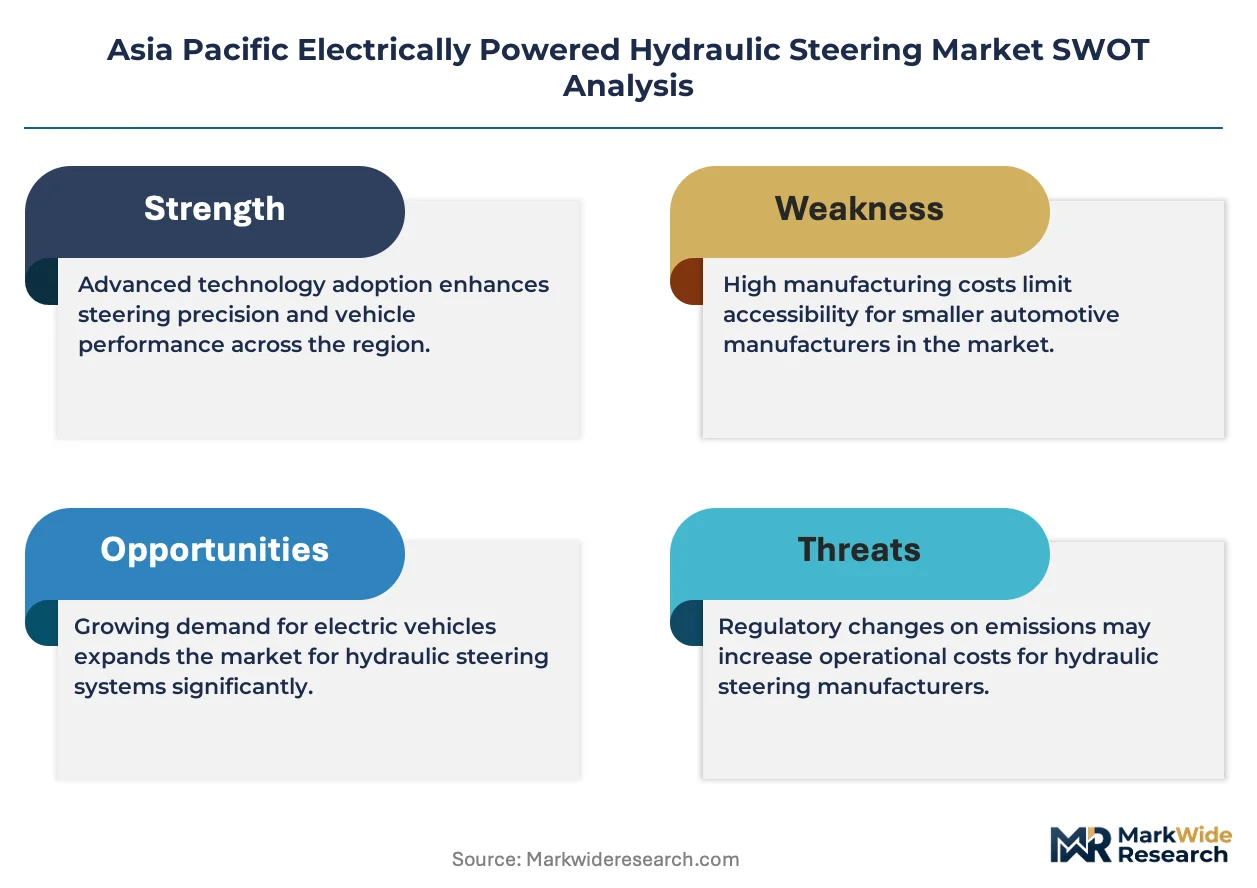
China's MIIT dual carbon goals are hardening emission benchmarks across automotive supply chains, forcing steering system suppliers to redesign hydraulic architectures for electrified powertrains while maintaining load-bearing performance in heavy commercial vehicles.
Growth Catalysts
- China's MIIT dual carbon goals:These mandates compress emission thresholds for automotive components, compelling OEMs to source electrically powered hydraulic steering systems that reduce parasitic engine load versus belt-driven alternatives.
- Commercial vehicle fleet expansion:Procurement managers in India and Southeast Asia are prioritizing fuel-efficient steering systems as diesel costs escalate and total cost of ownership calculations tighten.
- Eastern manufacturing corridor concentration:Demand clusters across Shanghai, Jiangsu, and Zhejiang provinces create procurement density that justifies localized supplier investment and shortens fulfillment cycles.
Market Restraints
- Copper and rare earth price volatility:Electric motor windings and permanent magnets face input cost swings that compress supplier margins and destabilize long-term contract pricing.
- Single-source hydraulic component concentration:Precision valve manufacturing remains concentrated among Japanese and German suppliers, exposing assemblers to geopolitical friction and shipping disruption.
- Full-electric EPS substitution threat:Rack-assist EPS systems are penetrating mid-duty truck segments where hybrid hydraulic-electric architectures previously dominated, narrowing the addressable window.
Strategic Opportunities
- India's BIS energy efficiency mandates:Component rating requirements create certified-supplier preference systems that reward early compliance with procurement preference in government and fleet tenders.
- 48V mild-hybrid integration:Convergence of electrically powered hydraulic steering with 48V electrical architectures enables energy recuperation and opens architecture standardization opportunities.
- Indonesia and Vietnam commercial vehicle growth:Underpenetrated ASEAN markets exhibit accelerating truck and bus assembly that lacks established steering supply relationships.
Industry Challenges
- Mechatronics engineering scarcity:Suppliers struggle to hire engineers capable of integrating hydraulic fluid dynamics with motor control algorithms and embedded software.
- Multi-jurisdiction certification timelines:Parallel BIS, GB, and METI approval processes extend product launch schedules and fragment engineering resources across documentation requirements.
- Legacy hydraulic system integration:Retrofit compatibility with existing chassis architectures demands custom calibration protocols that strain technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electrically Powered Hydraulic Steering Market |
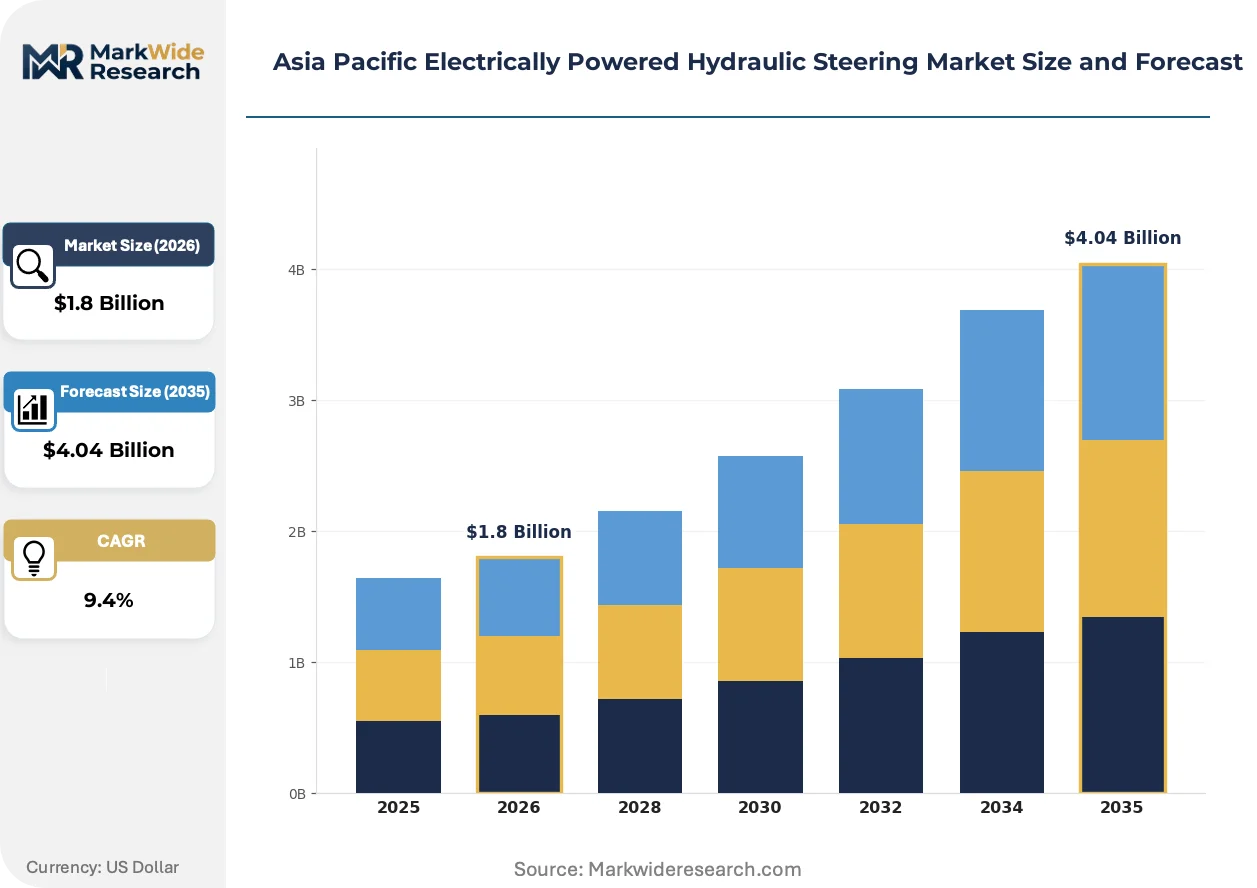
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: EPS, HPS, Hybrid EPS, Other End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Buses Application: Luxury Vehicles, Compact Cars, SUVs, Crossovers |
| Companies Covered | JTEKT Corporation, Nexteer Automotive Group, ZF Friedrichshafen AG, NSK Ltd., Robert Bosch GmbH, Denso Corporation, Hyundai Mobis, Mitsubishi Electric Corporation, Hitachi Astemo, Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electrically Powered Hydraulic Steering Market Strategic Shifts
Steering system electrification is bifurcating the market between full-electric EPS architectures and hybrid hydraulic-electric configurations, with voltage platform choices and thermal management strategies becoming decisive competitive variables.
Variable displacement electric pumps are electrifying steering energy management by modulating hydraulic pressure on demand rather than circulating fluid continuously. Heavy truck assemblers in China and India are adopting these units fastest where load-bearing requirements persist. This architecture is electrifying the competitive boundary between traditional hydraulic suppliers and electromechanical specialists.
Japan's METI efficiency standards are tightening certification thresholds for steering system suppliers serving the Asia Pacific region. The industrial consequence is accelerated R&D spending on motor-inverter integration and reduced hydraulic fluid volumes. Commercial vehicle platforms face the steepest compliance burden, with Japanese and Korean OEMs responding through captive supplier development programs.
Fleet procurement managers are consolidating steering system sourcing through vehicle-assembler direct contracts rather than aftermarket distribution channels. This disintermediation compresses supplier margins but secures volume commitments and design-in relationships. The pattern is most visible in India's organized logistics sector and China's e-commerce delivery fleet operators.
Asia Pacific Electrically Powered Hydraulic Steering Market Segmentation
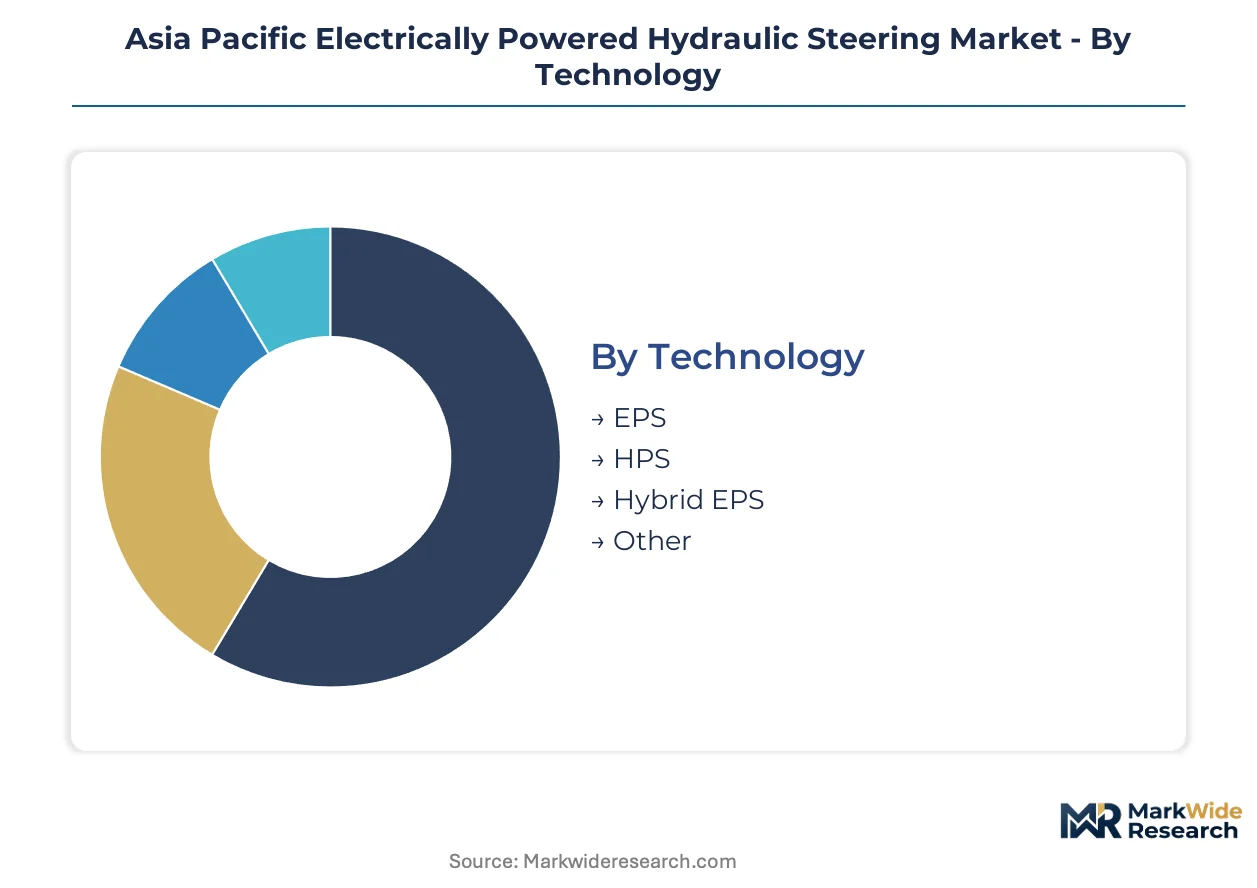
Technology architecture choices determine voltage platform selection and thermal management requirements across the Asia Pacific electrically powered hydraulic steering market. End-user procurement patterns and vehicle duty cycles further stratify demand concentration and supplier qualification pathways.
Technology:
Voltage platform and actuation method define the competitive boundary between full-electric and hybrid hydraulic architectures.
- EPS:Rack-assist and column-assist configurations operate at 12V-48V, eliminating hydraulic fluid entirely. Passenger car OEMs in China and India source these for compact cars and crossovers where load-bearing requirements are modest.
- HPS:Conventional belt-driven hydraulic pumps persist in legacy commercial vehicle platforms where retrofit economics delay electrification. Fleet operators in Southeast Asia maintain these systems through aftermarket channels.
- Hybrid EPS:Electric motor-driven hydraulic pumps modulate pressure on demand, cutting parasitic load while retaining load-bearing capacity. Heavy truck assemblers in China's eastern manufacturing corridor adopt these fastest for diesel cost reduction.
- Other:Experimental steer-by-wire prototypes and integrated chassis control modules serve premium vehicle development programs.
Hybrid EPS leads on scale; Hybrid EPS leads on momentum.
End User:
Procurement authority concentration shapes pricing power and design-in relationships across the value chain.
- OEMs:Vehicle brand owners in China and Korea direct steering system specification through platform engineering teams. MIIT dual carbon compliance deadlines compress their supplier selection timelines.
- Tier-1 Suppliers:System integrators like JTEKT Corporation and Hyundai Mobis manage multi-component sourcing and calibration protocols. Their captive relationships with assemblers lock out independent component vendors.
- Aftermarket Providers:Independent distributors serve fleet maintenance operations in India's organized logistics sector. BIS energy efficiency rating requirements now govern their certified product catalogs.
- Vehicle Assemblers:Contract manufacturers without full engineering authority rely on Tier-1 steering system packages for bus and truck production in Indonesia and Vietnam.
OEMs dominate procurement volume; Tier-1 Suppliers capture margin concentration.
Vehicle Type:
Duty cycle severity determines hydraulic retention versus full-electric substitution economics.
- Passenger Cars:Full-electric EPS architectures have displaced hybrid systems across China's compact car segment. METI efficiency standards in Japan accelerate motor-inverter integration R&D for this category.
- Light Commercial Vehicles:Vans and small trucks in India's e-commerce delivery fleets balance payload requirements with fuel economy targets. 48V mild-hybrid steering integration is climbing fastest here.
- Heavy Trucks:Load-bearing demands preserve hybrid hydraulic-electric architectures. Chinese assemblers face the steepest MIIT emission compliance burden for this segment.
- Buses:Urban transit operators in Southeast Asia prioritize steering system durability over energy efficiency. Procurement runs through municipal tender processes with extended service contracts.
Passenger Cars anchor volume; Light Commercial Vehicles show steepest expansion trajectory.
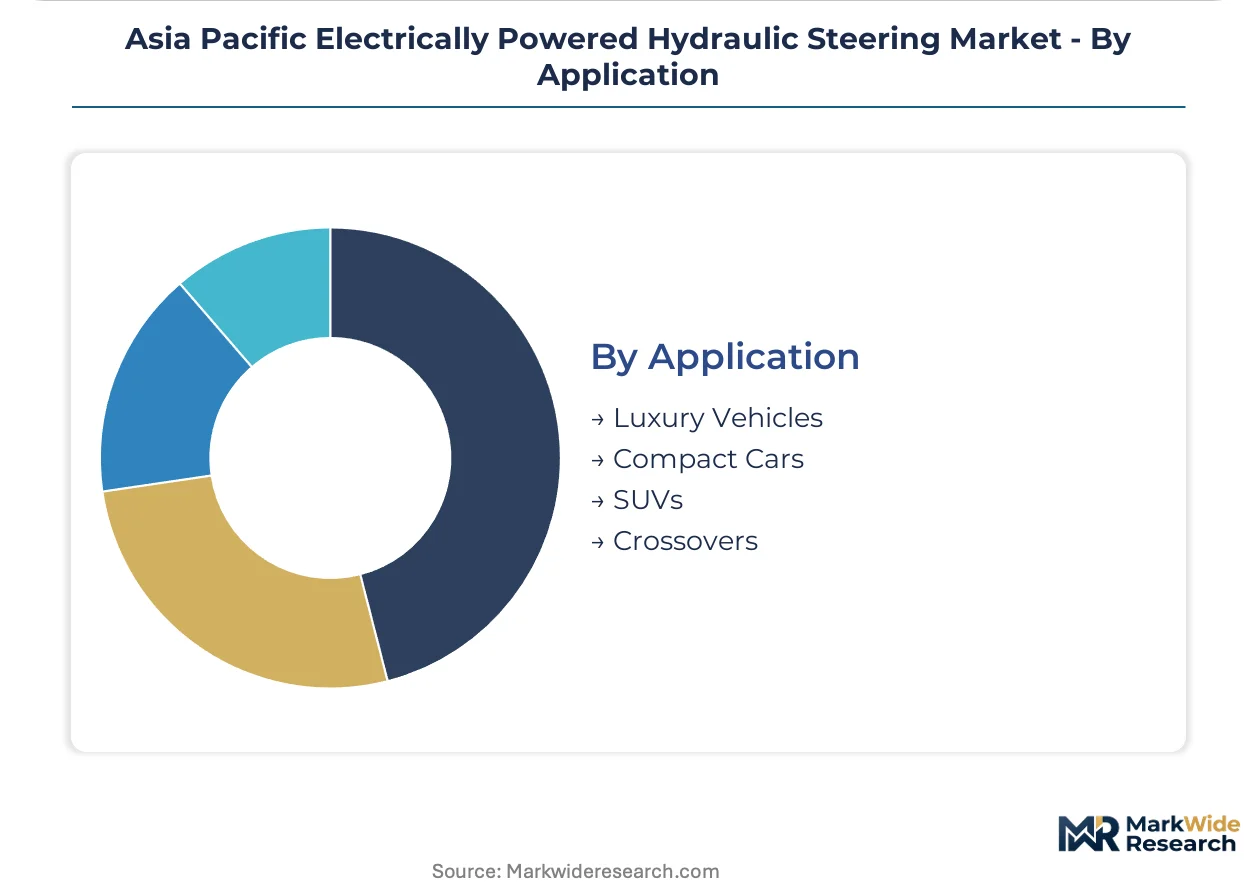
Application:
Price positioning and performance tier stratify technology adoption timelines.
- Luxury Vehicles:Premium OEMs specify advanced electromechanical architectures with integrated chassis control. ZF Friedrichshafen AG serves this tier through differentiated 48V system designs.
- Compact Cars:Cost-sensitive assemblers in China and India source standardized 12V EPS units through high-volume contracts. Procurement density in Shanghai and Jiangsu provinces shortens fulfillment cycles.
- SUVs:Higher curb weights sustain hybrid hydraulic-electric demand longer than in passenger cars. Korean OEMs respond through captive supplier development programs.
- Crossovers:Blended passenger-commercial duty cycles create specification complexity. Fleet procurement managers consolidate sourcing through direct assembler contracts rather than aftermarket channels.
Compact Cars lead on unit scale; Crossovers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics engineering clusters in Shanghai, Nagoya, and Seoul anchor steering system design capacity across the region. Foundry networks in Jiangsu and Zhejiang provinces supply precision hydraulic components to assemblers throughout East Asia. Talent pipelines from Tsinghua University, Tokyo Institute of Technology, and KAIST feed R&D programs at major Tier-1 suppliers.
China
MIIT dual carbon mandates compress emission thresholds for heavy truck steering systems. SAMR oversees evolving GB standards for electromechanical safety and intelligent connected vehicle cybersecurity. Shanghai-Jiangsu-Zhejiang manufacturing corridor concentrates procurement density for hybrid EPS architectures serving domestic OEMs.
Japan
METI efficiency standards harden certification requirements for motor-inverter integration in steering systems. JIS standards govern precision valve manufacturing specifications for regional export markets. Nagoya-Tokyo industrial belt hosts integrated manufacturing bases serving Korean and Chinese vehicle assemblers.
India
BIS energy efficiency mandates create certified-supplier preference systems for fleet procurement. Organized logistics sector operators consolidate sourcing through direct assembler contracts rather than aftermarket channels. Maharashtra and Tamil Nadu assembly plants drive volume demand for compact car and light commercial vehicle steering units.
South Korea
MFDS automotive component standards align with METI frameworks for regional export compatibility. Captive supply relationships between Tier-1 integrators and domestic vehicle assemblers lock out independent component vendors. Seoul-Incheon corridor concentrates R&D investment in 48V mild-hybrid steering architectures.
Vietnam
Commercial vehicle assembly growth lacks established steering supply relationships, creating procurement opportunity. General functional descriptors for national industrial policy guide foreign supplier establishment protocols. Northern industrial zones around Hai Phong and Bac Ninh attract component sourcing investment from Chinese Tier-1 suppliers.
Asia Pacific Electrically Powered Hydraulic Steering Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia Pacific electrically powered hydraulic steering market. Integrated manufacturing specialists with captive foundry capacity face pressure from modular system integrators outsourcing precision valve production. Three archetypes dominate: Japanese-Korean conglomerates with captive OEM relationships, German electromechanical specialists serving premium platforms, and Chinese domestic suppliers capturing state-mandated localization requirements. Dominant competitive moves include backward integration into precision machining capacity and strategic partnerships for 48V electrical architecture standardization.
Within the conglomerate tier, JTEKT Corporation and Hyundai Mobis exemplify integrated manufacturing models leveraging geographic proximity to anchor OEM supply relationships. ZF Friedrichshafen AG occupies a differentiated position among German-based electromechanical specialists. These three entities represent contrasting strategic postures: Japanese precision engineering heritage, Korean captive supply integration, and German premium-tier system architecture specialization.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive Group |
| ZF Friedrichshafen AG |
| NSK Ltd. |
| Robert Bosch GmbH |
| Denso Corporation |
| Hyundai Mobis |
| Mitsubishi Electric Corporation |
| Hitachi Astemo, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement managers in India's organized logistics sector concentrate buying power through direct assembler contracts, compressing supplier margins and shifting the market toward volume-scaled contract pricing with performance-linked rebates. This buyer concentration feeds back into supply chain restructuring as Tier-1 integrators consolidate precision component sourcing to defend margin positions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the Asia Pacific market, with certification grade under MIIT dual carbon compliance and volume scale driving differentiation between tiers. Cost compression in the economy tier is intensifying because Chinese domestic suppliers capture state-mandated localization requirements. Fleet operators exhibit the highest price sensitivity, while premium OEMs in Japan and Korea prioritize motor-inverter integration performance over unit cost.
Supply Chain Analysis
Certification gating under BIS, GB, and METI frameworks fragments supplier qualification pathways and extends product launch timelines. Manufacturing capacity concentrates in China, Japan, and South Korea, with precision valve production drawing from German and Japanese specialist foundries. Copper winding and rare earth magnet inputs face commodity price volatility exposure. Distribution runs through captive Tier-1 integrator relationships that lock out independent component vendors from OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MIIT dual carbon deadlines compress supplier selection timelines and accelerate procurement of fuel-efficient steering architectures.
For Market Incumbents: To counter full-electric EPS substitution in mid-duty truck segments, JTEKT Corporation and Hyundai Mobis should deepen backward integration into precision machining capacity in Japan and Korea while accelerating 48V mild-hybrid steering certification under METI efficiency standards. For New Entrants and Emerging Players: Launch via aftermarket distribution partnerships serving Indonesia and Vietnam commercial vehicle assemblers, where established steering supply relationships remain underdeveloped. White-space opportunity concentrates in heavy truck hybrid EPS for ASEAN markets lacking captive Tier-1 coverage. For Investors and Strategic Acquirers: Chinese automotive component conglomerates are the most active acquirer in this space, targeting precision valve manufacturers and motor-inverter specialists to secure supply security. Over the medium-term horizon, assess targets with multi-jurisdiction certification capabilities. Watch for MIIT cybersecurity protocol integration into GB standards as an inflection signal for R&D spending redirection.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Mild-Hybrid Platform Standardization | Enables energy recuperation convergence across Chinese and Korean OEM lineups. |
| Backward Integration into Precision Valve Manufacturing | Reduces single-source exposure to Japanese and German hydraulic component suppliers. |
| Multi-Jurisdiction Certification Investment | Accelerates product launch timelines under parallel BIS, GB, and METI approval processes. |
| Captive Supply Relationship Expansion | Locks in volume commitments with Korean vehicle assemblers and Indian fleet operators. |
| Mechatronics Engineering Talent Acquisition | Addresses scarcity in hydraulic fluid dynamics and motor control algorithm integration. |
Study Parameters
Multiple input streams — primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, and aftermarket distribution heads; secondary validation through vehicle production databases, MIIT regulatory filings, and customs trade records; plus patent landscape analysis — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical production volumes were cross-referenced against panel input from steering system engineering directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include technology architecture, vehicle duty cycle severity, procurement authority concentration, and regional regulatory cluster. CAGRs were derived from fitted trend analysis incorporating diesel cost trajectory, fleet expansion rates, and emission compliance deadline proximity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper and rare earth price volatility or geopolitical friction affecting precision valve supply. A model refresh is warranted upon material change in MIIT intelligent connected vehicle cybersecurity protocol integration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
CNG Powertrain Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Transmission Sales Market
Powertrain
Transmission Oil Pumps Market
Powertrain
EV Powertrain Market
Powertrain
Transmission Repair Market
Powertrain
Torque Converter Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Europe Turbocharger Market
Powertrain
Automotive Power Modules Market
Powertrain
Engine Flush Market
Powertrain
Engines Market
Powertrain
India Automotive Engine Oils Market