
 Australia Trailer Market | 2026-2036
Australia Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Trailer Market Insights
Commercial fleet operators are bifurcating from private buyers as the dominant demand archetype in the Australia trailer landscape. Drake Trailers leverages its engineering heritage to dominate heavy-transport niches in resource corridors. CIMC Trailers Australia anchors its position through manufacturing scale and direct distribution networks. Telwater sustains brand strength in the recreational-utility crossover segment through specialized aluminum fabrication.
A trailer is a non-powered vehicle designed for towing by a powered unit, constructed with steel or aluminum chassis members, suspension systems rated for specific aggregate trailer masses, and braking configurations governed by laden weight thresholds; its primary purpose is the efficient movement of goods, equipment, or recreational payloads across road networks. Flatbed configurations occupy the mature volume core of the Australian market, while enclosed trailers capture premium margin pools in commercial logistics and private recreational use. Aluminum material adoption leads product-level differentiation as operators seek payload optimization and corrosion resistance for coastal and mining deployments.
The Australian Design Rules enforced by the Department of Infrastructure, Transport, Regional Development, Communications and the Arts mandate braking performance, lighting, and dimensional standards that directly shape manufacturer compliance costs and product specifications. TGA registration requirements and state-based heavy vehicle access permits administered by entities such as the National Heavy Vehicle Regulator create layered market access conditions for interstate operators. Stakeholders must monitor the trajectory of mass-limit harmonization and electric-vehicle towing-capacity standards to align product development and fleet procurement cycles.
Market Dynamics
The Australian Design Rules administered by the Department of Infrastructure are tightening axle-load compliance thresholds, forcing fleet operators to accelerate replacement cycles and reshaping manufacturer product specifications across heavy-haul and agricultural segments.
Growth Catalysts
- ADR braking mandates:The Australian Design Rules now mandate advanced braking systems for trailers exceeding specified aggregate trailer masses, compelling fleet-wide upgrades among interstate operators.
- Queensland mining corridor expansion:Heavy-haul configurations dominate procurement in this geography as resource extraction operators scale fleet capacity to match output targets.
- Aluminum chassis fabrication:Fabricators are adopting aluminum material systems to deliver payload optimization and corrosion resistance for coastal and mining deployments.
Market Restraints
- Steel price volatility:Input cost swings for high-tensile steel plate directly compress manufacturer margin structures and destabilize contract pricing.
- Axle supplier concentration:Heavy-haul axle assemblies concentrate among a limited set of approved suppliers, creating single-source vulnerability for domestic fabricators.
- TGA registration timelines:Extended approval windows for modified trailer designs delay product commercialization and tie up working capital.
Strategic Opportunities
- Victoria agricultural logistics:Fleet renewal cycles among grain and livestock operators in this state present replacement demand for specialized tipping and livestock configurations.
- Electric-vehicle towing standards:Anticipated regulatory clarity on towing-capacity ratings for battery-electric prime movers will unlock product development for next-generation compatible trailers.
- Direct-to-fleet digital channels:Manufacturers are bypassing traditional dealer networks to capture configuration revenue through online specification tools.
Industry Challenges
- Welding certification bottlenecks:Qualified pressure-vessel and structural welders remain scarce, constraining production ramp capacity for aluminum-intensive designs.
- Legacy fleet integration:Operators running mixed-age trailer pools face compatibility complications with newer braking and coupling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Trailer Market |
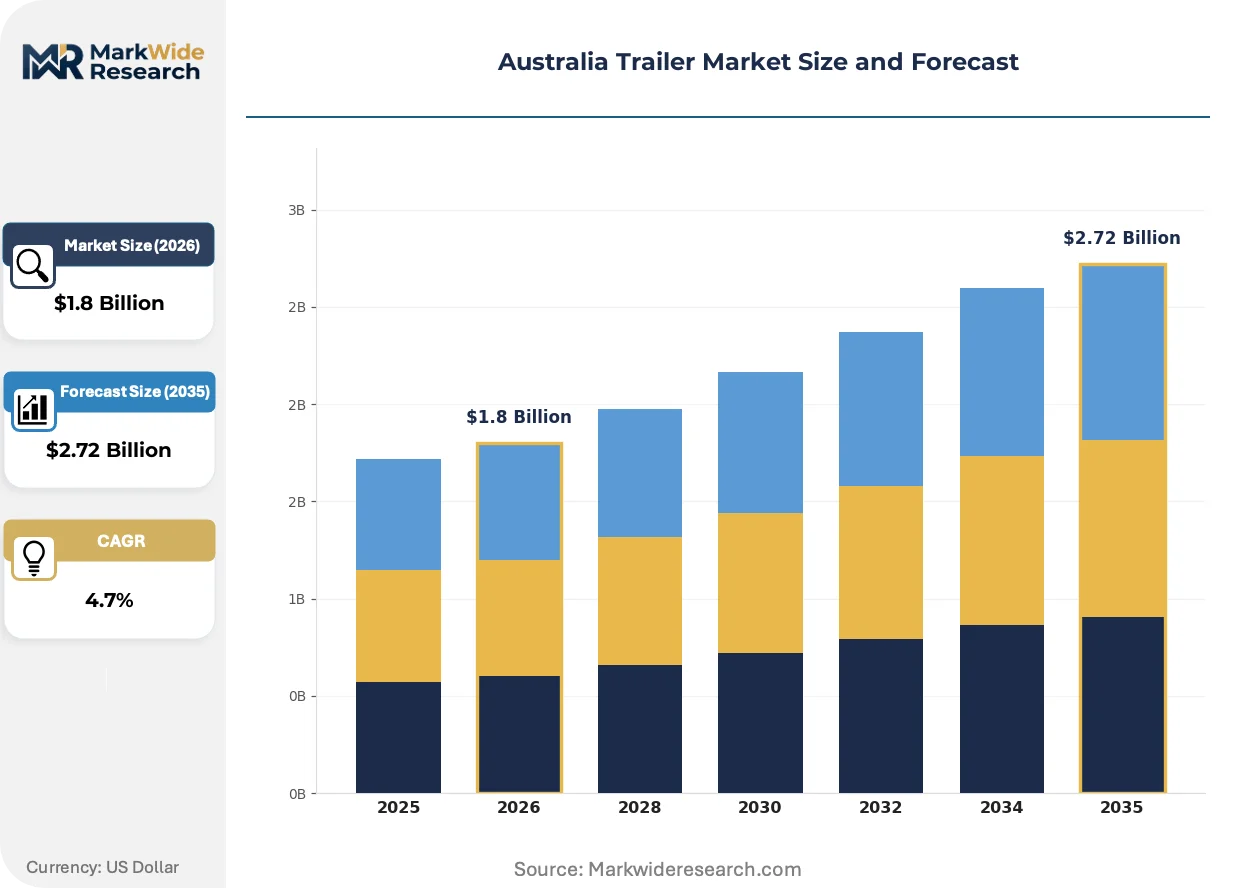
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Enclosed, Dump, Utility End User: Commercial, Government, Rental, Private Material: Steel, Aluminum, Composite, Wood Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Gothink Technology Group, Drake Trailers, The Drake Group, Telwater, CIMC Trailers Australia, Australia Pacific Trailers, Century Caravans and Trailers, Aluma, BOOMERANG ENGINEERING, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Trailer Market Trends and Innovations
Active reshaping in the Australia trailer landscape centers on material substitution, regulatory compliance automation, and the consolidation of buyer decision-making authority within centralized fleet procurement functions.
Aluminum monocoque construction is supplanting traditional steel channel-frame designs in premium commercial segments. Agricultural logistics operators in Victoria and New South Wales are specifying aluminum tipping trailers to maximize payload allowances under mass-limit regulations. This material transition is compressing the addressable market for conventional steel fabricators while elevating technical barriers to competitive entry.
The National Heavy Vehicle Regulator is harmonizing performance-based standards for higher productivity vehicles, creating a unified compliance pathway across state borders. This regulatory consolidation reduces permit fragmentation for interstate operators running B-triple and road train configurations. Heavy-haul specialists in Queensland's mining corridor are the primary beneficiaries, accelerating fleet standardization to exploit network access gains.
Fleet procurement centralization is concentrating specification authority within national transport managers rather than regional depot supervisors. This behavioral shift compresses sales cycles for standardized configurations while marginalizing custom-build specialists dependent on fragmented decision structures. The transformation is most visible among national agricultural logistics operators consolidating supplier panels across Victoria, New South Wales, and Queensland depots.
Australia Trailer Market Segmentation
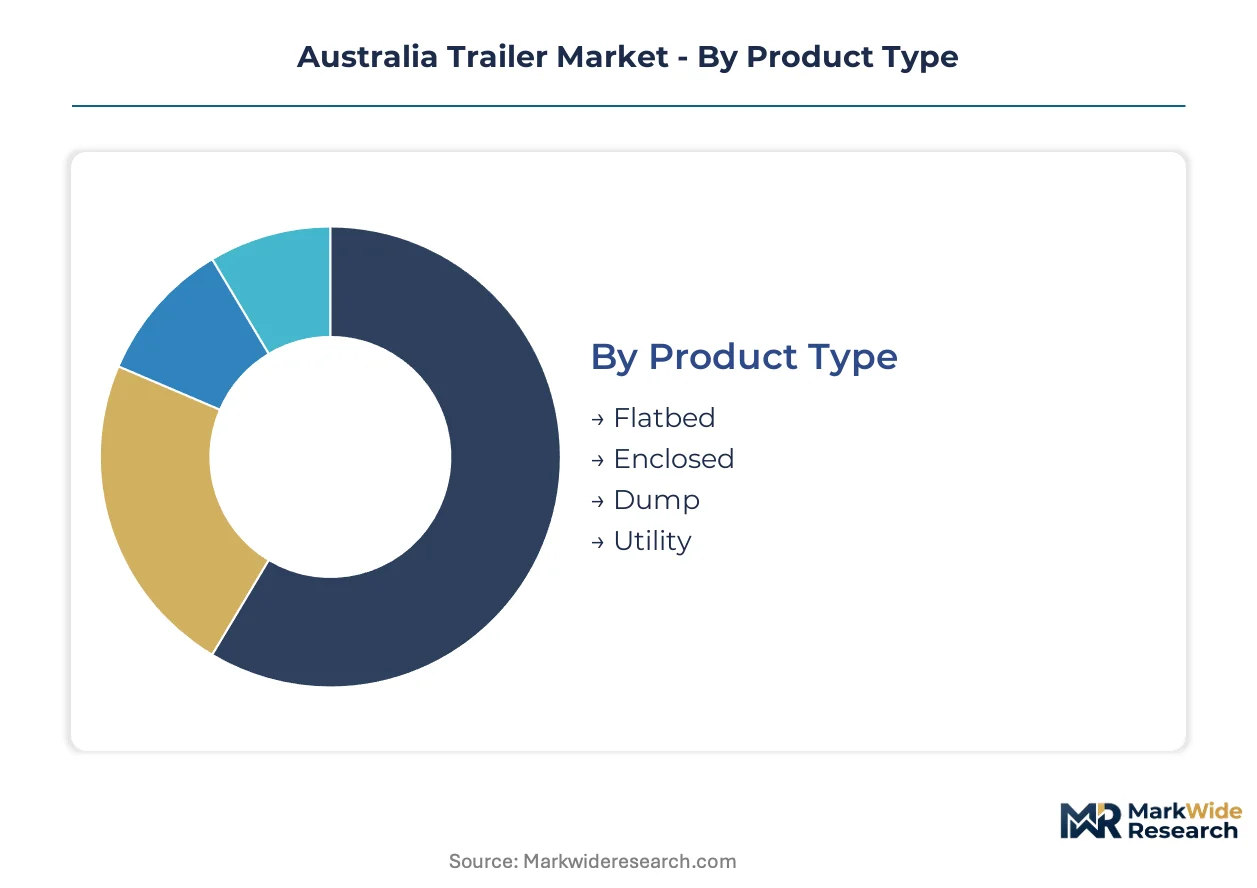
Segmentation in the Australia trailer market reveals how regulatory pressure and operational specialization fragment procurement patterns across states. Fleet operators and private buyers diverge sharply in specification priorities, forcing manufacturers to maintain parallel product architectures.
Product Type:
Domestic demand concentrates in configurations serving Queensland mining corridors and Victorian agricultural networks, with export-oriented fabrication limited by ADR compliance costs.
- Flatbed:Open-deck steel or aluminum platforms dominate heavy-haul contracts in resource extraction zones. Queensland operators specify reinforced chassis ratings for B-triple configurations hauling bulk commodities from mine sites to port terminals.
- Enclosed:Weather-protected box trailers with composite or aluminum panel construction capture premium logistics contracts. Interstate freight operators in New South Wales prioritize aerodynamic profiles and security specifications for high-value cargo lanes.
- Dump:Hydraulic tipping mechanisms serve construction waste and agricultural grain segments. Victorian grain handlers specify aluminum variants to maximize payload under mass-limit regulations.
- Utility:Light-duty configurations for recreational and small commercial use concentrate in retail channels. Private buyers in coastal regions favor corrosion-resistant aluminum builds for boat and equipment transport.
Flatbed holds the largest share; momentum sits with Enclosed as logistics operators prioritize cargo security.
End User:
Procurement authority is centralizing within national fleet managers, compressing sales cycles for standardized builds while marginalizing regional custom fabrication.
- Commercial:National transport and logistics operators dominate volume procurement through centralized supplier panels. Agricultural logistics firms across Victoria and New South Wales are accelerating fleet renewal cycles for specialized tipping and livestock configurations.
- Government:State infrastructure agencies and municipal fleets specify heavy-duty maintenance and emergency response trailers. Tender processes favor established fabricators with proven ADR compliance histories.
- Rental:Short-term lease pools serve construction project cycles and seasonal agricultural demand. Queensland mining contractors utilize rental fleets to manage capacity fluctuations without capital commitment.
- Private:Individual buyers prioritize recreational-utility crossover products through retail and online channels. Telwater's aluminum fabrication heritage anchors brand preference in this segment.
Commercial commands absolute volume; Rental is climbing fastest as project-based contracting expands.
Material:
Cost tier differentiation separates premium aluminum builds from commodity steel offerings, with composite materials occupying narrow specialty niches.
- Steel:High-tensile plate construction remains standard for heavy-haul and budget commercial segments. Price volatility in raw steel inputs compresses manufacturer margins and destabilizes contract pricing.
- Aluminum:Monocoque and channel-frame designs displace steel in premium commercial and coastal applications. Fabricators cite payload optimization and corrosion resistance as decisive specifications for mining and agricultural fleet renewals.
- Composite:Fiber-reinforced panels serve enclosed trailer applications demanding weight reduction and thermal insulation. Limited domestic fabrication capacity constrains segment expansion.
- Wood:Traditional flooring and side-rail materials persist in low-cost utility and agricultural livestock configurations. Biosecurity regulations limit reuse in cross-border livestock transport.
Steel retains volume leadership; Aluminum is gaining share fastest as mass-limit compliance tightens.
Distribution Channel:
Channel structure reflects the bifurcation between centralized fleet procurement and fragmented private buyer behavior.
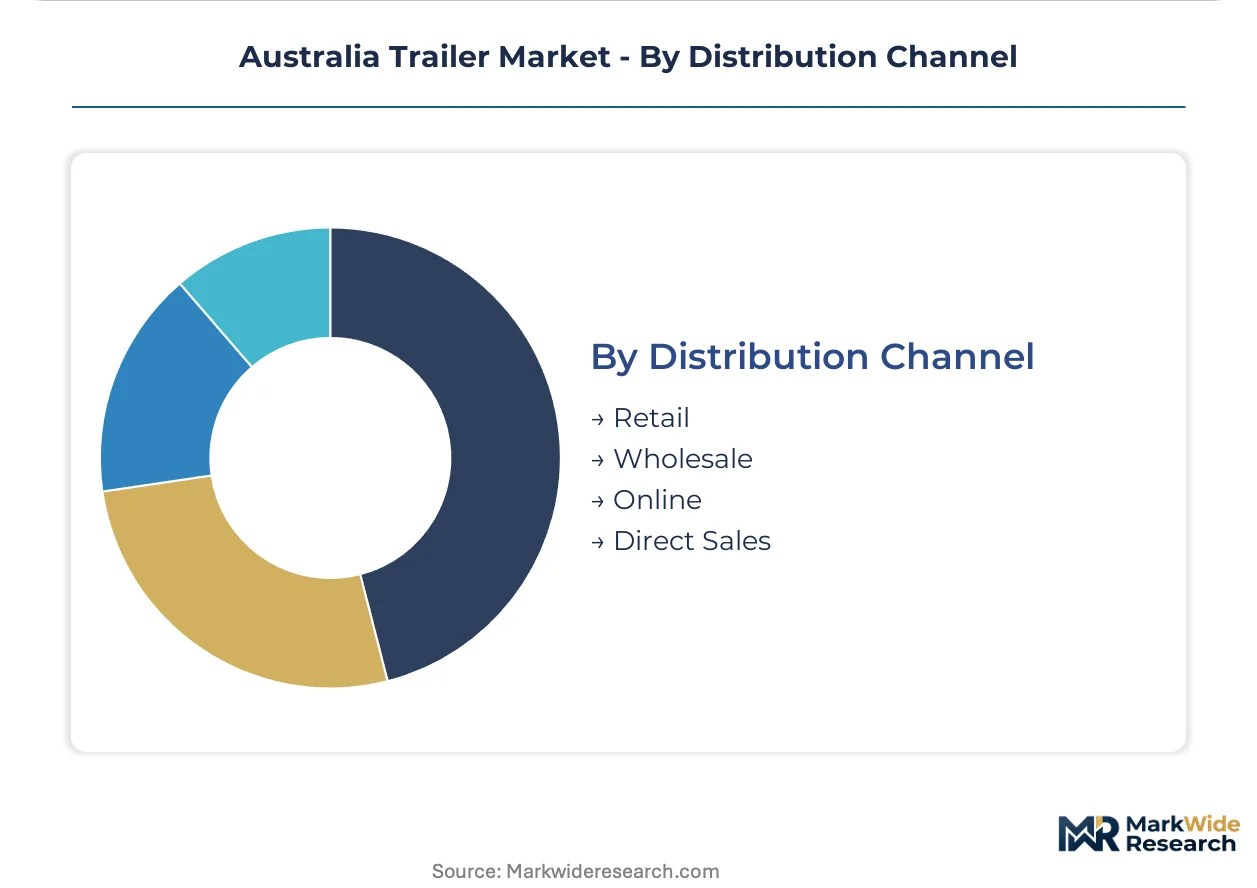
- Retail:Dealer networks serve private buyers and small commercial operators with standardized inventory. Geographic coverage concentrates in population centers along eastern seaboard corridors.
- Wholesale:Volume distributors supply regional dealers and rental fleet operators with bulk configurations. Inventory financing terms shape competitive positioning among national distributors.
- Online:Digital specification tools enable direct manufacturer-to-fleet configuration without dealer intermediation. National transport managers utilize online platforms to standardize procurement across multi-state depot networks.
- Direct Sales:Manufacturer field teams manage major fleet accounts and government tender processes. Drake Trailers and CIMC Trailers Australia leverage direct relationships for heavy-haul and agricultural specialization.
Retail captures the largest transaction count; Direct Sales delivers the steepest expansion trajectory as fleet centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Brisbane heavy-haul corridor anchors Queensland's dominance in Australian trailer procurement, with resource extraction operators scaling fleet capacity to match coal and mineral export throughput targets.
New South Wales
Sydney's interstate freight terminals drive demand for enclosed aerodynamic trailers serving high-value cargo lanes between Melbourne and Brisbane. The National Heavy Vehicle Regulator administers performance-based standards for B-triple configurations traversing the Hume Highway corridor. Newcastle's coal export infrastructure sustains heavy-haul flatbed renewal cycles among port-side logistics contractors.
Victoria
Grain handlers across the Wimmera and Mallee regions specify aluminum tipping trailers to maximize payload allowances under mass-limit regulations. The Victorian Farmers Federation advocates for standardized livestock trailer biosecurity protocols affecting cross-border fleet specifications. Melbourne's manufacturing belt hosts specialized fabricators serving agricultural logistics consolidation trends.
Queensland
Mining contractors in the Bowen Basin and Galilee Basin dominate heavy-haul procurement for B-double and road train configurations hauling bulk commodities to Gladstone and Hay Point terminals. The Department of Transport and Main Roads coordinates heavy vehicle access permits with the National Heavy Vehicle Regulator. Mackay's mining services cluster concentrates trailer maintenance and fleet management operations for resource extraction operators.
Western Australia
Iron ore exporters in the Pilbara region operate Australia's highest-productivity trailer fleets under mass exemption permits for quad-trailer road trains. Main Roads Western Australia administers remote access permits for unsealed haul roads connecting mine sites to Port Hedland and Dampier. Perth's equipment finance sector structures lease arrangements for fly-in-fly-out contractor fleets.
South Australia
Grain logistics operators across the Eyre Peninsula and Murray-Darling Basin renew livestock and tipping trailer fleets ahead of seasonal harvest peaks. The South Australian Department for Infrastructure and Transport enforces state-based access conditions for agricultural machinery movements. Adelaide's manufacturing base supplies specialized aluminum fabrications for viticulture and broadacre farming applications.
Australia Trailer Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and customer access dimensions. The vendor base concentrates among three tiers: heavy-transport engineering houses with resource corridor relationships, volume manufacturers leveraging scale economies, and recreational-utility specialists serving fragmented private demand. Two dominant competitive moves reshape positioning: direct-to-fleet digital channels bypassing dealer intermediation, and aluminum fabrication capabilities displacing legacy steel product architectures.
Within the engineering-heritage tier, Drake Trailers and The Drake Group exemplify heavy-transport specialization anchored in Queensland's mining corridor. CIMC Trailers Australia represents scale-driven manufacturing with distribution network control. Telwater occupies the recreational-utility crossover segment through aluminum fabrication differentiation. These three anchors demonstrate how geographic concentration and material capabilities stratify competitive positioning across distinct demand archetypes.
| Leading Market Players |
|---|
| Gothink Technology Group |
| Drake Trailers |
| The Drake Group |
| Telwater |
| CIMC Trailers Australia |
| Australia Pacific Trailers |
| Century Caravans and Trailers |
| Aluma |
| BOOMERANG ENGINEERING |
| Others |
Pricing and Supply Chain Analysis
Long-term fleet supply agreements between national transport operators and heavy-haul fabricators lock in aluminum chassis allocation and insulate pricing from quarterly steel volatility. These contractual structures concentrate procurement leverage among Queensland mining contractors and Victorian agricultural logistics firms, compressing margin recovery for mid-tier steel specialists caught between input cost swings and fixed-price tender obligations.
Pricing Analysis
Volume-discount tiering structures separate national fleet accounts from regional depot orders, with aluminum-intensive configurations commanding premium positioning based on ADR compliance certification and payload optimization ratings. Price differentiation rests on material grade certification and after-sales service bundling rather than base chassis specifications. Cost compression in steel-standard tiers is intensifying because of high-tensile plate input volatility, while agricultural buyers in Victoria demonstrate highest price sensitivity due to seasonal cash flow constraints.
Supply Chain Analysis
Inbound logistics costs from Chinese and South Korean steel mills through Port of Brisbane and Port Melbourne constrain working capital cycles for domestic fabricators awaiting containerized high-tensile plate deliveries. Raw material dependencies center on Australian-sourced aluminum billet, imported axle assemblies from Germany and the USA, and Chinese hydraulic component supply. Single-source vulnerability concentrates in heavy-haul axle supplier networks. Distribution runs through direct manufacturer field teams for fleet accounts and wholesale distributors serving regional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified pressure-vessel welders and ADR certification engineers represent binding constraints on production scaling, forcing stakeholders to compete for scarce technical talent rather than undifferentiated capacity. This capability scarcity elevates the strategic value of in-house certification pathways and apprenticeship pipelines.
For Market Incumbents: Compound engineering heritage advantages by embedding aluminum monocoque expertise into exclusive supplier panels for Queensland mining contractors, while accelerating backward integration into aluminum billet processing to offset Chinese steel price volatility. Defensive consolidation should prioritize captive welding certification academies to lock in scarce technical labor against emerging fabricator competition. For New Entrants and Emerging Players: TGA certification fast-track programs for modified trailer designs offer entry acceleration into Victorian agricultural tipping segments underserved by legacy steel fabricators. White-space targets include aluminum livestock configurations for cross-border biosecurity compliance and rental fleet supply for Queensland mining project cycles. Go-to-market positioning should emphasize direct digital configuration tools bypassing established dealer networks. For Investors and Strategic Acquirers: Engineering-heritage specialists with Queensland mining corridor relationships and proven ADR compliance histories represent the most defensible acquisition archetype. Long-term viability hinges on aluminum fabrication capability depth and fleet customer concentration rather than retail channel breadth. The signal to watch is National Heavy Vehicle Regulator harmonization momentum for higher productivity vehicle permits, which would accelerate fleet standardization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Monocoque Capacity Expansion | Payload optimization compliance with tightening ADR mass-limit thresholds locks in premium fleet procurement. |
| Direct-to-Fleet Digital Configuration Platform | Bypassing dealer intermediation captures specification revenue from centralized national transport managers. |
| Welding Certification Academy Partnership | Captive technical talent pipelines alleviate production bottlenecks for aluminum-intensive designs. |
| Backward Integration into Aluminum Billet Processing | In-house raw material control insulates margins from Chinese steel price volatility cycles. |
| ADR Compliance Automation Investment | Accelerated TGA registration timelines compress product commercialization cycles for modified designs. |
Research Methodology
Desk research of Australian Bureau of Statistics trade data, National Heavy Vehicle Regulator permit databases, and Department of Infrastructure ADR compliance filings preceded structured interviews with fleet procurement managers, trailer fabrication plant engineers, aluminum supplier account executives, and agricultural logistics operators. Primary fieldwork across Queensland mining corridors and Victorian grain handling networks combined with secondary validation from industry association technical bulletins. Bottom-up unit shipment estimates triangulated against top-down aggregate trailer mass registrations.
Variance-decomposition across product type, material system, end-user segment, and state-level regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from weighted average of historical replacement cycle analysis and forward fleet expansion commitments modeled against mass-limit harmonization trajectories. Industry-specific forecast inputs incorporated aluminum price index sensitivity and welding certification pipeline graduation rates.
Decision-makers should treat outputs as directional under assumptions of continued ADR compliance tightening and sustained Queensland mining output targets; material deviation in regulatory enforcement intensity or commodity export volumes would warrant model refresh. Specific risk factors include axle supplier concentration disruptions and electric-vehicle towing standard delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Caravan and Motorhome Market