
 Automotive Natural Gas Vehicle Market | 2026-2036
Automotive Natural Gas Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Natural Gas Vehicle Market Intelligence
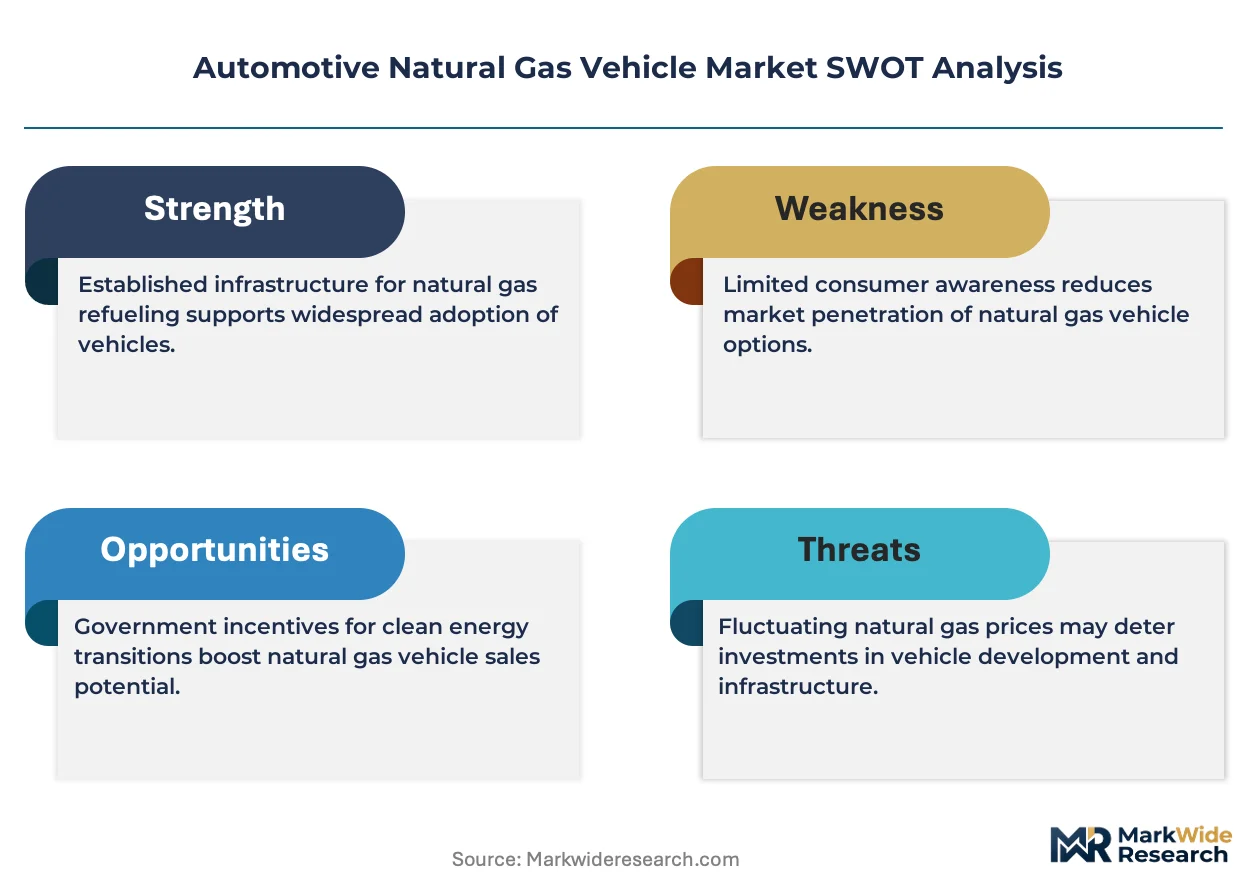
ISO 15500 certification for natural gas vehicle fuel systems is rotating supplier eligibility, forcing component makers to retest and requalify. Cummins, Inc. leverages its integrated engine-fuel system architecture to sustain fleet customer relationships. Hexagon Agility GmbH dominates Type 4 composite cylinder supply for North American transit agencies. Westport Fuel Systems Inc. anchors the aftermarket conversion segment through dealer network density.
Automotive natural gas vehicles employ spark-ignited or dual-fuel engines operating on compressed natural gas stored at 3,600 psi in cylindrical tanks, delivering 15-20% lower CO2 emissions than equivalent diesel platforms for urban freight and passenger transport duty cycles. Heavy-duty vehicles generate the deepest margin pools due to fuel consumption scale and total cost of ownership sensitivity among fleet buyers. Compressed natural gas systems lead unit volume while liquefied natural gas configurations extend range for long-haul commercial freight routes. Public transportation applications concentrate procurement through municipal tender processes that favor established OEM relationships.
EPA heavy-duty emission regulations and NHTSA fuel economy standards jointly determine engine calibration strategies and aftertreatment complexity for US market access. India's CEA guidelines and BIS cylinder standards shape product certification requirements for the country's state transport undertakings. EMA's evolving CO2 monitoring frameworks for commercial vehicles influence European OEM platform decisions. Stakeholders must monitor how carbon intensity accounting rules affect biogas qualification for fleet decarbonization targets.
Market Dynamics
Fleet operators are compressing total cost of ownership calculations to 36-month payback thresholds, forcing engine-fuel system suppliers to bundle maintenance and fuel infrastructure into procurement packages. This financial discipline is reshaping how municipal transit authorities structure vendor selection criteria.
Growth Catalysts
- EPA Heavy-Duty Emission Standards:Tightening particulate matter thresholds for urban bus fleets are mandating alternative fuel adoption. Municipal transit authorities in California and New York are accelerating compressed natural gas bus replacements.
- India State Transport Undertakings:State-run bus corporations in Maharashtra, Karnataka, and Delhi are dominating procurement volumes through centralized tender processes. The CEA guidelines and BIS cylinder standards are creating predictable certification pathways for domestic suppliers.
- Biogas Carbon Intensity Accounting:Evolving lifecycle assessment frameworks for renewable natural gas are qualifying landfill and agricultural methane capture for fleet decarbonization targets. Food waste digesters and wastewater treatment facilities are becoming anchor fuel suppliers.
Market Restraints
- Steel and Carbon Fiber Input Volatility:Type 3 and Type 4 cylinder manufacturing depends on specialized high-strength steel alloys and aerospace-grade carbon fiber prepreg. Price swings in these materials compress margin predictability for tank system suppliers.
- Limited Liquefaction Infrastructure:Liquefied natural gas adoption for long-haul freight remains constrained by sparse coastal and corridor fueling stations. The concentration of LNG liquefaction capacity on the US Gulf Coast creates geographic supply bottlenecks.
- Battery Electric Substitution:Declining lithium-ion pack costs and expanding depot charging infrastructure are positioning battery electric buses as direct competitors in urban transit applications. School districts and airport shuttle operators are piloting electric alternatives.
Strategic Opportunities
- Brazil Urban Freight Corridors:Underpenetrated last-mile delivery markets in São Paulo and Rio de Janeiro present conversion opportunities for light commercial natural gas vehicles. ANVISA fuel quality standards and state-level air quality mandates are aligning to support aftermarket kit deployment.
- Dual-Fuel Marine Convergence:Spark-ignited natural gas engine technology is migrating from automotive to harbor craft and inland waterway vessels. Port authorities in Rotterdam and Singapore are drafting bunkering specifications that leverage automotive fuel system supply chains.
- Subscription Fuel-As-A-Service Models:Fleet operators are unbundling vehicle acquisition from fuel procurement through long-term energy service contracts. This channel innovation allows municipal buyers to convert capital expenditure to operational expenditure.
Industry Challenges
- ISO 15500 Retesting Burden:Component makers face rotating supplier eligibility requirements as certification standards update. Fuel system manufacturers must retest and requalify products on compressed timelines to maintain OEM qualification status.
- High-Pressure System Integration Complexity:3,600 psi cylinder mounting, valve integration, and engine bay thermal management require specialized assembly technician training. Fleet maintenance depots lack sufficient certified personnel for in-house compressed natural gas system servicing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Natural Gas Vehicle Market |
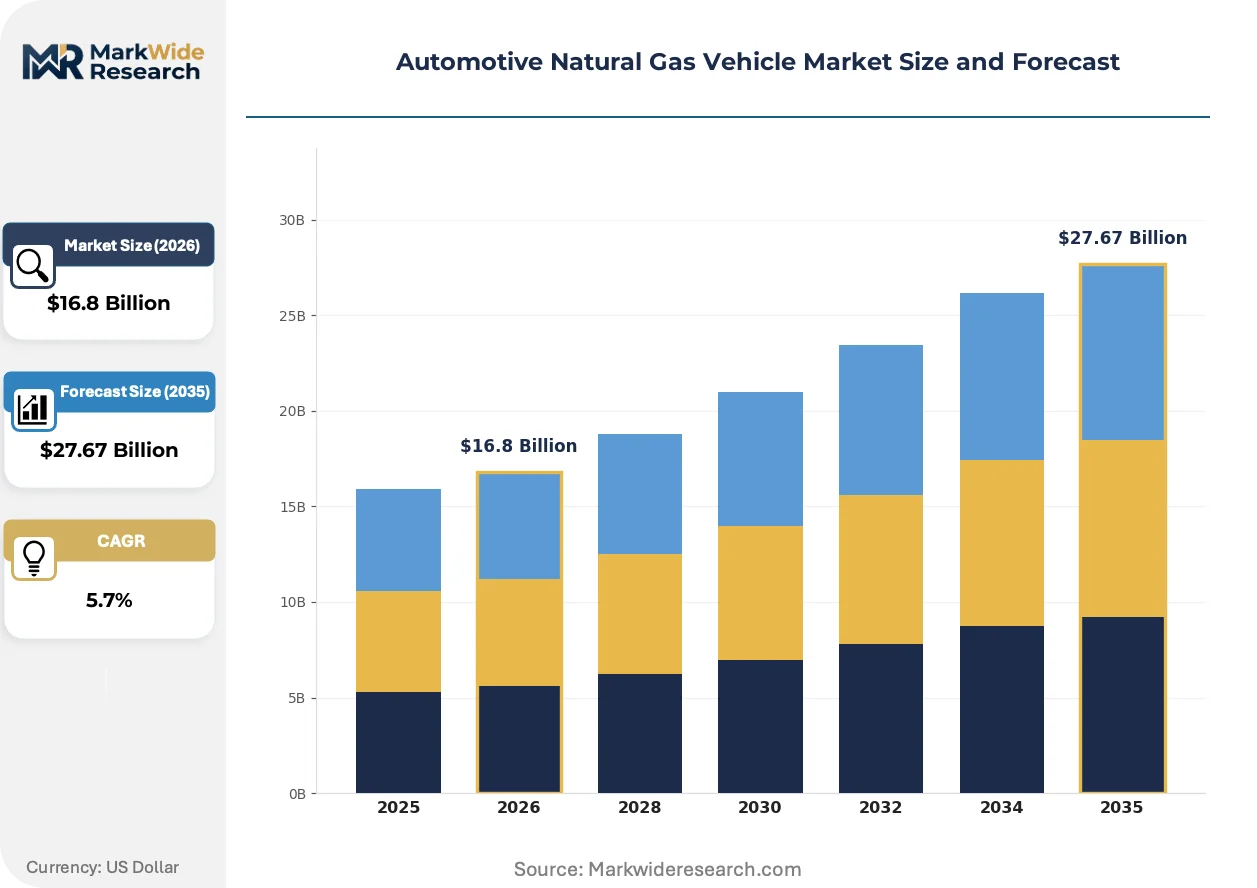
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Trucks, Buses, Heavy-Duty Vehicles Fuel System: Compressed Natural Gas, Liquefied Natural Gas, Biogas, Dual-Fuel Systems Application: Public Transportation, Commercial Freight, Industrial Use, Fleet Management Distribution Channel: OEMs, Aftermarket Providers, Dealers, Online Platforms |
| Companies Covered | AB Volvo, CNH Industrial N.V., Hexagon Agility GmbH, Westport Fuel Systems Inc., Cummins, Inc., PACCAR Inc., Navistar, Inc., Dong-Feng Group Company Limited, Beiqi Foton Motor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Natural Gas Vehicle Market Strategic Shifts & Innovations
Engine calibration strategies are fragmenting across regulatory jurisdictions, forcing platform architects to design modular architectures that accommodate divergent emission test cycles. This technical pluralism is elevating the strategic value of software-defined fuel management systems.
Type 4 composite cylinder technology is decomposing the traditional metal tank supply base. Filament-wound thermoplastic liners with carbon fiber overwrap deliver 70% weight reduction versus Type 1 steel equivalents. North American transit agencies are specifying these cylinders for roof-mounted bus configurations. The technology is decomposing incumbent metal-forming capacity and compressing regional supplier margins.
EMA's evolving CO2 monitoring frameworks for commercial vehicles are mandating onboard fuel consumption verification. European OEMs must install certified flow meters and data loggers that transmit to centralized registries. Heavy-duty tractor-trailer platforms face the steepest compliance costs, prompting engine manufacturers to prioritize natural gas variants for dedicated fleet customers.
Municipal tender processes are consolidating vendor relationships around turnkey infrastructure commitments. Transit authorities in India and the United States are awarding sole-source contracts to suppliers who deliver vehicles, fueling stations, and maintenance training as unified packages. This bundling is displacing component-level procurement and concentrating contract value with integrated system providers.
Automotive Natural Gas Vehicle Market Segmentation
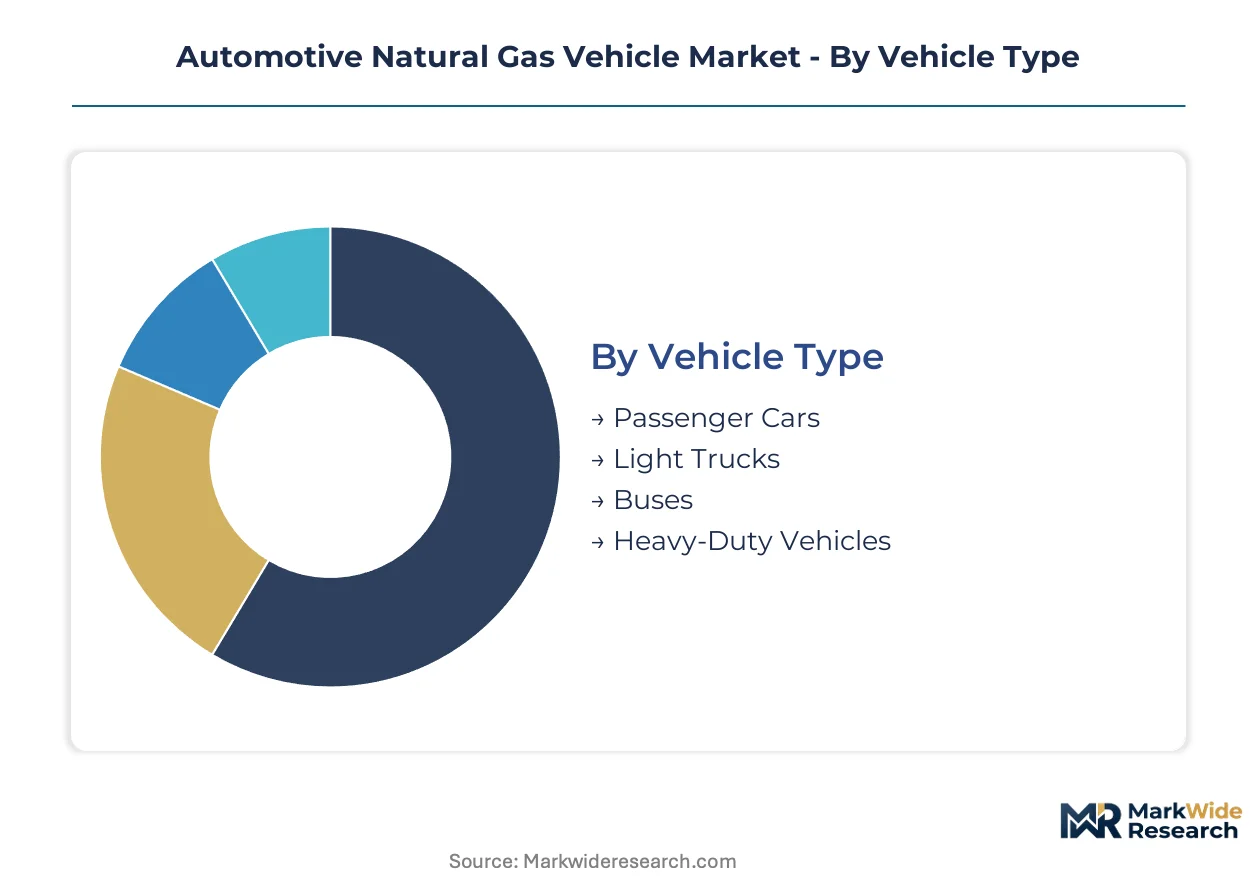
Segmentation in the Automotive Natural Gas Vehicle Market reveals how procurement channels, fuel system architectures, and duty-cycle requirements create distinct margin pools. Understanding these divisions exposes where fleet operators concentrate spending and where suppliers must align certification investments.
Vehicle Type:
Channel mix varies sharply across vehicle categories, with municipal transit authorities sourcing buses through tender processes while freight operators acquire heavy-duty units via fleet leasing channels.
- Passenger Cars:Aftermarket conversion kits dominate this segment, with bi-fuel systems allowing gasoline fallback. Demand concentrates in India and Brazil where state-level air quality mandates and ANVISA fuel quality standards support kit deployment through dealer networks.
- Light Trucks:Urban freight operators in São Paulo and Rio de Janeiro are expanding last-mile delivery fleets. State-level mandates and conversion incentives are aligning to accelerate aftermarket natural gas system adoption for commercial logistics.
- Buses:Municipal transit authorities in California, New York, and Indian state transport undertakings dominate procurement through centralized tender processes. EPA emission standards and CEA guidelines create predictable certification pathways for dedicated CNG platforms.
- Heavy-Duty Vehicles:Long-haul freight operators generate the deepest margin pools due to fuel consumption scale. LNG configurations extend range for corridor routes, though sparse fueling infrastructure constrains geographic deployment.
Heavy-Duty Vehicles dominate installed base value. Buses are where expansion concentrates for urban emission compliance.
Fuel System:
Cost tier stratification separates premium composite cylinder systems from conventional steel configurations, with carbon intensity accounting rules creating new qualification premiums for renewable variants.
- Compressed Natural Gas:Stored at 3,600 psi in cylindrical tanks, CNG systems lead unit volume across municipal bus and urban freight applications. Type 4 composite cylinders from Hexagon Agility deliver 70% weight reduction versus steel equivalents for roof-mounted configurations.
- Liquefied Natural Gas:Cryogenic storage at -162°C extends range for long-haul commercial freight. Sparse coastal and corridor fueling stations constrain adoption despite superior energy density for dedicated routes.
- Biogas:Landfill and agricultural methane capture qualifies under evolving lifecycle assessment frameworks. Food waste digesters and wastewater treatment facilities are becoming anchor fuel suppliers for fleet decarbonization targets.
- Dual-Fuel Systems:Spark-ignited architectures allow diesel fallback for operational flexibility. Engine calibration complexity rises as EPA, EMA, and India's CEA frameworks diverge on emission test cycles.
Compressed Natural Gas dominates installed base. Biogas is climbing the fastest as carbon intensity accounting matures.
Application:
Customer type determines procurement structure, with public agencies favoring turnkey infrastructure bundles while commercial operators prioritize total cost of ownership sensitivity.
- Public Transportation:Municipal tender processes consolidate vendor relationships around unified vehicle-station-training packages. Transit authorities in Maharashtra, Karnataka, and Delhi award sole-source contracts to integrated system providers.
- Commercial Freight:Fleet operators compress payback calculations to 36-month thresholds, forcing suppliers to bundle maintenance and fuel infrastructure. Long-haul corridors face LNG infrastructure gaps that constrain route planning.
- Industrial Use:Captive fleet operations at manufacturing facilities and mining sites prioritize fuel security over infrastructure density. Stationary compression equipment investments anchor site-level deployment decisions.
- Fleet Management:Subscription fuel-as-a-service models allow municipal buyers to convert capital expenditure to operational expenditure. Energy service contracts are unbundling vehicle acquisition from fuel procurement.
Public Transportation dominates installed base. Fleet Management is gaining share fastest through financial innovation.
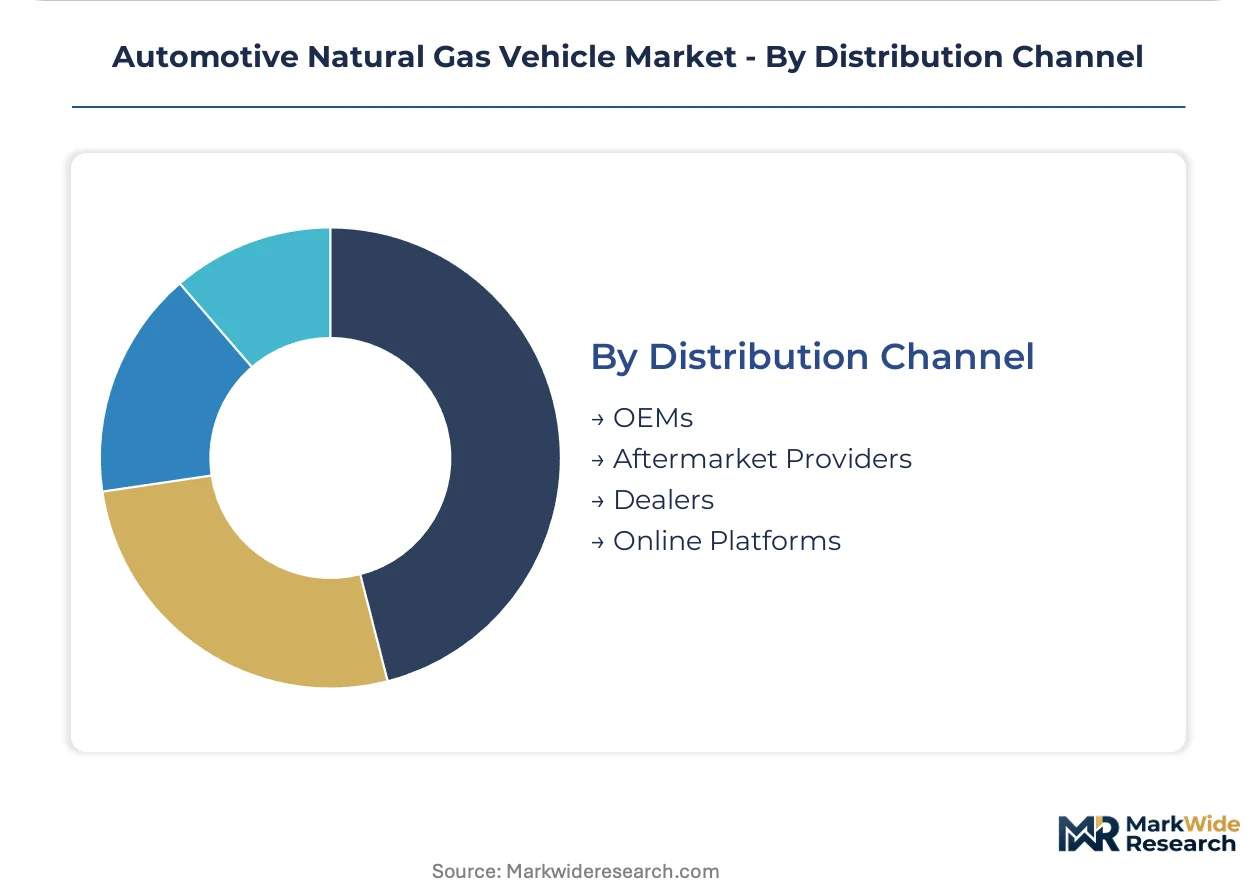
Distribution Channel:
Supply concentration favors integrated providers who control both manufacturing qualification and service network density, squeezing standalone component distributors.
- OEMs:Factory-installed systems from Cummins and Westport Fuel Systems anchor fleet customer relationships. ISO 15500 certification rotation forces continuous retesting to maintain qualification status.
- Aftermarket Providers:Conversion kit deployment depends on technician training availability for 3,600 psi system integration. Certified personnel scarcity limits depot-level servicing capacity.
- Dealers:Network density determines geographic reach for light commercial and passenger car conversions. Brazil's urban freight corridors present underpenetrated opportunities through established automotive retail channels.
- Online Platforms:Digital procurement channels remain nascent for high-pressure fuel systems requiring specialized installation. Parts and accessories represent the primary e-commerce category.
OEMs dominate installed base. Aftermarket Providers are where expansion concentrates for conversion market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet decarbonization mandates and state-level air quality programs are redirecting procurement budgets toward alternative fuel platforms. Municipal tender processes and federal emission standards collectively determine supplier qualification pathways across major automotive markets.
United States
California Air Resources Board mandates and EPA heavy-duty emission standards are accelerating compressed natural gas bus deployments in Los Angeles and San Francisco. Transit authorities in New York and Chicago are consolidating vendor relationships around turnkey vehicle-station-training packages.
India
State transport undertakings in Maharashtra, Karnataka, and Delhi dominate procurement volumes through centralized tender processes. CEA guidelines and BIS cylinder standards create predictable certification pathways for domestic suppliers. Municipal bus corporations in Mumbai and Bangalore are awarding sole-source contracts to integrated system providers.
China
Provincial air quality mandates in Shandong and Sichuan are expanding urban freight fleet conversions. MIIT fuel system standards and GB certification requirements shape product qualification for state-run transport operators. Manufacturing clusters in Chengdu and Weifang are anchoring cylinder production capacity.
Brazil
ANVISA fuel quality standards and state-level air quality mandates in São Paulo and Rio de Janeiro are aligning to support aftermarket kit deployment. Urban freight corridors present conversion opportunities for light commercial vehicles. Dealer network density determines geographic reach for conversion market penetration.
Germany
EMA CO2 monitoring frameworks for commercial vehicles mandate onboard fuel consumption verification. Port authorities in Hamburg are drafting bunkering specifications that leverage automotive fuel system supply chains. Industrial clusters in Lower Saxony anchor engine calibration and aftertreatment development.
Automotive Natural Gas Vehicle Market Key Industry Players
Player mix skews toward integrated engine-fuel system architects and specialized cylinder manufacturers. Market structure concentrates contract value with suppliers who bundle vehicles, fueling infrastructure, and maintenance training. Two strategic archetypes dominate: vertically integrated OEMs controlling manufacturing qualification and component specialists capturing premium composite cylinder margins. Competitive moves center on geographic expansion through dealer network density and technology licensing for dual-fuel calibration platforms.
Within the integrated-system tier, Cummins, Inc. and Westport Fuel Systems Inc. exemplify engine-fuel system bundling strategies that sustain fleet customer relationships. Hexagon Agility GmbH occupies a specialized position in Type 4 composite cylinder supply for North American transit agencies. Among Asian manufacturers, Dong-Feng Group Company Limited and Beiqi Foton Motor Co., Ltd. represent state-affiliated OEMs serving domestic procurement channels. European heavy-duty specialists AB Volvo and CNH Industrial N.V. anchor premium-platform development for emission-compliant freight applications.
| Leading Market Players |
|---|
| AB Volvo |
| CNH Industrial N.V. |
| Hexagon Agility GmbH |
| Westport Fuel Systems Inc. |
| Cummins, Inc. |
| PACCAR Inc. |
| Navistar, Inc. |
| Dong-Feng Group Company Limited |
| Beiqi Foton Motor Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Ninety-day cylinder certification lead times concentrate pricing power with ISO 15500-qualified suppliers, compressing margins for component makers caught in retesting cycles while rewarding integrated system architects who bundle fuel infrastructure with vehicle procurement.
Pricing Analysis
Certification grade creates the primary spread between premium Type 4 composite systems and conventional steel configurations. Three-tier pricing structure across OEM-integrated, aftermarket conversion, and dealer-installed levels reflects after-sales bundling intensity and technician training depth. Cost compression in aftermarket kits intensifies because carbon fiber prepreg volatility feeds through to cylinder margins. Municipal transit authorities demonstrate lowest price sensitivity due to total cost of ownership framing, while independent fleet operators face acute capital expenditure constraints.
Supply Chain Analysis
China and India anchor high-pressure cylinder manufacturing through Chengdu and Weifang production clusters, with Germany and the United States supplying specialized valve and regulator assemblies. Aerospace-grade carbon fiber prepreg, high-strength steel alloys, and cryogenic insulation materials constitute critical input dependencies. Single-source vulnerability concentrates in carbon fiber supply chains tethered to industrial gas and aerospace demand cycles. Distribution runs through OEM captive networks for factory-installed systems, while aftermarket channels rely on certified technician density and dealer service reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet decarbonization mandates across municipal transit authorities signal early-cycle expansion, with biogas carbon intensity accounting creating qualification premiums that accelerate renewable natural gas infrastructure deployment.
For Market Incumbents: Shield OEM qualification status through accelerated ISO 15500 recertification investments ahead of standard rotation cycles. Deepen backward integration into cylinder manufacturing capacity in India and China to capture state transport undertaking procurement volumes. Battery electric substitution in urban bus segments represents the primary displacement threat requiring dual-platform portfolio hedging. For New Entrants and Emerging Players: CEA guideline fast-tracks for domestic Indian suppliers create regulatory arbitrage opportunities against multinational incumbents. Brazil's underpenetrated urban freight corridors in São Paulo and Rio de Janeiro offer the most penetrable conversion market through established automotive dealer networks. Position around subscription fuel-as-a-service models to unbundle vehicle acquisition from energy procurement for municipal buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded natural gas fuel system divisions lacking fleet customer scale. Long-term viability hinges on biogas qualification rates and carbon intensity accounting standardization across EPA, EMA, and CEA jurisdictions. Monitor LNG liquefaction capacity buildout along coastal corridors as infrastructure inflection signal for heavy-duty freight adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Type 4 Composite Cylinder Capacity Expansion | Hexagon Agility's filament-wound technology displaces steel tank incumbent positions in North American transit. |
| Dual-Fuel Calibration Platform Licensing | Westport Fuel Systems extends automotive engine expertise into Rotterdam and Singapore harbor craft bunkering. |
| Biogas Supply Agreement Structuring | Food waste digester partnerships anchor renewable natural gas qualification for fleet decarbonization targets. |
| Turnkey Infrastructure Bundling | Cummins consolidates municipal tender awards through unified vehicle-station-training procurement packages. |
| Aftermarket Technician Certification Scaling | Dealer network density determines geographic reach for Brazil light commercial conversion market penetration. |
Research Approach
Desk research of EPA emission standard filings, CEA guideline publications, and BIS cylinder certification databases preceded structured interviews with OEM platform engineers, Tier 1 fuel system procurement leads, municipal transit authority fleet managers, and aftermarket conversion kit distributors. Primary fieldwork across California, Maharashtra, and São Paulo validated secondary data on tender processes and infrastructure deployment timelines. Bottom-up vehicle production estimates triangulated against top-down fleet operator expenditure surveys.
Variance decomposition across vehicle type, fuel system architecture, and application segments shaped the analytical framework over the projection horizon. Modeled dimensions included propulsion configuration, cylinder technology tier, procurement channel structure, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to fleet operator payback threshold observations, with biogas carbon intensity trajectory and battery electric cost parity assumptions as key forecast inputs.
Underlying assumptions cover EPA particulate matter standard enforcement continuity and CEA guideline stability, with deviation risk concentrated in lithium-ion pack cost trajectories and LNG liquefaction capacity geographic distribution. Forecasts reflect documented conditions without scenario probability weighting. Recalibration cycles align with material shifts in carbon intensity accounting rules and state transport undertaking procurement schedule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market