
 UK New Energy Vehicle TIC Services Market | 2026-2036
UK New Energy Vehicle TIC Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK New Energy Vehicle TIC Services Market Insights
Software-defined validation is repositioning how TIC contracts are structured, shifting from one-time certification to recurring platform-based engagements. Bureau Veritas leverages its UKAS-accredited laboratories to dominate battery abuse testing protocols. DEKRA SE anchors its position through dedicated hydrogen fuel cell evaluation centres in the Midlands. SGS Société Générale de Surveillance SA extends its service perimeter into charging infrastructure cybersecurity audits.
UK New Energy Vehicle TIC Services encompass technical verification of electric drivetrains, energy storage systems, and connected vehicle software against statutory performance and safety benchmarks, employing climatic chambers, electromagnetic compatibility rigs, and dynometer arrays to replicate real-world duty cycles. The primary commercial purpose is to grant market access by demonstrating conformity with type-approval requirements. Testing services capture the largest revenue pool given the capital intensity of propulsion system validation, while certification of charging infrastructure represents the fastest-expanding segment as network density obligations tighten. Battery safety application areas command premium margins due to thermal runaway liability exposure and insurer-mandated verification.
The Vehicle Certification Agency enforces UK type-approval alignment with UNECE regulations, while the Health and Safety Executive governs workplace battery handling standards; both bodies expand mandatory inspection scopes as chemistries evolve beyond lithium-ion. The British Standards Institution publishes PAS standards that prefigure statutory requirements, creating early-mover advantage for TIC firms that participate in drafting committees. Stakeholders must monitor how the UK's post-EU regulatory divergence from EU AI Act vehicle provisions reshapes mutual recognition agreements and cross-border service portability.
Market Dynamics
The Automated and Electric Vehicles Act is forcing fleet operators to adopt third-party battery verification protocols, restructuring how TIC contracts are awarded and priced across England's automotive corridor.
Growth Catalysts
- West Midlands hydrogen clusters:Dedicated fuel cell evaluation centres are drawing OEM validation contracts away from generalist testing facilities.
- UNECE battery safety alignment:The Vehicle Certification Agency's expanded type-approval scope mandates recurrent thermal runaway testing for commercial vehicle fleets.
- Charging infrastructure density obligations:Network operators must commission cybersecurity audits as a condition of public funding access under national decarbonisation frameworks.
Market Restraints
- Capital intensity of climatic chamber arrays:Dynometer rig procurement costs exceed GBP 2 million per installation, freezing mid-tier laboratory expansion.
- Post-EU regulatory divergence friction:Mutual recognition uncertainty with EU AI Act vehicle provisions complicates cross-border service portability for UK-accredited firms.
- Lithium-ion chemistry lock-in:Solid-state and sodium-ion alternatives lack standardised abuse testing protocols, delaying insurer-mandated verification expansion.
Strategic Opportunities
- Connected vehicle software validation:Over-the-air update certification represents an underdeveloped revenue stream with recurring engagement potential.
- Scottish renewable hydrogen corridors:Aberdeen and Glasgow port authorities are mandating fuel cell vessel compatibility testing ahead of statutory requirements.
- Second-life battery assessment:Stationary energy storage repurposing creates demand for degradation profiling services outside OEM warranty chains.
Industry Challenges
- Electromagnetic compatibility engineer scarcity:Specialist talent capable of interpreting CISPR 25 vehicle emissions standards commands premium compensation, compressing laboratory margins.
- UKAS accreditation timeline compression:New entrant laboratories face 18-24 month approval cycles for battery abuse testing scopes, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK New Energy Vehicle TIC Services Market |
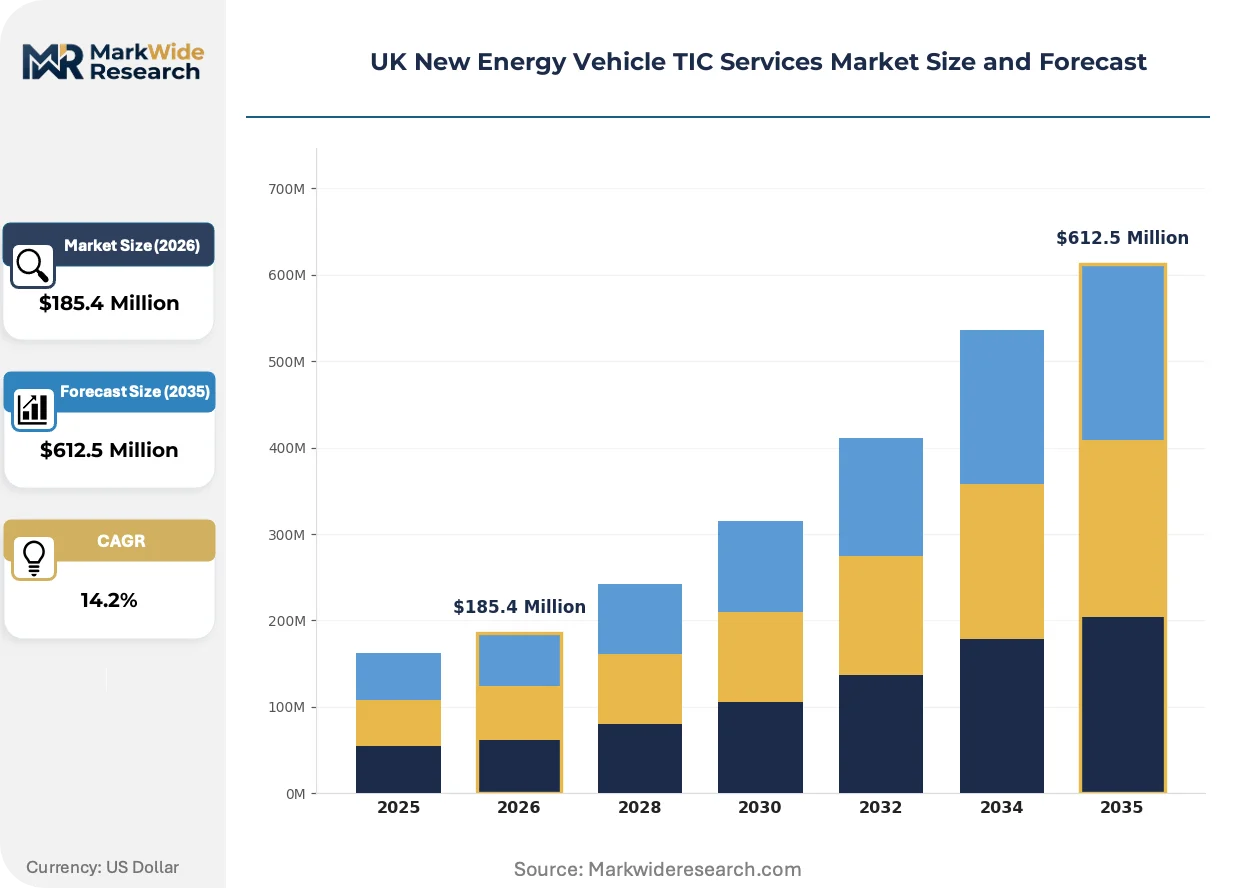
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $612.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Inspection, Certification, Auditing, Consulting New Energy Vehicle Type: Electric Vehicles, Hybrid Vehicles, Hydrogen Fuel Cell Vehicles, Plug-in Hybrid Vehicles Application Area: Battery Safety, Emission Compliance, Charging Infrastructure, Vehicle Performance Assessment, Software Validation Client Segment: OEMs, Suppliers, Charging Station Operators, Aftermarket Providers, Fleet Operators |
| Companies Covered | Bureau Veritas, DEKRA SE, Element Materials Technology, Intertek Group plc, SGS Société Générale de Surveillance SA, TÜV SÜD, TÜV Rheinland, The British Standards Institution, UL LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK New Energy Vehicle TIC Services Market Trends and Innovations
Software-defined validation architectures are displacing hardware-centric certification workflows, compressing test cycle duration while expanding recurring revenue attachment rates for platform-enabled TIC providers.
Digital twin simulation of battery thermal behaviour is converging with physical abuse testing protocols, enabling predictive failure modelling before prototype fabrication. Automotive OEMs in the West Midlands are adopting hybrid virtual-physical validation pipelines, collapsing development timelines from 18 months to 9 months for new cell chemistry introductions.
The Health and Safety Executive's evolving workplace battery handling standards are mandating recurrent inspection frequencies for commercial fleet depots. Logistics operators must now commission quarterly thermal imaging audits of charging infrastructure, creating subscription-based revenue streams for accredited inspection bodies. This pressure concentrates most intensely in Greater London's last-mile delivery hubs.
Fleet procurement departments are unbundling certification from equipment purchase contracts, establishing direct relationships with UKAS-accredited laboratories. Third-party verification is displacing OEM-bundled testing in municipal bus and commercial van segments, with Transport for London's zero-emission bus programme serving as the reference implementation for this purchasing model shift.
UK New Energy Vehicle TIC Services Market Segmentation
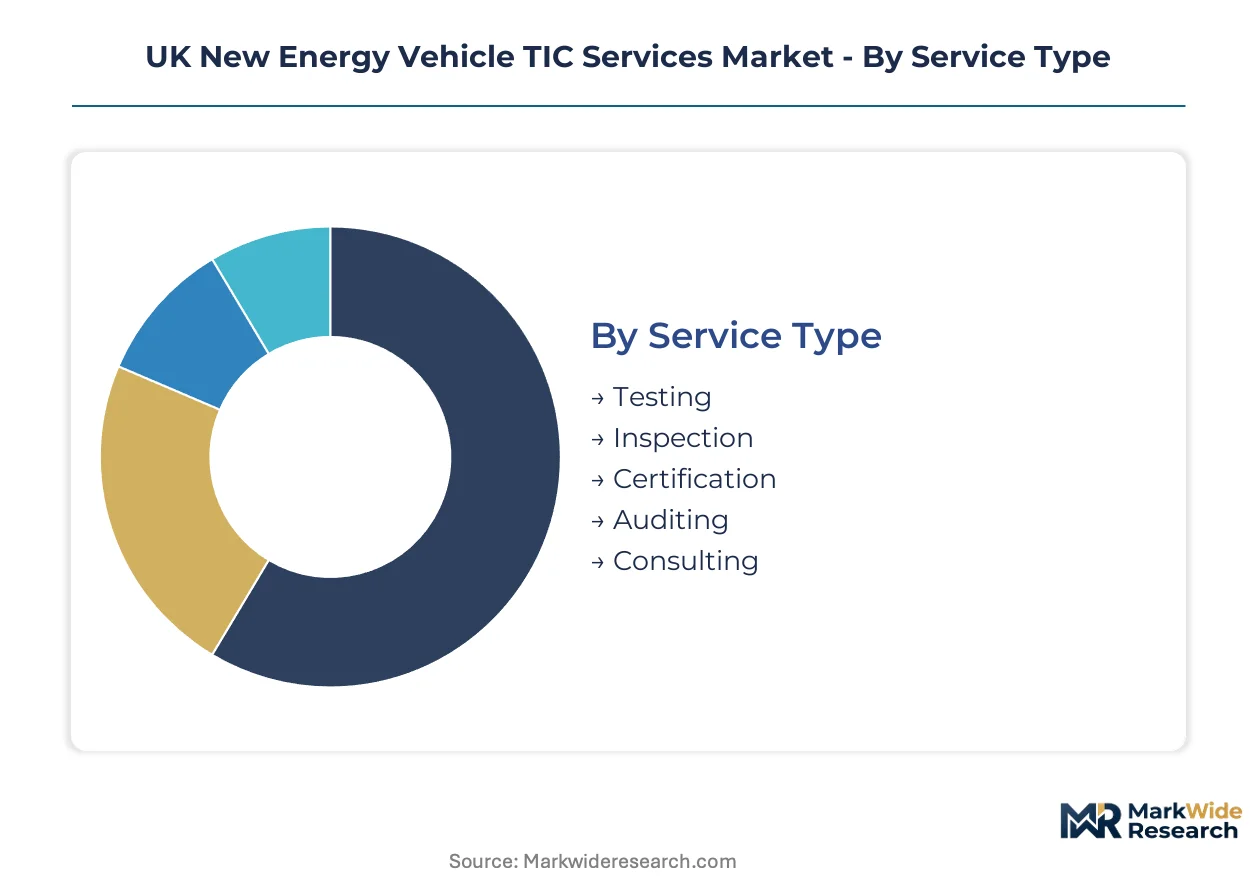
TIC service providers structure their UK operations around distinct capability clusters, with capital intensity and regulatory scope varying sharply across service modalities. Understanding these fault lines clarifies where laboratory infrastructure investments concentrate versus where platform-based recurring models displace one-off certification.
Service Type:
Volume concentration sits with commoditized inspection protocols, while premium margins attach to specialized testing requiring UKAS-accredited facilities and proprietary equipment arrays.
- Testing:Propulsion system validation consumes climatic chambers, electromagnetic compatibility rigs, and dynometer arrays to replicate real-world duty cycles. Fleet operators in England's automotive corridor commission recurrent thermal runaway testing as the Vehicle Certification Agency expands commercial vehicle battery safety mandates.
- Certification:Type-approval demonstration against UNECE regulations grants market access for new energy vehicle platforms. The British Standards Institution's PAS standards create early-mover advantage for TIC firms participating in drafting committees ahead of statutory adoption.
- Inspection:Workplace battery handling audits governed by the Health and Safety Executive mandate quarterly thermal imaging of charging infrastructure. Greater London's last-mile delivery hubs generate concentrated subscription demand.
- Auditing:Cybersecurity assessment of charging infrastructure secures public funding access under national decarbonisation frameworks.
- Consulting:Regulatory divergence guidance assists OEMs navigating post-EU mutual recognition uncertainty.
Mature deployment sits with Testing. Newer deployment is concentrated in Auditing.
New Energy Vehicle Type:
Application complexity and chemistry diversity determine where TIC contracts carry premium pricing versus standardized verification protocols.
- Electric Vehicles:Battery abuse testing for lithium-ion architectures dominates laboratory throughput. Thermal runaway liability exposure commands insurer-mandated verification premiums.
- Hydrogen Fuel Cell Vehicles:Dedicated evaluation centres in the West Midlands draw OEM validation contracts through specialized pressure vessel and membrane testing capabilities.
- Plug-in Hybrid Vehicles:Dual-powertrain validation requires integrated electromagnetic compatibility assessment of electric and combustion systems operating in tandem.
- Hybrid Vehicles:Conventional mild-hybrid architectures utilize standardized testing protocols with reduced capital requirements.
Commercial maturity centers on Electric Vehicles. Technology transition investment flows toward Hydrogen Fuel Cell Vehicles.
Application Area:
Regulatory enforcement intensity and liability exposure separate high-margin specialized verification from routine compliance documentation.
- Battery Safety:Thermal runaway propagation testing and abuse protocol validation command premium margins due to catastrophic failure liability. The Automated and Electric Vehicles Act mandates third-party verification for commercial fleet operators.
- Charging Infrastructure:Cybersecurity audits and grid integration testing represent the steepest expansion trajectory as network density obligations tighten under public funding conditions.
- Software Validation:Over-the-air update certification for connected vehicle platforms creates recurring revenue potential through platform-based engagement models.
- Emission Compliance:Tailpipe and well-to-wheel carbon accounting verification supports corporate fleet decarbonisation reporting.
- Vehicle Performance Assessment:Range validation and efficiency benchmarking provides procurement decision support for municipal and commercial fleet operators.
Established revenue concentration resides in Battery Safety. Emerging capability investment targets Software Validation.
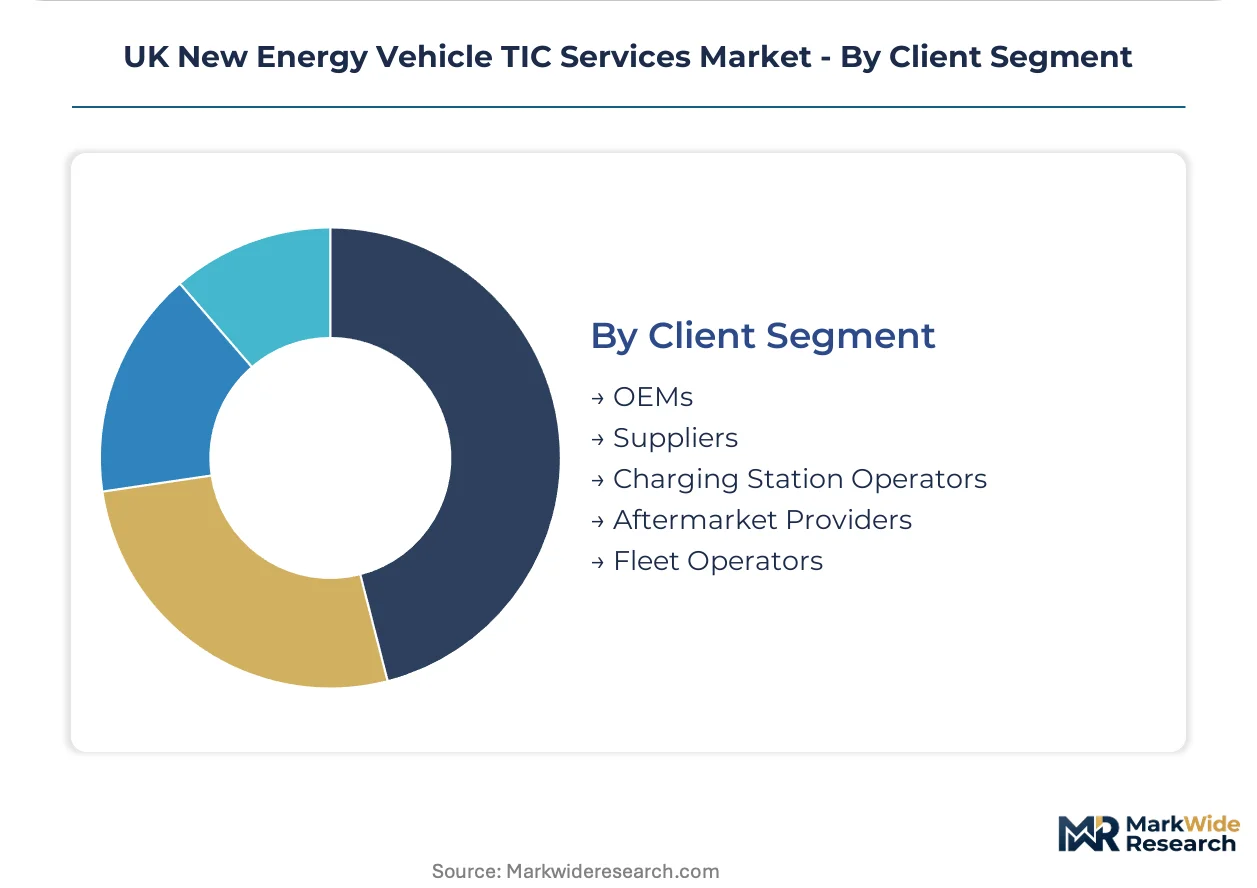
Client Segment:
Procurement centralization and technical sophistication determine whether TIC relationships operate through OEM-bundled contracts or direct laboratory engagement.
- Fleet Operators:Transport for London's zero-emission bus programme established the reference implementation for unbundled certification, with procurement departments commissioning UKAS-accredited laboratories directly rather than accepting OEM-bundled testing.
- OEMs:West Midlands automotive manufacturers adopt hybrid virtual-physical validation pipelines, collapsing development timelines for new cell chemistry introductions through digital twin simulation combined with physical abuse testing.
- Charging Station Operators:Network density obligations mandate cybersecurity audits as public funding conditions, creating audit subscription relationships with accredited inspection bodies.
- Suppliers:Tier-one battery and drivetrain component manufacturers require recurrent verification for production continuity.
- Aftermarket Providers:Second-life battery assessment for stationary energy storage repurposing creates degradation profiling demand outside OEM warranty chains.
Contracting model innovation originates with Fleet Operators. Volume concentration remains with OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing capacity concentrates in England's automotive corridor, while demand generation spreads across devolved administrations with distinct regulatory priorities. Scotland and Wales are developing specialized hydrogen and battery verification capabilities ahead of statutory mandates.
West Midlands
England's automotive manufacturing heartland hosts the densest concentration of battery abuse testing infrastructure. The Vehicle Certification Agency operates its primary commercial vehicle approval facility here, while dedicated hydrogen fuel cell evaluation centres draw OEM validation contracts from across Europe. Birmingham and Coventry anchor a cluster where climatic chamber arrays and dynometer rigs exceed GBP 50 million in combined capital deployment.
Greater London
Last-mile delivery fleet operators generate concentrated demand for workplace battery handling audits under Health and Safety Executive mandates. Transport for London's zero-emission bus programme established the reference implementation for unbundled certification, with procurement departments commissioning UKAS-accredited laboratories directly. Quarterly thermal imaging subscriptions for charging infrastructure concentrate in suburban distribution hubs.
Scotland
Aberdeen and Glasgow port authorities are mandating fuel cell vessel compatibility testing ahead of statutory requirements, creating early-mover advantage for TIC firms with hydrogen evaluation capabilities. The Scottish Government's renewable hydrogen corridor investments are accelerating demand for pressure vessel and membrane testing services. Edinburgh-based regulatory consultancies are positioning for post-EU divergence advisory work.
South East England
Connected vehicle software validation demand concentrates here, with over-the-air update certification emerging as a recurring revenue stream. The region's cybersecurity audit capacity serves charging infrastructure operators seeking public funding under national decarbonisation frameworks. Oxford and Cambridge technology clusters are spawning digital twin simulation providers that hybridize with physical testing protocols.
Wales
Second-life battery assessment for stationary energy storage is developing around Newport and Cardiff, targeting degradation profiling outside OEM warranty chains. The Welsh Government's circular economy incentives are attracting repurposing facility investments that require third-party verification. Grid-scale battery storage projects are commissioning pre-deployment safety audits from England-based laboratories with Welsh satellite operations.
UK New Energy Vehicle TIC Services Market Competitive Landscape
Top-tier vendors anchor UKAS-accredited laboratory networks, while mid-tier specialists compete on hydrogen fuel cell or cybersecurity niche credentials. The market structure reflects capital intensity barriers, with climatic chamber and dynometer rig investments exceeding GBP 2 million per installation freezing generalist expansion. Three archetypes dominate: pan-European certification houses with UK satellite operations, domestic specialists leveraging Vehicle Certification Agency relationships, and platform-enabled providers shifting toward recurring software validation engagements. Competitive moves concentrate on UKAS scope expansion and digital twin capability integration.
Within the pan-European tier, Bureau Veritas and DEKRA SE exemplify divergent specialization strategies. Bureau Veritas leverages its UKAS-accredited laboratory footprint to dominate battery abuse testing protocols, particularly thermal runaway verification for commercial vehicle fleets. DEKRA SE anchors its position through dedicated hydrogen fuel cell evaluation centres in the Midlands, drawing OEM contracts away from generalist facilities. SGS Société Générale de Surveillance SA occupies a position bridging physical testing and emerging digital audit requirements, extending into charging infrastructure cybersecurity verification.
| Leading Market Players |
|---|
| Bureau Veritas |
| DEKRA SE |
| Element Materials Technology |
| Intertek Group plc |
| SGS Société Générale de Surveillance SA |
| TÜV SÜD |
| TÜV Rheinland |
| The British Standards Institution |
| UL LLC |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement departments in Transport for London's zero-emission bus programme command pricing power through unbundled certification contracts, forcing TIC providers toward subscription-based thermal imaging audits and recurring platform engagements rather than one-time project fees.
Pricing Analysis
Margin tightening in UKAS-accredited battery abuse testing reflects climatic chamber capital costs exceeding GBP 2 million per installation. Pricing stratifies across premium certification tiers for thermal runaway verification, standard compliance documentation, and economy inspection bundles for routine workplace audits. Cost-down pressure on mid-tier laboratories accelerates because fleet operators now source verification directly rather than accepting OEM-bundled testing. Municipal bus procurement shows highest price sensitivity; hydrogen fuel cell evaluation centres retain pricing power through dedicated Midlands infrastructure.
Supply Chain Analysis
Freight costs for dynometer rig components from Germany, Japan, and the United States inflate capital deployment timelines for new laboratory entrants. Equipment procurement draws from specialized electromagnetic compatibility rig manufacturers, climatic chamber fabricators, and dynometer array suppliers concentrated in industrial automation hubs. Single-source vulnerability sits with UKAS-accredited calibration services tethered to domestic metrology institutes. Distribution runs through direct OEM sales for major capital equipment and regional service partners for consumables and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into digital twin simulation capabilities is accelerating as West Midlands OEMs collapse cell chemistry validation timelines, forcing TIC providers to control hybrid virtual-physical pipeline technologies.
For Market Incumbents: To counter platform-enabled entrants capturing over-the-air update certification revenue, Bureau Veritas-class laboratories should deepen backward integration into proprietary battery thermal modeling software and expand UKAS scope for solid-state chemistry protocols before statutory mandates arrive. Capacity addition in Scottish hydrogen corridors secures early-mover positioning ahead of Aberdeen port authority requirements. For New Entrants and Emerging Players: Fleet operator procurement departments represent the most penetrable channel partner type for unbundled certification relationships. White-space targets include second-life battery degradation profiling for stationary storage outside OEM warranty chains and cybersecurity audit subscriptions for charging infrastructure operators seeking public funding access. A regulatory divergence advisory practice targeting post-EU mutual recognition uncertainty offers differentiated entry positioning. For Investors and Strategic Acquirers: The window for entry favors UKAS-accredited specialists with hydrogen fuel cell evaluation capabilities and established Vehicle Certification Agency relationships. Long-term viability hinges on recurring revenue attachment rates from software-defined validation platforms rather than transactional testing volumes. Watch for Health and Safety Executive expansion of workplace battery handling inspection frequencies as the inflection signal for subscription model acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UKAS Scope Expansion for Solid-State Protocols | Early accreditation ahead of statutory chemistry mandates captures premium thermal runaway verification margins. |
| Digital Twin Simulation Capability Buildout | Hybrid virtual-physical pipelines align with West Midlands OEM timeline compression demands for cell introductions. |
| Hydrogen Evaluation Centre Investment | Dedicated Midlands pressure vessel testing draws OEM validation contracts from European fuel cell programmes. |
| Charging Infrastructure Cybersecurity Audit Subscription | Network density obligations under national decarbonisation frameworks create recurring public funding gatekeeper revenue. |
| Second-Life Battery Assessment Service Launch | Welsh circular economy incentives and stationary storage repurposing demand degradation profiling outside OEM chains. |
Research Methodology
Multi-period observation of UKAS accreditation timelines, Vehicle Certification Agency type-approval expansion patterns, and fleet procurement contract unbundling rates anchored the trend analysis, supplemented by interviews with TIC laboratory directors, OEM platform engineers, fleet procurement managers, and Health and Safety Executive compliance officers. Secondary validation drew from UNECE regulatory filings, British Standards Institution PAS standard development records, and Automated and Electric Vehicles Act implementation guidance. Bottom-up laboratory capacity modeling and top-down fleet verification demand estimation enabled triangulation across independent analytical paths.
Input-output matrices mapped service type, vehicle architecture, application area, and client segment dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro fleet electrification trajectories and regulatory mandate enforcement schedules. Forecast inputs incorporated climatic chamber deployment pipelines, UKAS approval backlogs, and hydrogen corridor infrastructure investment disclosures from Scottish and Welsh development agencies.
Caveats apply where post-EU regulatory divergence resolution, solid-state battery chemistry commercialization timelines, or insurer mandate expansion for alternative chemistries could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market