
 CNG Vehicles Market | 2026-2036
CNG Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
CNG Vehicles Market Analytics
EURO VI-compliant engine specification is collapsing the cost gap between diesel and compressed natural gas powertrains for heavy-duty logistics. Hyundai Motor Company leverages its dedicated CNG platform architecture across Asian and Latin American assembly plants. Tata Motors anchors the Indian market through integrated in-house production of fuel storage cylinders and pressure regulation systems. Volkswagen Group competes on modular engine families that accommodate both gasoline and CNG injection without major block redesign.
Compressed natural gas vehicles employ spark-ignited internal combustion engines modified to operate on methane stored at pressures of 20–25 megapascals in carbon-fiber-wrapped aluminum or steel cylinders, delivering torque curves comparable to conventional gasoline while reducing particulate and nitrogen oxide emissions for urban air quality compliance. The public transport application segment dominates unit volume because municipal bus fleets operate on fixed routes with centralized refueling infrastructure that amortizes station capital across high daily utilization. Heavy-duty vehicles represent the fastest-expanding structural category as long-haul operators seek fuel cost arbitrage against volatile diesel pricing across regional freight corridors. Fuel tanks command the largest component margin pool due to safety certification requirements and specialized composite manufacturing processes that limit supplier entry.
The US EPA and NHTSA coordinate greenhouse gas and fuel economy standards that effectively credit dedicated alternative fuel vehicles against fleet-average compliance obligations. India's CEA and Petroleum and Natural Gas Regulatory Board jointly oversee city gas distribution licensing that determines refueling station density and geographic priority for CNG infrastructure rollout. Stakeholders must monitor how carbon intensity accounting rules in major automotive markets redefine the comparative emissions advantage of compressed natural gas against battery-electric and hydrogen alternatives.
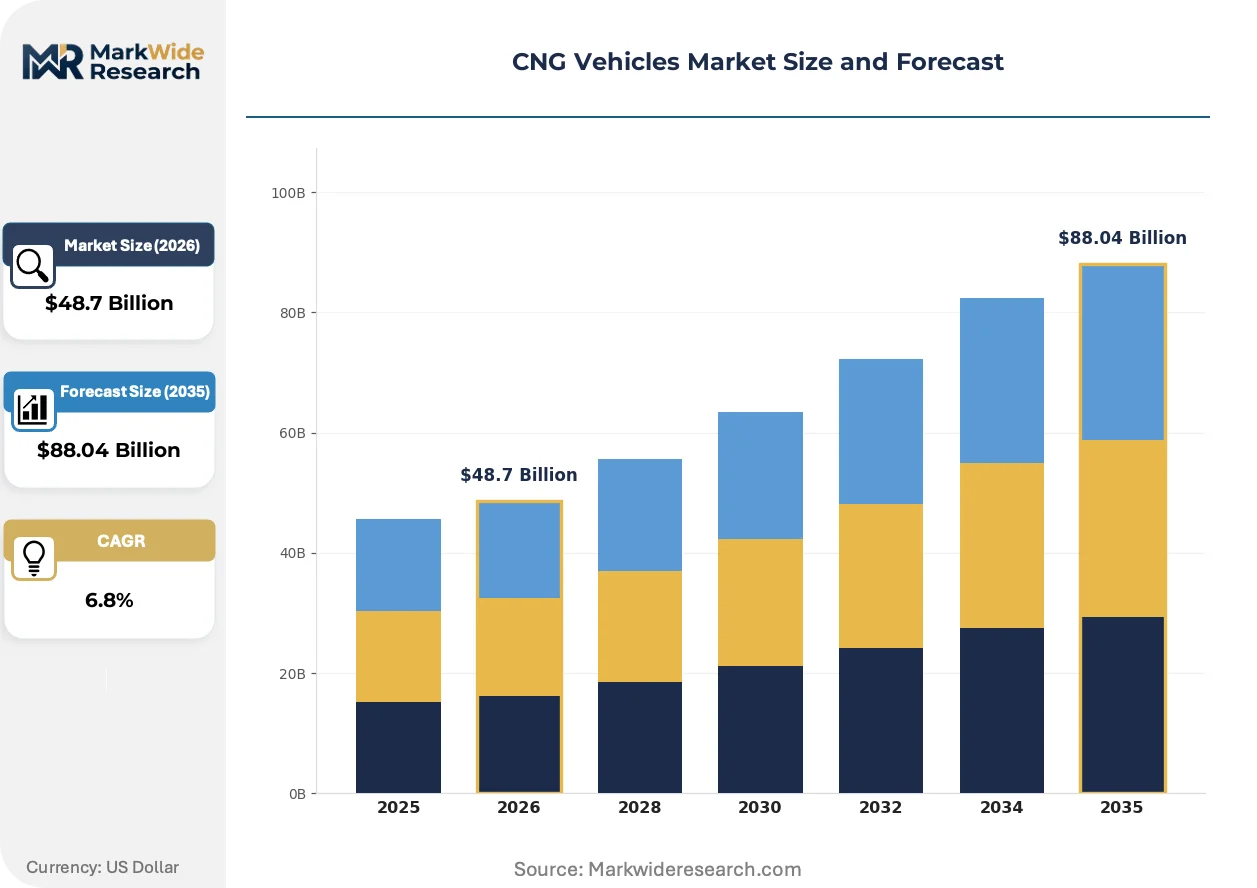
Market Dynamics
Fleet electrification mandates and carbon intensity accounting rules are compressing the comparative advantage window for compressed natural gas against battery-electric alternatives in municipal transport procurement.
Growth Catalysts
- EU Green Deal transport decarbonization targets:Heavy-duty logistics operators across Germany and Poland face binding emission reduction obligations that favor near-term CNG fleet conversion over longer-cycle battery-electric deployment.
- City gas distribution licensing expansion:India's Petroleum and Natural Gas Regulatory Board prioritizes CNG station density along Gujarat and Maharashtra freight corridors, enabling high-utilization fleet economics.
- Carbon-fiber composite cylinder manufacturing:Automated filament winding processes reduce Type-IV tank production cycle times, improving OEM supply security for high-pressure storage systems.
Market Restraints
- Natural gas price volatility:Regional pipeline supply disruptions and LNG spot market fluctuations compress fuel cost arbitrage against diesel in European freight corridors.
- Refueling infrastructure capital intensity:Station deployment requires compression equipment and high-pressure storage that amortizes poorly in low-density rural route networks.
- Battery-electric range parity:Lithium-ion energy density improvements in heavy-duty platforms threaten CNG's total cost of ownership advantage in long-haul segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic manufacturing incentives for fuel systems and pressure regulation equipment attract integrated production investments.
- Biomethane injection into grid gas:Renewable natural gas certification programs in Germany and France enable carbon-negative fleet positioning for municipal operators.
- Dual-fuel retrofit kits for existing diesel fleets:Aftermarket conversion systems open addressable market in aging heavy-duty vehicle populations across Latin American corridors.
Industry Challenges
- High-pressure vessel certification timelines:UN ECE R110 and ISO 11439 testing protocols extend product qualification cycles, delaying new tank supplier market entry.
- Composite manufacturing skill scarcity:Filament winding technicians and automated composite process engineers remain concentrated in aerospace and wind energy sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNG Vehicles Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Trucks, Buses, Heavy-Duty Vehicles Fuel Storage: Cylinder, Tube, LNG Bunker, Compressed Gas Application: Public Transport, Freight Transport, Personal Use, Emergency Services Component: Fuel Tanks, Pressure Regulators, Injectors, Electronic Control Units |
| Companies Covered | Hyundai Motor Company, Tata Motors, Volkswagen Group, Volvo Group, Renault, Ford Motor Company, Suzuki Motor Corporation, Honda Motor Company, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNG Vehicles Market Evolving Landscape
Powertrain architecture and fuel storage technology are diverging along application-specific optimization paths rather than converging on universal platform solutions.
Carbon-fiber-wrapped aluminum liner cylinders achieve 20–25 megapascal operating pressures while reducing weight penalty versus all-metal alternatives. Municipal bus fleets in Italy and Argentina prioritize Type-IV tank specifications for roof-mount configurations that preserve passenger cabin space. The storage technology landscape is bifurcating between premium composite systems for high-utilization fleets and lower-cost steel alternatives for emerging market price-sensitive segments.
The US EPA coordinates greenhouse gas standards with NHTSA fuel economy regulations that credit dedicated alternative fuel vehicles against fleet-average compliance obligations. Heavy-duty truck manufacturers respond by expanding dedicated CNG engine offerings rather than dual-fuel architectures that sacrifice efficiency. Long-haul freight operators in California and Texas leverage these credits to offset conventional diesel platform emissions in mixed fleets.
Fleet procurement committees now require total cost of ownership modeling that incorporates carbon intensity accounting and residual value risk. Municipal transport authorities in Germany and India favor multi-year fuel supply contracts with price hedging mechanisms over spot market exposure. This contractual preference shift favors established CNG suppliers with integrated trading and logistics capabilities over equipment-only vendors.
CNG Vehicles Market Segmentation
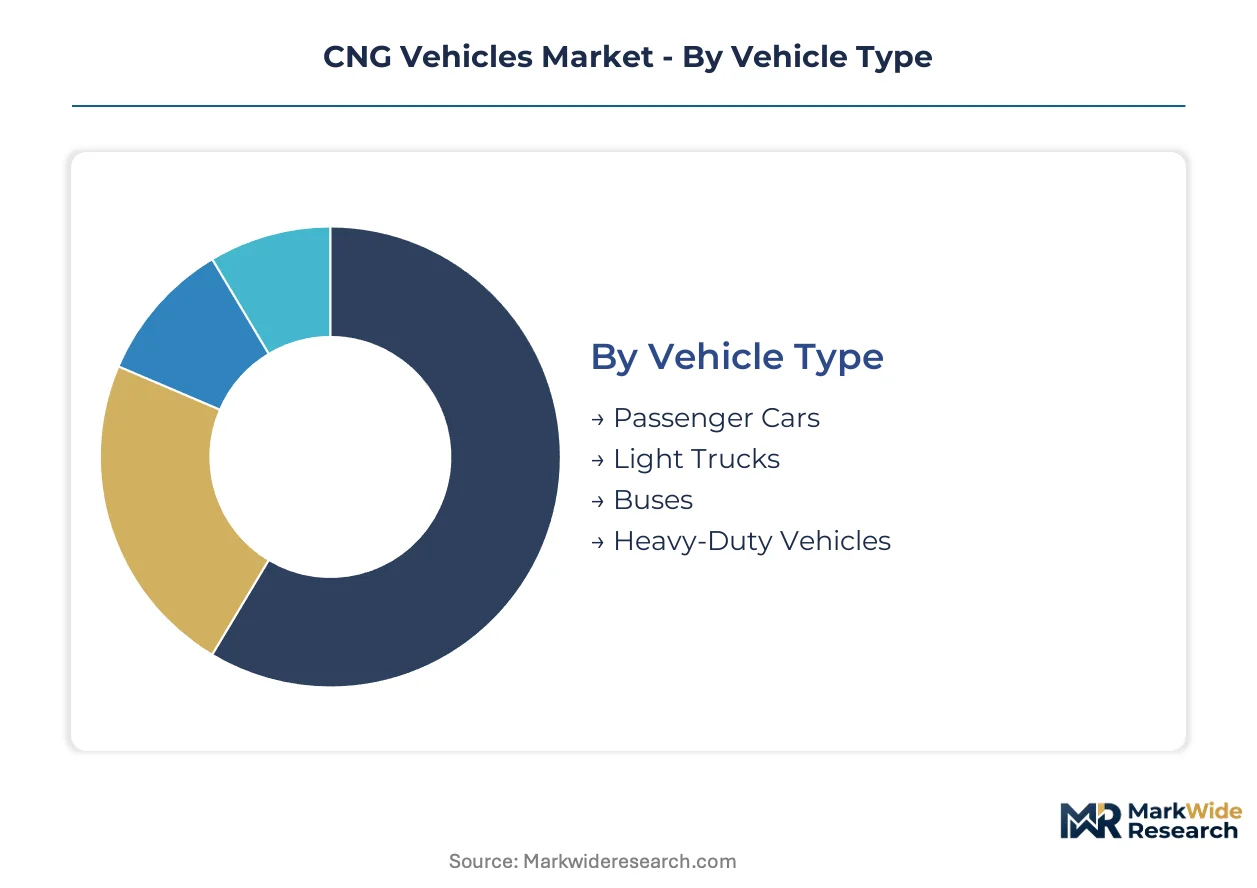
CNG vehicle segmentation reflects divergent certification requirements and infrastructure economics across mobility applications. Regulatory frameworks in Germany, India, and California create distinct compliance pathways that reshape component specifications and fleet procurement priorities.
Vehicle Type:
EU Green Deal emission targets and India's city gas distribution mandates differentiate powertrain investment by duty cycle and route predictability.
- Passenger Cars:Bi-fuel systems dominate OEM offerings, allowing gasoline fallback where refueling infrastructure remains sparse. Urban private owners in Delhi and Mumbai prioritize factory-fitted CNG variants over aftermarket conversions due to warranty preservation and Type-IV tank safety ratings.
- Heavy-Duty Vehicles:Dedicated spark-ignited engines with stoichiometric combustion achieve EURO VI compliance without selective catalytic reduction complexity. Long-haul operators across Germany's Rhine-Ruhr freight corridor exploit fuel cost arbitrage against diesel through multi-year supply contracts with municipal gas utilities.
- Light Trucks:Last-mile delivery fleets in São Paulo and Buenos Aires adopt medium-pressure storage for urban route optimization.
- Buses:Roof-mount Type-IV configurations preserve passenger cabin space in high-floor municipal transit specifications.
Heavy-Duty Vehicles handle the majority of throughput; Passenger Cars is the fastest mover on share.
Fuel Storage:
Pressure vessel certification timelines and composite manufacturing scale separate premium fleet applications from price-sensitive emerging market deployments.
- Cylinder:Type-IV carbon-fiber-wrapped aluminum liners achieve 20–25 megapascal operating pressures with 30% weight reduction versus steel alternatives. Italian and Argentinian bus operators specify roof-mount cylinder arrays to maximize passenger capacity while meeting UN ECE R110 safety protocols.
- LNG Bunker:Cryogenic storage at minus 162 degrees Celsius enables maritime and long-haul trucking applications where energy density trumps infrastructure ubiquity. European freight corridors with dedicated LNG stations favor this format for 1,500+ kilometer range requirements.
- Tube:Seamless steel construction persists in Indian light commercial vehicle retrofits where capital constraints override weight efficiency.
- Compressed Gas:Low-pressure metal tanks serve stationary engine and forklift applications with limited mobility requirements.
Cylinder configurations dominate fleet procurement volume; LNG Bunker is expanding most quickly in heavy-duty long-haul segments.
Application:
Route predictability and utilization intensity determine whether centralized refueling economics justify CNG capital deployment over battery-electric alternatives.
- Public Transport:Municipal bus fleets operate on fixed circuits with depot-based fast-fill stations that amortize compression equipment across 18-hour daily utilization. Berlin and Delhi transport authorities mandate CNG procurement for Euro VI compliance ahead of full electrification timelines.
- Freight Transport:Hub-and-spoke logistics operators in Gujarat and Maharashtra industrial corridors leverage India's Petroleum and Natural Gas Regulatory Board licensing priorities for corridor station density.
- Personal Use:Private vehicle conversions concentrate in regions with retail pump price differentials exceeding 40% versus gasoline.
- Emergency Services:Police and ambulance fleets in Rome and Warsaw prioritize bi-fuel reliability for uninterrupted service during infrastructure disruptions.
Public Transport anchors unit volume deployment; Freight Transport is gaining share fastest as corridor economics mature.
Component:
Supply security for high-pressure systems concentrates among composite specialists and precision machining houses with aerospace process heritage.
- Fuel Tanks:Automated filament winding of carbon fiber over aluminum liners requires specialized cleanroom environments and ultrasonic inspection protocols that limit qualified supplier pools. Safety certification cycles extend 18–24 months for new market entrants under ISO 11439 and UN ECE R110.
- Pressure Regulators:Multi-stage pressure reduction from storage to injection manifold demands precision machining tolerances and materials compatibility with sour gas compositions.
- Injectors:Gas-specific nozzle geometries optimize methane-air mixing for stoichiometric combustion without the lubrication benefits of liquid fuels.
- Electronic Control Units:Engine management systems coordinate spark timing, fuel metering, and knock detection across variable gas composition and ambient temperature ranges.
Fuel Tanks command the dominant margin pool; Pressure Regulators face the steepest supply concentration constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for compressed natural gas powertrain components tilts heavily toward Asian manufacturing clusters, while finished vehicle exports flow from Germany, India, and South Korea toward Latin American and Middle Eastern fleet operators seeking emission-compliant heavy-duty platforms.
India
Municipal bus procurement in Delhi and Mumbai drives Type-IV cylinder demand as city gas distribution networks expand under Petroleum and Natural Gas Regulatory Board licensing priorities. The PLI scheme for automotive components draws filament winding equipment investments toward Gujarat industrial corridors. Tata Motors anchors integrated production of fuel storage systems and pressure regulation equipment in Pune and Sanand manufacturing clusters.
Germany
Rhine-Ruhr freight operators exploit fuel cost arbitrage through multi-year biomethane supply contracts with municipal gas utilities. EU Green Deal transport decarbonization targets bind heavy-duty logistics operators to near-term fleet conversion timelines. KBA certification protocols for high-pressure vessels concentrate composite cylinder testing facilities in Stuttgart and Munich automotive engineering corridors.
United States
California and Texas long-haul fleets leverage EPA-NHTSA compliance credits for dedicated alternative fuel vehicles against mixed-fleet emission obligations. Station deployment concentrates along Interstate freight corridors where compression equipment amortizes across high-utilization logistics contracts. Cummins Westport and Clean Energy Fuels anchor refueling infrastructure partnerships in Los Angeles Basin and Dallas-Fort Worth distribution hubs.
Italy
Rome and Milan municipal transport authorities mandate CNG procurement for Euro VI compliance ahead of full electrification timelines. Biomethane injection into grid gas enables carbon-negative fleet positioning under national renewable natural gas certification programs. Iveco maintains dedicated spark-ignited engine production in Turin for European and Latin American bus export markets.
Argentina
Buenos Aires and Córdoba bus operators specify roof-mount Type-IV configurations to maximize passenger capacity while meeting UN ECE R110 safety protocols. Retail pump price differentials exceeding forty percent versus gasoline sustain private vehicle conversion demand. Local assembly partnerships with Volkswagen Group and Fiat Chrysler concentrate CNG platform production in Córdoba and General Pacheco industrial zones.
CNG Vehicles Market Competitive Landscape
Concentration sits with integrated automotive OEMs that control in-house production of high-pressure fuel storage and engine management systems. The vendor structure tiers between full-platform manufacturers, component specialists with aerospace composite heritage, and regional retrofit kit assemblers. Dominant competitive moves span backward integration into cylinder manufacturing and strategic partnerships with city gas distribution utilities for refueling infrastructure co-deployment.
Within the integrated OEM tier, Hyundai Motor Company and Tata Motors exemplify platform-scale players with dedicated CNG architecture spanning multiple assembly geographies. Volkswagen Group occupies a position emphasizing modular engine families that accommodate both gasoline and CNG injection without major block redesign. Volvo Group represents the heavy-duty specialist archetype, with Renault anchoring European light commercial vehicle offerings. Ford Motor Company and General Motors exemplify North American manufacturers leveraging EPA compliance credits through dedicated alternative fuel vehicle offerings. Suzuki Motor Corporation and Honda Motor Company occupy positions in Asian passenger car markets where bi-fuel systems dominate factory-fitted variants.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Tata Motors |
| Volkswagen Group |
| Volvo Group |
| Renault |
| Ford Motor Company |
| Suzuki Motor Corporation |
| Honda Motor Company |
| General Motors |
| Others |
Value Network & Pricing Analysis
Type-IV carbon-fiber cylinder substitution for legacy steel tanks simultaneously concentrates manufacturing geography in Asian composite corridors and compresses pricing premiums for European and Latin American fleet operators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for high-pressure storage systems. Pricing stratifies across UN ECE R110-certified premium tiers, ISO 11439-compliant standard tiers, and uncertified economy retrofit segments. Cost compression in the economy tier is intensifying because Indian and Argentinian aftermarket assemblers source unbranded steel alternatives from unregulated workshops. Municipal transport authorities exhibit the lowest price sensitivity due to total cost of ownership mandates, while private vehicle converters in emerging markets demand the steepest discounts.
Supply Chain Analysis
Panama Canal transit constraints and Red Sea routing disruptions expose filament-wound cylinder logistics to extended delivery cycles. Manufacturing gravity centers on China, South Korea, and Germany for carbon-fiber prepreg, automated winding equipment, and precision pressure regulation components. Raw material dependencies span aerospace-grade carbon fiber, 6061-T6 aluminum liners, and high-purity methane-compatible elastomers. Single-source vulnerability concentrates in Japanese Toray carbon-fiber supply. Distribution runs through Tier 1 automotive supplier networks with captive cylinder assembly at OEM-owned plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CNG vehicle market fragmentation creates specialist opportunities as fleet procurement committees bifurcate between premium composite systems and price-sensitive steel retrofits.
For Market Incumbents: Shield platform-scale position by accelerating backward integration into filament winding capacity in Gujarat and Maharashtra industrial corridors. Battery-electric range parity in heavy-duty segments threatens CNG's total cost of ownership advantage, demanding defensive certification investment in biomethane-compatible engine architectures. For New Entrants and Emerging Players: Anchor in Latin American dual-fuel retrofit markets where aging diesel fleets and retail pump price differentials above forty percent create immediate addressable demand. Target São Paulo and Buenos Aires last-mile delivery operators with medium-pressure storage kits bundled with local service partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component specialists holding ISO 11439 certification but lacking integrated gas utility partnerships. Five-to-ten year viability hinges on carbon intensity accounting rules in EU and Indian markets. Monitor biomethane injection rates into grid gas as the critical inflection signal for carbon-negative fleet positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Tata Motors' captive fuel tank production in Pune secures supply against composite material shortages. |
| Biomethane Supply Contracting | German municipal utilities' renewable natural gas certification enables carbon-negative fleet positioning for Rhine-Ruhr operators. |
| Dual-Fuel Retrofit Platform Development | Aftermarket conversion systems unlock demand in Argentina's aging heavy-duty vehicle population. |
| City Gas Distribution Partnership | Clean Energy Fuels' compression equipment co-deployment with California fleet operators amortizes station capital. |
| Type-IV Certification Acceleration | Hyundai's dedicated CNG platform architecture across Asian assembly plants reduces UN ECE R110 qualification cycles. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, municipal fleet managers, and petroleum regulatory board officials converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Petroleum and Natural Gas Regulatory Board licensing records, EPA-NHTSA compliance credit filings, and UN ECE R110 certification databases. Bottom-up vehicle production estimates triangulated against top-down city gas distribution infrastructure deployment data.
Segmentation dimensions modeled span vehicle class, fuel storage technology tier, application duty cycle, and regional regulatory cluster across the projection horizon. CAGRs derived from weighted scenario analysis incorporating biomethane penetration rates and battery-electric substitution elasticity. Industry-specific inputs include filament winding capacity expansion timelines and municipal bus procurement contract durations.
Decision-makers should treat outputs as directional under stable natural gas price assumptions and current carbon intensity accounting methodologies; material deviation in EU Green Deal transport targets or lithium-ion energy density improvements would warrant model refresh. Practitioners should keep alternative scenarios live as India's PLI scheme disbursement patterns and German biomethane grid injection mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market