
 Automotive Flex Fuel Engine Market | 2026-2036
Automotive Flex Fuel Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Flex Fuel Engine Market Analysis
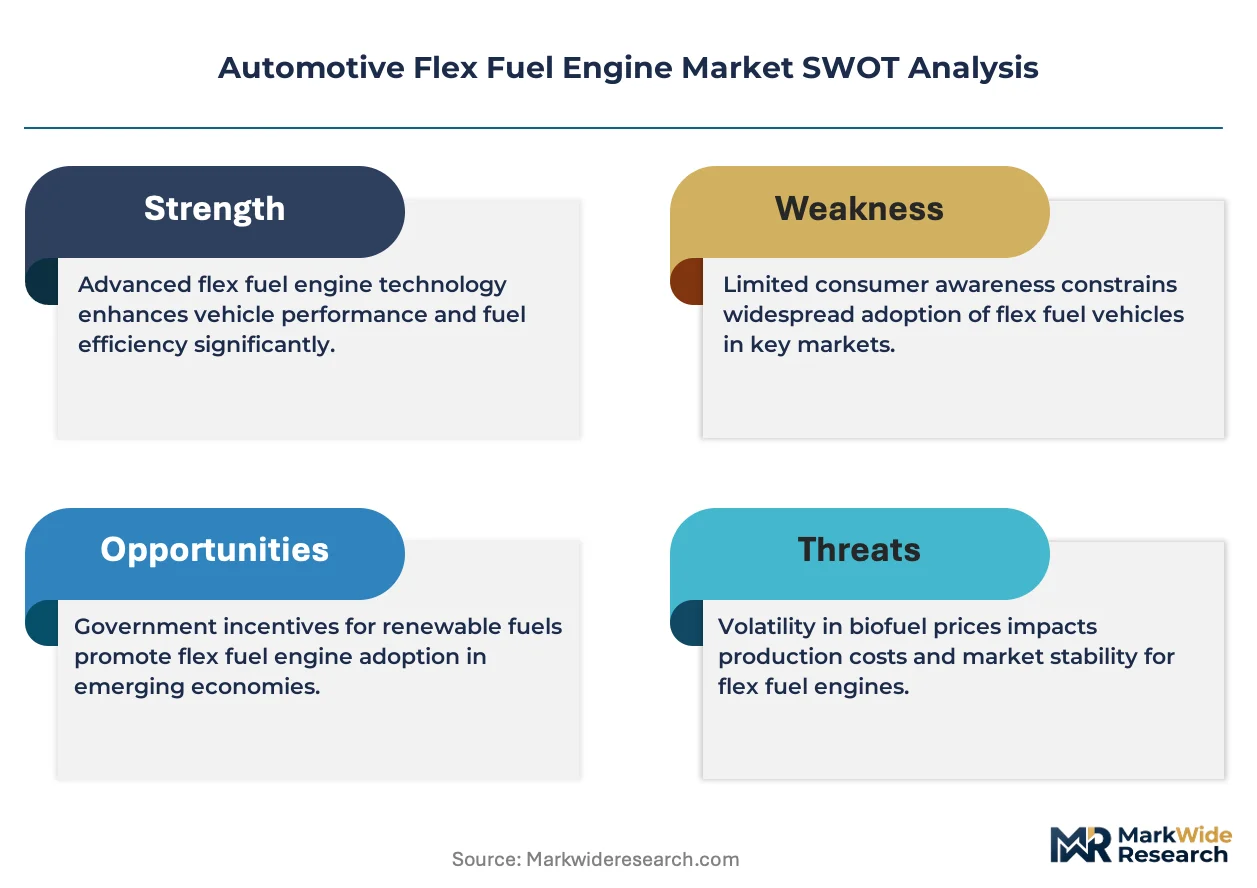
Aluminum cylinder heads is decoupling from traditional cast-iron architectures in flex fuel engine manufacturing, cutting thermal mass and improving cold-start ethanol compatibility. Ford Motor Company leverages its modular EcoBoost platform to sustain production flexibility across gasoline and E85 variants. General Motors anchors its flex fuel portfolio in full-size truck segments where fleet fuel economics drive purchasing decisions.
An automotive flex fuel engine is an internal combustion powertrain engineered with corrosion-resistant fuel injectors, stainless steel fuel lines, and recalibrated engine control modules to operate on variable ethanol-gasoline blends ranging from E0 to E85 or pure hydrous ethanol. Its primary purpose is to reduce petroleum dependency while maintaining drivability across disparate regional fuel supplies. Small and medium engines dominate OEM factory installations for passenger cars and light commercial vehicles, while heavy-duty engines command concentrated margin pools in fleet and agricultural applications. Aftermarket retrofit kits represent the fastest-growing installation channel as aging vehicle populations seek compliance with tightening biofuel mandates.
EPA renewable fuel standards and Brazil's ANP biofuel regulations shape product certification requirements and pump infrastructure investment cycles across both markets. OEMs must navigate divergent ethanol blend caps and emissions testing protocols to maintain market access. Stakeholders should monitor pending revisions to U.S. Renewable Fuel Standard volume obligations and Brazilian RenovaBio carbon intensity benchmarks as these will redirect capital toward specific engine displacement classes and fuel system architectures.
Market Dynamics
EPA renewable fuel standards and Brazil's ANP biofuel regulations are tightening emissions thresholds and redirecting capital toward ethanol-compatible powertrain architectures. Fleet operators now face compliance-driven procurement mandates that favor engines capable of operating across variable ethanol-gasoline blends.
Growth Catalysts
- EPA Renewable Fuel Standard:Volume obligations for advanced biofuels are expanding pump infrastructure across the U.S. Midwest corn-belt processing hubs, creating guaranteed offtake for E85-compatible engines.
- Fleet fuel economics:Full-size truck and agricultural equipment operators in Brazil's Sao Paulo industrial corridor are prioritizing total cost of ownership calculations that favor ethanol's price stability over petroleum volatility.
- Aluminum thermal management:Advanced cylinder head materials are reducing cold-start emissions penalties that previously limited ethanol adoption in temperate climates.
Market Restraints
- Stainless steel supply concentration:Corrosion-resistant fuel line manufacturing clusters in East Asian forging centers create input cost volatility for flex fuel system suppliers.
- Ethanol blend cap fragmentation:Divergent E85 versus E100 certification requirements between U.S. and Brazilian regulatory frameworks force redundant engineering cycles.
- Battery electric substitution:Zero-emission powertrains are capturing municipal fleet procurement contracts that previously defaulted to flex fuel as the compliance pathway.
Strategic Opportunities
- Aftermarket retrofit channel:Aging vehicle populations in Brazilian secondary cities seek ANP-compliant conversion kits to extend asset life under tightening biofuel mandates.
- Heavy-duty agricultural applications:Combine harvester and irrigation pump manufacturers represent an underpenetrated segment for E100-compatible engine platforms.
- RenovaBio carbon intensity benchmarks:Brazilian regulatory refinements will redirect investment toward specific engine displacement classes optimized for hydrous ethanol combustion efficiency.
Industry Challenges
- ECM recalibration expertise:Engine control module programming for variable ethanol blends requires specialized calibration engineering talent concentrated at OEM technical centers.
- Multi-fuel certification timelines:Simultaneous EPA and ANP homologation processes extend product launch cycles by 8-14 months for new engine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Flex Fuel Engine Market |
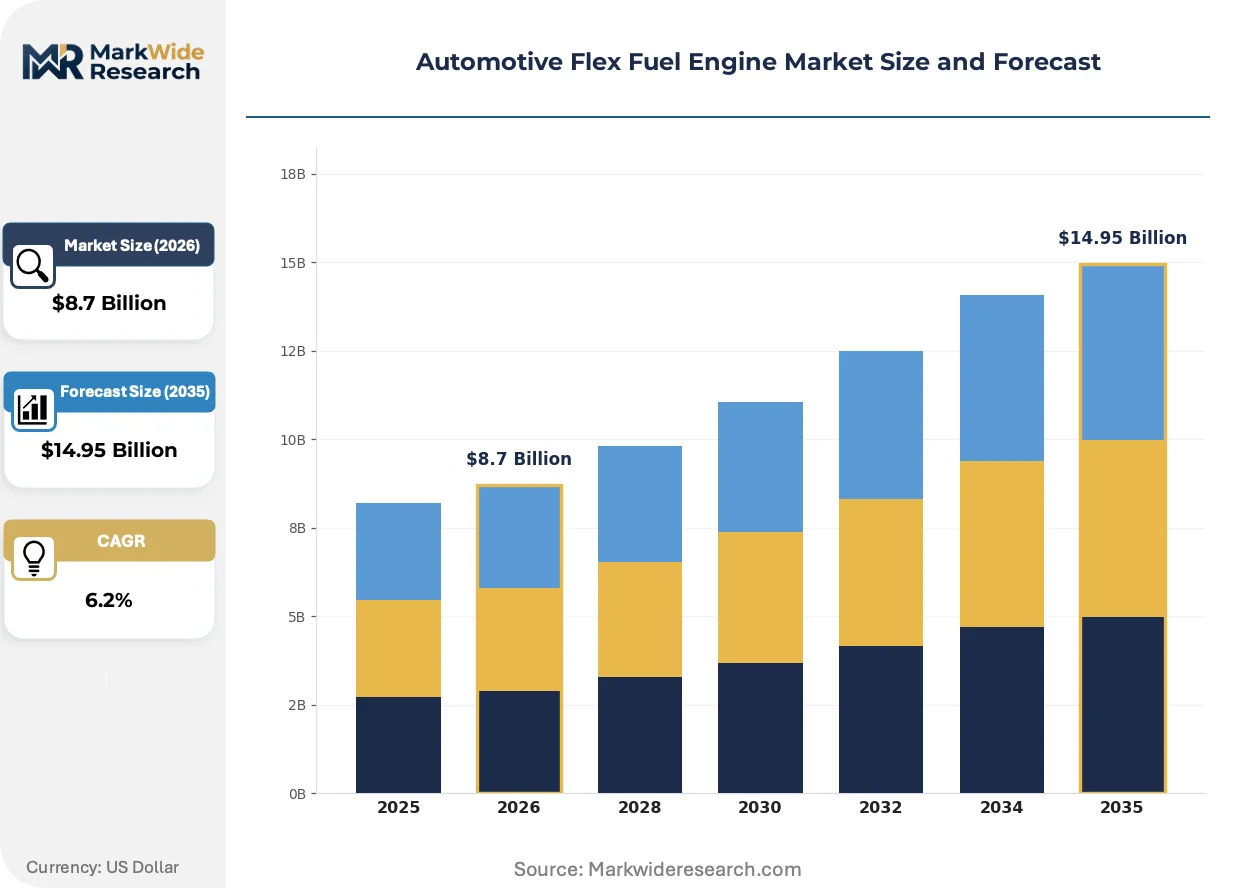
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Engine, Medium Engine, Large Engine, Heavy-Duty Engine Fuel Type: Ethanol, Methanol, Gasoline, Biofuel End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Installation Type: Factory Installation, Aftermarket Installation, Retrofit Kits, Engine Replacements |
| Companies Covered | Ford Motor Company, General Motors, Volkswagen AG, Toyota Motor Corporation, Honda Motor Co., Ltd., Stellantis NV, Nissan Motor Co., Ltd., Chrysler, Audi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Flex Fuel Engine Market Emerging Trajectories
Powertrain engineering is converging on modular architectures that sustain manufacturing flexibility across gasoline, ethanol, and hybrid variants without dedicated production lines. This shift is compressing capital requirements while expanding addressable market coverage.
Direct injection system optimization is automating real-time fuel blend detection and combustion parameter adjustment. Tier 1 suppliers are integrating wideband ethanol sensors with adaptive spark timing algorithms. Agricultural equipment manufacturers are adopting these systems fastest due to variable fuel quality at remote operations. This convergence is automating the previously manual calibration burden that limited flex fuel penetration in non-OEM retrofit applications.
ANP biofuel regulations are mandating hydrous ethanol compatibility for all new commercial vehicle registrations in designated metropolitan zones. Brazilian engine foundries are retooling casting lines to accommodate higher compression ratios required for E100 operation. Light commercial vehicle segments are absorbing the steepest compliance costs as they serve dual urban and rural duty cycles with disparate fuel availability.
Fleet procurement committees are unbundling powertrain specification from chassis sourcing decisions. Large agricultural cooperatives and municipal transport authorities now issue standalone engine tenders evaluated on fuel cost elasticity over depreciation periods. This pattern is most pronounced in Brazil's interior states where ethanol price advantages against gasoline exceed 30% seasonally and fleet operators possess dedicated storage infrastructure.
Automotive Flex Fuel Engine Market Segmentation
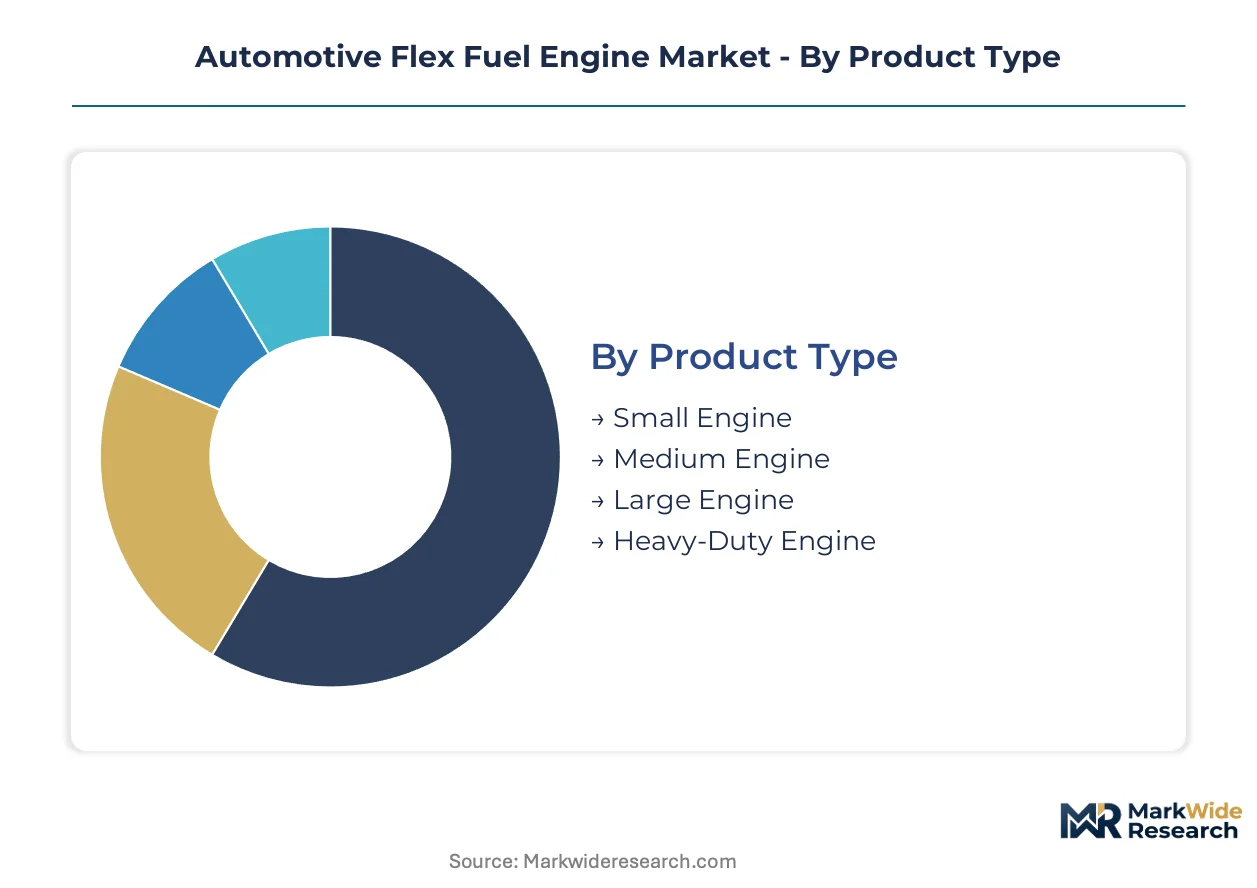
Flex fuel engine segmentation reveals divergent margin structures across displacement classes and installation channels. Factory-installed systems command premium pricing through OEM warranty integration, while aftermarket retrofits compete on compliance-driven replacement cycles.
Product Type:
Volume concentrates in commuter-vehicle displacement brackets, while premium pools concentrate in fleet and agricultural applications requiring E100 compatibility.
- Small Engine:Optimized for sub-1.6L displacement passenger cars with simplified fuel system architectures. Demand clusters in Brazil's urban commuter segments where Sao Paulo's ANP compliance zones mandate ethanol-compatible powertrains for new registrations.
- Medium Engine:Dominates light commercial vehicle factory installations with modular EcoBoost-style architectures supporting gasoline-to-E85 flexibility. Fleet procurement committees in the U.S. Midwest prioritize this bracket for total cost of ownership calculations across variable ethanol pricing.
- Large Engine:Serves full-size truck segments with reinforced fuel injectors and stainless steel line packages.
- Heavy-Duty Engine:Commands concentrated agricultural equipment margins through E100-optimized compression ratios and thermal management systems.
Today's leader: Medium Engine. Tomorrow's challenger: Heavy-Duty Engine.
Fuel Type:
Certification complexity fragments engineering resources across divergent blend specifications and regional regulatory thresholds.
- Ethanol:Hydrous and anhydrous variants dominate Brazilian and U.S. markets respectively, with ANP and EPA protocols requiring distinct engine control module calibrations. Foundries in Sao Paulo's industrial corridor are retooling casting lines for higher compression ratios demanded by E100 operation.
- Methanol:Niche applications in racing and industrial fleet trials face limited pump infrastructure outside specialized supply contracts.
- Gasoline:Baseline compatibility requirement across all flex fuel architectures, with E0-to-E85 range coverage.
- Biofuel:Emerging feedstock-diverse blends including cellulosic and waste-derived variants tracked under RenovaBio carbon intensity benchmarks.
Ethanol retains volume dominance; biofuel climbs the fastest on regulatory carbon accounting.
End User:
Procurement authority is unbundling from chassis sourcing as fleet operators and cooperatives issue standalone engine tenders.
- OEMs:Ford and General Motors anchor factory installation volumes through modular platform strategies spanning gasoline and E85 variants without dedicated production lines.
- Aftermarket Providers:Conversion kit specialists capture compliance-driven demand from aging vehicle populations in Brazilian secondary cities facing ANP mandate deadlines.
- Fleet Operators:Agricultural cooperatives and municipal transport authorities evaluate fuel cost elasticity over depreciation periods, with Brazil's interior states showing seasonal ethanol price advantages exceeding petroleum benchmarks.
- Vehicle Assemblers:Contract manufacturers serving emerging market brands source certified flex fuel powertrains from tier-1 engine foundries.
Fleet operators drive specification authority; aftermarket providers expand most quickly on mandate compliance.
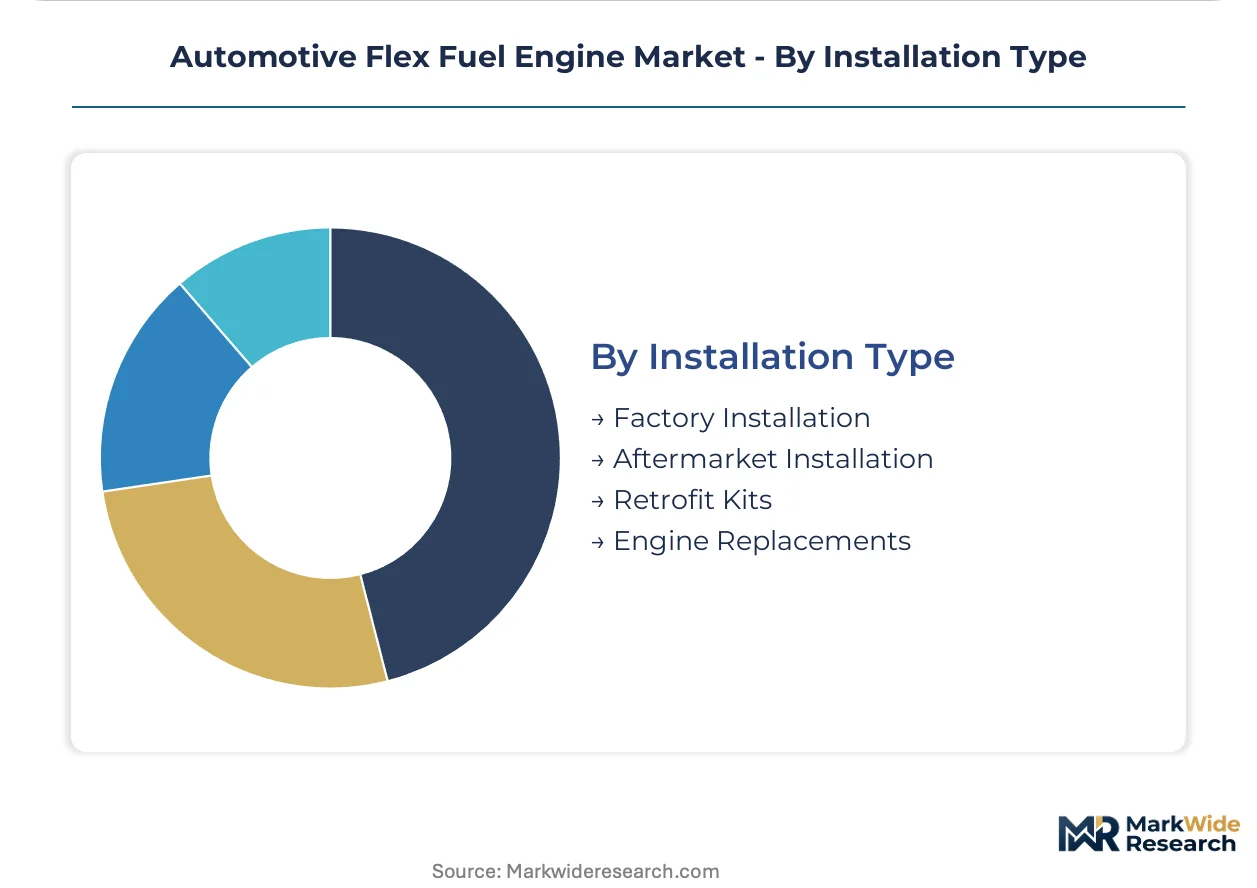
Installation Type:
Channel economics diverge sharply between warranty-integrated factory builds and price-sensitive retrofit conversions.
- Factory Installation:OEM-integrated systems with corrosion-resistant fuel injectors and recalibrated engine control modules command premium positioning through warranty coverage and emissions certification bundling.
- Aftermarket Installation:Independent service networks compete on speed of compliance conversion for existing vehicle populations.
- Retrofit Kits:Fastest-expanding channel as ANP biofuel regulations tighten and secondary-city vehicle owners seek asset life extension.
- Engine Replacements:Heavy-duty agricultural and commercial fleet segments utilize drop-in replacements during scheduled overhaul cycles.
Factory installation holds margin leadership; retrofit kits represent the steepest expansion trajectory on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors flex fuel engine manufacturing, with foundries retooling casting lines for E100-optimized compression ratios. EPA and ANP biofuel mandates are redirecting capital toward ethanol-compatible powertrains across the Americas.
Brazil
Fleet operators in São Paulo and Minas Gerais prioritize total cost of ownership calculations favoring ethanol's price stability. ANP biofuel regulations mandate hydrous ethanol compatibility for commercial vehicle registrations in designated metropolitan zones. Foundries in São Paulo's industrial corridor are retooling casting lines to accommodate higher compression ratios required for E100 operation.
United States
Full-size truck fleet operators across the Midwest corn-belt evaluate fuel cost elasticity over depreciation periods. EPA renewable fuel standards expand pump infrastructure across Iowa and Illinois processing hubs. Detroit-area technical centers concentrate engine control module calibration expertise for variable ethanol-gasoline blends.
Canada
Agricultural cooperatives in Saskatchewan and Alberta seek E85-compatible powertrains for combine harvester and irrigation pump applications. Environment and Climate Change Canada aligns vehicle emissions testing with EPA protocols. Ontario-based engine foundries supply certified flex fuel powertrains to emerging market brands through contract manufacturing arrangements.
Mexico
Vehicle assemblers in Nuevo León and the Bajío Region source flex fuel powertrains for export markets. Mexico's national energy regulator monitors biofuel blending standards for regional harmonization. Guanajuato's automotive cluster integrates corrosion-resistant fuel system components into light commercial vehicle production lines.
Automotive Flex Fuel Engine Market Vendor Landscape
Modular platform diversification dominates the current landscape as OEMs compress capital requirements across gasoline, ethanol, and hybrid variants. The vendor base stratifies into three tiers: integrated automotive OEMs with factory installation scale, tier-1 engine foundries supplying contract manufacturers, and aftermarket conversion kit specialists. Two strategic archetypes prevail: full-line manufacturers leveraging EcoBoost-style architectures, and agricultural equipment specialists optimizing for E100 thermal management. Competitive moves center on capacity expansion in Brazilian foundries and strategic partnerships for ECM recalibration expertise.
Within the integrated OEM tier, Ford Motor Company and General Motors occupy positions defined by modular platform strategies spanning gasoline and E85 variants without dedicated production lines. Volkswagen AG exemplifies the European archetype navigating divergent EPA and ANP certification requirements. Toyota Motor Corporation anchors the hybrid-flex convergence segment, representing manufacturers adapting thermal management systems for variable ethanol blends across temperate and tropical climates.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors |
| Volkswagen AG |
| Toyota Motor Corporation |
| Honda Motor Co., Ltd. |
| Stellantis NV |
| Nissan Motor Co., Ltd. |
| Chrysler |
| Audi |
| Others |
Supply Flow & Price Mechanics
Captive integration of corrosion-resistant fuel system component manufacturing anchors both supply security and margin control for flex fuel engine suppliers serving ANP-mandated Brazilian markets. Foundries in São Paulo's industrial corridor that internalize stainless steel fuel line forging and ECM calibration programming capture pricing power denied to assemblers sourcing from fragmented East Asian forging centers.
Pricing Analysis
Input-cost pass-through from stainless steel and aluminum alloy markets shapes factory-installed system pricing, with foundries indexing corrosion-resistant fuel line contracts to commodity exchange benchmarks. Premium-mid-economy pricing differentiation separates OEM-integrated warranty-backed installations from aftermarket retrofit kits competing on compliance speed. Pricing pressure stems from battery electric substitution in municipal fleet procurement, compressing margins in light commercial segments. Fleet operators in Brazil's interior states exhibit lowest price sensitivity due to dedicated ethanol storage infrastructure and seasonal price advantages exceeding petroleum benchmarks.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Ford and General Motors platform engineering teams, while independent service networks distribute aftermarket retrofit kits through Brazilian secondary cities. Geographic supply concentration centers on Brazil, the United States, and Mexico, with São Paulo foundries, Detroit-area technical centers, and Nuevo León assembly clusters anchoring regional production. Raw material dependencies include stainless steel alloys for corrosion-resistant fuel lines, aluminum cylinder head castings, and wideband ethanol sensors. Single-source vulnerability concentrates in East Asian forging centers for specialized fuel system components. Distribution runs through tier-1 engine foundries supplying contract manufacturers and OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANP biofuel mandates and EPA renewable fuel standards generate demand inelasticity for ethanol-compatible powertrain certification. Fleet procurement committees now unbundle engine specification from chassis sourcing, creating specification authority shifts that favor specialized suppliers.
For Market Incumbents: Acquire ECM recalibration engineering talent concentrated at Detroit-area and São Paulo technical centers to defend against battery electric substitution in municipal fleet contracts. Pursue backward integration into stainless steel fuel line forging to offset East Asian supply concentration. Expand capacity in Brazilian foundries serving ANP-mandated metropolitan zones before compliance deadlines tighten. For New Entrants and Emerging Players: EPA renewable fuel standard volume obligations in the U.S. Midwest open a window for aftermarket retrofit kit specialists targeting aging vehicle populations in corn-belt processing hubs. Agricultural equipment applications represent the most penetrable segment, with combine harvester and irrigation pump manufacturers seeking E100-compatible engine platforms. Pursue go-to-market partnerships with agricultural cooperatives issuing standalone engine tenders based on fuel cost elasticity calculations. For Investors and Strategic Acquirers: Consolidation pressure builds where ECM recalibration expertise concentrates at OEM technical centers and tier-1 foundries lack adaptive spark timing algorithm capabilities. Long-term viability favors suppliers with modular platform architectures spanning gasoline, ethanol, and hybrid variants without dedicated production lines. Target acquisition profiles include aftermarket conversion kit specialists with ANP certification track records in Brazilian secondary cities. Watch pending revisions to U.S. Renewable Fuel Standard volume obligations and Brazilian RenovaBio carbon intensity benchmarks as inflection indicators redirecting capital toward specific engine displacement classes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Ford's EcoBoost modular architecture sustains production flexibility across gasoline and E85 variants without dedicated lines. |
| Backward Integration | Foundries capturing stainless steel fuel line forging in-house offset East Asian supply concentration and input cost volatility. |
| Geographic Manufacturing Footprint | São Paulo industrial corridor retooling for E100-optimized compression ratios captures ANP mandate-driven demand concentration. |
| Software-Defined Vehicle Investment | Adaptive spark timing algorithms automating real-time fuel blend detection reduce manual calibration burdens in retrofit applications. |
| Long-term Supply Agreement | Agricultural cooperatives locking ethanol price stability through dedicated storage infrastructure secure total cost of ownership advantages. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 foundry procurement leads, aftermarket distributor operations heads, and fleet procurement committees at agricultural cooperatives with secondary validation. Secondary sources included EPA renewable fuel standard filings, ANP biofuel regulation updates, vehicle production databases, and IHS Markit registration data tracking flex fuel engine installations across Brazil and the United States. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Segment-weighting approaches modeled displacement class, fuel type certification, installation channel, and end-user procurement authority across the analysis window. CAGRs derived from production volume trajectories indexed to regulatory milestone timing and pump infrastructure expansion cycles. Forecast inputs incorporated OEM platform engineering roadmaps, foundry capacity expansion announcements, and fleet operator tender patterns.
Revisions become necessary when EPA or ANP regulatory frameworks shift volume obligations or carbon intensity benchmarks, when battery electric substitution accelerates in municipal fleet procurement, or when stainless steel supply concentration triggers input cost volatility. Forecasts reflect documented assumptions regarding regulatory compliance timelines and infrastructure investment cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market