
 Global Rubber Transmission Belts Market | 2026-2036
Global Rubber Transmission Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Transmission Belts Market Outlook
A shortage of compound formulation chemists is collapsing output capacity at several mid-tier manufacturers. Gates Corporation leverages captive rubber mixing facilities to insulate its supply schedule from raw-material volatility. Continental AG anchors its position through integrated testing laboratories that validate belt fatigue life under DIN 22102 protocols. Mitsuboshi Belting Ltd. dominates Asian aftermarket channels with localized distribution centers in Thailand and Indonesia.
Rubber transmission belts are reinforced elastomeric loops engineered to transfer mechanical power between rotating shafts, typically incorporating tensile members of polyester, aramid, or steel cord embedded in natural or synthetic rubber matrices cured under controlled temperature and pressure. Their primary commercial purpose is synchronous or frictional power delivery in industrial, agricultural, and automotive systems where direct mechanical coupling proves impractical. V-Belts occupy the largest share of replacement demand owing to universal compatibility with legacy pulley geometries across industrial machinery. Timing Belts command premium positioning due to precise tooth engagement requirements in automotive OEM powertrain assemblies. Synthetic Rubber formulations are displacing natural rubber in high-temperature conveyor applications within mining and material handling.
REACH in the European Union restricts polycyclic aromatic hydrocarbon content in rubber compounds, compelling reformulation of belt edge stocks and cover grades. EPA enforcement under the Toxic Substances Control Act affects U.S. imports of chloroprene-based timing belts from certain Asian suppliers. China's GB/T 1171 standard mandates minimum tensile strength thresholds for agricultural equipment belts sold domestically. Stakeholders must monitor evolving chemical compliance thresholds in their target export jurisdictions before committing to compound recipes or supplier qualification programs.
Market Dynamics
REACH compliance in the European Union is forcing wholesale reformulation of rubber compounds, collapsing output capacity at mid-tier manufacturers while integrated players capture displaced volume through captive mixing facilities.
Growth Catalysts
- Chile and Peru mining expansion:Bulk ore transport operations in the Atacama Desert and Andean copper belts are expanding belt procurement for conveyor systems handling sulfide concentrates.
- GB/T 1171 standard enforcement:China's agricultural equipment mandate is accelerating replacement cycles for combine harvester and irrigation pump belts across Shandong and Henan provinces.
- Aramid tensile member adoption:High-modulus synthetic fiber reinforcement is penetrating heavy-duty industrial power transmission where steel cord weight penalties previously limited deployment.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian latex supply disruptions transmit directly to compound costs, compressing margins for non-integrated processors.
- Chloroprene regulatory friction:EPA enforcement under the Toxic Substances Control Act restricts U.S. import channels for neoprene-based timing belts from certain Asian supply bases.
- Polyurethane synchronous belt substitution:Thermoplastic elastomer alternatives are capturing low-load precision applications in packaging machinery and 3D printing equipment.
Strategic Opportunities
- Indonesian aftermarket penetration:Mitsuboshi Belting's localized distribution model in Jakarta and Surabaya demonstrates scalable channel architecture for palm oil processing and rubber plantation equipment.
- EU Green Deal chemical transition:Bio-based synthetic rubber development aligns with ECHA low-carbon compound roadmaps for industrial belt cover grades.
- Predictive maintenance integration:IoT-enabled belt wear monitoring converges with industrial asset management platforms to create condition-based replacement revenue streams.
Industry Challenges
- Compound formulation chemist scarcity:Specialized rubber chemistry expertise concentration at top-tier manufacturers leaves mid-cap producers unable to qualify new REACH-compliant recipes.
- DIN 22102 certification timelines:Extended belt fatigue life validation protocols delay product launches for mining conveyor applications in German and Austrian export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Transmission Belts Market |
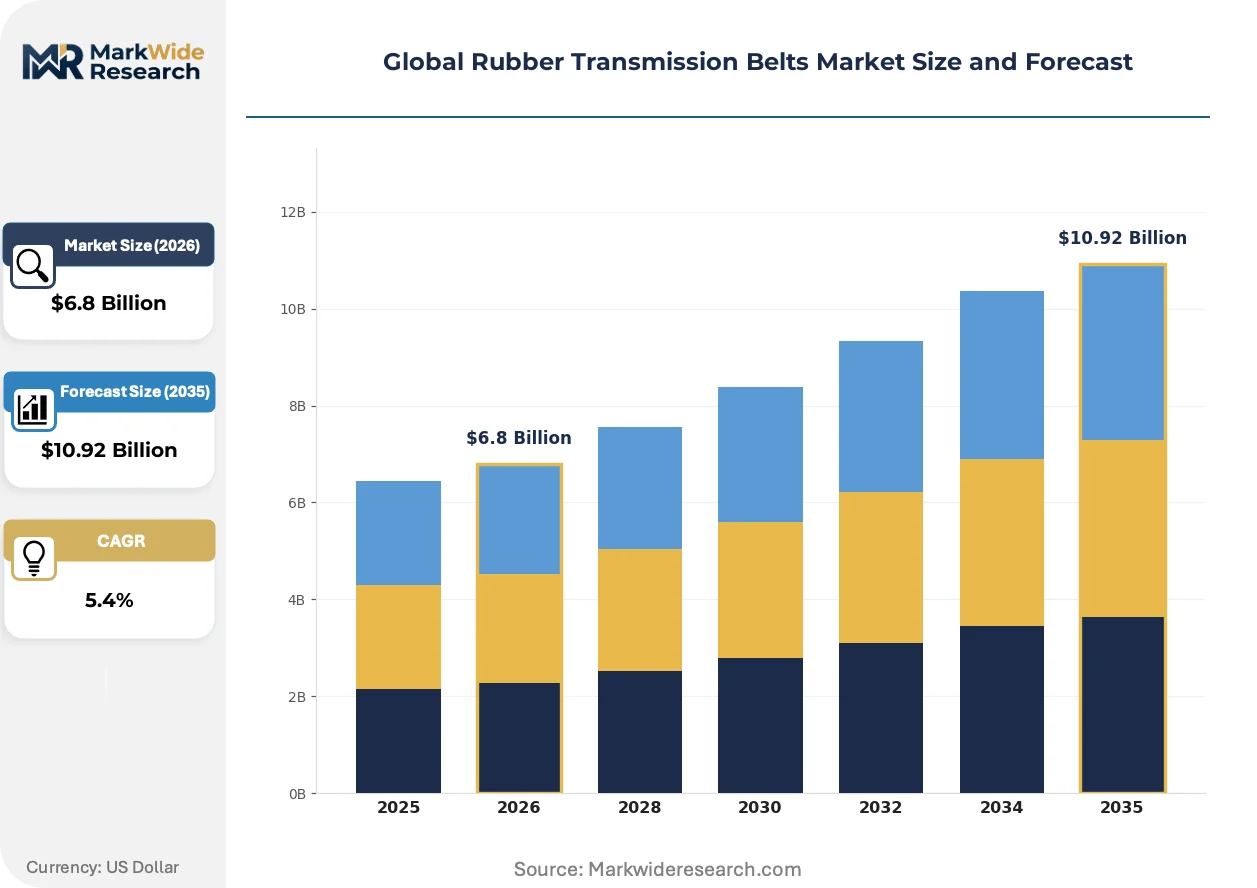
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Belts, V-Belts, Flat Belts, Timing Belts End User: Automotive OEMs, Food Processing, Mining, Material Handling Application: Power Transmission, Conveyor Systems, Agricultural Equipment, Industrial Machinery Material: Natural Rubber, Synthetic Rubber, Polyurethane, Composites |
| Companies Covered | Mitsuboshi Belting Ltd., Dayco Products LLC, Gates Corporation, The Goodyear Tire & Rubber Company, Fenner PLC, Continental AG, Optibelt GmbH, Habasit AG, Bando Chemical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Transmission Belts Market Strategic Shifts
Material science advances and regulatory chemistry mandates are restructuring competitive advantage around compound control and testing infrastructure rather than molding capacity alone.
Ethylene propylene diene monomer (EPDM) formulations with saturated backbone structures are displacing polychloroprene in outdoor power transmission applications. Mining operators in Chile's Atacama operations and Peruvian Andean sites are specifying EPDM V-belts for UV and ozone resistance at altitude. This displacement is compressing neoprene demand in heavy industrial segments while elevating compound complexity requirements.
REACH polycyclic aromatic hydrocarbon restrictions are tightening disclosure thresholds for rubber edge stocks and cover compounds sold into EU member states. The regulation compels reformulation of carbon black grades and process oil selections across belt product lines. Mining conveyor suppliers serving German and Austrian bulk material handling projects face accelerated supplier qualification timelines.
Buyer consolidation among industrial distributors is compressing replacement part procurement into fewer channel relationships with technical service capabilities. Authorized distributor networks with in-house belt tensioning and alignment expertise are displacing generic wholesale purchasing in aftermarket segments. This concentration is most visible across China's industrial machinery corridor surrounding Shanghai and Jiangsu province manufacturing clusters.
Global Rubber Transmission Belts Market Segmentation
Rubber transmission belt procurement channels diverge sharply by segment. Industrial distributors stock high-velocity V-belt SKUs for maintenance-repair-operations buyers, while OEM powertrain contracts route timing belts through tier-one supplier qualification programs with multi-year validation timelines.
Product Type:
Channel mix varies by geometry complexity. V-belts flow through broad industrial distribution, while timing belts require technical service partnerships.
- V-Belts:Trapezoidal cross-section elastomeric loops with polyester or aramid tensile cords, cured for frictional grip in pulley grooves. Replacement demand concentrates across China's industrial machinery corridor around Shanghai and Jiangsu province, driven by legacy equipment fleets requiring standardized geometries.
- Timing Belts:Synchronous toothed belts molded with precise pitch profiles for positive power transfer without slip. Automotive OEM powertrain assemblies in German and Austrian export markets specify these under DIN validation protocols, with procurement consolidating through integrated tier-one supplier networks.
- Flat Belts:Wide, thin elastomeric webs running on flat pulleys for high-speed power transmission.
- Round Belts:Solid circular cross-section belts for light-duty fractional horsepower drives in packaging and textile machinery.
By volume, V-Belts leads. By growth pace, Timing Belts is expanding most quickly.
End User:
Cost tier stratification separates premium-specification mining contracts from price-sensitive agricultural replacement cycles.
- Mining:Heavy-duty conveyor and power transmission belts engineered for bulk ore transport with steel cord or aramid reinforcement. Procurement in Chile's Atacama Desert and Peruvian Andean copper belts is accelerating as sulfide concentrate throughput expands, with operators specifying EPDM compounds for UV and ozone resistance at altitude.
- Automotive OEMs:Precision timing belts for engine camshaft synchronization with tooth profiles molded to micron tolerances. REACH polycyclic aromatic hydrocarbon restrictions are compressing qualified supplier pools for EU-bound production, favoring compound-integrated manufacturers with captive mixing facilities.
- Material Handling:Conveyor systems for warehouse automation and parcel sorting operations.
- Food Processing:FDA-compliant white rubber belts with oil and fat resistance for hygienic conveying applications.
Mining commands the highest unit values. Food Processing is climbing the fastest as sanitary specification premiums expand.
Application:
Customer type segmentation separates project-based conveyor system engineering from recurring industrial maintenance spend.
- Conveyor Systems:Continuous-loop belts for bulk material transport with multi-ply carcass construction and abrasion-resistant cover grades. Mining operators in Chile and Peru are expanding procurement for sulfide concentrate handling, with DIN 22102 fatigue life validation required for German and Austrian export projects.
- Power Transmission:Drive belts transferring mechanical power between rotating shafts in industrial machinery. China's GB/T 1171 standard enforcement is accelerating replacement cycles for agricultural equipment across Shandong and Henan provinces.
- Industrial Machinery:General manufacturing equipment drives spanning compressors, pumps, and machine tools.
- Agricultural Equipment:Harvester and irrigation pump belts exposed to outdoor temperature cycling and moisture.
Power Transmission dominates installed base. Conveyor Systems is gaining share fastest on mining capital expenditure.
Material:
Supply concentration for synthetic rubber compounds is restructuring competitive advantage around formulation control.
- Synthetic Rubber:EPDM, chloroprene, and nitrile formulations engineered for specific temperature, chemical, and abrasion resistance profiles. Mining conveyor applications in Chile and Peru are specifying EPDM V-belts for UV and ozone resistance, displacing polychloroprene in heavy industrial segments while elevating compound complexity requirements.
- Natural Rubber:Hevea brasiliensis latex-based compounds with high tensile strength and elasticity. Thai and Indonesian supply disruptions transmit directly to compound costs, compressing margins for non-integrated processors serving standard industrial power transmission.
- Polyurethane:Thermoplastic elastomer synchronous belts for low-load precision applications.
- Composites:Hybrid constructions combining rubber matrices with textile or metallic reinforcement systems.
Synthetic Rubber leads by volume. Polyurethane shows the steepest expansion trajectory in packaging machinery precision drives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance anchors European procurement standards, while mining expansion in Chile and Peru and China's agricultural equipment mandates reshape regional demand patterns across three continents.
China
GB/T 1171 standard enforcement accelerates replacement cycles for combine harvester and irrigation pump belts. MIIT industrial machinery directives concentrate procurement authority in state-owned equipment fleets. The industrial machinery corridor surrounding Shanghai and Jiangsu province manufacturing clusters absorbs the highest volume of V-belt replacement demand.
Germany
DIN 22102 fatigue life validation protocols govern mining conveyor belt qualification for export projects to Chilean and Peruvian operators. ECHA enforcement of REACH polycyclic aromatic hydrocarbon restrictions compresses qualified supplier pools for rubber edge stocks. Industrial belt testing laboratories in the Ruhr region anchor Continental AG's integrated validation infrastructure.
United States
EPA enforcement under the Toxic Substances Control Act restricts import channels for chloroprene-based timing belts from certain Asian supply bases. Agricultural equipment replacement demand concentrates across Midwest grain belt operations. Gates Corporation leverages captive rubber mixing facilities to insulate domestic supply schedules from Thai and Indonesian latex volatility.
Chile
Atacama Desert copper mining operations specify EPDM V-belts for UV and ozone resistance at altitude. National mining regulator SERNAGEOMIN oversees bulk material handling safety standards for sulfide concentrate transport systems. Antofagasta and Calama industrial zones anchor procurement for expanded ore conveyor infrastructure.
Indonesia
Palm oil processing and rubber plantation equipment drive aftermarket belt demand across Jakarta and Surabaya distribution nodes. Ministry of Industry localization incentives support domestic compound formulation capacity. Mitsuboshi Belting's localized distribution centers demonstrate scalable channel architecture for Southeast Asian agricultural machinery segments.
Global Rubber Transmission Belts Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in rubber transmission belt supply. The upper tier controls captive rubber mixing and compound formulation infrastructure, insulating production schedules from raw material volatility. Mid-cap processors face collapsing output capacity due to chemist scarcity. Two dominant competitive moves define current positioning: backward integration into synthetic rubber compounding and geographic expansion through localized distribution centers in high-growth aftermarket regions.
Within the integrated compound-control archetype, Gates Corporation and Continental AG exemplify manufacturers with in-house mixing and validation infrastructure. Mitsuboshi Belting Ltd. occupies a position representing Asian aftermarket channel depth through regional distribution localization. These three anchors demonstrate how competitive advantage is restructuring around formulation chemistry expertise and testing laboratory accreditation rather than molding capacity alone.
| Leading Market Players |
|---|
| Mitsuboshi Belting Ltd. |
| Dayco Products LLC |
| Gates Corporation |
| The Goodyear Tire & Rubber Company |
| Fenner PLC |
| Continental AG |
| Optibelt GmbH |
| Habasit AG |
| Bando Chemical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive rubber mixing capacity at integrated manufacturers creates asymmetric scale advantages that compress price floors for non-integrated processors while elevating procurement leverage for buyers with multi-year offtake contracts. Thai and Indonesian latex supply disruptions transmit volatility through compound costs, forcing tier-two suppliers into spot-market exposure that tier-one competitors with in-house formulation avoid.
Pricing Analysis
Geographic price spreads widen between EU-compliant EPDM formulations and standard chloroprene grades sold into less regulated Asian aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates DIN 22102-certified mining conveyor belts from GB/T 1171 agricultural equipment belts and generic industrial V-belt replacements. Pricing pressure stems from polyurethane synchronous belt substitution in packaging machinery precision drives. Mining operators in Chile and Peru show least price sensitivity due to specification rigidity, while agricultural replacement buyers across China's Shandong and Henan provinces concentrate volume procurement for maximum discount leverage.
Supply Chain Analysis
Strategic stockpiling of carbon black and process oils dominates inventory strategy among REACH-compliant compounders, while just-in-time latex procurement exposes non-integrated processors to Thai and Indonesian supply disruptions. Manufacturing gravity centers on China, Germany, and the United States, with synthetic rubber formulation drawing from petroleum feedstocks and aramid fiber reinforcement anchored in domestic textile supply bases. Single-source vulnerability concentrates in specialty chemical additives for low-PAH carbon black grades. Distribution runs through authorized industrial distributor networks with in-house belt tensioning and alignment expertise, displacing generic wholesale purchasing across China's Shanghai-Jiangsu machinery corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rubber chemistry expertise concentration at top-tier manufacturers leaves mid-cap producers unable to qualify new REACH-compliant recipes, restructuring competitive advantage around compound control rather than molding capacity alone.
For Market Incumbents: Compound formulation chemistry capabilities through captive laboratory accreditation and backward integration into synthetic rubber mixing facilities. Defend against polyurethane synchronous belt substitution in precision power transmission by accelerating EPDM V-belt specification capture in Chilean and Peruvian mining procurement. Prioritize DIN 22102 certification maintenance for German and Austrian export project eligibility. For New Entrants and Emerging Players: Differentiate on bio-based synthetic rubber compound development aligned with EU Green Deal low-carbon roadmaps for industrial belt cover grades. Target Indonesian aftermarket channels for palm oil processing and rubber plantation equipment through localized distribution architecture modeled on Mitsuboshi Belting's Jakarta and Surabaya presence. Pursue IoT-enabled belt wear monitoring integration with industrial asset management platforms as condition-based replacement revenue entry point. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound-integrated manufacturers with captive mixing infrastructure and accredited testing laboratories over molding-capacity-dependent processors. Long-term viability hinges on regulatory chemistry adaptation capacity across REACH, EPA, and GB/T compliance frameworks. Acquisition target archetype: mid-tier processors with stranded formulation expertise gaps but established distributor relationships. Signal to watch: extended DIN 22102 certification timelines compressing qualified supplier pools for mining conveyor applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Mixing | Insulates production schedules from Thai and Indonesian latex volatility. |
| EPDM Formulation Qualification for Mining Applications | Captures specification demand from Chilean and Peruvian altitude operations. |
| DIN 22102 Testing Laboratory Accreditation | Unlocks German and Austrian export project procurement channels. |
| Localized Distribution Center Deployment | Replicates Mitsuboshi Belting's Southeast Asian aftermarket channel architecture. |
| IoT-Enabled Predictive Maintenance Integration | Converges belt wear monitoring with industrial asset management platforms. |
Study Parameters
The analysis maps V-belt, timing belt, flat belt, and round belt product categories, each validated through maintenance directors at mining operations, procurement leads at agricultural equipment OEMs, aftermarket service heads at industrial distributors, and technical R&D directors at compound formulation facilities. Primary interview insights triangulate against customs and trade data, rubber industry association reports, SEC 10-K filings, and national standards body documentation. Bottom-up SKU-level demand modeling reconciles with top-down macroeconomic drivers across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including vehicle production databases for automotive timing belt demand, mining capital expenditure trackers for conveyor system procurement, and agricultural machinery registration data for replacement cycle estimation. Segmentation dimensions span product geometry, end-use industry, application type, and material formulation grade. CAGRs derive from regression analysis of historical shipment data and elasticity-adjusted demand projections, with aramid tensile member adoption rates and EPDM displacement curves as industry-specific forecast inputs.
Material uncertainties — natural rubber price volatility, REACH disclosure threshold revisions, and EPA enforcement scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance timelines and compound qualification success rates. Practitioners should keep alternative scenarios live as bio-based synthetic rubber development trajectories and polyurethane substitution penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market