
 Air Motor Market | 2026-2036
Air Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Air Motor Market Intelligence
A shortage of certified pneumatic technicians is redrawing competitive boundaries across the supply base. Atlas Copco AB leverages its aftermarket training academies to lock in long-term service contracts with heavy-industry buyers. Festo AG & Co. KG sustains technology leadership through deep specialization in valve-control architectures for precision automation. SMC Corporation anchors its position via manufacturing scale across Asian production hubs, competing on delivery velocity for bulk OEM orders.
An air motor converts compressed air into rotational mechanical energy through expansion-driven piston, vane, turbine, or gear mechanisms, typically operating at pressures between 0.4 and 0.7 MPa with variable speed ranges up to 30,000 rpm depending on configuration. These devices serve explosion-critical environments where electrical spark hazards prohibit conventional motor deployment. Vane air motors dominate volume shipments across material handling and pneumatic tool applications due to their compact torque-to-weight ratio and minimal maintenance requirements. Piston configurations command premium positioning in aerospace supplier workflows where precise stall-torque characteristics justify higher capital outlays. Gear air motors occupy a mature niche in marine winch drives, with margin pools eroding as Chinese producers expand planetary-gear offerings.
The EU F-Gas Regulation and REACH compliance frameworks restrict fluorinated gas use in industrial equipment, channeling investment toward compressed-air infrastructure that avoids regulated refrigerant cycles. ISO 4414 pneumatic machinery safety standards and ATEX explosion-protection directives shape product certification requirements for European market access, with non-compliant suppliers facing customs barriers. In the United States, OSHA workplace safety rules and EPA energy-efficiency guidelines influence buyer procurement specifications for manufacturing plant installations. Stakeholders must monitor evolving carbon-border adjustment mechanisms and decide whether to localize assembly within regulated jurisdictions or absorb compliance costs through supplier networks.
Market Dynamics
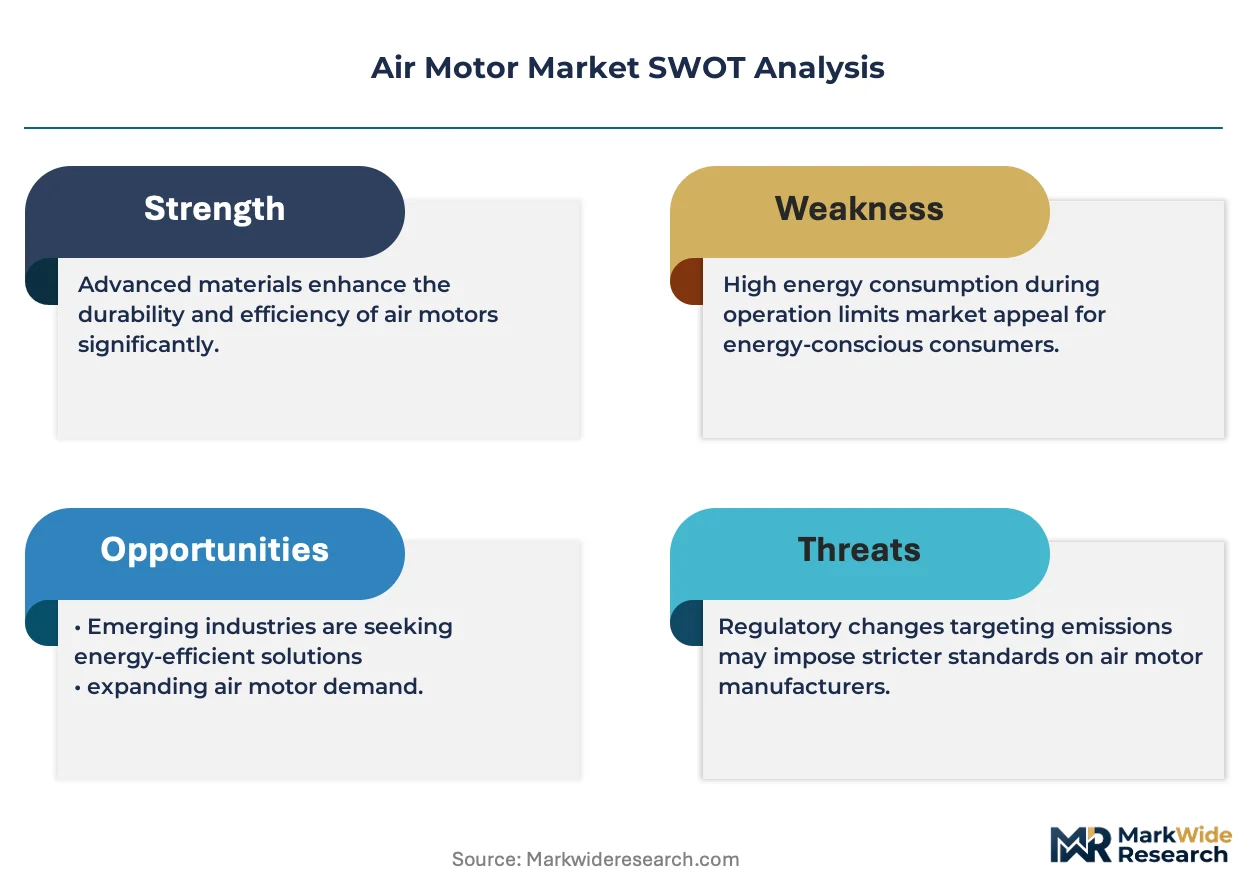
The EU F-Gas Regulation is compressing demand for refrigerant-based industrial equipment and redirecting capital toward compressed-air infrastructure, fundamentally restructuring competitive positioning across pneumatic system suppliers.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated gases in industrial cooling systems channel investment toward compressed-air alternatives that bypass regulated refrigerant cycles entirely.
- Automotive assembly automation:Pneumatic tool manufacturers in German industrial clusters around Stuttgart are expanding vane-type air motor orders for precision fastening operations.
- Explosion-critical environments:ATEX-certified air motors eliminate electrical spark hazards in oil and gas extraction facilities, chemical processing plants, and mining operations where conventional motors face deployment bans.
Market Restraints
- Compressed air energy inefficiency:Pneumatic systems convert only 10-20% of electrical input into usable mechanical work, creating lifecycle cost penalties versus direct-drive electric alternatives in energy-intensive continuous-duty applications.
- Supply concentration in precision components:High-tolerance vane and piston machining capabilities concentrate among specialized German and Japanese tooling suppliers, creating single-source vulnerabilities for tier-two assemblers.
- Substitution by brushless DC motors:Intrinsically safe brushless DC systems with sealed enclosures are penetrating Class I Division 1 environments previously reserved for pneumatic drives.
Strategic Opportunities
- India manufacturing expansion:Production-linked incentive schemes for industrial machinery are attracting pneumatic component assembly investments to serve domestic automotive and textile equipment builders.
- Carbon-border adjustment mechanisms:EU CBAM implementation creates first-mover advantage for suppliers localizing air motor production within regulated jurisdictions to avoid embedded carbon tariffs.
- IoT-enabled predictive maintenance:Integration of pressure sensors and vibration analytics with pneumatic systems enables condition-monitoring service contracts that extend customer lifetime value beyond hardware margins.
Industry Challenges
- Certified pneumatic technician scarcity:ISO 4414 machinery safety competence requirements outpace vocational training pipeline output, constraining installation and service capacity expansion.
- Legacy system integration complexity:Retrofitting modern variable-speed air motors into established compressed-air networks requires pressure-regulator recalibration and line-diameter assessment that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Motor Market |
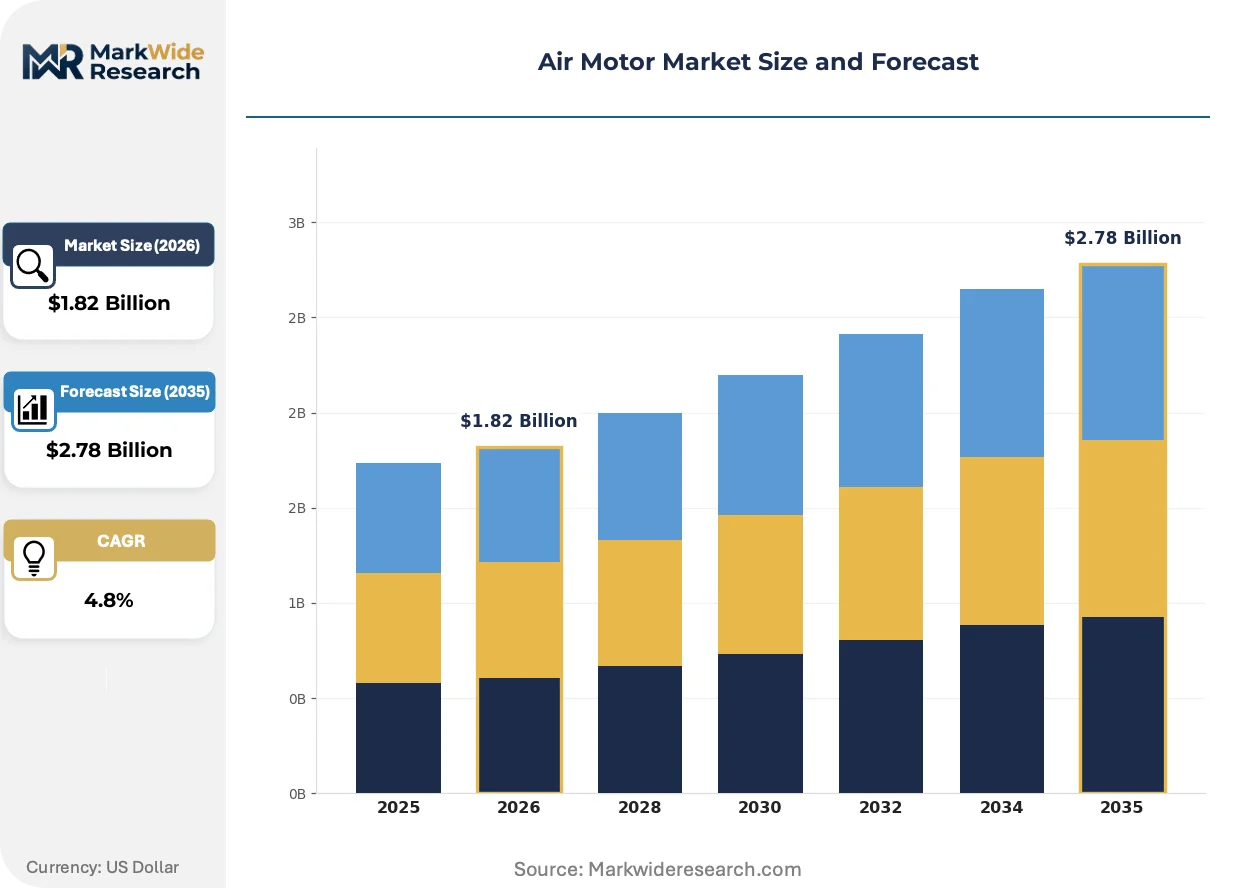
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.78 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Air Motor, Vane Air Motor, Turbine Air Motor, Gear Air Motor Technology: Direct Drive, Planetary Gear, Valve Control, Speed Regulation, Electronic Feedback Application: Material Handling, Pneumatic Tools, Textile Machinery, Packaging Equipment, Automation Systems End User Industry: Manufacturing Plants, Aerospace Suppliers, Construction Firms, Marine Equipment Providers |
| Companies Covered | SMC Corporation, Kaeser Kompressoren SE, Atlas Copco AB, Gast Manufacturing Inc., Bimba Manufacturing Company, Ingersoll Rand Inc., Festo AG & Co. KG, Norgren Ltd., Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Motor Market Strategic Shifts & Innovations
Compressed-air system architecture is fragmenting across multiple performance tiers as end-users demand application-specific optimization rather than universal pneumatic solutions.
Composite vane materials incorporating carbon-fiber reinforced polymers are fragmenting the traditional metal-vane market by delivering superior wear resistance in high-cyclic material handling equipment. Food and beverage packaging lines in the Netherlands are adopting these units for washdown-compatible conveyor drives. The shift is compressing maintenance intervals and enabling predictive replacement scheduling that reduces unplanned downtime.
REACH compliance frameworks are mandating material disclosure and restricted substance documentation for pneumatic components sold into European manufacturing supply chains. Component suppliers must maintain detailed substance inventories and safe-use instructions across their product portfolios. Air motor manufacturers serving automotive tier-one suppliers in Germany are accelerating supply chain audits to verify downstream compliance.
Buyer preference is consolidating around total-cost-of-ownership procurement models that weight energy consumption, maintenance burden, and disposal compliance more heavily than capital expenditure. Industrial distributors in the United States are restructuring sales compensation to reward lifecycle-value selling over unit-volume transactions. This behavioral shift is most pronounced among pharmaceutical and semiconductor fabrication buyers with extended equipment depreciation horizons.
Air Motor Market Segmentation
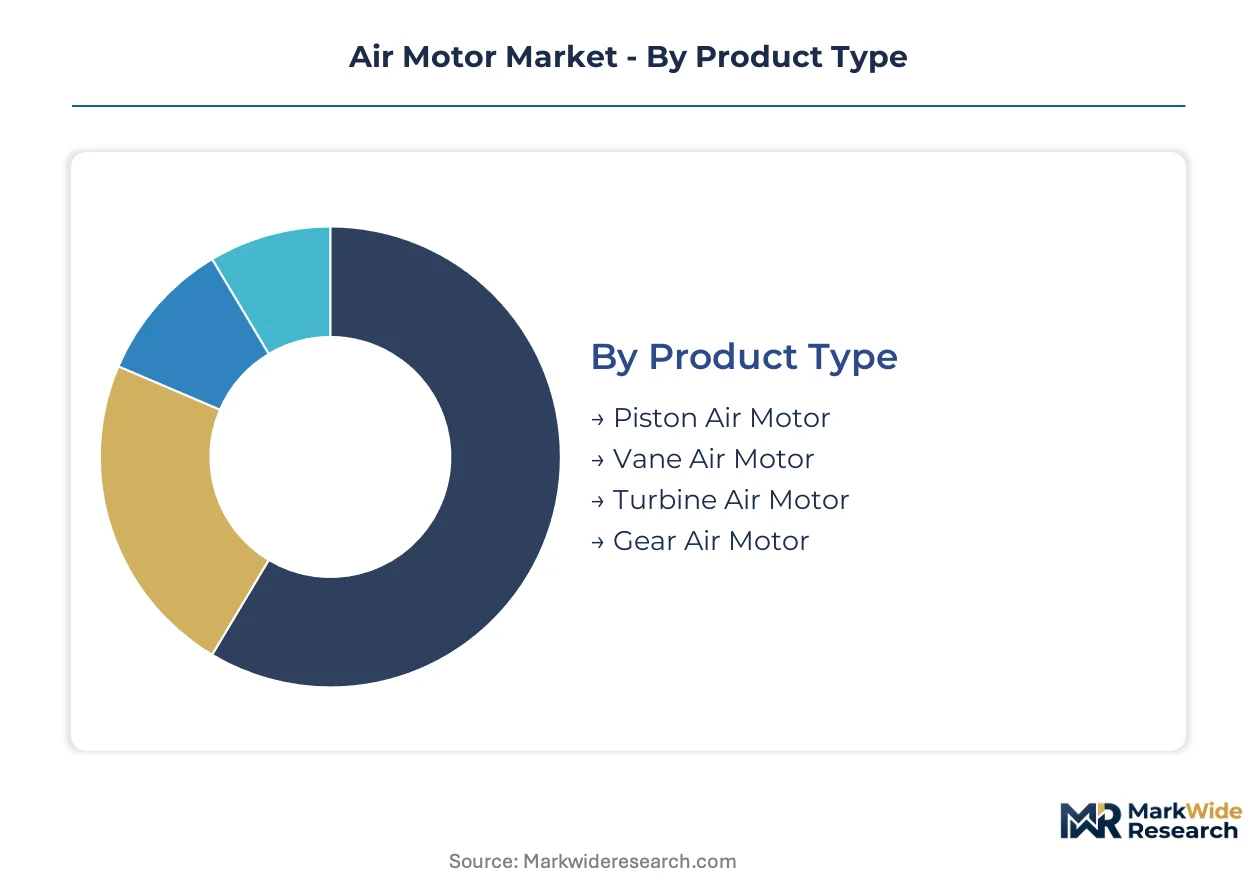
Air motor procurement channels diverge sharply by segment, with industrial distributors handling high-volume vane units for automotive assembly while direct manufacturer relationships dominate aerospace piston specifications. Understanding these channel dynamics reveals where margin pools concentrate and which segments warrant specialized sales investment.
Product Type:
Channel economics favor vane and piston configurations through contrasting routes—vane motors move through stocking distributors serving high-frequency MRO demand, while piston variants require application engineering support that rewards direct OEM partnerships.
- Vane Air Motor:Eccentric rotor with sliding vanes converts compressed air into rotational force at 0.4–0.7 MPa operating pressure. German automotive clusters around Stuttgart and Nuremberg are expanding orders for precision fastening tools, driven by assembly line automation mandates and F-Gas Regulation compliance pressures. These units dominate volume shipments through their compact torque-to-weight ratio and minimal maintenance requirements.
- Piston Air Motor:Reciprocating piston architecture delivers precise stall-torque characteristics critical for controlled tightening operations. Aerospace suppliers in Germany's industrial belt specify these for carbon-fiber composite drilling workflows where torque consistency prevents substrate delamination, justifying premium positioning despite higher capital outlays.
- Turbine Air Motor:Radial or axial turbine designs achieve speeds exceeding 30,000 rpm for high-speed grinding and polishing applications in precision metal finishing shops.
- Gear Air Motor:Planetary or spur gear configurations multiply torque output for marine winch drives and heavy-load positioning equipment, with margin pressure intensifying as Chinese producers expand planetary offerings.
Vane air motors dominate installed base across material handling and pneumatic tool applications. Piston configurations are where expansion concentrates in aerospace and precision automation workflows.
Technology:
Technology tiering follows customer sophistication—basic direct-drive units serve price-sensitive bulk buyers while electronic feedback systems command service-contract premiums from predictive maintenance adopters.
- Valve Control:Precision pneumatic valve architectures enable micro-positioning accuracy for semiconductor wafer handling and pharmaceutical filling equipment. Festo AG sustains technology leadership through deep specialization in this domain, with European pharmaceutical manufacturers specifying these systems for isolator-grade containment applications requiring 0.1 mm repeatability.
- Electronic Feedback:Integrated position sensors and closed-loop controllers enable IoT-enabled condition monitoring that extends customer lifetime value beyond hardware margins. Food and beverage packaging lines in the Netherlands are adopting these for predictive replacement scheduling that reduces unplanned downtime.
- Direct Drive:Simple rotor-to-output shaft coupling minimizes mechanical losses for continuous-duty conveyor and pump applications where capital cost minimization outweighs efficiency optimization.
- Planetary Gear:Compact torque multiplication suits space-constrained marine deck equipment and offshore platform machinery exposed to salt spray corrosion.
- Speed Regulation:Mechanical or pneumatic governing maintains constant rpm under variable load conditions for wire winding and filament tensioning operations in textile production.
Valve control architectures anchor premium positioning in precision automation. Electronic feedback systems are climbing the fastest as buyers consolidate around total-cost-of-ownership procurement models.
Application:
Application mix determines aftermarket intensity—material handling and pneumatic tools generate recurring seal and vane replacement demand, while automation systems lock in long-term service contracts.
- Material Handling:Conveyor drives, hoist mechanisms, and positioning actuators in warehousing and distribution centers. German automotive tier-one suppliers specify washdown-compatible composite vane units for assembly line conveyor systems, with REACH compliance frameworks mandating material disclosure documentation across European supply chains.
- Automation Systems:Integrated robotic workcells and pick-and-place machinery requiring synchronized multi-axis pneumatic control. Semiconductor fabrication facilities in the United States are specifying ATEX-certified air motors for solvent-handling zones where electrical spark hazards prohibit conventional motor deployment.
- Pneumatic Tools:Handheld drills, grinders, impact wrenches, and fastening equipment for construction and maintenance operations.
- Textile Machinery:Yarn tensioning, loom drives, and fabric handling equipment in spinning and weaving operations.
- Packaging Equipment:Cartoning, labeling, and sealing machinery for food, beverage, and consumer goods production lines.
Material handling commands the largest installed base by unit volume. Automation systems represent the steepest expansion trajectory as manufacturing reshoring accelerates demand for flexible production equipment.
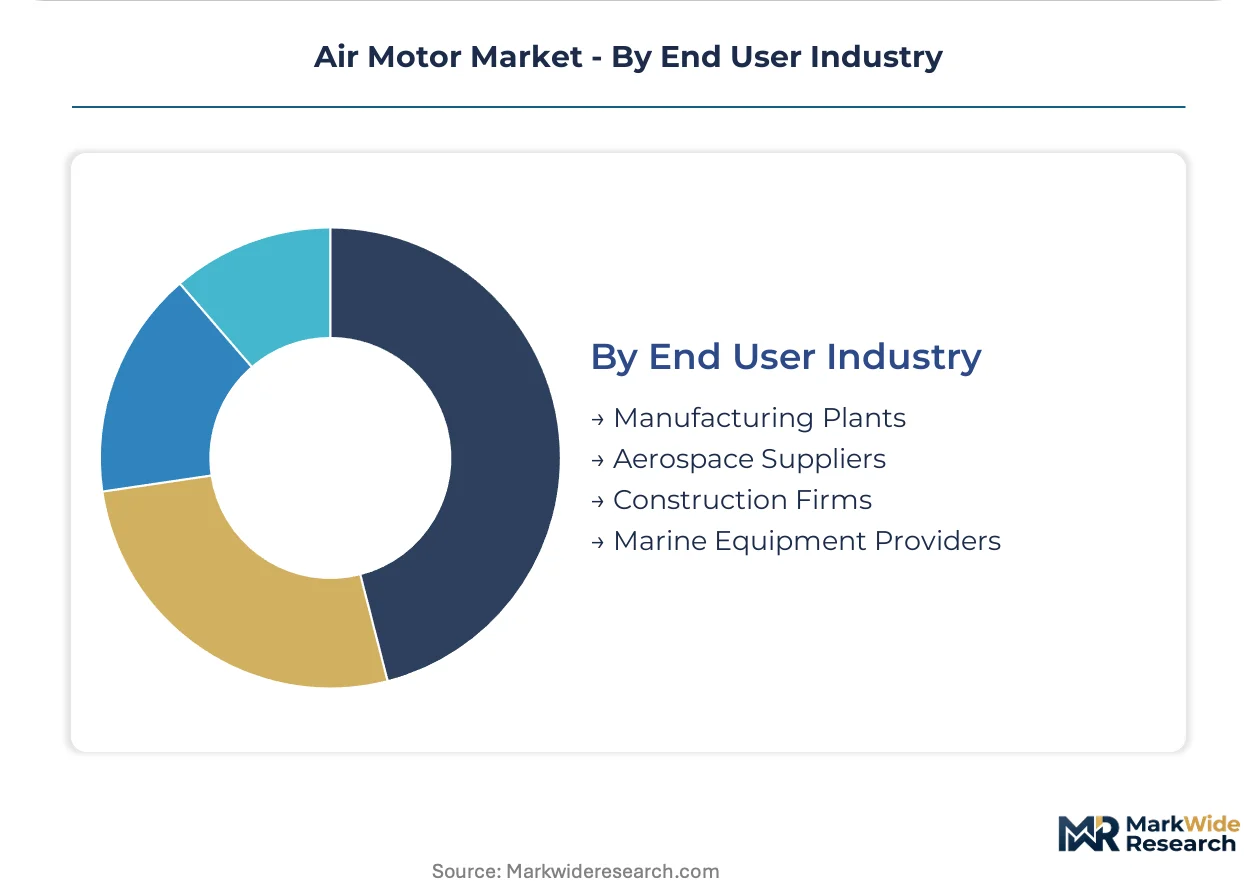
End User Industry:
End-user concentration shapes geographic sales deployment—manufacturing plants distribute demand across industrial belts, while aerospace suppliers cluster in certification-intensive regional hubs.
- Manufacturing Plants:Broad-base demand spanning automotive assembly, metal fabrication, and general machinery production. Atlas Copco leverages aftermarket training academies to lock in long-term service contracts with heavy-industry buyers across German industrial zones, addressing certified pneumatic technician scarcity that constrains competitor expansion.
- Aerospace Suppliers:Tier-one and tier-two contractors supplying airframe and engine manufacturers with precision-machined components. These buyers extend equipment depreciation horizons and weight energy consumption heavily in procurement specifications, favoring lifecycle-value selling over unit-volume transactions.
- Construction Firms:Site-based equipment for concrete finishing, structural steel erection, and infrastructure development projects.
- Marine Equipment Providers:Deck machinery, winch systems, and cargo handling equipment for commercial shipping and offshore vessels.
Manufacturing plants dominate current demand by unit volume. Aerospace suppliers are gaining share fastest as precision requirements and extended depreciation horizons justify premium pneumatic system investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes air motors primarily through precision automation workflows, while the United States deploys them for explosion-critical extraction environments, and India absorbs volume shipments for cost-sensitive textile and automotive assembly equipment.
United States
Petrochemical facilities along the Gulf Coast specify ATEX-certified vane units for solvent-handling zones where electrical spark hazards prohibit conventional motor deployment. OSHA workplace safety rules and EPA energy-efficiency guidelines shape procurement specifications for manufacturing plant installations. Semiconductor fabrication clusters in Arizona and Texas are expanding pneumatic automation for wafer handling equipment.
Germany
Automotive tier-one suppliers around Stuttgart and Nuremberg are scaling orders for precision fastening tools driven by assembly line automation mandates. The EU F-Gas Regulation and REACH compliance frameworks restrict fluorinated gas use and mandate material disclosure documentation across supply chains. Aerospace suppliers in Baden-Württemberg specify piston configurations for carbon-fiber composite drilling workflows.
China
Marine equipment builders in Jiangsu and Zhejiang provinces are absorbing gear-type units for winch drives and deck machinery on commercial shipping vessels. MIIT industrial equipment standards and dual carbon goals pressure manufacturers toward energy-efficient compressed-air infrastructure. Yangtze River Delta manufacturing hubs are localizing planetary-gear production to serve domestic shipbuilding demand.
India
Textile machinery builders in Gujarat and Tamil Nadu are sourcing vane motors for yarn tensioning and loom drive applications under production-linked incentive schemes for industrial machinery. BIS certification requirements and DGFT import regulations shape component sourcing strategies. Automotive component suppliers in Pune and Chennai are integrating pneumatic tools into tier-two assembly workflows.
Japan
Precision automation equipment manufacturers in Nagoya and Osaka metropolitan areas specify valve-control architectures for semiconductor and pharmaceutical filling applications. METI industrial technology roadmaps and JIS standards govern pneumatic machinery safety and performance benchmarks. Kyushu-based robotics integrators are embedding electronic feedback systems for predictive maintenance contracts.
Air Motor Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that competes on application engineering depth and regional manufacturing proximity. The upper tier commands premium positioning through captive service networks and training infrastructure that locks in long-term buyer relationships. Three archetypes populate the competitive terrain: diversified industrial conglomerates with full pneumatic system portfolios, precision automation specialists with valve-control expertise, and volume manufacturers competing on delivery velocity for bulk OEM orders. Consolidation pressure is intensifying through backward integration into precision machining capabilities and strategic partnerships with compressed-air infrastructure providers.
Within the diversified conglomerate tier, Atlas Copco AB and Ingersoll Rand Inc. exemplify integrated positioning through aftermarket training academies and service contract penetration. Festo AG & Co. KG occupies a specialist position anchored by deep valve-control specialization for precision automation workflows. SMC Corporation represents the scale-driven archetype with manufacturing presence across Asian production hubs competing on delivery velocity for high-volume orders.
| Leading Market Players |
|---|
| SMC Corporation |
| Kaeser Kompressoren SE |
| Atlas Copco AB |
| Gast Manufacturing Inc. |
| Bimba Manufacturing Company |
| Ingersoll Rand Inc. |
| Festo AG & Co. KG |
| Norgren Ltd. |
| Parker Hannifin Corporation |
| Others |
Cost & Logistics Intelligence
Capacity utilization at German precision-machining centers for high-tolerance vane and piston components creates natural price floors that tier-two assemblers struggle to undercut. This concentration of specialized tooling capability concentrates pricing power among established suppliers while compressing margins for downstream integrators dependent on single-source component streams.
Pricing Analysis
Long-term service contracts dominate aerospace and heavy-industry procurement, locking in predictable revenue streams for suppliers with certified technician networks. Spot-market transactions govern high-volume vane motor sales through industrial distributors serving automotive MRO demand. Price differentiation hinges on ATEX certification tier and aftermarket service bundling. Cost compression in standard-grade vane motors is intensifying as Chinese producers expand planetary-gear offerings. Tier-two automotive suppliers exhibit highest price sensitivity; aerospace tier-one contractors prioritize lifecycle value over capital outlay.
Supply Chain Analysis
Germany and Japan anchor precision-machining output for high-tolerance vane and piston components, while China scales planetary-gear production for marine winch applications. Raw material flows draw from specialized aluminum alloys for rotor housings, carbon-fiber reinforced polymers for composite vanes, and precision-ground steel for piston assemblies. Single-source vulnerability concentrates in German tooling suppliers holding proprietary profiles for aerospace-grade piston architectures. Distribution runs through authorized industrial distributors for automotive MRO channels and direct manufacturer relationships for aerospace specification engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among German automotive tier-one suppliers and US semiconductor fabrication operators, compressing supplier margins while rewarding scale and certification depth. This consolidation elevates procurement sophistication and lifecycle-cost evaluation criteria.
For Market Incumbents: Secure captive technician training infrastructure to lock in long-term service contract renewals as ISO 4414 competence requirements outpace vocational pipeline output. Deepen backward integration into precision vane-machining capabilities to reduce single-source exposure to German tooling suppliers. Defend against brushless DC motor substitution by emphasizing ATEX-certified pneumatic safety in Class I Division 1 environments where electrical spark hazards persist.
For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance integration, targeting food and beverage packaging lines in the Netherlands where vibration analytics reduce unplanned downtime. Penetrate India's production-linked incentive schemes for industrial machinery by localizing assembly in Gujarat and Tamil Nadu to serve textile equipment builders. Pursue carbon-border adjustment advantage by establishing EU-based production ahead of CBAM full implementation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision automation specialists with valve-control expertise over volume manufacturers facing margin erosion. Long-term viability hinges on service-contract penetration and captive training academy infrastructure. Acquisition targets should demonstrate certified technician pipeline development and aerospace tier-one relationships. Watch for inflection in EU F-Gas Regulation enforcement intensity as a signal for compressed-air infrastructure investment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Reduces single-source dependency on German tooling suppliers for aerospace-grade components. |
| Certified Technician Academy Expansion | Addresses ISO 4414 competence scarcity and locks in long-term service contract renewals with heavy-industry buyers. |
| IoT-Enabled Predictive Maintenance Platform | Enables condition-monitoring service contracts that extend customer lifetime value beyond hardware margins in food packaging. |
| EU Localized Assembly Investment | Positions suppliers to avoid embedded carbon tariffs under CBAM implementation for regulated jurisdiction access. |
| Composite Vane Material Development | Captures washdown-compatible conveyor drive demand in Netherlands food and beverage packaging lines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across maintenance directors at German automotive plants, OEM procurement teams specifying pneumatic automation, aftermarket service heads managing compressed-air networks, and plant engineers evaluating ATEX-certified equipment alternatives. Secondary validation drew from SEC filings of diversified industrial conglomerates, customs records tracking pneumatic component trade flows, ISO 4414 machinery safety documentation, and REACH compliance framework disclosures. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the modeling period, segmentation dimensions included product type architecture, technology tier, application intensity, and end-user industry concentration. CAGRs were derived from installed base growth trajectories and replacement cycle analysis. Forecast inputs incorporated EU F-Gas Regulation compliance timelines, production-linked incentive scheme uptake in India, and carbon-border adjustment mechanism implementation schedules.
Forecasts assume regulatory continuity in EU REACH and F-Gas frameworks, US OSHA and EPA guidelines, and India BIS certification requirements; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in refrigerant regulation enforcement, certified technician pipeline output, and brushless DC motor penetration rates in explosion-critical environments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Automotive Motor Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
North America Electric Motor Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Implant Motors Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Electric AC Motors Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
Global Automotive Micro Motor Market