
 Automotive Alternative Fuel Vehicle Market | 2026-2036
Automotive Alternative Fuel Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Alternative Fuel Vehicle Market Outlook
Platform modularization around swappable battery packs and shared electric skateboard architectures is hardening as the dominant product configuration. Tesla Inc. leverages its proprietary 4680 cell format and vertical integration to sustain manufacturing cost advantages. BYD Co. Ltd. anchors its position through in-house production of lithium iron phosphate cells and semiconductor components. Toyota Motor Corporation differentiates via parallel development of solid-state battery and hydrogen fuel cell pathways.
An automotive alternative fuel vehicle employs a propulsion system that substitutes petroleum-derived fuels with electricity stored in rechargeable battery packs, hydrogen converted through electrochemical fuel cells, or compressed natural gas combusted in modified internal combustion engines, typically achieving tank-to-wheel efficiencies of 60-90% compared to 20-30% for conventional gasoline powertrains. Battery electric vehicles occupy the largest value pool as cathode chemistry shifts toward lithium iron phosphate and high-nickel formulations reduce cobalt dependence. Hydrogen fuel cell vehicles represent a concentrated growth corridor for heavy-duty commercial applications where energy density requirements exceed battery practicality. Plug-in hybrid electric vehicles sustain transitional demand among individual consumers with limited home charging access.
The US EPA tailpipe emission standards and NHTSA corporate average fuel economy rules mandate progressive CO2 reductions that reshape OEM powertrain investment allocation. The EU F-Gas Regulation and CE marking requirements for high-voltage systems establish technical barriers governing market access for imported vehicles. China's MIIT new energy vehicle credit system and GB/T charging standards create domestic preference effects that foreign manufacturers must navigate through joint ventures. Stakeholders must monitor divergence between regional battery passport requirements and carbon border adjustment mechanisms to anticipate compliance cost allocation across production networks.
Market Dynamics
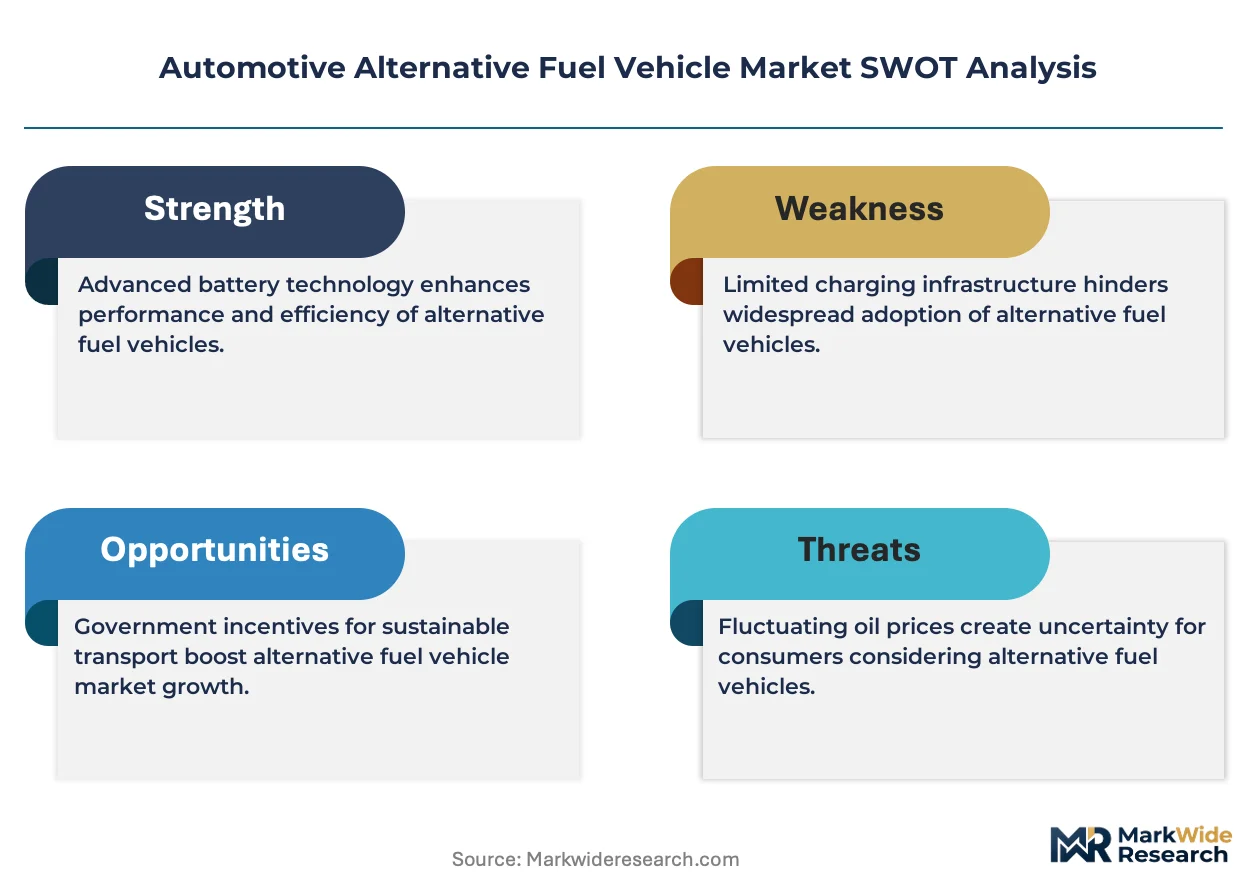
Platform modularization around swappable battery packs and shared electric skateboard architectures is hardening as the dominant product configuration, compressing development cycles and forcing tier-one suppliers to restructure component contracts around cell-to-pack integration.
Growth Catalysts
- US Inflation Reduction Act:Tax credits up to $7,500 per vehicle accelerate fleet electrification timelines for commercial operators.
- EU Green Deal CO2 fleet targets:Binding 2035 zero-emission mandates force OEM platform commitments across passenger and commercial segments.
- Cell chemistry advances:Lithium iron phosphate formulations reduce cobalt dependence while extending cycle life for mass-market applications.
Market Restraints
- Critical mineral concentration:Lithium and rare earth processing concentrates in China, creating geopolitical supply vulnerability.
- Charging infrastructure gap:Grid interconnection delays in Germany and US Midwest extend payback periods for fleet operators.
- Hydrogen fuel cell cost structure:Platinum catalyst requirements and compression energy losses limit light-duty viability.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cells attract greenfield manufacturing investments.
- Vehicle-to-grid integration:Bidirectional charging creates distributed energy revenue streams for fleet asset owners.
- Battery passport mandates:EU due diligence requirements favor vertically integrated producers with traceable supply chains.
Industry Challenges
- High-voltage systems certification:CE marking and GB/T testing protocols extend homologation timelines by 8-14 months.
- Semiconductor talent scarcity:Power electronics and battery management system engineering functions face acute hiring competition.
- Legacy platform integration:Internal combustion service networks require retraining and equipment retrofit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Alternative Fuel Vehicle Market |
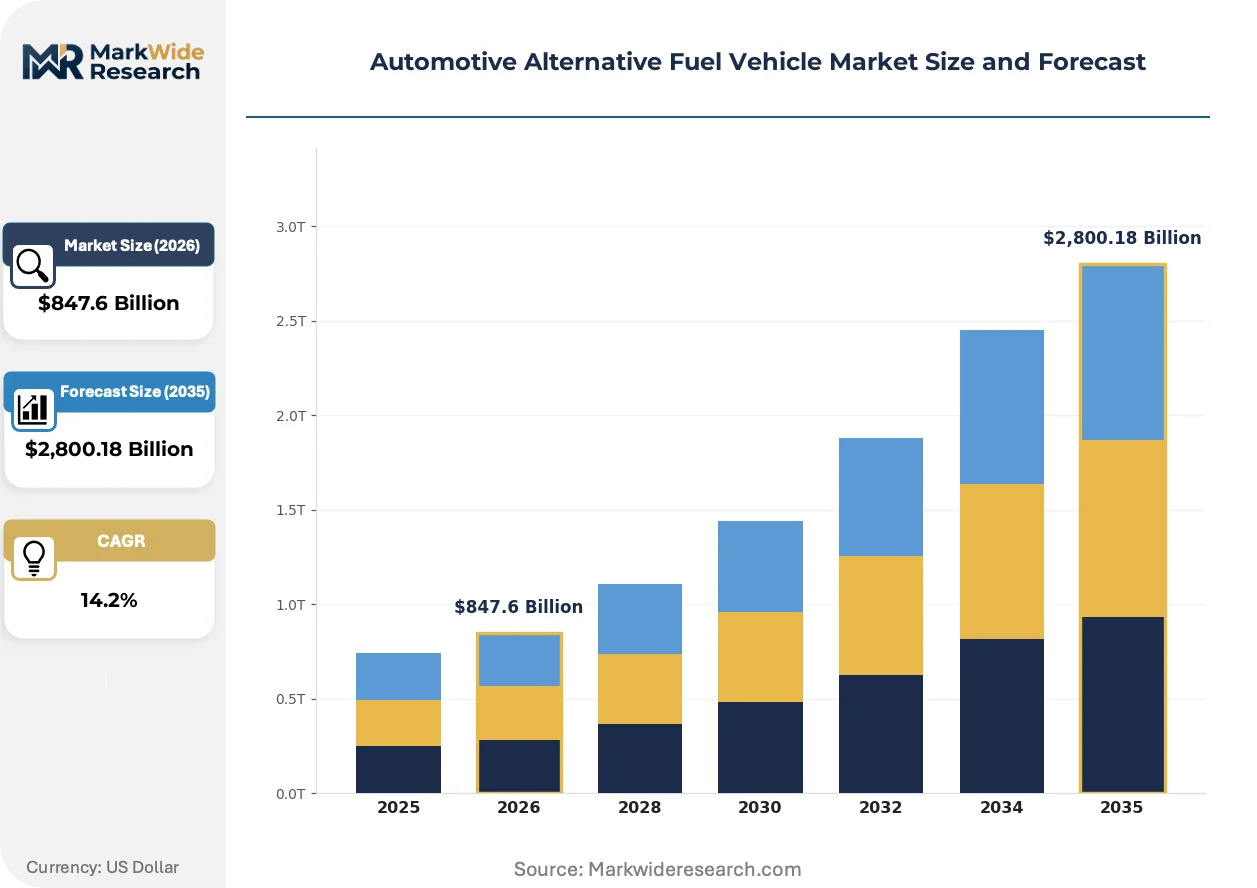
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Hydrogen Fuel Cell Vehicle, Compressed Natural Gas Vehicle Technology: Electric Drive, Fuel Cell Technology, Hybrid Technology, Compressed Natural Gas Technology End User: Government Fleets, Public Transport, Individual Consumers, Delivery Services Charging Infrastructure: Home Charging Stations, Public Charging Stations, Fast Charging Networks, Wireless Charging Solutions |
| Companies Covered | Tesla Inc., BYD Co. Ltd., Toyota Motor Corporation, Volkswagen AG, Hyundai Motor Company, SAIC Motor Corp., Stellantis N.V., Honda Motor Co. Ltd., Nissan Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Alternative Fuel Vehicle Market Strategic Shifts
Electrification is compressing traditional powertrain development cycles while simultaneously fragmenting competitive advantage sources across cell chemistry, software-defined vehicle architectures, and energy ecosystem integration.
Cell-to-pack battery architectures are eliminating module housings and cooling redundancy. Commercial van manufacturers in the Netherlands and California are adopting these platforms for last-mile delivery. This density improvement is electrifying vehicle segments previously excluded by weight and range constraints.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in thermal management systems. OEMs must redesign heat pump circuits before 2027 compliance deadlines. Heavy-duty applications face the steepest engineering cost adjustments.
Fleet operators are consolidating procurement decisions under energy-as-a-service contracts. Third-party providers now bundle vehicles, charging infrastructure, and electricity supply in single agreements. This unbundling of asset ownership from mobility service is most advanced in Germany and the United Kingdom.
Automotive Alternative Fuel Vehicle Market Segmentation
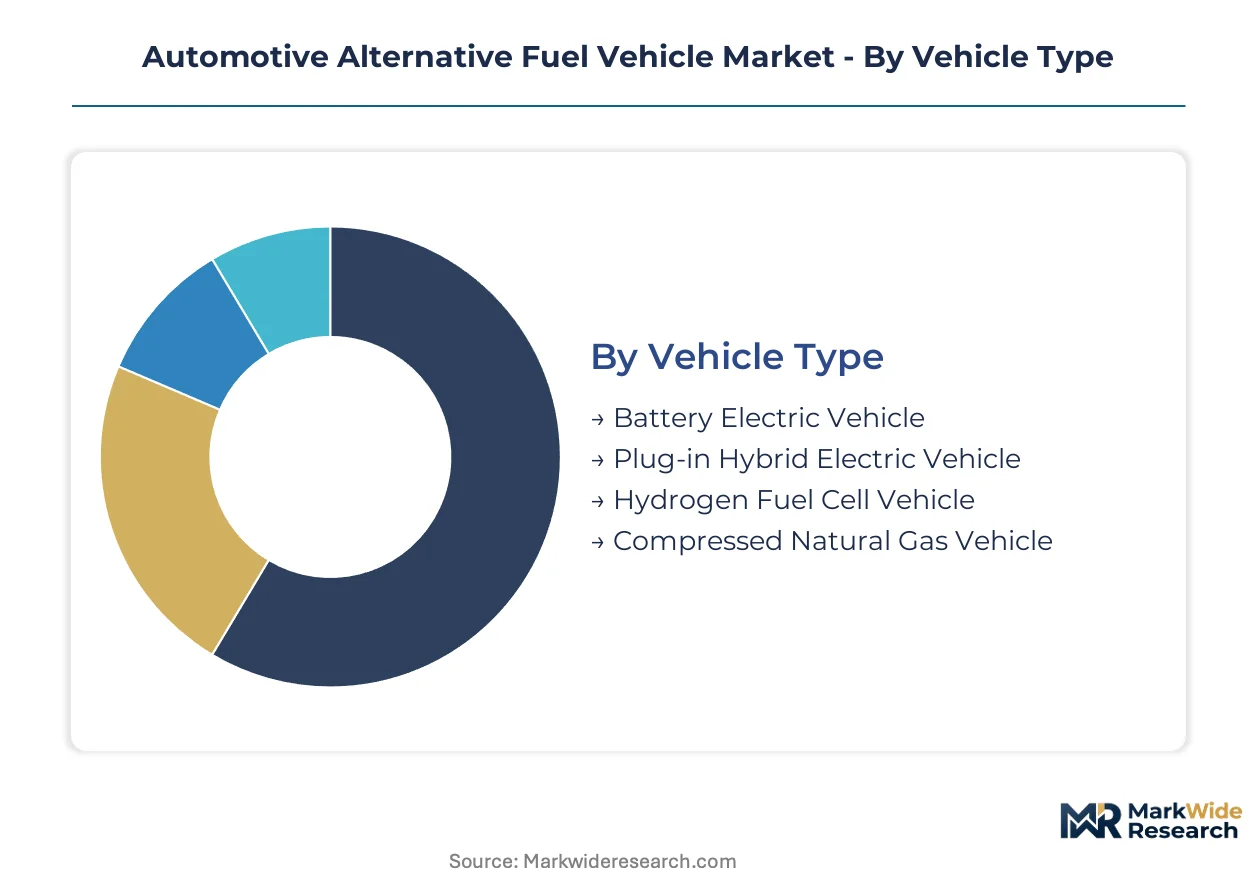
Alternative fuel vehicle segmentation reflects divergent certification burdens and infrastructure dependencies that reshape procurement economics across fleet operators and individual buyers. Each dimension carries distinct regulatory gatekeepers and capital intensity profiles that determine market entry sequencing for OEMs and charging network providers.
Vehicle Type:
Battery electric vehicles face NHTSA FMVSS 305 high-voltage safety certification and UN ECE R100 type approval, while hydrogen fuel cell variants trigger additional EPA emissions certifications and DOT hazardous material transport permits.
- Battery Electric Vehicle:Lithium-ion cell configurations utilizing NMC 811 or LFP cathode chemistries achieve 300-500 km range per charge. Demand concentrates among Chinese fleet operators and German corporate leasing programs, constrained by grid interconnection bottlenecks in rural distribution networks.
- Plug-in Hybrid Electric Vehicle:Dual-powertrain architectures combine 50-100 km electric range with combustion backup for extended duty cycles. Japanese and South Korean individual consumers with limited residential charging access sustain procurement volumes despite higher maintenance complexity.
- Hydrogen Fuel Cell Vehicle:Proton exchange membrane stacks require DOE hydrogen fueling protocol compliance and localized safety inspections.
- Compressed Natural Gas Vehicle:Modified internal combustion platforms need EPA OBD-II emissions certification and NGV2 tank integrity testing.
Battery electric vehicles sit at the top of the volume ranking, with hydrogen fuel cell vehicles climbing the fastest in heavy-duty commercial corridors.
Technology:
Technology selection determines R&D amortization periods and supplier contract structures, with electric drive systems commanding the steepest upfront engineering investment.
- Electric Drive:Permanent magnet synchronous motors with silicon carbide inverters deliver 97% energy conversion efficiency. Tesla and BYD captive production of power electronics compresses cost curves faster than outsourced tier-one sourcing.
- Fuel Cell Technology:Platinum-loaded membrane electrode assemblies face ECHA REACH substance restrictions and escalating catalyst cost volatility.
- Hybrid Technology:Power-split planetary gear systems blend mechanical and electric torque paths.
- Compressed Natural Gas Technology:Spark-ignited stoichiometric combustion requires hardened valve seats and upgraded fuel injection hardware.
Electric drive systems capture the dominant revenue share, though fuel cell technology gains traction fastest in long-haul freight applications.
End User:
End user categories segment procurement decision-making authority and total cost of ownership calculation methodologies.
- Government Fleets:Municipal and federal procurement offices apply Buy America domestic content requirements and IRA tax credit stacking. California state agencies and US Postal Service electrification mandates anchor North American demand concentration.
- Public Transport:Bus rapid transit operators specify opportunity charging protocols and depot infrastructure integration. European cities with ULEZ congestion charging zones accelerate battery electric and hydrogen bus deployment.
- Individual Consumers:Residential garage ownership and utility rate structures determine charging economics.
- Delivery Services:Last-mile logistics providers prioritize route-optimized range specifications and asset utilization metrics.
Delivery services lead volume procurement, with public transport expanding most quickly under municipal decarbonization mandates.
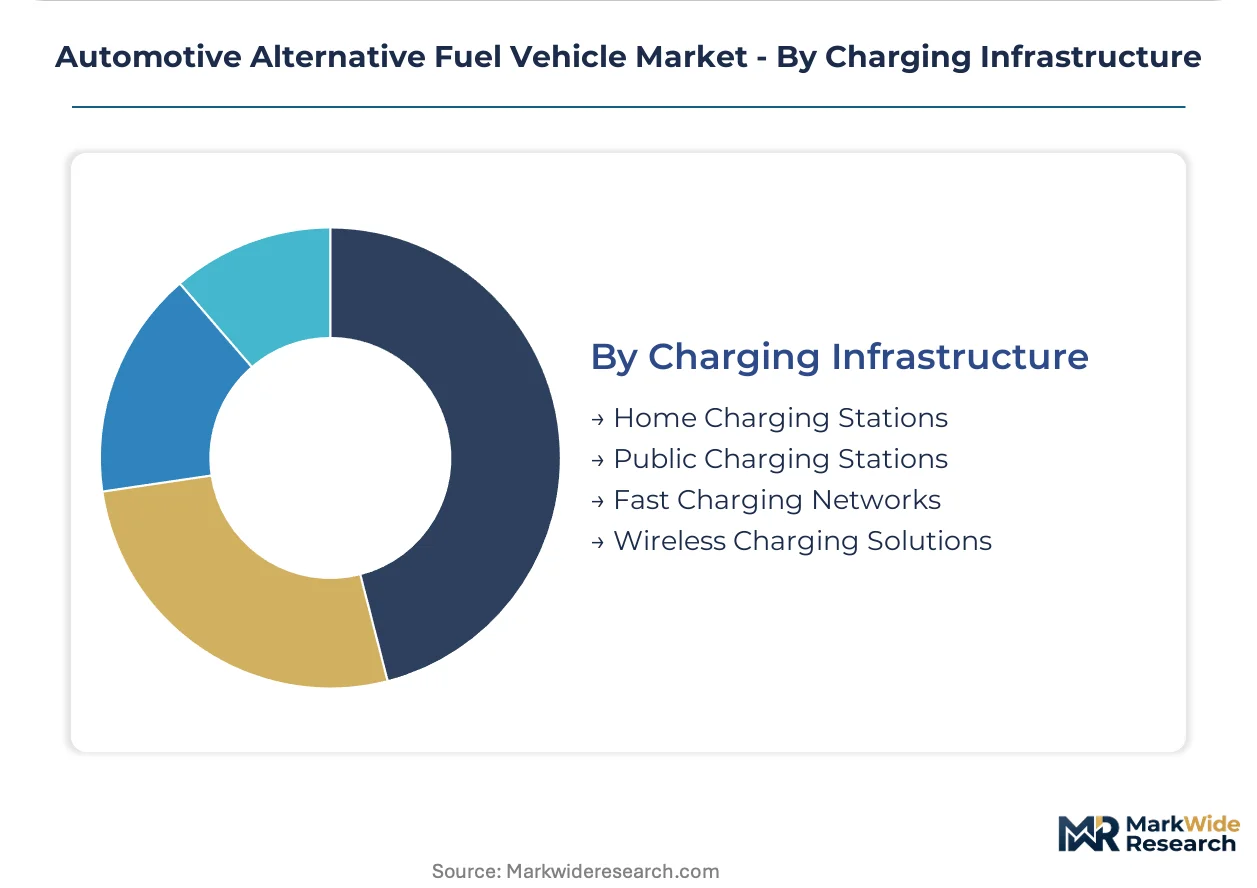
Charging Infrastructure:
Infrastructure segmentation maps capital deployment timelines against utilization rate thresholds and grid interconnection complexity.
- Home Charging Stations:Level 2 AC units (7-22 kW) require NEC Article 625 electrical code compliance and utility demand response program enrollment. German and Dutch residential markets achieve highest penetration through building code mandates and subsidy stacking.
- Public Charging Stations:Level 2 and DC fast chargers face ADA accessibility requirements and local zoning permit variances. California and Norway deploy highest density per vehicle in service.
- Fast Charging Networks:350 kW liquid-cooled cable systems need utility transformer upgrades and ISO 15118 plug-and-charge certification.
- Wireless Charging Solutions:Inductive pad systems require SAE J2954 interoperability testing and foreign object detection validation.
Public charging stations dominate installed base, with fast charging networks posting the steepest expansion trajectory among infrastructure categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive alternative fuel vehicle industry traces its modern scaling to Japan's 1997 Prius launch and China's subsequent battery manufacturing buildout during the 2010s. These origins established the dual poles of hybrid commercialization and battery cost reduction that now define regional competitive positioning.
China
Domestic fleet electrification dominates procurement volumes, with municipal bus operators and ride-hailing platforms driving battery electric absorption. MIIT new energy vehicle credit mandates force foreign OEMs into joint venture structures with local partners like SAIC and BYD. The Yangtze River Delta cluster around Shanghai anchors cathode material refining and cell-to-pack assembly lines.
United States
Commercial van and heavy-duty truck fleets accelerate electrification timelines under IRA tax credit stacking provisions. EPA tailpipe standards and NHTSA CAFE rules mandate progressive CO2 reductions that reshape powertrain R&D allocation. Michigan and California host competing engineering centers where legacy Detroit capabilities intersect with Silicon Valley battery management software development.
Germany
Industrial automotive suppliers face EU Green Deal 2035 zero-emission mandates that force platform commitments across passenger and commercial segments. KBA type approval processes and CE marking requirements for high-voltage systems extend homologation timelines. Bavaria and Baden-Württemberg concentrate fuel cell R&D corridors alongside established powertrain engineering networks.
South Korea
Battery chemistry innovation and semiconductor integration drive competitive positioning, with chaebol-affiliated suppliers controlling cathode and anode material streams. METI-coordinated hydrogen economy roadmaps support fuel cell commercial vehicle pilots. The Ulsan industrial complex hosts integrated petrochemical-to-fuel-cell manufacturing chains.
India
Two-wheeler and three-wheeler electrification leads volume penetration among price-sensitive individual consumers and last-mile delivery operators. PLI scheme production-linked incentives for advanced chemistry cells attract greenfield manufacturing investments. Tamil Nadu and Gujarat emerge as battery assembly and electric powertrain component clusters.
Automotive Alternative Fuel Vehicle Market Competitive Environment
Premium-margin players sit above commodity-margin players across battery chemistry control and software-defined vehicle architecture integration. The vendor base organizes into three tiers: captive cell producers with upstream mineral offtake, modular platform licensors, and regional assemblers dependent on outsourced powertrain supply. Consolidation pressures concentrate among tier-two suppliers lacking cell-to-pack integration capabilities. Dominant competitive moves include strategic partnerships for charging network access and backward integration into lithium refining.
Among Asia-Pacific-based manufacturers, BYD Co. Ltd. and SAIC Motor Corp. exemplify the captive-supply archetype through in-house cell production, while Tesla Inc. occupies a position defined by vertical manufacturing control and proprietary charging infrastructure. These three entities represent distinct strategic postures: the integrated Chinese state-affiliated conglomerate, the private Chinese battery-to-vehicle specialist, and the US-based software-hardware synthesis model.
| Leading Market Players |
|---|
| Tesla Inc. |
| BYD Co. Ltd. |
| Toyota Motor Corporation |
| Volkswagen AG |
| Hyundai Motor Company |
| SAIC Motor Corp. |
| Stellantis N.V. |
| Honda Motor Co. Ltd. |
| Nissan Motor Corporation |
| Others |
Value Chain & Pricing Dynamics
EU battery passport mandates and carbon border adjustment mechanisms gate qualified supply access and premium-tier pricing power for OEMs with traceable cathode material streams. Manufacturers lacking vertically integrated lithium refining face margin compression as compliance costs accumulate across tier-one supplier contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments battery electric vehicles by cathode chemistry grade and certification tier. Price differentiation rests on NMC 811 versus LFP cell formulations and CE marking or GB/T compliance status. Pricing pressure stems from cobalt and lithium price volatility transmitted through cathode material contracts. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while individual consumers in premium segments absorb technology premiums for extended-range configurations.
Supply Chain Analysis
Semiconductor talent scarcity in Bavaria and Michigan constrains power electronics and battery management system engineering capacity for tier-one suppliers. Cathode active material production concentrates in China, South Korea, and Japan, with lithium carbonate and nickel sulfate feedstocks drawing from Australian hard-rock and Chilean brine operations. Single-source vulnerability pervades rare earth magnet supply for permanent magnet motors. Distribution runs through captive cell-to-pack integration at BYD and SAIC facilities, with outsourced module assembly for legacy OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement shifts toward solid-state battery and hydrogen fuel cell platforms demanding premium engineering specifications and extended validation timelines.
For Market Incumbents: Anchor manufacturing cost advantages through backward integration into lithium iron phosphate cell production and silicon carbide inverter fabrication. Defend against BYD and SAIC volume expansion by securing cathode material offtake agreements with Australian and Chilean miners. Prioritize CE marking and GB/T certification investments to compress homologation timelines for EU and China market access.
For New Entrants and Emerging Players: Capture vehicle-to-grid integration service contracts with German and California fleet operators seeking distributed energy revenue streams. Target last-mile delivery van segments in India and Southeast Asia where two-wheeler electrification expertise transfers to light commercial applications. Deploy energy-as-a-service bundling to bypass upfront asset ownership barriers among price-sensitive municipal procurement offices.
For Investors and Strategic Acquirers: Roll-up economics work for modular platform licensors because cell-to-pack integration capabilities fragment across tier-two suppliers lacking OEM validation. Five-to-ten year viability hinges on cathode chemistry control and charging network access rather than assembly scale alone. Monitor divergence between regional battery passport requirements and carbon border adjustment implementation timelines as inflection indicators for compliance cost allocation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Shared electric skateboard architectures compress development cycles for commercial van and truck variants. |
| Battery Supply Agreement | Cathode material offtake with Australian miners secures LFP cell cost advantages against cobalt price volatility. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities differentiate Tesla and BYD from legacy OEM service network dependencies. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat assembly clusters access India PLI scheme incentives for advanced chemistry cells. |
| Charging Infrastructure Partnership | Fast charging network access determines fleet operator procurement decisions in Germany and California corridors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured OEM platform engineers, tier-one supplier procurement leads, fleet operator asset managers, and charging network development officers. Secondary validation drew from EPA tailpipe emission filings, NHTSA CAFE rulemaking dockets, MIIT new energy vehicle production databases, and EU F-Gas Regulation implementation schedules. Bottom-up vehicle registration data and top-down OEM revenue segmentation were cross-referenced for triangulation.
Historical reference periods anchored projections across the modeling period, with CAGR derivation reflecting segment-specific adoption curves and regulatory compliance deadlines. Segmentation dimensions included vehicle class, propulsion architecture, cathode chemistry tier, and regional production cluster. Forecast inputs incorporated IRA tax credit utilization rates and EU Green Deal CO2 fleet target enforcement trajectories.
Mineral price volatility, regulatory delay in carbon border adjustment mechanisms, and semiconductor talent scarcity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding cathode material cost curves and charging infrastructure deployment schedules. Material deviation in named triggers warrants pause and re-evaluation of platform commitment timelines and supplier contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
India CNG Market