
 Air Conditioning Systems Market | 2026-2036
Air Conditioning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Conditioning Systems Market Intelligence
Aftermarket service revenue is tilting toward predictive maintenance contracts as original equipment manufacturers seek recurring income streams. Daikin Industries leverages its refrigerant recycling network to capture lifecycle value from installed base units. Carrier Global anchors its competitiveness through captive supply of low-global-warming-potential refrigerants. Trane Technologies differentiates via building automation integration that extends hardware into platform-level contracts.
Air conditioning systems are electromechanical assemblies that transfer thermal energy between conditioned spaces and ambient environments using vapor-compression or absorption refrigeration cycles, typically operating with refrigerants at pressures between 150 and 450 psi. Their primary commercial purpose is to maintain temperature, humidity, and air quality parameters within specified ranges for human comfort, process stability, or equipment protection. Split systems dominate residential installation volumes across warm-climate markets, while central air configurations command premium pricing in commercial new-build projects. Inverter technology is displacing non-inverter alternatives in regulatory jurisdictions with minimum energy performance standards, creating margin concentration among compressor specialists with variable-speed motor control expertise.
The US Department of Energy enforces minimum seasonal energy efficiency ratio standards that disqualify lower-efficiency equipment from interstate commerce, while the EPA regulates refrigerant phase-down schedules under its authority to limit hydrofluorocarbon emissions. India's Bureau of Energy Efficiency operates a mandatory star-labeling program that redirects consumer demand toward inverter-equipped models rated four stars and above. Stakeholders must monitor refrigerant chemistry transitions and regional efficiency enforcement intensity to align product portfolios with compliance timelines and avoid stranded inventory in markets tightening environmental thresholds fastest.
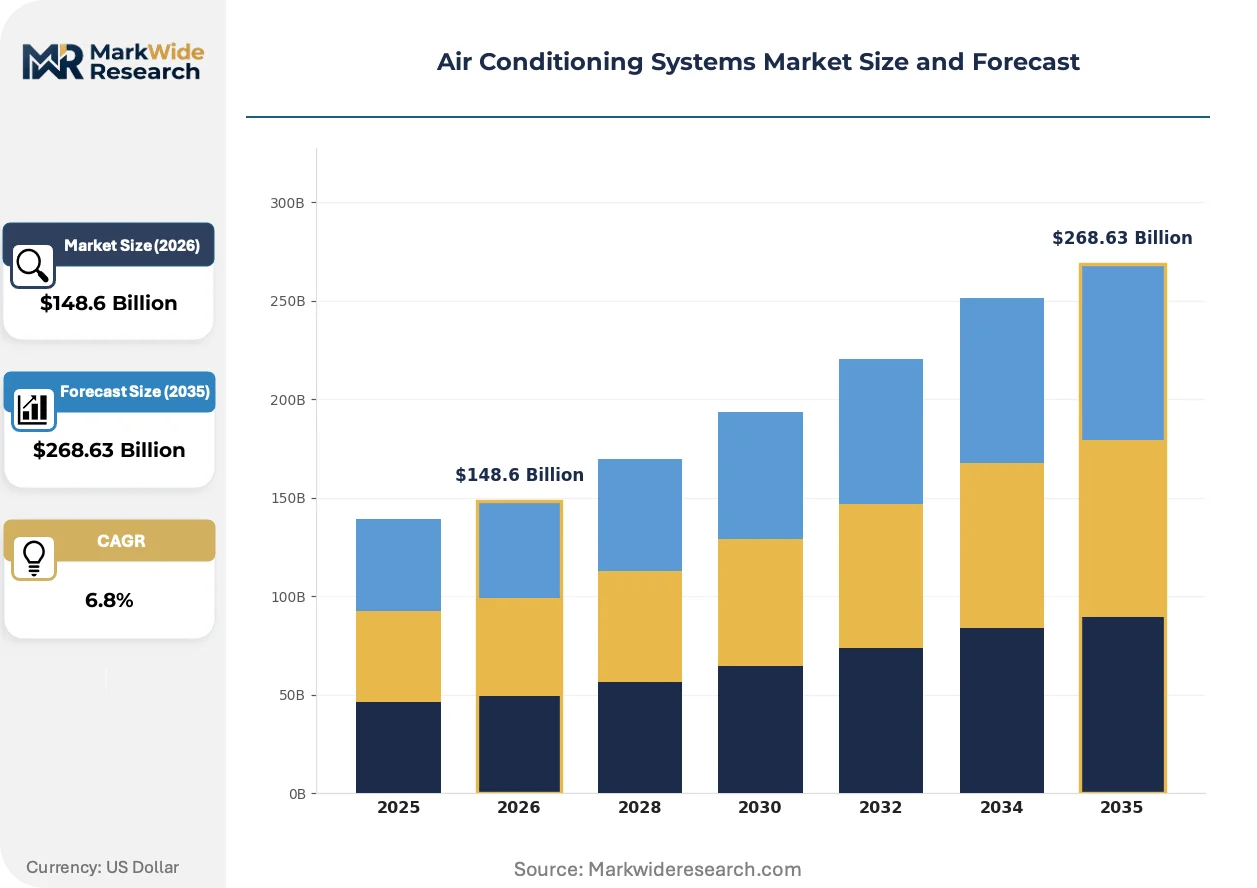
Market Dynamics
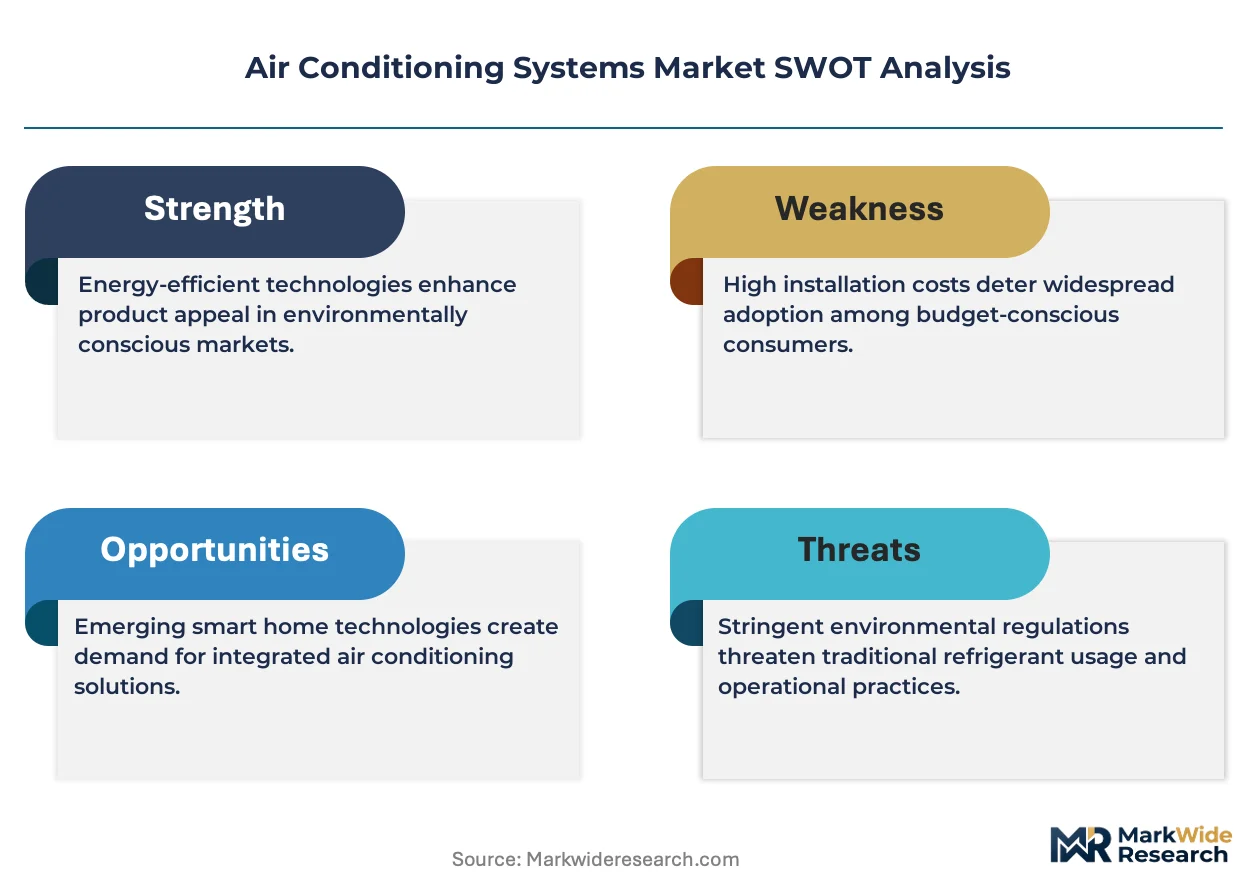
Inverter compressor technology is collapsing the cost-performance gap between premium and standard equipment tiers, forcing manufacturers to absorb R&D costs while India's Bureau of Energy Efficiency tightens minimum energy performance standards annually.
Growth Catalysts
- SEER Mandates:India's Bureau of Energy Efficiency star-labeling program redirects consumer demand toward inverter-equipped models rated four stars and above, accelerating technology turnover in the installed base.
- Electronics Assembly Concentration:Vietnam's industrial corridor cities generate precision cooling infrastructure demand as foreign electronics plants expand climate-controlled cleanroom floor space.
- Refrigerant Chemistry Transition:The EPA's hydrofluorocarbon phase-down schedule under Section 608 of the Clean Air Act creates replacement cycles for commercial equipment using legacy refrigerants.
Market Restraints
- Copper and Aluminum Volatility:Raw material input costs for heat exchangers and compressor housings fluctuate with commodity markets, compressing margin visibility for equipment manufacturers.
- Compressor Supply Concentration:Variable-speed motor control expertise concentrates among Japanese and Korean component specialists, creating bottleneck risk for inverter system assembly.
- Technical Skill Scarcity:Refrigerant handling certification requirements under EPA Section 608 and equivalent national frameworks limit qualified service technician availability in fragmented installation markets.
Strategic Opportunities
- Philippines Commercial Real Estate:Southeast Asian developers expand climate-controlled floor space faster than any buyer segment, creating premium project pipelines for central air configurations.
- Building Automation Convergence:Integration between HVAC hardware and IoT-enabled energy management platforms opens recurring revenue streams through performance-based service contracts.
- Refrigerant Recycling Infrastructure:Lifecycle value capture from installed base units expands as regulatory frameworks mandate recovery and reclamation of high-global-warming-potential refrigerants.
Industry Challenges
- Certification Timeline Compression:The US Department of Energy's seasonal energy efficiency ratio standard updates and India's parallel star-rating revisions force simultaneous product requalification across multiple jurisdictions.
- Legacy System Integration Friction:Building automation retrofits encounter protocol incompatibility between existing pneumatic controls and digital variable refrigerant flow management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Conditioning Systems Market |
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window Units, Split Systems, Central Air, Portable Units End User: Residential, Commercial, Industrial, Hospitality Technology: Inverter, Non-Inverter, Smart Controls, Eco-Friendly Systems Installation Type: Self-Contained, Ducted, Ductless, Rooftop |
| Companies Covered | Johnson Controls, Lennox International, Daikin Industries, Samsung Electronics, LG Electronics, Carrier Global, Mitsubishi Electric, Gree Electric Appliances, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Conditioning Systems Market Strategic Shifts & Innovations
Refrigerant chemistry, compressor motor control, and service contract structures are undergoing simultaneous transformation as environmental regulations and buyer procurement preferences converge on lifecycle cost optimization over first-cost minimization.
Variable-speed inverter drives are collapsing the efficiency penalty that previously separated non-inverter equipment from premium alternatives. Commercial real estate developers in Southeast Asia specify inverter-equipped central plants for new construction, eliminating the historical split between residential retrofit and commercial new-build technology tiers. The resulting compression is eliminating mid-tier product positioning and forcing manufacturers to choose between economy non-inverter exports and full-featured variable-speed platforms.
Europe's F-Gas Regulation mandates stepped reductions in hydrofluorocarbon availability through 2030, with quotas tightening faster than equipment replacement cycles. Equipment manufacturers accelerate transitions to hydrofluoroolefin blends and natural refrigerants in commercial product lines. The chillers and rooftop units serving European commercial buildings face the most accelerated retooling schedules as quota scarcity drives refrigerant price spikes.
Service procurement patterns favor predictive maintenance contracts over transactional break-fix arrangements. Original equipment manufacturers capture recurring revenue by embedding sensors in compressor and heat exchanger assemblies, selling uptime guarantees rather than replacement parts. This shift concentrates fastest in India's commercial sector, where star-rated building codes and energy audit requirements make continuous performance monitoring a compliance necessity.
Air Conditioning Systems Market Segmentation
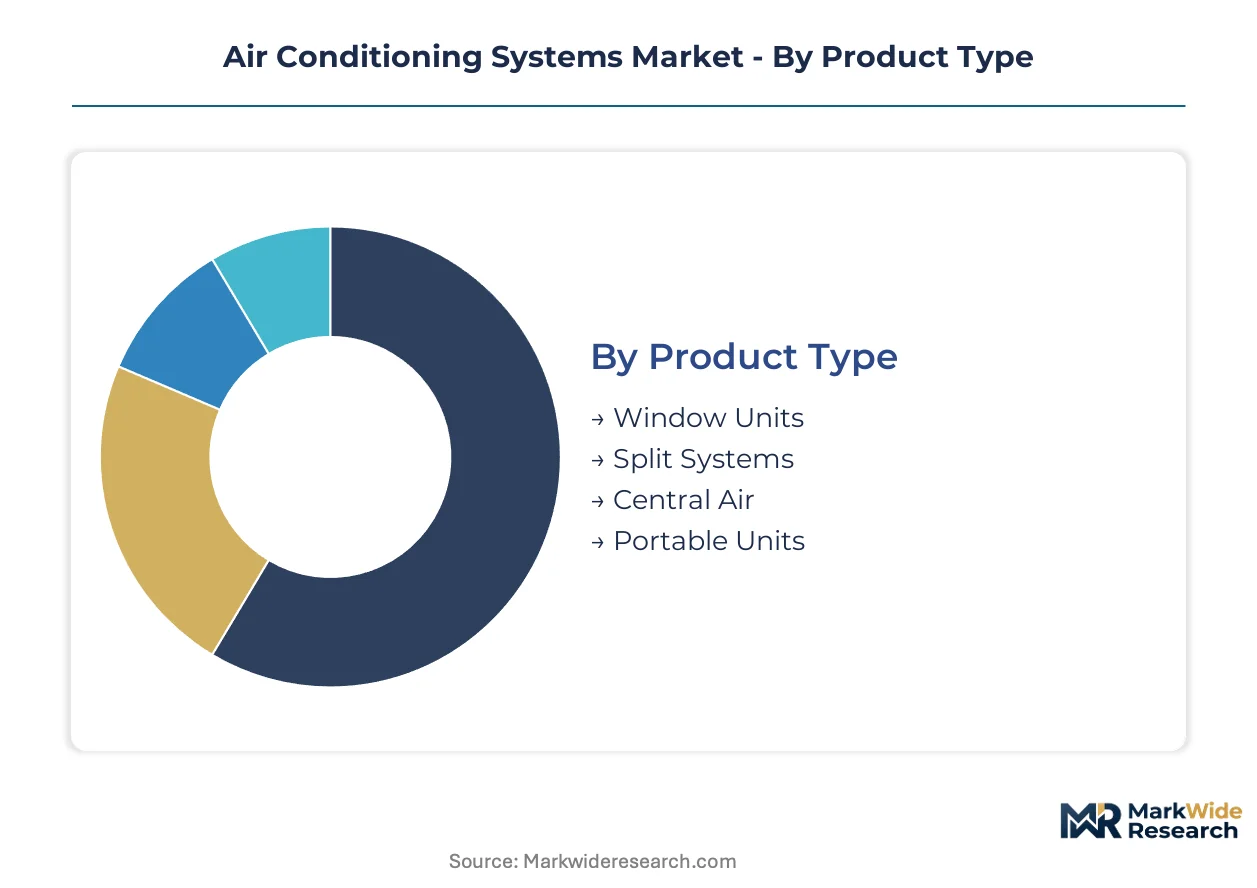
Segmentation reveals how inverter technology and regulatory pressure are fragmenting traditional product hierarchies across the air conditioning value chain. Buyers now sort equipment by lifecycle cost compliance rather than first-cost tiers, reshaping procurement patterns across residential, commercial, and industrial channels.
Product Type:
Equipment formats span from single-room solutions to building-scale central plants, each occupying distinct positions in the cost-performance spectrum.
- Window Units:Self-contained electromechanical assemblies mount through wall apertures for individual room cooling. Demand concentrates in North American rental housing and Southeast Asian urban informal settlements where installation infrastructure is limited and tenant turnover is high.
- Split Systems:Separate indoor evaporator and outdoor condenser units connect via refrigerant lines, enabling flexible zoning without ductwork. Vietnam's electronics corridor factories and India's tier-2 residential markets drive volume as BEE star-labeling mandates push inverter adoption in this format.
- Central Air:Ducted distribution systems with packaged or split heat pumps serve whole-building loads. Philippines commercial real estate developers specify these for premium office and retail developments.
- Portable Units:Mobile self-contained units with exhaust hose deployment target temporary cooling needs. European F-Gas quota constraints accelerate replacement demand in this retrofit-friendly category.
The dominant share belongs to Split Systems, while Central Air is closing the gap fastest.
End User:
Customer archetypes diverge sharply in procurement sophistication, from price-sensitive residential buyers to lifecycle-cost-focused industrial facilities managers.
- Residential:Individual households and multi-family housing operators purchase equipment through retail and contractor channels. India's BEE star-labeling program redirects demand toward inverter-equipped models rated four stars and above.
- Commercial:Office, retail, and institutional building operators prioritize energy audit compliance and predictive maintenance integration. This segment shows steepest expansion trajectory for building automation platform contracts.
- Industrial:Manufacturing and process facilities require precision temperature and humidity control for equipment protection and quality assurance. Vietnam's foreign electronics assembly plants generate concentrated demand for cleanroom-grade cooling infrastructure.
- Hospitality:Hotels and resorts balance guest comfort expectations with operational cost visibility. Seasonal occupancy patterns favor equipment with rapid startup efficiency and modular capacity scaling.
Commercial installations command premium pricing, though Industrial procurement volumes are scaling most aggressively.
Technology:
Control architectures and refrigerant chemistries define competitive positioning as efficiency mandates eliminate legacy alternatives.
- Inverter:Variable-speed compressor drives modulate cooling output to match thermal loads rather than cycling on-off. India's Bureau of Energy Efficiency tightens minimum energy performance standards annually, collapsing the cost-performance gap with non-inverter alternatives.
- Non-Inverter:Fixed-speed compressors cycle at full capacity until setpoint is reached, then shut down. Regulatory disqualification from interstate commerce under US DOE SEER standards and India's star-labeling program confines this technology to export markets with weaker enforcement.
- Smart Controls:IoT-enabled thermostats and zone management systems integrate with building automation platforms. Predictive maintenance contracts embed these sensors to sell uptime guarantees rather than replacement parts.
- Eco-Friendly Systems:Equipment designed for hydrofluoroolefin blends or natural refrigerants with lower global warming potential. Europe's F-Gas Regulation mandates stepped reductions in hydrofluorocarbon availability through 2030.
Inverter platforms absorb the majority of new investment, while Eco-Friendly Systems face the most compressed compliance timelines.
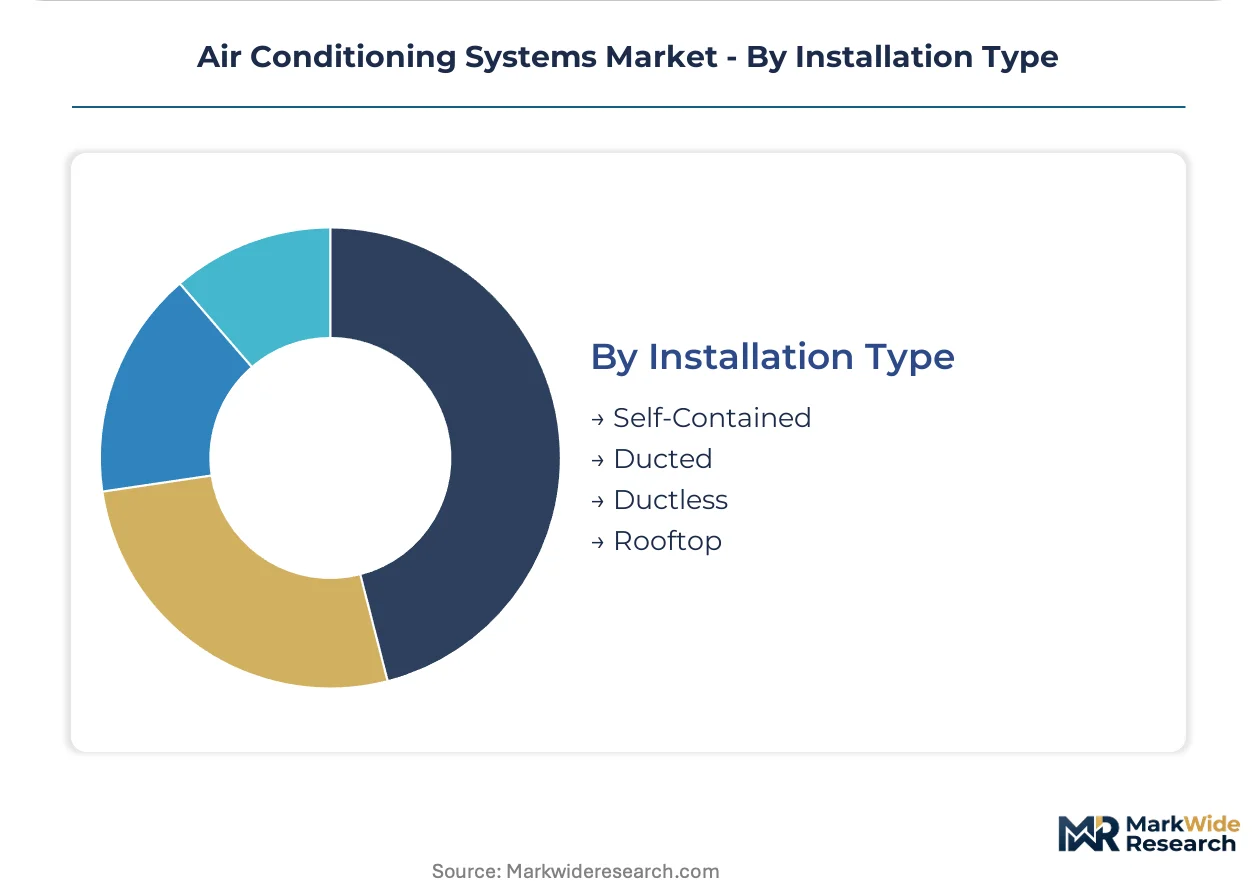
Installation Type:
Physical integration methods determine project economics and retrofit feasibility across building vintages.
- Self-Contained:Factory-sealed refrigerant circuits require no field charging or brazing. Window and portable units dominate this category for minimal-skill deployment.
- Ducted:Central air handlers distribute conditioned air through building-wide duct networks. New commercial construction in Southeast Asia specifies these for integrated building automation.
- Ductless:Multi-zone mini-split and variable refrigerant flow systems eliminate ductwork losses. India's residential retrofit market favors this format for aging building stock.
- Rooftop:Packaged units combining compressor, condenser, and air handler in weatherized enclosures. US commercial replacement cycles accelerate as EPA Section 608 refrigerant phase-down progresses.
Ductless configurations lead residential retrofit volumes, while Rooftop units face the most accelerated replacement pressure from refrigerant chemistry transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys air conditioning systems primarily for residential comfort cooling, while Vietnam channels demand toward precision industrial climate control for electronics manufacturing. This consumption-mix differential shapes regulatory priorities and technology procurement patterns across major markets.
United States
Commercial building stock replacement cycles drive steady equipment turnover, particularly in Sun Belt metros. The EPA enforces hydrofluorocarbon phase-down schedules under Section 608 of the Clean Air Act. Dallas-Fort Worth and Phoenix concentrate rooftop unit demand as commercial real estate operators modernize aging HVAC infrastructure.
India
Tier-2 residential markets and commercial office construction generate split system volumes. The Bureau of Energy Efficiency operates a mandatory star-labeling program that redirects demand toward inverter-equipped models rated four stars and above. Ahmedabad and Surat industrial zones anchor manufacturing capacity expansion for domestic and export markets.
Vietnam
Foreign electronics assembly plants require cleanroom-grade precision cooling infrastructure. The country's national energy efficiency regulator implements building code standards for industrial facilities. Ho Chi Minh City and Bac Ninh province concentrate demand as Samsung and Intel expand semiconductor and display manufacturing operations.
Germany
Commercial building retrofits and industrial process cooling sustain equipment demand despite moderate climate. The F-Gas Regulation mandates stepped reductions in hydrofluorocarbon availability through 2030. The Rhine-Ruhr industrial corridor faces accelerated chiller replacement cycles as refrigerant quota scarcity drives equipment turnover.
Philippines
Commercial real estate developers expand climate-controlled floor space faster than any buyer segment in Southeast Asia. The national energy efficiency authority promotes green building certification for premium developments. Metro Manila and Cebu City anchor premium office and retail construction pipelines specifying central air configurations.
Air Conditioning Systems Market Key Industry Players
Capability concentration sits with inverter compressor specialists and refrigerant chemistry innovators; scale advantage sits with diversified electromechanical conglomerates with captive distribution networks. The market structures around three tiers: integrated HVAC-platform providers, component-specialist suppliers, and regional assembly operators. Dominant competitive moves include backward integration into low-global-warming-potential refrigerant supply and building automation platform acquisition.
Within the integrated-platform tier, Daikin Industries and Carrier Global exemplify archetypes combining hardware manufacturing with lifecycle service infrastructure. Trane Technologies occupies a position emphasizing building automation convergence over standalone equipment sales. These three anchors illustrate how competitive positioning increasingly depends on recurring revenue streams from installed base management rather than transactional equipment margins.
| Leading Market Players |
|---|
| Johnson Controls |
| Lennox International |
| Daikin Industries |
| Samsung Electronics |
| LG Electronics |
| Carrier Global |
| Mitsubishi Electric |
| Gree Electric Appliances |
| Trane Technologies |
| Others |
Cost & Logistics Intelligence
The Shanghai-Singapore maritime corridor carries copper concentrate and aluminum ingot shipments that compress margin visibility for compressor housing manufacturers, while its freight rate volatility feeds directly into three-tier pricing stratification across premium inverter systems, standard ducted configurations, and economy non-inverter exports.
Pricing Analysis
Long-term offtake contracts dominate commercial project procurement, locking in volume commitments from Philippines developers and Vietnam electronics plant operators twelve to eighteen months ahead of installation. Price differentiation hinges on BEE star-rating certification tiers and bundled predictive maintenance service levels. Cost compression in economy non-inverter tiers intensifies because India's tightening SEER mandates strand legacy inventory. Residential retrofit buyers in India's tier-2 cities exhibit highest price sensitivity, while industrial facilities managers prioritize lifecycle cost compliance over first-cost minimization.
Supply Chain Analysis
Upstream feedstock flows for refrigerant chemistry and compressor motor laminates concentrate in China, Japan, and South Korea, with hydrofluoroolefin blend precursors and rare-earth magnet materials drawing from concentrated chemical processing clusters. Copper tube and aluminum fin stock for heat exchangers hinge on Chilean concentrate and Indonesian smelter output. Single-source vulnerability around Japanese variable-speed motor control IP creates bottleneck risk for inverter system assembly. Distribution runs through captive OEM service networks and authorized dealer channels, with Daikin Industries and Carrier Global maintaining direct control over technician certification pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air conditioning hardware is transitioning toward platform-economics logic as building automation convergence and refrigerant lifecycle management create recurring revenue infrastructure. Interoperability between HVAC sensors and IoT-enabled energy management platforms is collapsing the distinction between equipment vendor and facilities service provider.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance sensors in compressor and heat exchanger assemblies before emerging IoT-native entrants capture building automation integration contracts. Backward integration into low-global-warming-potential refrigerant supply secures margin protection against EPA Section 608 quota scarcity and Europe's F-Gas Regulation tightening.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 residential retrofit market where BEE star-labeling enforcement creates technology turnover demand but incumbent service networks remain underdeveloped. Target ductless multi-zone installations for aging building stock with simplified self-contained refrigerant circuits requiring minimal field certification. Partner with regional electrical contractors for installation capacity rather than competing for scarce EPA Section 608 certified technicians.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electromechanical conglomerates with underutilized inverter compressor manufacturing capacity and dormant refrigerant recycling infrastructure. Long-term viability across the analysis window rests on installed base service revenue ratios exceeding transactional equipment margins. Monitor India's Bureau of Energy Efficiency star-rating revision cadence as the inflection signal for technology turnover velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-GWP Refrigerant Supply | Captive hydrofluoroolefin sourcing protects Carrier Global against Europe's F-Gas quota scarcity. |
| Building Automation Platform Acquisition | Trane Technologies extends hardware contracts into recurring performance-based service revenue streams. |
| Predictive Maintenance Sensor Deployment | Embedded compressor monitoring converts Daikin Industries' installed base into subscription uptime guarantees. |
| Technician Certification Pipeline Control | Direct EPA Section 608 training programs lock in service channel exclusivity for incumbent OEMs. |
| India Tier-2 Distribution Partnership | Regional electrical contractor alliances bypass scarce certified technician bottlenecks for new entrants. |
Research Approach
Desk research of customs trade databases, Bureau of Energy Efficiency star-rating registration records, and EPA Section 608 certification filings preceded structured interviews with commercial facilities managers, HVAC contractor operations heads, refrigerant supply procurement leads, and building automation integration engineers. Primary fieldwork across India's tier-2 cities, Vietnam's Bac Ninh industrial corridor, and the Philippines' Metro Manila commercial development zone validated equipment shipment volumes and project pipeline timelines. Secondary triangulation incorporated SEC 10-K equipment revenue disclosures, compressor import manifests, and green building certification databases. Bottom-up unit economics and top-down market sizing converged through cross-referencing manufacturer production capacity announcements with national energy efficiency program targets.
Assumptions around India's SEER mandate enforcement intensity, Europe's F-Gas Regulation quota allocation mechanics, and Vietnam's electronics foreign direct investment continuity were held fixed across the projection horizon, while copper and aluminum commodity price bands were stress-tested at high-low scenarios. Segmentation modeling spanned product format, end-user archetype, control technology, and installation type, with additional granularity on refrigerant chemistry transition timelines. CAGRs were derived from fitted growth curves anchored to regulatory compliance deadlines and replacement cycle dynamics. Forecast inputs included cleanroom-grade cooling capacity requirements from Samsung and Intel expansion disclosures, and BEE star-labeling adoption curves from historical tier-migration patterns.
Macroeconomic conditions sit as an overlay; deviation in Indian residential construction credit availability, Vietnamese dong exchange rate stability, or Philippines commercial real estate capitalization rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and refrigerant chemistry substitution pace. Cross-checking against national energy efficiency program budget appropriations and major electronics manufacturer capex guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Warm Air Furnaces Market