
 Italy HVAC Market | 2026-2036
Italy HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Italy HVAC Market Insights
Refrigerant transition from R-410A to lower-GWP alternatives is fragmenting equipment compatibility across Italy's installed base. Daikin Industries leverages its VRF portfolio to capture premium commercial retrofits in Milan's office districts. Carrier Corporation anchors its position through extensive service networks covering northern Italy's manufacturing belt. Clivet SpA specializes in water-source heat pumps for the Alpine hospitality sector, differentiating through regional climate adaptation.
Heating, ventilation, and air conditioning encompasses mechanical systems regulating indoor temperature, humidity, and air quality through vapor-compression refrigeration cycles, ductwork distribution, and building automation controls operating at COP ratings from 3.0 to 5.5 for heat pumps. Heat pumps command the fastest expansion within product type segments as gas boiler replacements accelerate under decarbonization mandates. Variable Refrigerant Flow technology leads technology segments for commercial flexibility, while centralized systems dominate new construction in institutional end users where lifecycle cost optimization outweighs first-cost premiums.
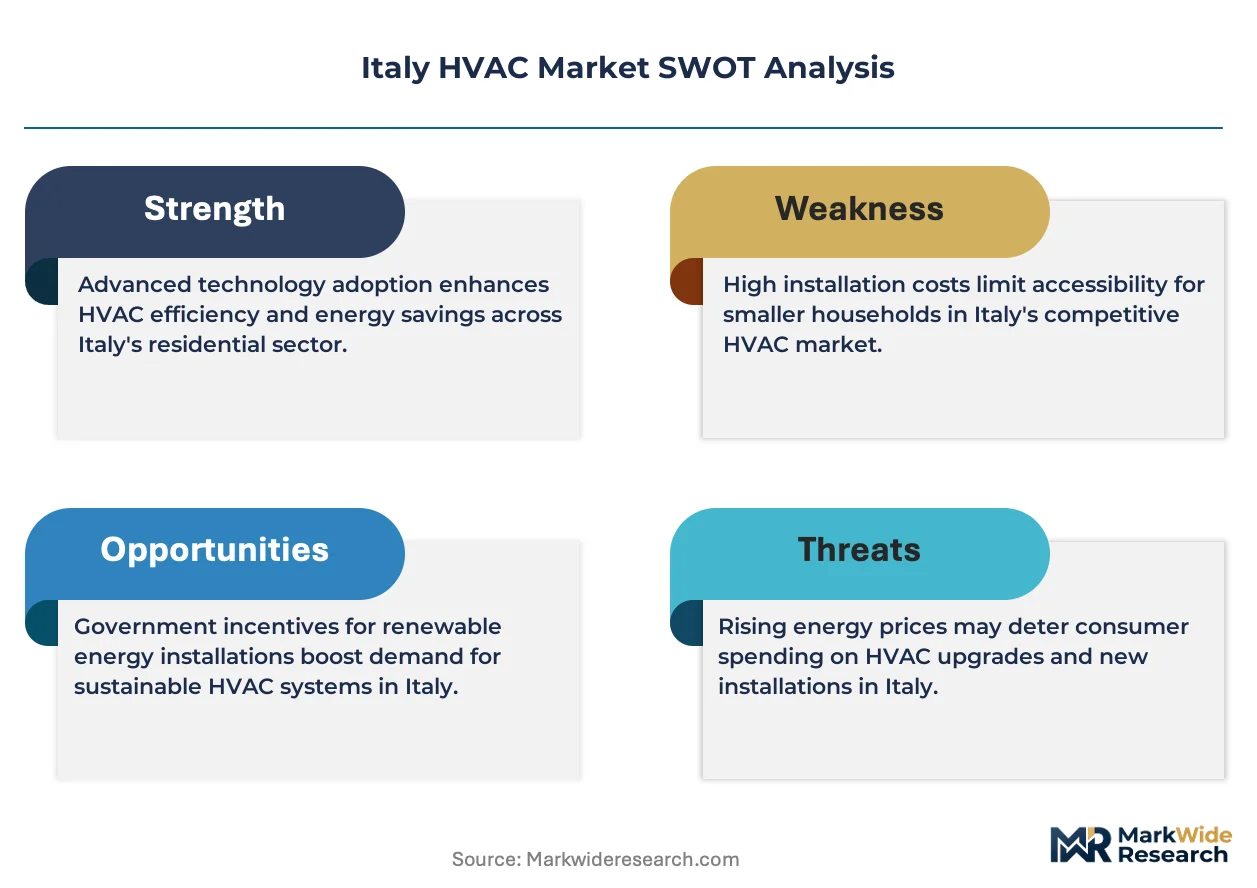
Italy's Ministry of Economic Development enforces EU F-Gas Regulation phase-down schedules, compelling manufacturers to redesign equipment lines for refrigerants below 750 GWP. The Superbonus 110% tax incentive, administered through Agenzia delle Entrate, structures residential demand toward high-efficiency heat pump installations with stringent ENEA energy performance verification. Stakeholders must monitor how the EU Green Deal's building renovation wave recalibrates subsidy thresholds and which refrigerant platforms achieve scale before stranded asset risk materializes in the installed base.
Market Dynamics
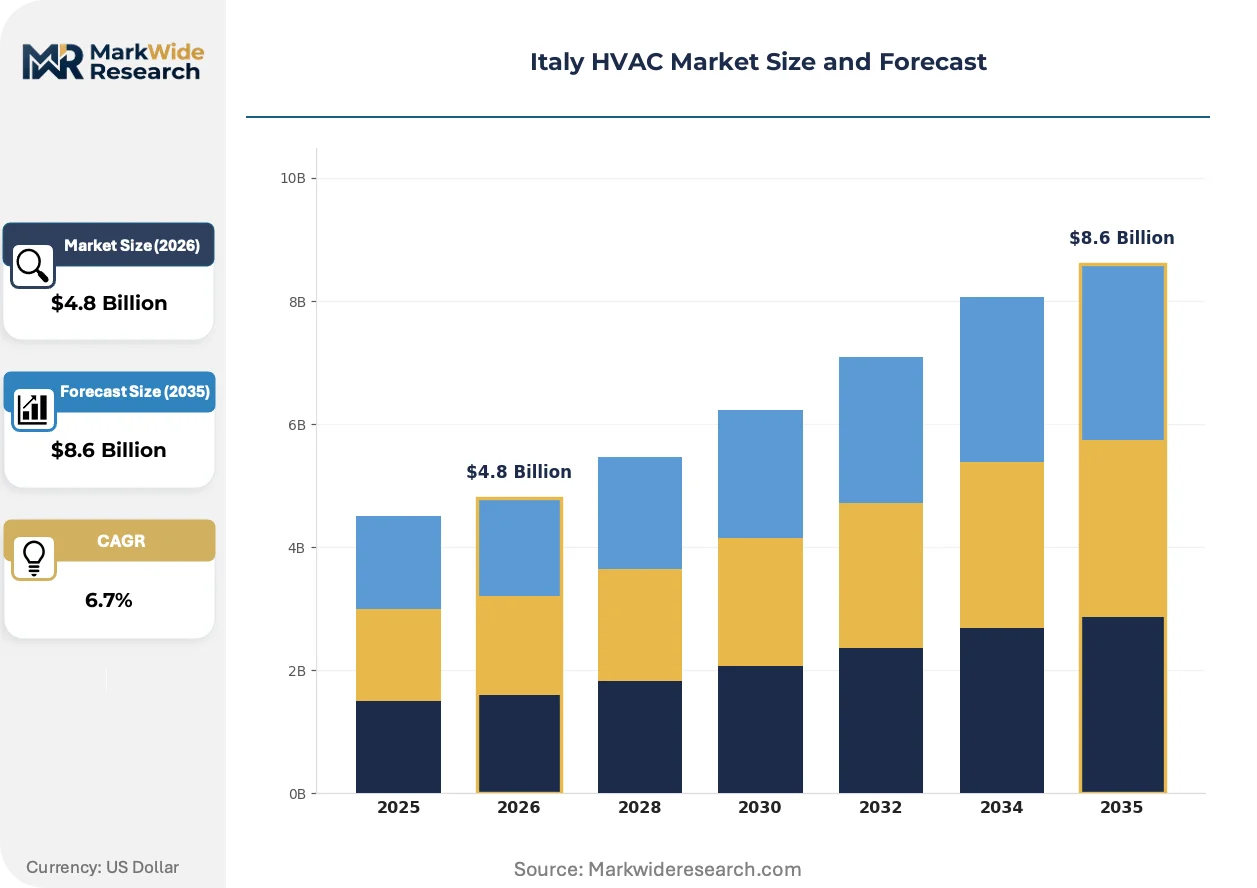
Italy's HVAC sector is experiencing a forced equipment turnover as the EU F-Gas Regulation compels refrigerant transitions that obsolete existing installed bases while Superbonus 110% subsidies accelerate residential heat pump adoption.
Growth Catalysts
- Superbonus 110% Incentive:Italy's tax credit scheme administered through Agenzia delle Entrate covers residential heat pump installations with ENEA verification, channeling homeowner investment toward high-efficiency replacements.
- Gas Boiler Phase-Out Mandates:National decarbonization targets under the EU Green Deal's building renovation wave are structurally redirecting heating demand from fossil combustion to electric heat pump systems.
- Alpine Hospitality Modernization:Ski resort operators across Trentino-Alto Adige and Valle d'Aosta are retrofitting lodging stock with water-source heat pumps to meet sustainability certification requirements from tour operators.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger and coil manufacturing faces input cost pressure from base metal commodity swings, compressing OEM margins on standardized equipment lines.
- Refrigerant Supply Concentration:Lower-GWP alternative production clusters in German and Belgian chemical corridors, creating import dependency for Italian equipment assemblers during transition phases.
- Grid Capacity Limitations:Rural distribution networks in southern regions constrain simultaneous electric heating and cooling adoption, capping addressable market penetration in Calabria and Sicily.
Strategic Opportunities
- VRF System Penetration in Milan Office Stock:Commercial landlords in Lombardy's financial district are prioritizing zoned climate control for ESG compliance, opening premium retrofit volumes.
- Building Automation Convergence:Integration of heat pump operations with BMS platforms and demand-response signaling creates service revenue streams for controls-fluent installers.
- Certified Installer Network Expansion:F-Gas certification requirements under ECHA implementation are winnowing the contractor base, rewarding scaled training investments by distributors.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:The compressed timeline for R-410A phase-down is outpacing technician retraining capacity, delaying installation throughput during peak seasons.
- Legacy Hydronic System Integration:Residential retrofits require hydraulic reconfiguration to accommodate heat pump operating temperatures, extending project timelines and contractor scheduling complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy HVAC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Heat Pumps, Air Conditioners, Ventilation Systems End User: Commercial, Residential, Industrial, Institutional Technology: Variable Refrigerant Flow, Split Systems, Centralized Systems, Hybrid Systems Installation: New Construction, Retrofit, Upgradation, Maintenance |
| Companies Covered | Daikin Industries, Ltd., Carrier Corporation, Johnson Controls International PLC, Robert Bosch GmbH, Midea Group Co., Ltd., Mitsubishi Electric Europe BV, Vaillant Group, BDR Thermea Group, Clivet SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy HVAC Market Trends and Innovations
Equipment refrigerant platforms are fragmenting as manufacturers place diverging bets on R-32, R-454B, and CO2 architectures, while digital service models reconfigure how building operators procure climate systems.
R-32 refrigerant is collapsing the installed base compatibility window for residential split systems. Italian OEMs are retooling production lines around this lower-GWP platform ahead of regulatory deadlines. Homeowners in the Po Valley are encountering equipment replacement scenarios where outdoor and indoor units from different vintages cannot pair, forcing full-system upgrades rather than component swaps.
The EU F-Gas Regulation phase-down schedule is compressing equipment design cycles. Manufacturers must certify new chiller and heat pump lines every three to four years rather than decade-long platforms. Northern Italy's commercial sector bears the highest compliance burden, as Milan and Turin building managers face stranded asset risk in centrally-plant equipment purchased during the R-410A era.
Service contracting is unbundling from equipment sales as energy-as-a-service models penetrate institutional buyers. Hospital and university procurement teams in Emilia-Romagna are shifting from capital purchase to performance-based agreements where HVAC contractors retain ownership and guarantee thermal output. This transfers operational risk to installers while locking in long-term maintenance relationships.
Italy HVAC Market Segmentation
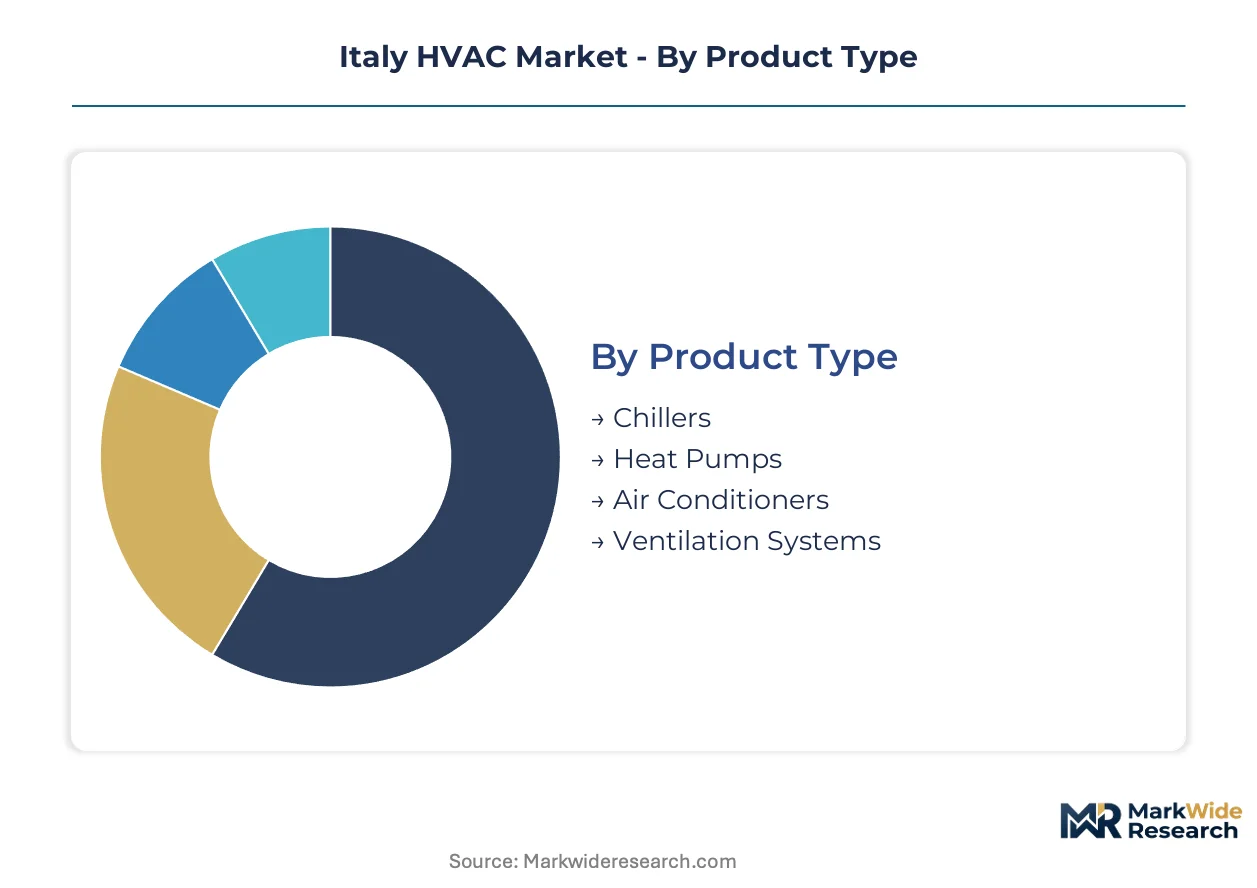
Italy's HVAC market fragments across equipment categories, building applications, and installation contexts that each carry distinct regulatory exposure and margin profiles. Understanding these boundaries clarifies where Superbonus incentives apply, where refrigerant transitions bite hardest, and where service revenue pools concentrate.
Product Type:
Equipment cost tier determines subsidy eligibility and replacement cycle intensity across Italian building stock.
- Heat Pumps:Electric vapor-compression systems extracting thermal energy from air, water, or ground sources deliver COP ratings between 3.0 and 5.5. Demand clusters in northern residential corridors where gas boiler replacements accelerate under Agenzia delle Entrate verification protocols. The steepest expansion runs through air-source configurations eligible for full Superbonus coverage.
- Air Conditioners:Split and multi-split cooling equipment dominates southern Italian adoption patterns, with capacity ratings scaling from 2.5 kW residential units to 20 kW light commercial systems. Calabria and Sicily installation volumes face grid capacity constraints that cap simultaneous heating and cooling penetration.
- Chillers:Centrifugal and screw-compression water chillers serve large commercial and institutional cooling loads above 300 kW.
- Ventilation Systems:Heat recovery ventilators and air handling units address indoor air quality mandates in tightened building envelopes.
Heat pumps command the established base. The steepest expansion runs through ventilation systems tied to building energy certification upgrades.
End User:
Customer type dictates procurement sophistication, financing access, and sensitivity to operating cost versus first-cost tradeoffs.
- Commercial:Office landlords, retail operators, and hospitality groups across Lombardy and Piedmont prioritize zoned climate control and ESG compliance documentation. Milan financial district retrofits are driving VRF penetration as lease competitiveness increasingly requires green building certification.
- Residential:Single-family and multi-family homeowners access Superbonus 110% tax credits through ENEA-verified heat pump installations, with northern regions showing highest retrofit propensity due to colder heating degree-days.
- Industrial:Manufacturing facilities in Turin's automotive supplier belt and Bologna's packaging machinery corridor require process cooling and precision environmental control.
- Institutional:Hospitals, universities, and government buildings in Emilia-Romagna are shifting toward energy-as-a-service procurement models where contractors retain equipment ownership.
Commercial applications anchor current revenue. Residential retrofits are climbing fastest as subsidy uptake normalizes across income tiers.
Technology:
System architecture determines refrigerant charge volumes, installation labor intensity, and compatibility with legacy building infrastructure.
- Variable Refrigerant Flow:Multi-zone heat pump systems modulating refrigerant flow to match individual space loads enable simultaneous heating and cooling across building zones. Premium commercial retrofits in Milan's Class A office stock favor VRF for its retrofit flexibility and metering precision.
- Split Systems:Single-zone residential air conditioners and heat pumps face R-32 transition compatibility constraints that force full-system replacements rather than component swaps.
- Centralized Systems:Chiller-and-boiler plants with air handling distribution dominate new institutional construction where lifecycle cost optimization outweighs first-cost premiums.
- Hybrid Systems:Gas-electric dual-fuel configurations bridge heating transitions in regions with uncertain grid capacity or volatile electricity pricing.
Split systems retain volume leadership. VRF technology is gaining share fastest in commercial retrofit applications.
Installation:
Project context shapes contractor scheduling, margin structure, and exposure to refrigerant handling certification requirements.
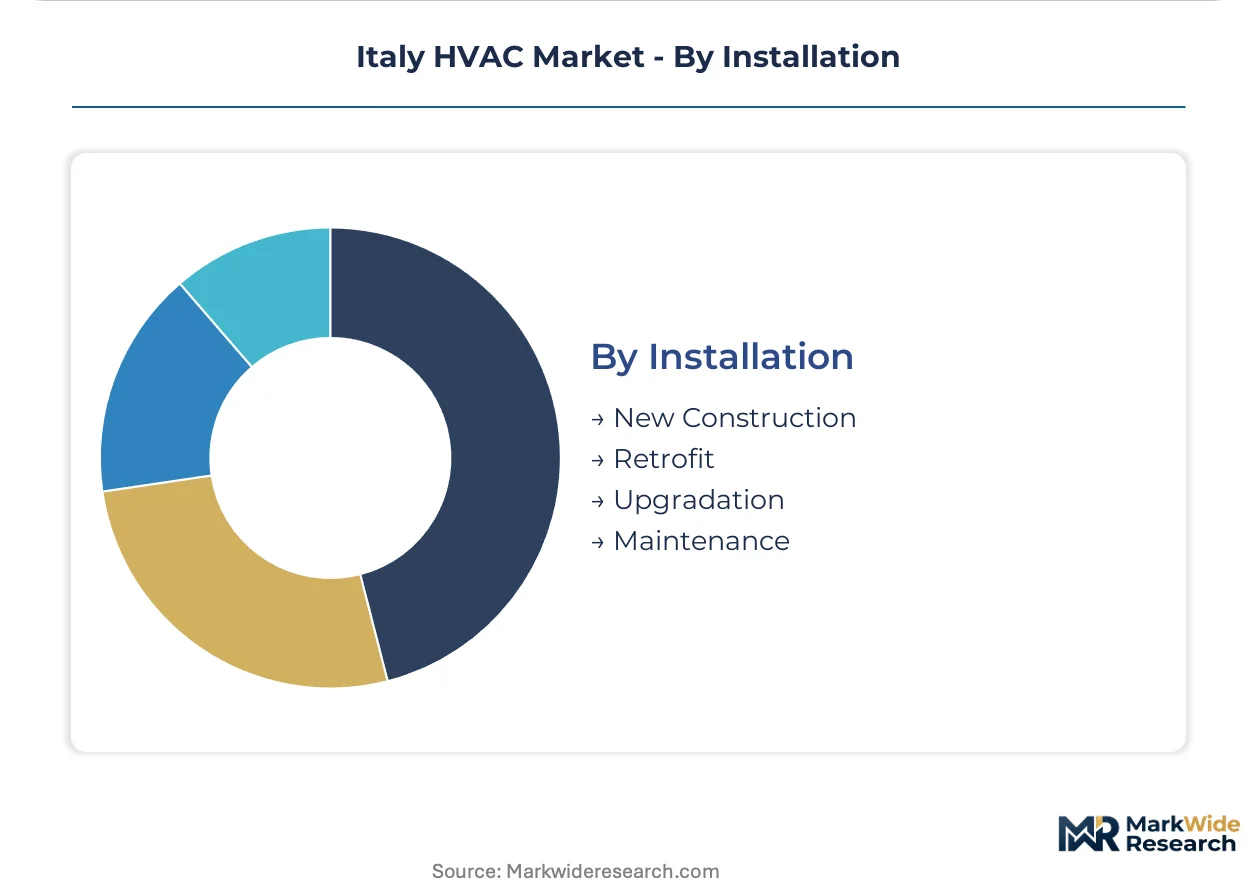
- Retrofit:Existing building equipment replacements dominate Italian HVAC volume, with hydraulic reconfiguration requirements extending project timelines for residential heat pump conversions. F-Gas certification bottlenecks are compressing installation throughput during peak heating and cooling seasons.
- New Construction:Greenfield building projects in northern industrial corridors specify integrated heat pump and ventilation systems from design phase, avoiding the compatibility constraints that plague retrofit work.
- Upgradation:Partial system enhancements addressing efficiency shortfalls or capacity expansion needs.
- Maintenance:Service contracts and reactive repair work generate recurring revenue streams, with F-Gas Regulation compliance driving technician certification investments.
Retrofit activity commands the established base. New construction is expanding most quickly in logistics and data center development clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical corridors supply lower-GWP refrigerants to Italian equipment assemblers, while Alpine tourism operators in Trentino-Alto Adige drive specialized heat pump demand. This trade flow shapes equipment compatibility and service network development across the peninsula.
Lombardy
Milan's Class A office stock drives premium VRF retrofits as landlords pursue ESG compliance for lease competitiveness. The EU F-Gas Regulation phase-down compresses equipment design cycles for commercial building managers. Daikin Industries leverages its VRF portfolio to capture retrofit volumes in the financial district.
Piedmont
Turin's automotive supplier belt requires precision environmental control for manufacturing processes. Italy's Ministry of Economic Development enforces refrigerant transitions that obsolete existing installed bases. Carrier Corporation anchors its position through extensive service networks covering the manufacturing corridor.
Veneto
Ski resort operators across the Alpine provinces retrofit lodging stock with water-source heat pumps for sustainability certification. The Superbonus 110% tax incentive structures residential demand toward high-efficiency replacements. Clivet SpA specializes in water-source systems for the hospitality sector, differentiating through regional climate adaptation.
Emilia-Romagna
Hospital and university procurement teams shift from capital purchase to performance-based agreements where contractors retain equipment ownership. ENEA energy performance verification requirements channel investment toward verified high-efficiency installations. This institutional cluster generates recurring service revenue streams for controls-fluent installers.
Lazio
Rome's public building renovation wave concentrates institutional demand for centralized chiller-and-boiler plants. Grid capacity limitations in surrounding rural areas constrain electric heating adoption, capping addressable market penetration. The capital region's procurement patterns influence national subsidy threshold calibration.
Italy HVAC Market Competitive Landscape
On the supply side, the industry is consolidating around diversified industrial conglomerates with captive distribution networks, while regional specialists defend positions in climate-specific applications. Three archetypes dominate: Japanese-Korean electronics houses with VRF platforms, European heating specialists with hydronic expertise, and Chinese scale players with cost-optimized residential equipment. Competitive moves concentrate on refrigerant platform certification races and installer network certification investments.
Within the diversified industrial tier, Daikin Industries, Ltd. and Carrier Corporation occupy anchor positions exemplifying platform breadth, while Clivet SpA represents the regional specialist archetype with Alpine climate adaptation capabilities. These three entities illustrate the competitive tension between global scale and local climate optimization that defines procurement decisions across Italian building stock.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Carrier Corporation |
| Johnson Controls International PLC |
| Robert Bosch GmbH |
| Midea Group Co., Ltd. |
| Mitsubishi Electric Europe BV |
| Vaillant Group |
| BDR Thermea Group |
| Clivet SpA |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum price volatility in commodity markets compresses OEM margins while simultaneously widening the spread between economy and premium equipment tiers, forcing manufacturers to redraw supplier relationships around metal hedging strategies and regional fabrication partnerships.
Pricing Analysis
R-410A-to-R-32 equipment generation gaps drive the dominant pricing architecture, with next-generation heat pumps commanding premium positioning over stranded prior-generation inventory. Three-tier pricing structure across premium, standard, and economy levels separates ENEA-verified Superbonus-eligible systems from uncertified alternatives. Cost compression in mid-tier residential splits is intensifying because German and Belgian refrigerant import dependencies inflate landed costs for Italian assemblers. Residential retrofit contractors exhibit highest price sensitivity, while Alpine hospitality operators prioritize climate-specific performance over first-cost optimization.
Supply Chain Analysis
Tariff exposure between Germany and Italy dominates supply chain risk calculations for lower-GWP refrigerant procurement. Component sourcing draws from German chemical corridors for refrigerants, Chinese manufacturing zones for compressor assemblies, and domestic Italian metal fabrication for heat exchanger coils. Single-source vulnerability concentrates in specialty refrigerant supply during EU F-Gas Regulation transition phases. Distribution runs through captive dealer networks controlled by diversified industrial conglomerates alongside independent HVAC contractors pursuing F-Gas certification upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant platform fragmentation creates defendable niches for specialists mastering specific climate applications or certification tiers, as Superbonus incentive complexity rewards localized installation expertise over pure equipment scale.
For Market Incumbents: Insulate service revenue streams by deepening captive installer certification programs ahead of ECHA-mandated F-Gas qualification bottlenecks. Lock in backward integration into heat exchanger metal supply through long-term offtake agreements with Lombardy and Piedmont fabrication facilities. Counter Chinese cost-optimized residential entrants by bundling ENEA verification services with equipment sales. For New Entrants and Emerging Players: Southern Italy grid capacity constraints present the most penetrable white-space for hybrid gas-electric systems bridging infrastructure limitations. Target Calabria and Sicily commercial retrofits with split-system offerings that circumvent simultaneous heating-cooling electrical load issues. Enter through distributor partnerships with existing F-Gas-certified contractors rather than greenfield network builds. For Investors and Strategic Acquirers: The market sits at a forced-equipment-turnover phase that favors controls-fluent service platforms over pure manufacturing scale. Long-term viability hinges on recurring revenue attachment rates rather than transactional equipment volumes. Monitor Agenzia delle Entrate Superbonus threshold adjustments as the primary inflection signal for residential demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Certification Race | Early R-32 and R-454B line approvals secure Superbonus eligibility ahead of regulatory deadlines. |
| F-Gas Certification Network Investment | Scaled technician training programs capture installation throughput during compressed R-410A phase-down timelines. |
| Alpine Climate System Specialization | Water-source heat pump expertise for Trentino-Alto Adige hospitality differentiates against standardized competitors. |
| Building Automation Integration | BMS convergence capabilities unlock energy-as-a-service contracts with Emilia-Romagna institutional buyers. |
| Metal Supply Backward Integration | Captive copper and aluminum sourcing hedges commodity volatility compressing standardized equipment margins. |
Research Methodology
A standing panel of HVAC contractor operations managers, ENEA energy auditors, Agenzia delle Entrate tax credit administrators, and commercial building facility directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with distribution channel partners and aftermarket service heads alongside secondary validation through EU F-Gas Regulation implementation reports, ECHA certification database tracking, and Italian customs trade data for refrigerant and compressor imports. Bottom-up equipment shipment analysis triangulated against top-down building stock renovation projections.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling Superbonus policy continuity against subsidy reduction pathways. Segmentation dimensions included product type, end-user category, technology architecture, and installation context alongside regional heating degree-day clustering. CAGRs were derived from equipment replacement cycle analysis and incentive uptake elasticity modeling. Forecast inputs incorporated refrigerant phase-down schedules and grid capacity expansion timelines for southern regions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese scale players or accelerated EU Green Deal building renovation wave funding would shift outcomes. Continuous validation against Agenzia delle Entrate disbursement data and ENEA verification volumes is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Compressor Market