
 Global Portable Air Conditioner Market | 2026-2036
Global Portable Air Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Air Conditioner Market Outlook
Market Dynamics
Multi-source component procurement is repositioning how portable air conditioner manufacturers manage cost volatility and supply assurance. LG Electronics leverages captive compressor production to buffer against refrigerant supply shocks. Midea Group anchors its cost structure through integrated sheet-metal and electronics manufacturing in Guangdong. De'Longhi Appliances S.r.l. competes on design specialization, commanding premium placement in European retail channels.
A portable air conditioner is a self-contained refrigeration appliance with hermetically sealed compressor, condenser, and evaporator assemblies mounted on casters, typically rated between 5,000 and 14,000 BTU per hour and exhausting waste heat through a flexible duct. Its primary commercial purpose is spot cooling in spaces where permanent HVAC installation is structurally impractical or economically unjustified. Single-hose configurations still dominate unit shipments globally due to lower retail price points, though dual-hose designs capture disproportionate margin in commercial and hospitality applications where operating efficiency determines total cost of ownership. Smart connectivity represents the fastest-expanding product dimension, with Wi-Fi-enabled models commanding pricing premiums through energy management integrations.
The US Department of Energy enforces minimum combined energy efficiency ratio standards that disqualify lower-tier imports from American retail channels. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing redesigns toward R290 propane or R32 systems for European market access. China's GB standards and India's Bureau of Energy Efficiency labeling program impose parallel efficiency mandates that shape product development roadmaps. Stakeholders must monitor refrigerant transition timelines and efficiency tier migrations to avoid stranded inventory in channels with tightening compliance windows.
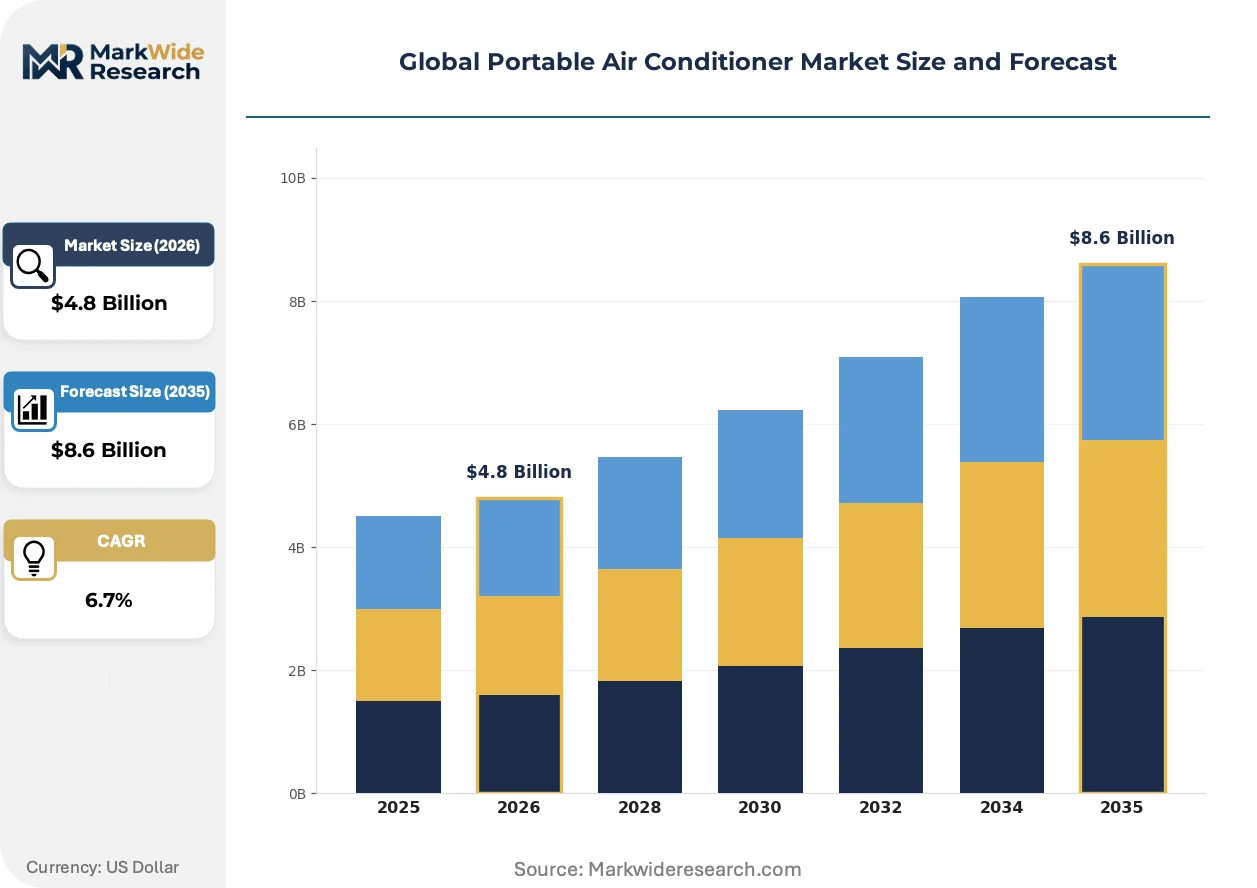
Market Dynamics
The refrigerant transition mandated by the EU F-Gas Regulation and parallel efficiency standards in the US and India is forcing a complete product architecture redesign, compressing development timelines while opening premium positioning for compliant manufacturers.
Growth Catalysts
- Rental housing expansion:Urban migration in India and Southeast Asia generates demand for non-permanent cooling in leasehold properties where structural HVAC modification is prohibited.
- Grid instability patterns:Frequent power fluctuations in emerging markets favor portable units with lower startup current draws compared to fixed split systems.
- Smart home integration:Wi-Fi-enabled energy management protocols allow utilities to modulate cooling loads during peak demand periods, creating regulatory preference in demand-response jurisdictions.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials constitute 35-40% of unit manufacturing cost, exposing margin structures to London Metal Exchange fluctuations.
- Compressor supply concentration:Hermetic rotary compressor production clusters in China and Thailand, creating single-source vulnerability for non-integrated assemblers.
- Single-hose efficiency ceiling:Thermodynamic limitations of negative-pressure cooling constrain BTU-per-watt performance below dual-hose alternatives, locking entry-tier products out of commercial specification channels.
Strategic Opportunities
- Indonesia residential penetration:Archipelago geography and informal housing stock favor mobile cooling over centralized systems in 17,000+ inhabited islands.
- R290 propane transition:EU F-Gas phasedown timeline accelerates hydrocarbon refrigerant adoption, rewarding early movers with first-mover certification advantages.
- Direct-to-installer channels:Bypassing retail markup through HVAC contractor networks captures commercial replacement demand with higher attach rates for dual-hose configurations.
Industry Challenges
- Hydrocarbon refrigerant technician certification:R290 and R32 handling requires specialized training infrastructure that remains underdeveloped outside Western Europe and Japan.
- Cross-border efficiency label harmonization:Divergent test procedures between DOE, EU Ecodesign, and India's BEE create SKU proliferation and inventory segmentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Air Conditioner Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Contained, Dual-Hose, Single-Hose, Smart Application: Residential, Commercial, Industrial, Hospitality Power Rating: 500W, 1000W, 1500W, 2000W Installation: Window, Portable, Ceiling, Wall-Mounted |
| Companies Covered | LG Electronics, Honeywell International Inc., Whirlpool Corporation, Haier Group Corporation, Midea Group, Daikin Industries, Ltd., Panasonic Corporation, Electrolux, De'Longhi Appliances S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Air Conditioner Market Strategic Shifts
Refrigerant chemistry, connectivity architecture, and channel economics are converging to redefine product positioning and margin capture across price tiers.
Variable-speed inverter compressors are integrating into mid-tier portable units, enabling partial-load efficiency gains that single-speed rotary designs cannot match. Commercial buyers in hospitality and healthcare verticals are specifying inverter-equipped models for 24-hour operation cycles despite 40-60% unit cost premiums. This technology is integrating spot-cooling products into building energy management systems previously reserved for permanent HVAC infrastructure.
The EU F-Gas Regulation's 2024-2030 phasedown schedule is compressing hydrofluorocarbon availability for sub-3kg charge systems. European manufacturers are retooling production lines for R290 propane with charge limits below 152g to satisfy IEC safety standards for indoor use. Asian exporters without hydrocarbon-ready factories face channel exclusion from EU retail and commercial specification markets by 2027.
Commercial procurement is consolidating through facilities management aggregators that negotiate enterprise pricing for multi-site cooling refresh cycles. These intermediaries displace traditional distributor relationships by bundling installation, maintenance, and equipment replacement under single-contract arrangements. The model is most advanced in US healthcare and German industrial manufacturing verticals where standardized asset management protocols dominate capital expenditure planning.
Global Portable Air Conditioner Market Segmentation
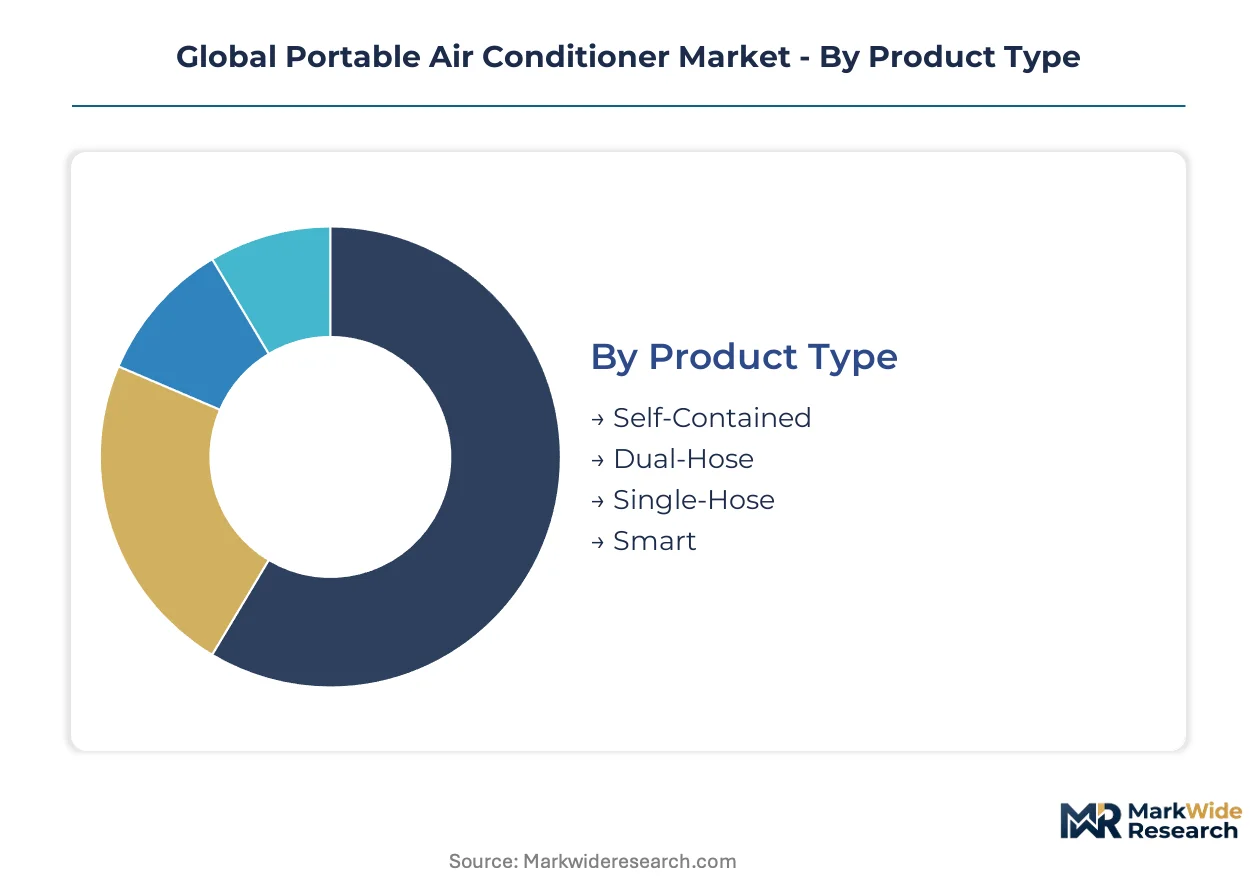
Product architecture and application context determine margin capture and channel strategy in portable air conditioning. Segment boundaries are hardening around refrigerant compliance, connectivity integration, and end-use specification requirements.
Product Type:
Capital intensity escalates with compressor integration complexity and refrigerant system redesign cycles.
- Self-Contained:Hermetically sealed refrigeration circuits with integrated condensate management eliminate external drainage infrastructure. Demand concentrates in US rental housing and Japanese compact dwellings where structural modification is restricted by lease terms or building codes.
- Dual-Hose:Separate intake and exhaust ducts maintain neutral room pressure, delivering 40% higher effective cooling capacity per rated BTU. Commercial buyers in German industrial facilities and US healthcare clinics specify these units for continuous-duty cycles despite 25-35% retail price premiums over single-hose alternatives.
- Single-Hose:Negative-pressure operation draws unconditioned air through building envelopes, capping efficiency at the entry tier.
- Smart:Wi-Fi modules and cloud-connected energy management enable utility demand-response integration.
Self-contained units absorb the bulk of installed capacity; smart connectivity is expanding most quickly.
Application:
Customer procurement authority and replacement cycle frequency vary sharply across end-use contexts.
- Residential:Individual purchase decisions dominate, with Indian urban renters and Southeast Asian leasehold tenants driving volume through e-commerce channels. Grid instability in Lagos, Karachi, and Jakarta favors portable units with inverter compressor soft-start capability over fixed split systems.
- Commercial:Facilities management aggregators and HVAC contractors control specification, bundling equipment with installation and maintenance contracts. US healthcare systems and German manufacturing plants are consolidating procurement through enterprise agreements that displace traditional distributor relationships.
- Industrial:Spot-cooling requirements in machine shops and warehouse loading docks demand 14,000+ BTU output with powder-coated steel cabinets.
- Hospitality:Seasonal occupancy fluctuations and historic building constraints in European city centers create replacement demand for non-permanent cooling.
Residential applications anchor global shipment volume; commercial procurement is climbing the fastest as enterprise buyers consolidate supplier relationships.
Power Rating:
Electrical infrastructure constraints and operating cost sensitivity shape specification across voltage standards and tariff structures.
- 500W:Compact units rated below 6,000 BTU serve European studio apartments and Japanese single-room dwellings where circuit capacity limits peak draw.
- 1000W:Mid-range output dominates Indian and Brazilian residential markets, balancing cooling coverage against generator compatibility where grid reliability is intermittent.
- 1500W:Higher-capacity units address US suburban home offices and Australian rental properties with 120V/240V split-phase availability.
- 2000W:Maximum portable output serves industrial spot-cooling and commercial kitchen applications requiring rapid temperature reduction.
The 1000W tier carries the majority of unit shipments; 1500W ratings are gaining share fastest as remote work expands home office cooling requirements.
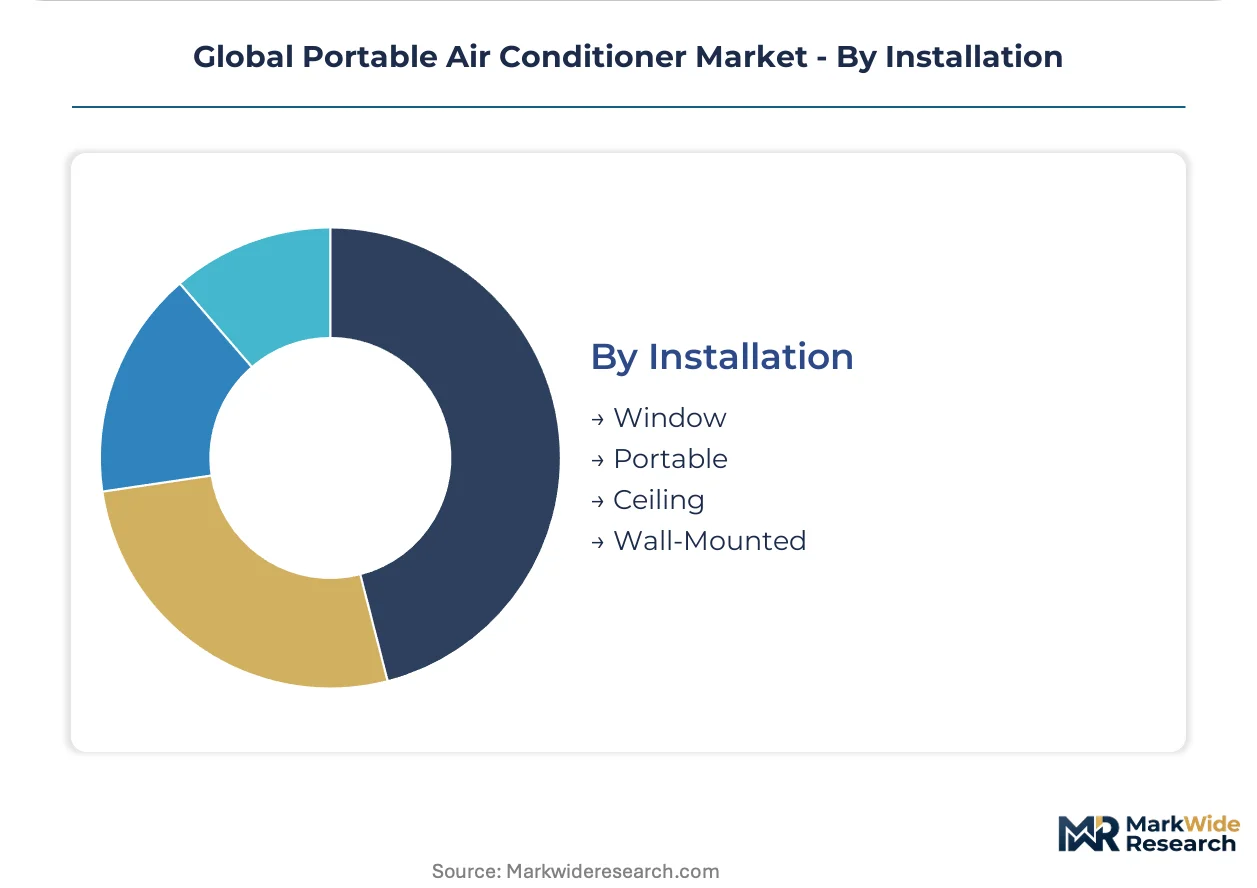
Installation:
Channel economics and customer technical capability determine attachment rates for professional installation services versus self-assembly.
- Window:Bracket-mounted units require sash modification and weather sealing, common in US Northeast and Midwest pre-war housing stock with double-hung windows.
- Portable:Castor-mounted mobility with flexible exhaust ducting captures demand where window geometry or building regulations prohibit fixed installation.
- Ceiling:Suspended cassette configurations serve commercial retrofit applications with limited floor space and suspended tile ceilings.
- Wall-Mounted:Through-wall sleeve installation mimics permanent mini-split aesthetics while preserving unit mobility for seasonal removal.
Portable installation dominates unit economics; ceiling configurations are expanding most quickly in commercial retrofit channels where floor space carries premium lease rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in India, where rental housing expansion and grid instability create structural preference for mobile cooling over fixed installations. Urban migration patterns across emerging markets are reshaping regional shipment volumes and product specifications.
United States
Retrofit demand in aging Northeast and Midwest housing stock drives single-hose unit sales through home improvement retailers. DOE minimum efficiency standards compress margins on entry-tier imports while favoring inverter-equipped models. Dallas-Fort Worth and Phoenix metropolitan clusters see concentrated commercial procurement for hospitality and healthcare spot-cooling.
India
Grid instability in Mumbai, Delhi-NCR, and Bangalore favors portable units with soft-start compressor capability over fixed split systems. Bureau of Energy Efficiency labeling programs tighten efficiency tiers annually, forcing SKU rationalization. Tamil Nadu and Gujarat manufacturing corridors supply domestic demand and export to Southeast Asian markets.
Germany
EU F-Gas Regulation phasedown accelerates R290 propane transition in Stuttgart and Munich industrial zones. Commercial buyers specify dual-hose configurations for continuous-duty cycles in manufacturing facilities. Berlin's historic building stock creates replacement demand where structural HVAC modification is prohibited.
China
GB standards and dual carbon goals compress refrigerant choices toward R32 and hydrocarbon alternatives. Guangdong Province anchors integrated manufacturing from sheet-metal fabrication to electronics assembly. Shanghai and Beijing urban renters drive domestic demand for compact self-contained units in leasehold properties.
Indonesia
Archipelago geography and informal housing across 17,000+ inhabited islands favor mobile cooling over centralized systems. Jakarta and Surabaya see concentrated e-commerce distribution for 1000W-rated units compatible with generator backup. National electrification programs expand addressable market beyond Java's grid reliability.
Global Portable Air Conditioner Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retool for hydrocarbon refrigerant compliance and inverter compressor integration. The vendor base stratifies across three tiers: integrated conglomerates with captive component production, mid-scale specialists focused on design differentiation, and regional assemblers dependent on outsourced compressors. Strategic archetypes include efficiency-led premium positioning, cost-optimized volume manufacturing, and connectivity-first smart home integration. M&A activity and geographic licensing agreements represent the primary competitive moves as companies secure refrigerant certification and local market access.
Within the integrated conglomerate tier, LG Electronics and Midea Group exemplify backward integration strategies that buffer supply volatility through in-house compressor and electronics production. De'Longhi Appliances S.r.l. occupies a design-specialist position, commanding premium placement in European retail channels through aesthetic differentiation. Honeywell International Inc. and Whirlpool Corporation anchor the diversified industrial group archetype, leveraging cross-category brand recognition and existing distribution infrastructure for market entry.
| Leading Market Players |
|---|
| LG Electronics |
| Honeywell International Inc. |
| Whirlpool Corporation |
| Haier Group Corporation |
| Midea Group |
| Daikin Industries, Ltd. |
| Panasonic Corporation |
| Electrolux |
| De'Longhi Appliances S.r.l. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation phasedown timelines gate qualified supply and premium-tier pricing access, compressing hydrofluorocarbon refrigerant availability while rewarding early R290 propane adopters with certification moats that command 25-35% retail premiums over non-compliant imports.
Pricing Analysis
Volume concentrates in single-hose entry-tier units through Indian e-commerce channels and US home improvement retailers, while margin pools in dual-hose inverter-equipped models specified by German industrial facilities and US healthcare systems. Price differentiation rests on refrigerant compliance grade and compressor technology tier, with hydrocarbon-ready factories capturing EU market access denied to legacy HFC assemblers. Cost compression in entry-tier products intensifies as DOE minimum efficiency standards disqualify lower-tier imports from American retail channels. Residential renters in Southeast Asian leasehold properties exhibit highest price sensitivity, while facilities management aggregators in US healthcare verticals prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Workforce availability for hydrocarbon refrigerant technician certification remains concentrated in Western Europe and Japan, constraining R290-ready service infrastructure expansion into emerging markets. Manufacturing gravity centers on China, Thailand, and India, with Guangdong Province anchoring integrated production from sheet-metal fabrication to electronics assembly. Raw material dependencies span copper and aluminum heat exchanger alloys, hermetic rotary compressors, and Wi-Fi connectivity modules. Single-source vulnerability clusters in Chinese and Thai compressor production, exposing non-integrated assemblers to supply disruption. Distribution runs through facilities management aggregators in US healthcare and German industrial verticals, bypassing traditional retail markup for enterprise contract bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable air conditioner market operates as a cost-of-compliance story where EU F-Gas Regulation refrigerant mandates erect barrier-to-entry moats favoring manufacturers with hydrocarbon-ready production lines and certified technician networks.
For Market Incumbents: Deepen backward integration into captive compressor production to buffer against supply concentration in China and Thailand, while accelerating R290 propane certification investments ahead of EU channel exclusion deadlines. Defend margin position by locking enterprise contracts with US healthcare facilities management aggregators before competitor consolidation displaces distributor relationships. For New Entrants and Emerging Players: Capture white-space opportunity in Indonesian archipelago markets where informal housing across 17,000+ islands favors mobile cooling over centralized infrastructure, and grid instability in secondary cities creates generator-compatible demand. Prioritize direct-to-installer channel development in commercial retrofit segments where HVAC contractor networks yield higher dual-hose attach rates than retail distribution. For Investors and Strategic Acquirers: R290 propane certification completion in Asian export factories is the leading indicator that manufacturing assets will retain EU market access through the phasedown timeline. Target acquisition profiles should emphasize mid-scale specialists with hydrocarbon-ready production lines and established technician training partnerships, as these capabilities will concentrate value capture over the medium-term horizon. Watch for EU customs enforcement intensity against non-compliant imports as the signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| R290 Propane Production Retooling | Secures EU market access ahead of F-Gas Regulation channel exclusion deadlines. |
| Inverter Compressor Integration | Captures 24-hour commercial specification demand from US healthcare and German manufacturing. |
| Facilities Management Aggregator Partnership | Bypasses retail markup through enterprise contract bundling in consolidated procurement channels. |
| Direct-to-Installer Channel Development | Targets commercial replacement demand with higher dual-hose configuration attach rates. |
| Smart Connectivity Module Integration | Enables utility demand-response participation and energy management system compatibility. |
Study Parameters
Multi-period observation of refrigerant transition timelines, efficiency standard migrations, and compressor technology adoption anchored the trend analysis, supplemented by interviews with HVAC contractor network managers, facilities management procurement leads, appliance retail category buyers, and compressor manufacturing plant directors. Secondary validation drew from EU F-Gas Regulation implementation notices, US DOE efficiency standard dockets, India's Bureau of Energy Efficiency labeling program updates, and customs trade data for heat exchanger material flows. Bottom-up shipment modeling by product architecture and power rating tier triangulated against top-down market value estimates.
Input-output matrices mapped unit economics across manufacturing cost structures, channel margin stacks, and end-use price sensitivity curves across the projection horizon. Segmentation dimensions modeled include product type, installation configuration, power rating tier, application context, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical penetration patterns in comparable appliance categories. Industry-specific forecast inputs incorporated grid reliability indices for emerging market urban centers and rental housing formation rates in Indian and Southeast Asian metropolitan areas.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant transition timeline acceleration, copper and aluminum price volatility, and compressor supply chain disruption scenarios. Forecasts reflect documented assumptions regarding efficiency standard enforcement intensity and enterprise procurement consolidation velocity. Material deviation in EU customs enforcement patterns or Indian grid reliability investment trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market