
 US Compressed Air Treatment Equipment Market | 2026-2036
US Compressed Air Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Compressed Air Treatment Equipment Market Insights
ISO 8573-1:2010 air purity class certification is reorganizing competitive access in the US compressed air treatment landscape. Donaldson Company leverages its filtration depth to anchor positions in pharmaceutical and food processing accounts. Parker Hannifin competes through hydraulic-pneumatic cross-selling strength across industrial distribution channels.
Compressed air treatment equipment encompasses dryers, filters, separators, and conditioning accessories engineered to remove moisture, particulate, oil aerosols, and microbial contaminants from compressed air streams, typically achieving pressure dew points from -70°C to +10°C depending on technology selection. The equipment serves as critical infrastructure protecting pneumatic tools, process instrumentation, and product-contact applications from contamination-induced failure. Desiccant and refrigerated dryer technologies command the largest installed base, though membrane systems are gaining traction in point-of-use pharmaceutical skids where space constraints dominate. Activated charcoal oil vapor removal stages attach premium pricing in food processing and healthcare facilities where Class 0 purity per ISO 8573-1 represents non-negotiable specification.
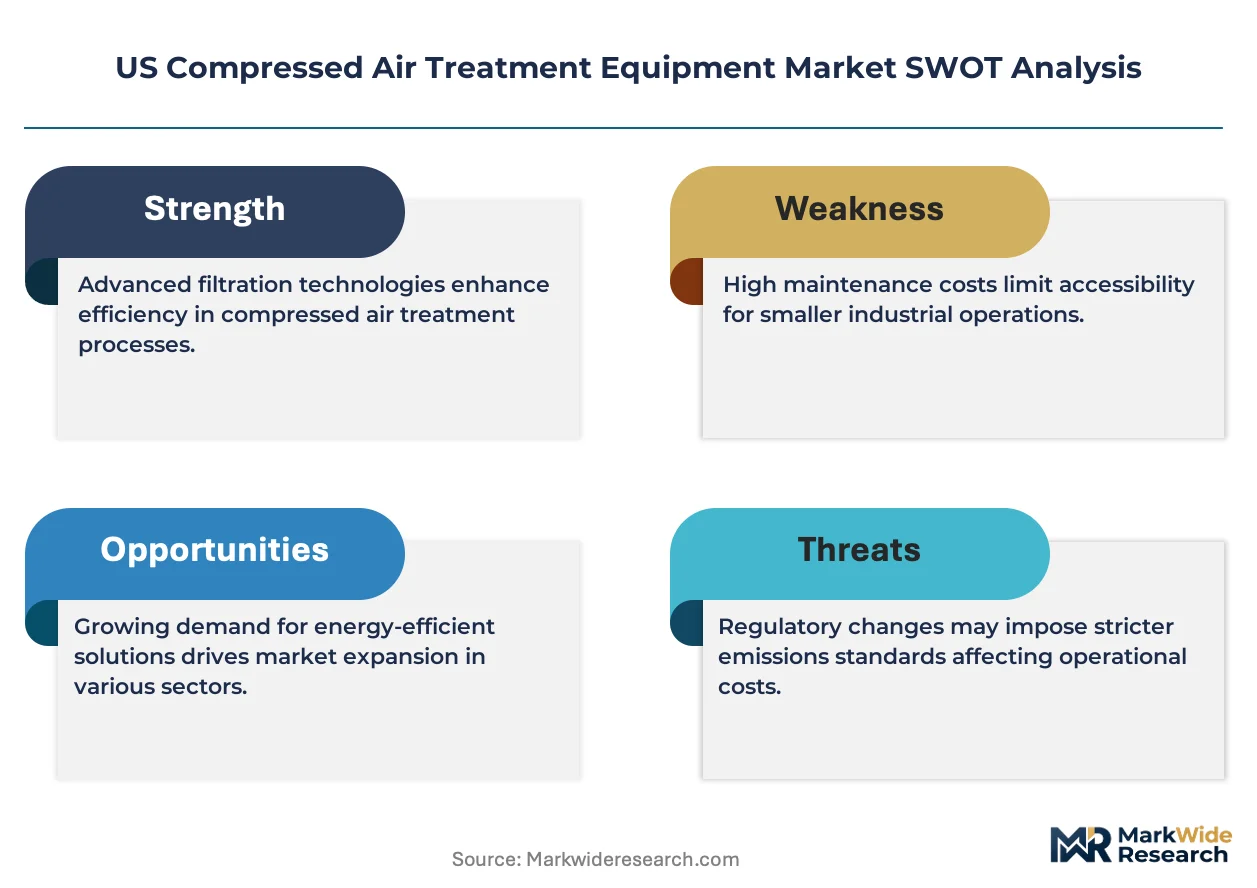
OSHA 29 CFR 1910.134 breathing air requirements, FDA 21 CFR Part 211 cGMP provisions, and EPA Clean Air Act National Emission Standards for Hazardous Air Pollutants collectively dictate filtration efficiency minimums, material compatibility, and documentation protocols across US manufacturing and healthcare installations. State-level environmental variances in California and Texas add compliance layers for equipment deployed in emissions-sensitive zones. Stakeholders must monitor pending EPA reconsideration of oil mist discharge thresholds and evolving FDA guidance on aseptic processing air quality.
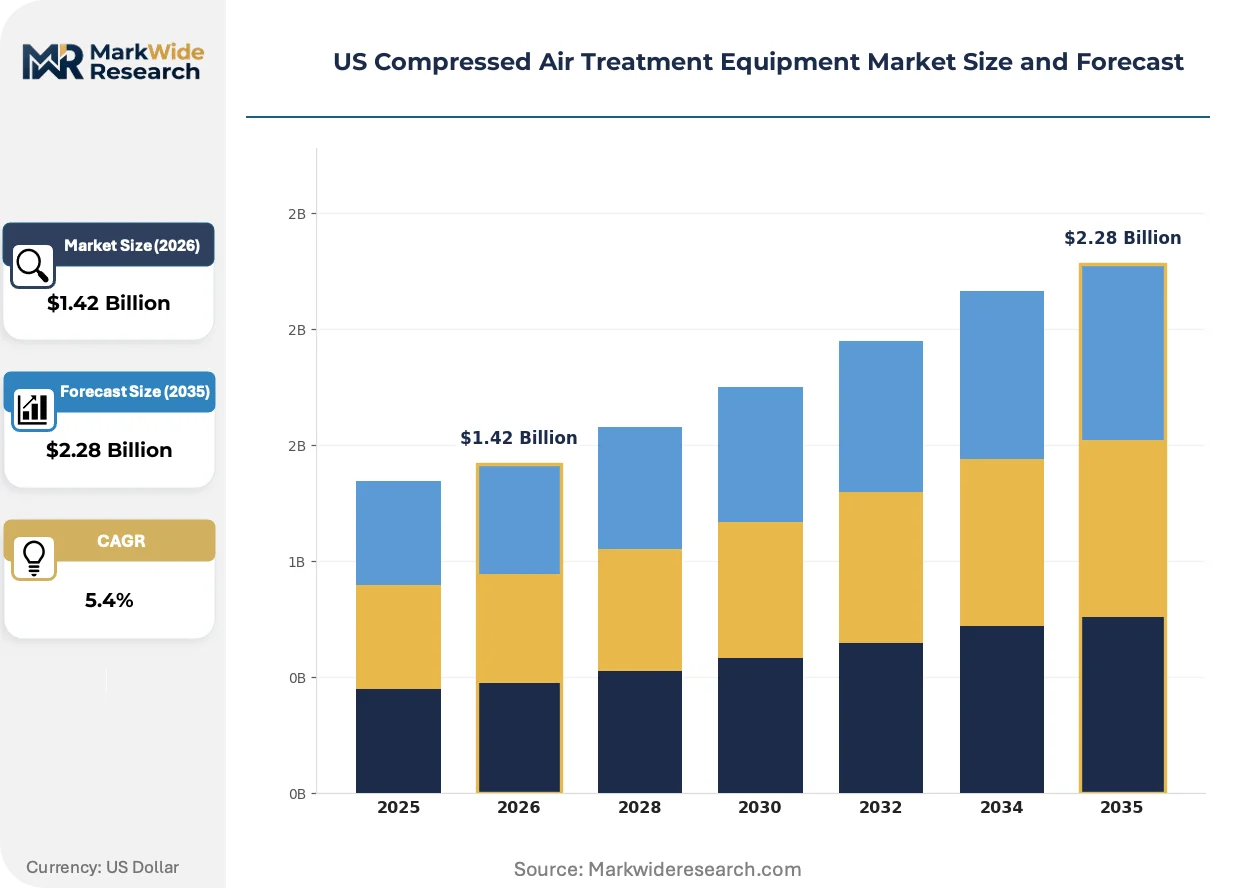
Market Dynamics
OSHA breathing air standards and FDA cGMP tightening are forcing compressed air treatment equipment upgrades across US pharmaceutical corridors, while desiccant dryer technology gains ground in cleanroom infrastructure expansions.
Growth Catalysts
- OSHA 29 CFR 1910.134 Enforcement:Breathing air purity mandates in manufacturing and healthcare facilities are accelerating filtration system replacement cycles.
- Pharmaceutical Cleanroom Expansion:New Jersey and North Carolina manufacturing hubs are installing ISO 8573-1 Class 0 infrastructure for aseptic processing lines.
- Membrane Dryer Miniaturization:Point-of-use pharmaceutical skids in space-constrained facilities are adopting hollow-fiber membrane systems for dew point control.
Market Restraints
- Activated Alumina Supply Concentration:Desiccant dryer input costs fluctuate with bauxite processing capacity concentrated in Gulf Coast chemical corridors.
- Refrigerated Dryer Technical Ceiling:Pressure dew point floors near +3°C limit deployment in sub-zero pharmaceutical applications without hybrid configurations.
- California Air Resources Board Variances:State-level oil mist discharge thresholds create compliance friction for equipment deployed across multi-state manufacturing networks.
Strategic Opportunities
- Gulf Coast Petrochemical Cluster Modernization:Texas and Louisiana facilities are retrofitting legacy compressed air systems to meet EPA NESHAP hazardous air pollutant standards.
- Food Processing Oil Vapor Removal:Activated charcoal final-stage filtration represents underpenetrated white space in USDA-inspected meat and dairy operations.
- Industrial IoT Convergence:Dew point sensors integrated with predictive maintenance platforms enable remote monitoring contracts for distributed manufacturing footprints.
Industry Challenges
- ISO 8573-1 Certification Timeline:Third-party validation protocols for Class 0 purity documentation extend sales cycles by four to eight months in pharmaceutical accounts.
- Legacy Pneumatic Integration:Retrofit installations in Great Lakes automotive plants face compatibility friction with existing instrument air headers and control valve specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Compressed Air Treatment Equipment Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Dryers, Separators, Accessories Application: Manufacturing, Pharmaceuticals, Food Processing, Automotive End User: Industrial Plants, Research Laboratories, Healthcare Facilities, Food Companies Technology: Membrane, Refrigerated, Desiccant, Activated Charcoal |
| Companies Covered | Atlas Copco, Chicago Pneumatic, Donaldson Company, Inc., Gardner Denver, SPX FLOW, Inc., Sullair, Parker Hannifin, Ingersoll Rand, Alpha-Pure Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Compressed Air Treatment Equipment Market Trends and Innovations
Heat-of-compression desiccant regeneration and smart monitoring architectures are compressing energy intensity and maintenance intervals across US industrial compressed air infrastructure.
Heat-of-compression desiccant dryers are supplanting heated blower purge systems in large-volume petrochemical and automotive installations. Gulf Coast refineries and Great Lakes assembly plants are adopting these units to capture compressor exhaust heat for regeneration cycles. This thermal integration is supplanting electric heater elements and cutting operating energy draw by roughly one-third in continuous-duty applications.
FDA draft guidance on aseptic processing air quality is tightening microbial monitoring requirements for pharmaceutical compressed air systems. Manufacturers must now validate bioburden detection protocols alongside particulate and moisture specifications. New Jersey and North Carolina cleanroom operators are responding by specifying redundant filtration trains with integrity testing documentation.
Compressed air treatment procurement is consolidating through integrated facility management contracts rather than discrete capital equipment purchases. Food processing and healthcare systems are bundling dryer, filter, and monitoring procurement under multi-year performance agreements. This service model penetration is most visible in California and Texas where energy efficiency incentives reward guaranteed output specifications over equipment ownership.
US Compressed Air Treatment Equipment Market Segmentation
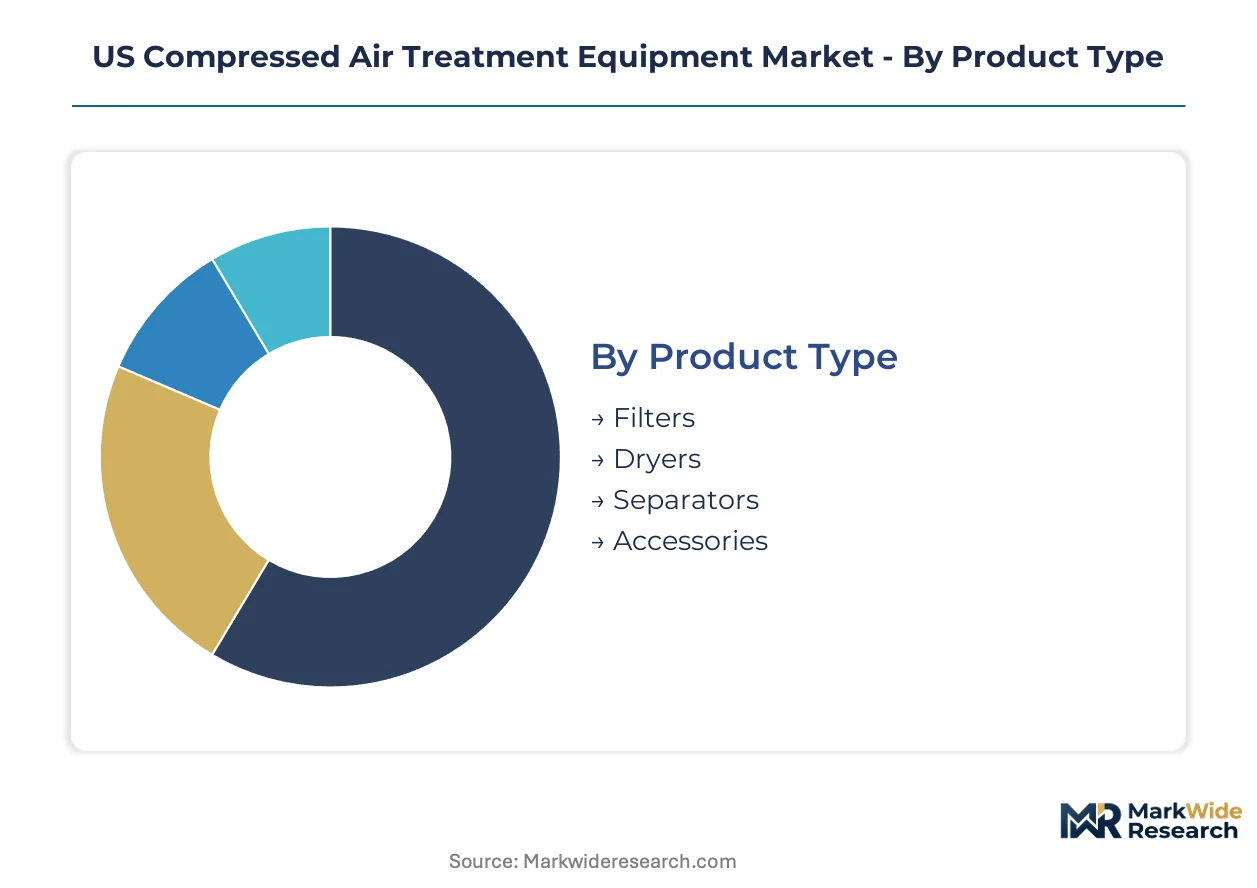
Compressed air treatment equipment segments diverge sharply by purity specification and energy intensity, with pharmaceutical-grade systems commanding premium pricing against commodity industrial alternatives. Segmentation clarity enables targeted positioning across OSHA-regulated breathing air, FDA-validated process air, and general manufacturing utility applications.
Product Type:
Membrane and point-of-use filtration technologies pose the strongest substitution threat to conventional centralized dryer systems in space-constrained pharmaceutical skids.
- Filters:Coalescing and particulate filtration stages remove oil aerosols and solid contaminants down to 0.01 micron in critical process lines. Demand concentrates in New Jersey pharmaceutical corridors where redundant filtration trains satisfy FDA draft guidance on aseptic processing air quality validation.
- Dryers:Refrigerated and desiccant technologies achieve pressure dew points from +10°C to -70°C depending on application criticality. Great Lakes automotive plants favor heat-of-compression desiccant regeneration to capture compressor exhaust thermal energy and cut operating draw.
- Separators:Centrifugal and gravitational moisture removal units protect downstream components from bulk liquid contamination.
- Accessories:Dew point sensors, drain valves, and conditioning hardware complete integrated treatment skids.
Dryers retain volume leadership; filters hold the steepest expansion curve as point-of-use pharmaceutical specifications tighten.
Application:
Cost-tier stratification separates pharmaceutical-grade Class 0 infrastructure from general manufacturing utility specifications.
- Manufacturing:General industrial pneumatic systems require moisture and particulate control for tool protection and instrument air reliability. Gulf Coast petrochemical clusters are retrofitting legacy compressed air infrastructure to meet EPA NESHAP hazardous air pollutant standards.
- Pharmaceuticals:Aseptic processing lines mandate ISO 8573-1 Class 0 purity with validated microbial detection protocols. North Carolina cleanroom expansions are driving specification intensity for oil vapor removal and bioburden monitoring documentation.
- Food Processing:USDA-inspected meat and dairy operations require activated charcoal final-stage filtration for oil vapor elimination below detection thresholds.
- Automotive:Assembly plant instrument air systems balance dew point performance against energy consumption in high-volume continuous-duty environments.
Manufacturing commands installed base dominance; pharmaceuticals climbs fastest on cleanroom infrastructure expansion.
End User:
Customer-type fragmentation separates capital-intensive industrial plants from specification-driven healthcare and food safety environments.
- Industrial Plants:Petrochemical refineries and automotive assembly facilities operate large-scale compressed air networks with energy efficiency as primary procurement criterion. Texas and Louisiana Gulf Coast facilities are modernizing legacy systems under integrated facility management contracts.
- Research Laboratories:Analytical instrumentation and cleanroom operations require stable dew point control with minimal pressure fluctuation.
- Healthcare Facilities:Hospital surgical suites and breathing air systems fall under OSHA 29 CFR 1910.134 enforcement with documented filtration integrity testing.
- Food Companies:Dairy processing and meatpacking operations face USDA inspection protocols alongside compressed air contact-surface safety requirements.
Industrial Plants anchor revenue concentration; Healthcare Facilities expand most quickly on OSHA breathing air mandate enforcement.
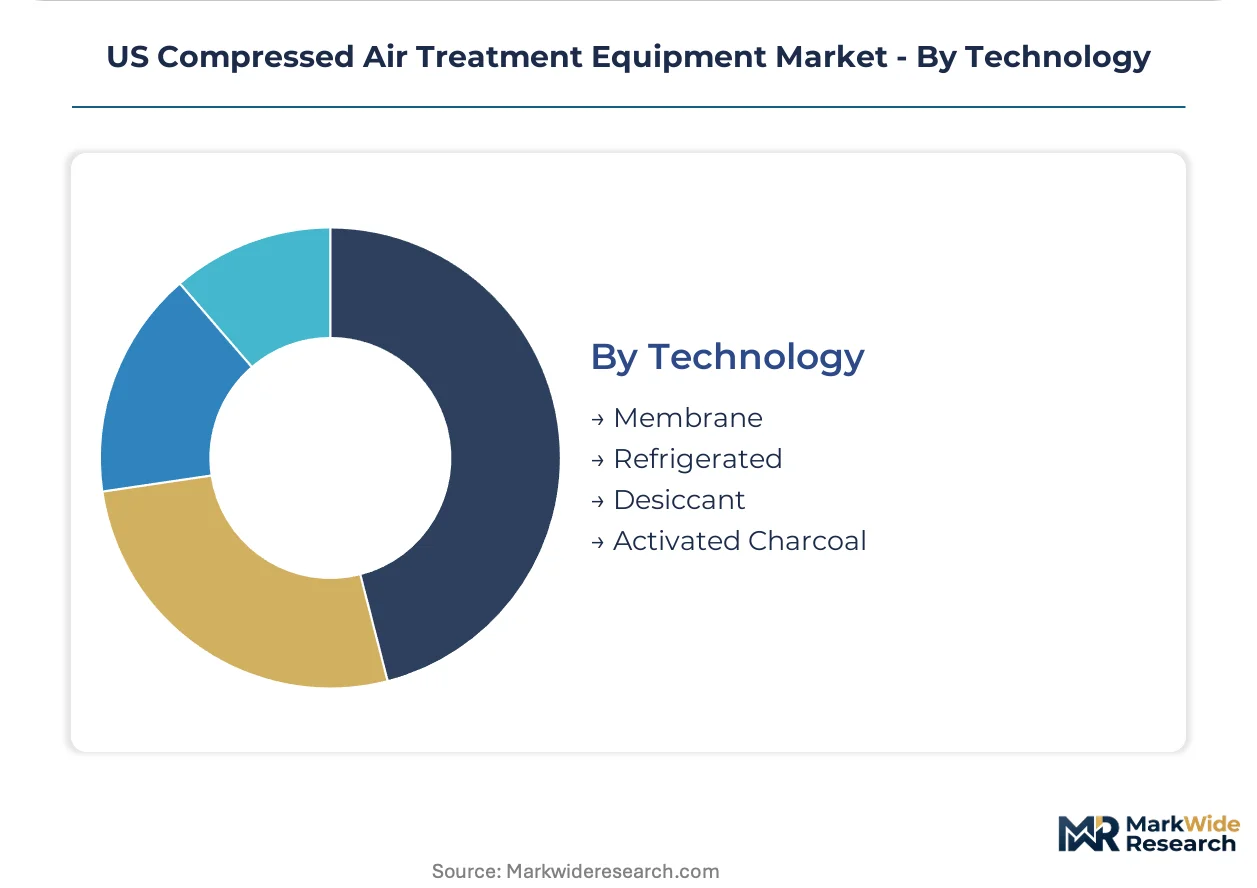
Technology:
Maturity-stage differentiation separates established desiccant and refrigerated platforms from emerging membrane miniaturization.
- Membrane:Hollow-fiber systems achieve moderate dew point suppression without moving parts or desiccant media replacement. Point-of-use pharmaceutical skids in space-constrained New Jersey facilities are adopting membrane dryers where footprint constraints override energy efficiency priorities.
- Refrigerated:Mechanical cooling systems deliver pressure dew points near +3°C for general industrial applications. Technical floors limit deployment in sub-zero pharmaceutical processes without hybrid desiccant configurations.
- Desiccant:Heat-of-compression and heated blower purge systems achieve -40°C to -70°C dew points for critical process air. Activated alumina supply concentration in Gulf Coast chemical corridors creates input cost volatility.
- Activated Charcoal:Oil vapor adsorption stages attach premium pricing in food processing and healthcare facilities where Class 0 purity represents non-negotiable specification.
Desiccant technology maintains revenue leadership; membrane systems gain share fastest on pharmaceutical skid miniaturization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate heavily in pharmaceutical manufacturing clusters, automotive assembly corridors, and petrochemical processing hubs, with regulatory enforcement intensity varying sharply across state-level jurisdictions.
New Jersey and North Carolina
Pharmaceutical cleanroom expansions in these Atlantic states are driving ISO 8573-1 Class 0 infrastructure procurement. FDA 21 CFR Part 211 cGMP provisions mandate validated microbial detection protocols alongside particulate control. New Brunswick and Research Triangle Park facilities are installing redundant filtration trains with integrity testing documentation for aseptic processing lines.
Texas and Louisiana
Gulf Coast petrochemical clusters are retrofitting legacy compressed air systems under EPA NESHAP hazardous air pollutant standards. OSHA 29 CFR 1910.134 breathing air requirements extend to contractor populations in refinery turnaround operations. Houston and Lake Charles facilities are adopting heat-of-compression desiccant regeneration to capture compressor exhaust thermal energy.
Michigan and Ohio
Great Lakes automotive assembly plants balance dew point performance against energy consumption in high-volume instrument air networks. State-level utility rebate programs reward verified compressed air efficiency improvements. Detroit and Toledo corridors favor hybrid desiccant-refrigerated configurations for sub-zero paint booth applications.
California
Food processing and healthcare systems are bundling treatment equipment procurement under integrated facility management contracts with guaranteed output specifications. California Air Resources Board oil mist discharge thresholds create compliance friction for multi-state manufacturing networks. Central Valley dairy operations and Los Angeles-area meatpacking facilities require activated charcoal final-stage filtration for USDA inspection protocols.
US Compressed Air Treatment Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with cross-category pneumatic portfolios, creating tiered competitive access where filtration depth, thermal integration expertise, and distribution channel density separate premium positioning from commodity supply. Three archetypes dominate: integrated compressor-treatment system suppliers, standalone filtration specialists, and industrial distribution channel players leveraging hydraulic-pneumatic cross-selling strength. Consolidation pressure operates through strategic partnerships for IoT-enabled monitoring platforms and geographic expansion into pharmaceutical corridor proximity.
Among diversified industrial conglomerates, Atlas Copco and Ingersoll Rand exemplify scale-driven positions spanning compressor origination through downstream treatment integration. Donaldson Company, Inc. occupies a specialist position anchored in filtration depth, particularly in pharmaceutical and food processing accounts where ISO 8573-1 Class 0 documentation requirements favor dedicated contamination control expertise. Parker Hannifin sits within the distribution-leverage archetype, competing through industrial channel density and hydraulic-pneumatic cross-selling strength rather than standalone treatment technology origination.
| Leading Market Players |
|---|
| Atlas Copco |
| Chicago Pneumatic |
| Donaldson Company, Inc. |
| Gardner Denver |
| SPX FLOW, Inc. |
| Sullair |
| Parker Hannifin |
| Ingersoll Rand |
| Alpha-Pure Corporation |
| Others |
Pricing and Supply Chain Analysis
Compressor OEM scale economies in the Great Lakes automotive corridor anchor supply concentration and establish price floors for treatment equipment tiers. Activated alumina desiccant costs fluctuate with Gulf Coast bauxite processing capacity, feeding through to dryer system pricing in pharmaceutical and petrochemical accounts. Buyer procurement consolidation under integrated facility management contracts is compressing margins for standalone filtration specialists.
Pricing Analysis
Cost-plus contracts with activated alumina indexation dominate desiccant dryer procurement in Texas and Louisiana petrochemical clusters. Three-tier pricing structure across Class 0 pharmaceutical-grade, ISO 8573-1 industrial-certified, and general utility specifications separates premium documentation-heavy systems from commodity alternatives. Pricing pressure stems from membrane dryer substitution in space-constrained New Jersey pharmaceutical skids. Industrial plants exhibit highest price sensitivity; healthcare facilities under OSHA breathing air mandates show lowest.
Supply Chain Analysis
Inventory cycles for activated alumina and activated charcoal extend lead times for pharmaceutical-grade filtration trains by six to ten weeks. Manufacturing concentrates in Germany, China, and the United States for compressor-treatment integrated systems; desiccant media production draws from bauxite processing corridors in Australia, Brazil, and Guinea. Single-source vulnerability sits with Gulf Coast chemical concentration for alumina supply. Distribution runs through industrial pneumatics distributors with hydraulic cross-selling capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressed air treatment procurement is shifting toward platform-based service models where IoT-enabled monitoring and guaranteed output specifications replace discrete equipment ownership, creating interoperability requirements that favor integrated compressor-treatment suppliers over standalone component vendors.
For Market Incumbents: Secure FDA 21 CFR Part 211 cGMP validation documentation capabilities to defend pharmaceutical account retention against membrane dryer entrants. Anchor backward integration into activated alumina supply or long-term offtake agreements with Gulf Coast processors to buffer input cost volatility. Channel control through exclusive industrial distribution partnerships remains critical for automotive corridor access. For New Entrants and Emerging Players: Anchor in California food processing and healthcare integrated facility management contracts where performance-based procurement lowers capital equipment barriers. Target activated charcoal final-stage filtration for USDA-inspected meat and dairy operations as the most penetrable white space. Pursue direct OEM partnerships with pharmaceutical skid fabricators rather than distributor channel builds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors filtration specialists with ISO 8573-1 Class 0 certification infrastructure over commodity dryer manufacturers facing membrane substitution. Long-term viability over a five-to-ten-year horizon rests on regulatory compliance service capabilities rather than hardware margins. Watch EPA reconsideration of oil mist discharge thresholds as the signal for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-of-Compression Technology Deployment | Captures compressor exhaust thermal energy to cut operating draw by one-third in continuous-duty petrochemical applications. |
| IoT-Enabled Remote Monitoring Platform | Enables predictive maintenance contracts for distributed pharmaceutical manufacturing footprints under FDA draft guidance. |
| Activated Alumina Supply Integration | Buffers input cost volatility from bauxite processing concentration in Gulf Coast chemical corridors. |
| Class 0 Certification Infrastructure Investment | Extends sales cycles but locks in pharmaceutical account retention against membrane dryer substitution threats. |
| Integrated Facility Management Contract Expansion | Consolidates procurement bundling in California and Texas where energy efficiency incentives reward guaranteed output specifications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through SEC 10-K filings, customs and trade data, EPA NESHAP regulatory filings, and compressed air industry association technical publications. Bottom-up equipment unit economics triangulated against top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through installed base replacement cycles, cleanroom infrastructure expansion trajectories, and regulatory enforcement intensity variations by state jurisdiction. CAGRs derived from regression analysis of historical equipment shipments against pharmaceutical manufacturing capital expenditure patterns and automotive production indices. Forecast inputs incorporated OSHA inspection frequency data and FDA guidance publication timelines.
Material uncertainties — EPA reconsideration of oil mist discharge thresholds, activated alumina supply disruptions, and membrane dryer technology performance improvements — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and industrial capital expenditure stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Europe Ventilation Equipment Market