
 Refrigerant Compressors Market | 2026-2036
Refrigerant Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerant Compressors Market Analysis
Capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is redrawing competitive boundaries in refrigerant compressors. Danfoss leverages in-house power electronics and semiconductor fabrication to control variable-speed scroll supply chains. BITZER sustains dominance in semi-hermetic reciprocating platforms through German engineering centers and foundry investments. Emerson Electric Co. anchors North American commercial HVAC service networks with extensive wholesaler relationships and technician training infrastructure.
A refrigerant compressor is a mechanical device that increases the pressure and temperature of gaseous refrigerant to enable phase-change heat transfer in vapor-compression refrigeration cycles, typically operating with discharge pressures between 150 and 450 psi depending on the working fluid and application. These machines serve as the thermodynamic heart of climate control systems, cold storage warehouses, and automotive cabin cooling by converting electrical or mechanical energy into refrigerant pressure work. Scroll compressors command premium positioning in commercial HVAC systems due to superior efficiency and reduced vibration profiles compared to reciprocating alternatives. Inverter technology represents the fastest-expanding segment as variable-speed drives displace fixed-speed units in residential and light-commercial installations across temperate climates. Rotary compressors occupy mature, cost-optimized niches in compact refrigeration appliances where manufacturing scale outweighs efficiency optimization.
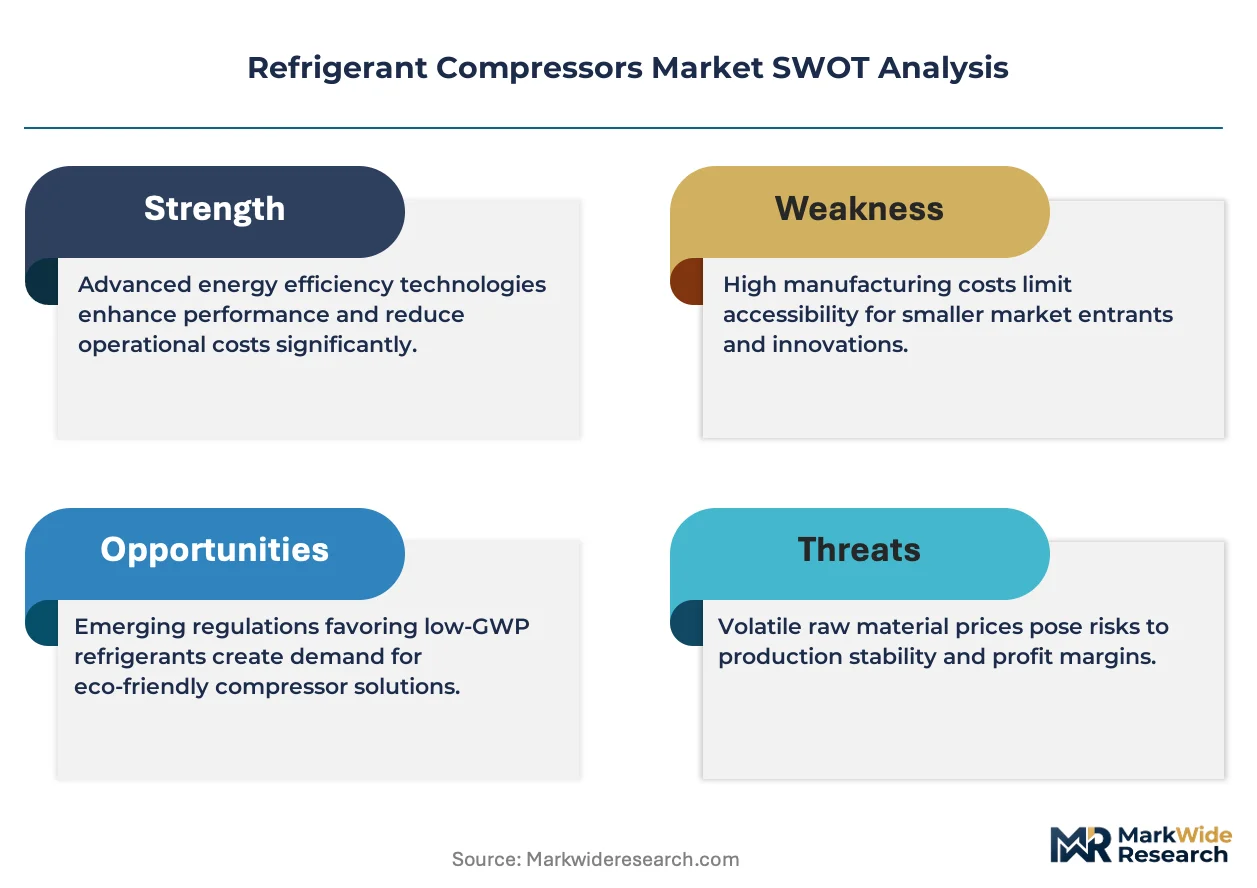
The EPA's Significant New Alternatives Policy program and the EU F-Gas Regulation are restricting high-global-warming-potential refrigerants, forcing compressor redesigns for lower-pressure, flammable alternatives like R-32 and R-290. China's MEE enforces dual carbon goals that tighten efficiency mandates on industrial cooling systems, while India's BIS certification requirements for refrigeration equipment create compliance barriers for imported compressor assemblies. Stakeholders must monitor refrigerant transition timelines and calibrate R&D portfolios between hydrocarbon-compatible architectures and transcritical CO₂ platforms before regulatory phase-downs harden into supply constraints.
Market Dynamics
The EU F-Gas Regulation's phasedown of hydrofluorocarbon quotas is forcing compressor architecture redesigns across the supply chain, while inverter penetration in commercial HVAC accelerates variable-speed displacement of fixed-speed platforms.
Growth Catalysts
- Cold chain logistics expansion:Southeast Asian operators are scaling refrigerated warehouse capacity to serve pharmaceutical distribution and e-commerce grocery fulfillment, driving demand for semi-hermetic reciprocating units.
- India's commercial retrofit wave:BITZER certification requirements under BIS standards are accelerating inverter-driven scroll compressor adoption in aging supermarket refrigeration systems.
- Transcritical CO₂ technology maturation:Climate-neutral refrigeration architectures are gaining traction in European food retail as operators anticipate complete HFC phase-out timelines.
Market Restraints
- Copper and rare earth price volatility:Permanent magnet materials for inverter motors face supply concentration risks from Chinese processing facilities, compressing margins on variable-speed scroll production.
- Flammable refrigerant safety barriers:R-290 (propane) charge limits under IEC safety standards restrict compressor displacement architectures in commercial applications below 150 kW cooling capacity.
- Semi-hermetic platform obsolescence risk:German engineering centers dominate reciprocating casting expertise, creating geographic concentration vulnerability as scroll technology captures efficiency-sensitive segments.
Strategic Opportunities
- Industrial heat pump convergence:Waste heat recovery applications in food processing are creating demand for high-pressure ammonia compressors that bridge refrigeration and heating cycles.
- Service network digitization:Predictive maintenance platforms using vibration analytics are enabling compressor OEMs to capture recurring revenue streams from distributed cold storage operators.
- Indian PLI scheme alignment:Domestic manufacturing incentives for refrigeration components are attracting assembly investments to Gujarat and Tamil Nadu industrial corridors.
Industry Challenges
- Refrigerant transition certification backlog:Laboratory testing capacity for A2L and A3 safety classifications is creating 12-18 month approval delays for new compressor platforms.
- Power electronics integration complexity:Variable-speed drive firmware development requires embedded systems talent scarce in traditional compressor engineering organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerant Compressors Market |
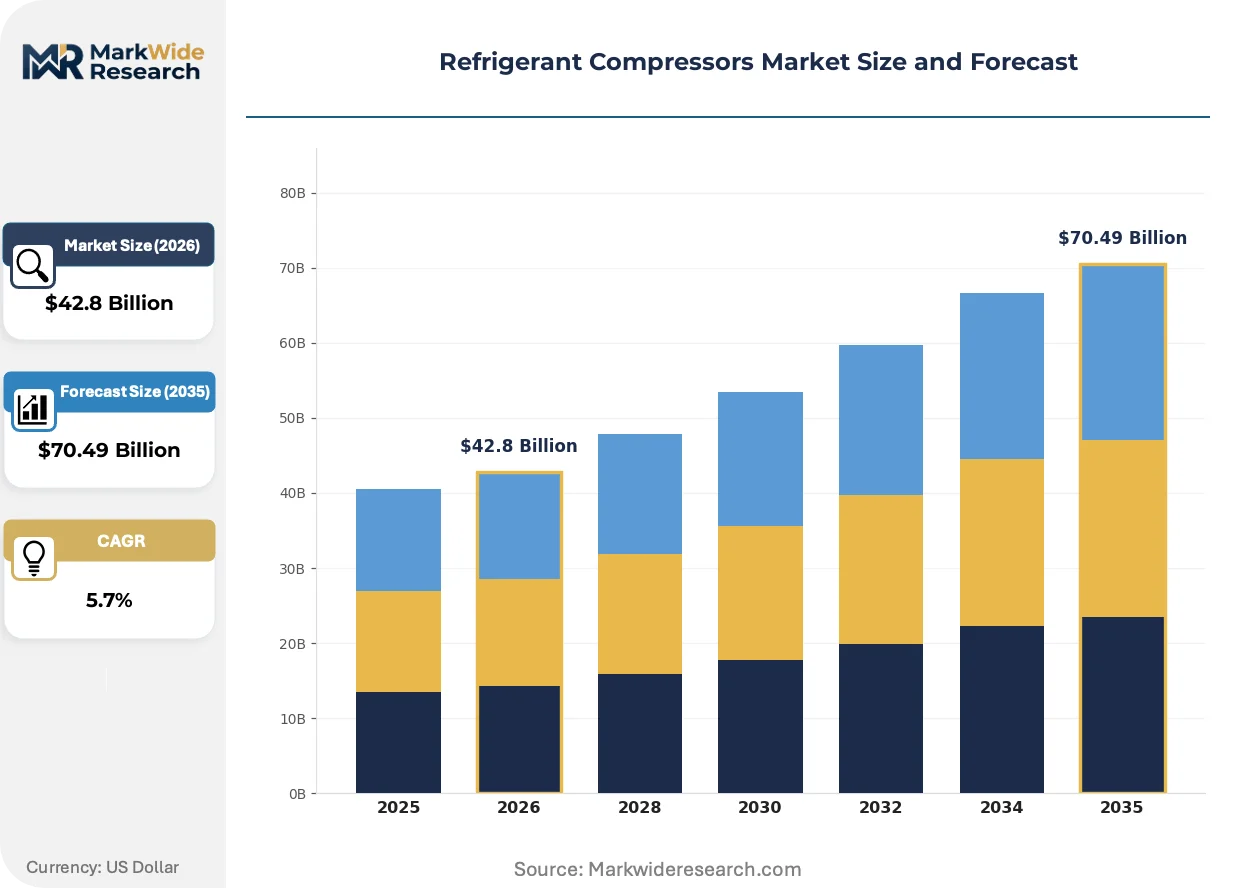
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Scroll, Rotary, Centrifugal Application: HVAC Systems, Refrigeration, Industrial Cooling, Automotive Air Conditioning End User: Residential, Commercial, Industrial, Transportation Technology: Variable Speed, Fixed Speed, Digital Scroll, Inverter Technology |
| Companies Covered | Danfoss, Emerson Electric Co., BITZER, Tecumseh Products Company LLC, Mitsubishi Electric Corporation, LG Electronics, Johnson Controls, Panasonic Corporation, Embraco LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerant Compressors Market Emerging Trajectories
Digital compressor controls and alternative refrigerant architectures are converging to redefine efficiency benchmarks, while regulatory phase-downs compress technology transition timelines across end-use verticals.
Magnetic bearing centrifugal compression is decomposing the traditional oil-lubricated chiller paradigm in large commercial installations. Data center operators in Singapore and Frankfurt are specifying oil-free platforms to eliminate maintenance intervals and refrigerant contamination risks. This technology is decomposing the service revenue model that sustained incumbent OEMs through scheduled maintenance contracts.
The EPA's Significant New Alternatives Policy program is accelerating refrigerant transition timelines by restricting high-GWP working fluids in new equipment. Compressor manufacturers must now validate seal compatibility and pressure envelope integrity for R-32 and R-454B blends before 2025 production windows. North American commercial HVAC OEMs are responding by dual-certifying scroll platforms for both legacy and transitional refrigerants.
Food retailers are consolidating compressor procurement through integrated facility management contracts rather than equipment-only transactions. Unbundled after-sales service agreements are displacing traditional warranty-plus-maintenance structures in European supermarket chains. This shift is most visible in Germany and the Netherlands, where REWE and Albert Heijn have centralized refrigeration asset management under energy-performance contracting frameworks.
Refrigerant Compressors Market Segmentation
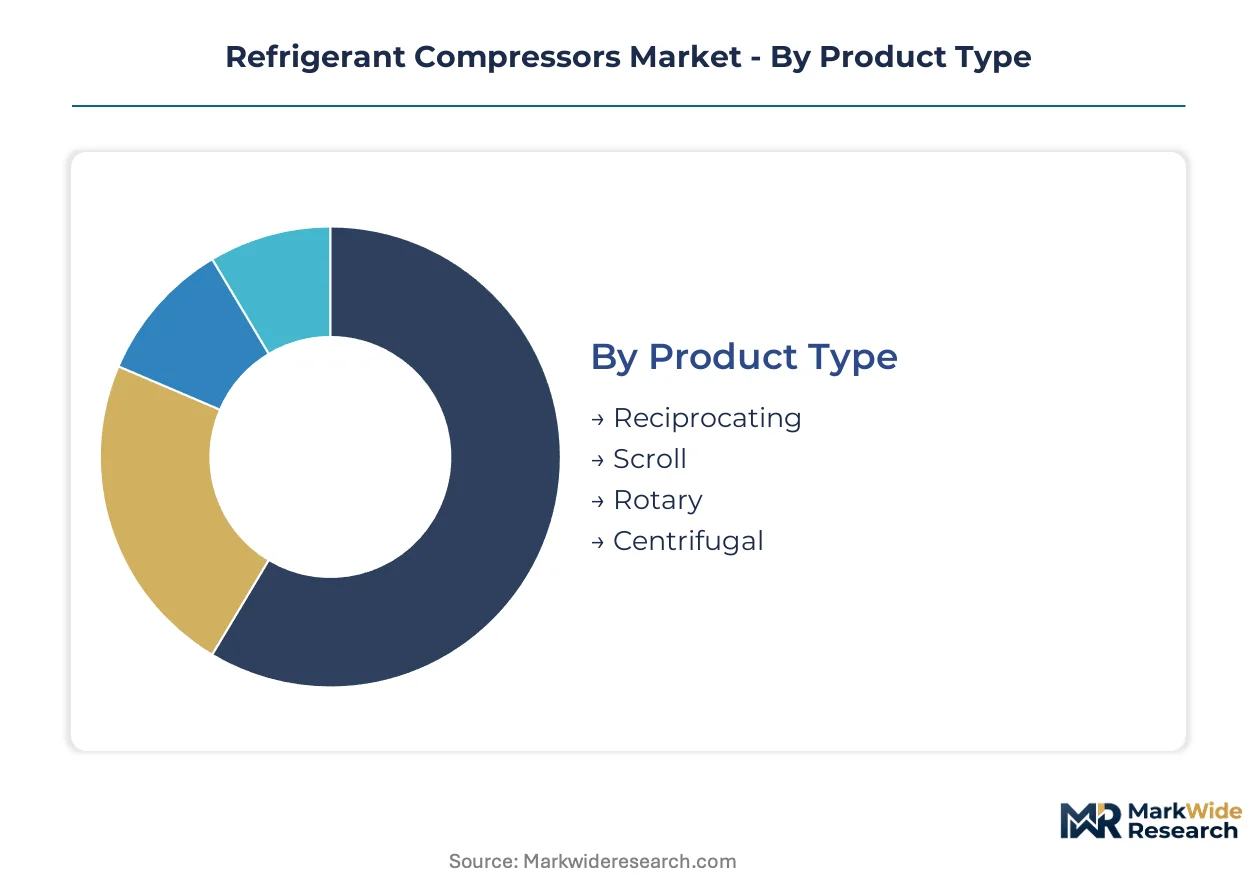
Refrigerant compressor segmentation reveals how technology transitions and regulatory pressures fragment demand across incompatible equipment architectures. Compressor selection now hinges on refrigerant compatibility, efficiency mandates, and service infrastructure availability rather than unit cost alone.
Product Type:
Scroll compressors face the strongest substitution pressure as magnetic bearing centrifugal technology captures large-tonnage commercial installations previously served by oil-lubricated platforms.
- Reciprocating:Semi-hermetic designs dominate cold storage warehouses and industrial process cooling where maintenance access and field serviceability outweigh efficiency premiums. BITZER and Carlyle sustain foundry investments in cast iron crankcases to preserve European and North American supply chains against scroll displacement.
- Scroll:Orbiting spiral plate geometry delivers isentropic efficiency advantages of 15-20% over reciprocating alternatives in 3-50 HP ranges. Inverter-driven scrolls now command supermarket retrofit specifications in India under BIS certification mandates, while fixed-speed variants retreat to cost-sensitive residential HVAC replacement markets.
- Rotary:Compact vane and rolling piston architectures serve household refrigerators and window air conditioners where manufacturing scale at Chinese facilities enables sub-$50 unit economics.
- Centrifugal:Magnetic bearing oil-free platforms are decomposing traditional chiller service revenue models in Singapore and Frankfurt data centers.
Scroll compressors anchor the volume base while centrifugal platforms gain share at the steepest rate.
Application:
Cost tier differentiation separates specification-grade commercial installations from commodity replacement markets.
- HVAC Systems:Variable-speed heat pump compressors now face dual refrigerant certification requirements under EPA SNAP timelines for R-32 and R-454B transitions. OEMs stock dual-pressure envelope scrolls to bridge 2024-2026 production windows.
- Refrigeration:Transcritical CO₂ booster architectures are capturing European food retail as REWE and Albert Heijn consolidate procurement under energy-performance contracting. Ammonia systems retain dominance in industrial cold storage above 500 kW capacity.
- Industrial Cooling:Process chillers for pharmaceutical and chemical manufacturing specify semi-hermetic reciprocating units for refrigerant containment integrity.
- Automotive Air Conditioning:Electric vehicle thermal management demands compressors capable of heating and cooling cycles from common refrigerant circuits.
Refrigeration applications concentrate margin capture while HVAC Systems expand most quickly through residential heat pump retrofits.
End User:
Customer type determines procurement sophistication, with integrated facility managers extracting performance guarantees unavailable to fragmented residential buyers.
- Residential:Split-system replacements drive volume through wholesale distributor networks where contractor brand loyalty outweighs efficiency optimization.
- Commercial:Centralized asset management contracts now bundle compressor procurement with predictive maintenance subscriptions.
- Industrial:Food processors specify ammonia-compatible reciprocating platforms for simultaneous cooling and heat recovery applications.
- Transportation:Reefer container operators face IEC safety standard restrictions on R-290 charge limits below 150 kW cooling capacity.
Commercial end users anchor technology migration while Industrial applications climb fastest on waste heat recovery convergence.
Technology:
Supply concentration in power electronics is forcing compressor OEMs into backward integration partnerships or captive semiconductor sourcing.
- Variable Speed:Permanent magnet motors face rare earth processing concentration risks from Chinese facilities, compressing margins despite efficiency premiums.
- Fixed Speed:Single-phase induction motors retain cost advantages in emerging market residential replacements where electricity tariff structures blunt inverter payback calculations.
- Digital Scroll:Axial compliance modulation enables capacity control without inverter electronics, bridging cost-efficiency gaps in light commercial applications.
- Inverter Technology:Embedded systems talent scarcity in traditional compressor engineering organizations is extending firmware development timelines.
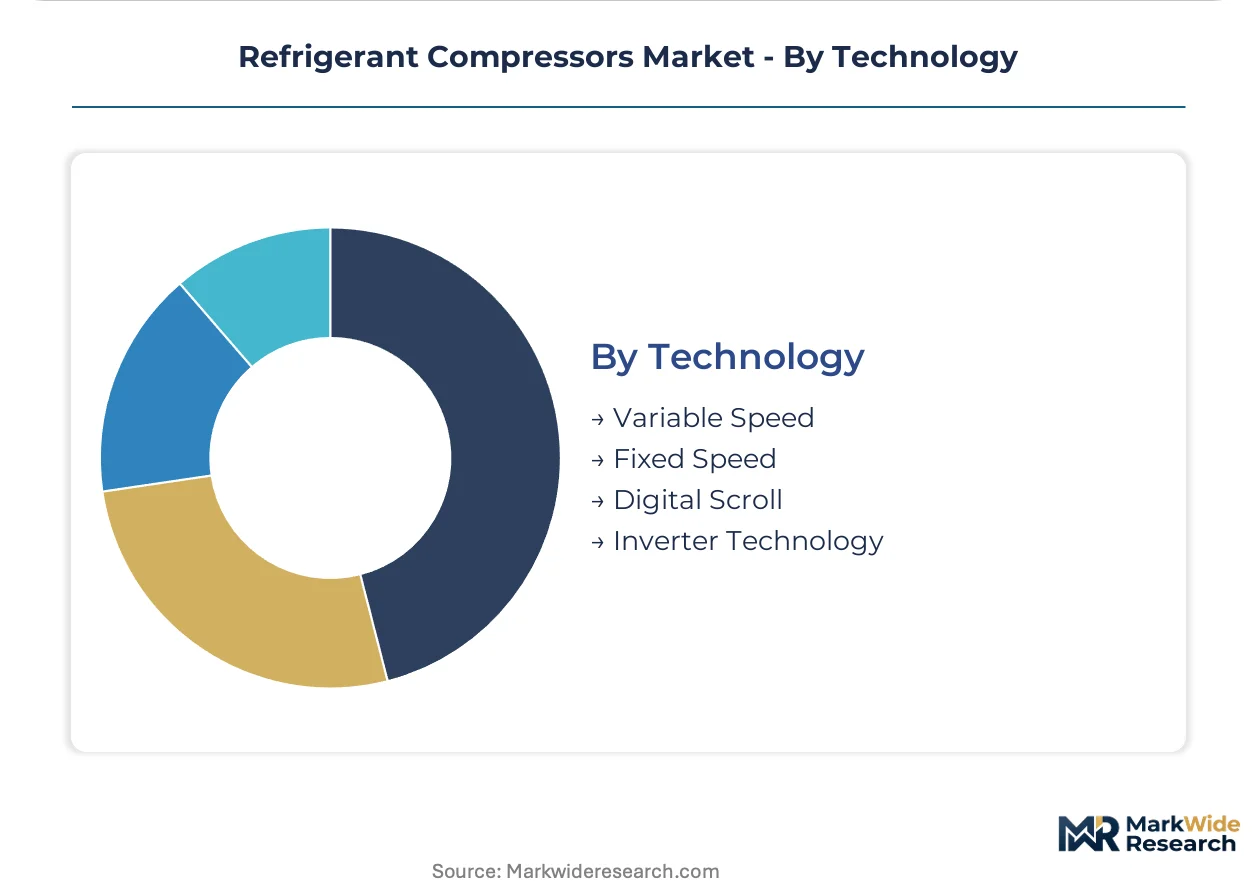
Fixed-speed platforms anchor emerging market volume while inverter technology captures specification-grade commercial retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies. Southeast Asian cold chain operators prioritize unit economics over efficiency premiums, while European food retailers absorb technology premiums for transcritical CO₂ compliance.
United States
Data center cooling demand in Northern Virginia and Dallas-Fort Worth accelerates oil-free centrifugal compressor specifications. The EPA SNAP program restricts R-410A in new equipment from 2025, forcing dual-refrigerant scroll certification. Houston industrial corridors sustain ammonia compressor demand for petrochemical process cooling.
Germany
Supermarket chains REWE and Edeka consolidate refrigeration procurement under energy-performance contracting frameworks. The EU F-Gas Regulation mandates HFC quota reductions of 55% by 2030. Bavarian engineering centers in Schweinfurt anchor semi-hermetic reciprocating foundry expertise against scroll displacement.
China
Domestic heat pump production in Zhejiang and Guangdong provinces scales for export to European retrofit markets. The MEE enforces dual carbon goals tightening industrial cooling efficiency mandates. Qingdao and Shanghai industrial clusters concentrate rotary compressor manufacturing for household appliance OEMs.
India
BIS certification requirements for commercial refrigeration equipment accelerate inverter-driven scroll adoption in supermarket retrofits. The PLI scheme for white goods components attracts assembly investments to Gujarat and Tamil Nadu corridors. Mumbai pharmaceutical cold storage operators specify semi-hermetic units for field serviceability.
Japan
Commercial building HVAC replacement cycles in Tokyo and Osaka drive variable-speed heat pump compressor demand. METI efficiency standards for refrigeration equipment tighten minimum performance coefficients. Nagoya industrial clusters sustain precision casting capabilities for compact rotary compressor platforms.
Refrigerant Compressors Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with captive power electronics capabilities command specification-grade commercial segments, while assembly-dependent competitors compete on manufacturing scale in residential replacement markets. Three archetypes dominate: vertically integrated European engineering specialists, Asian manufacturing scale platforms, and North American service-network anchors. Competitive moves concentrate on backward integration into semiconductor sourcing and predictive maintenance platform development.
Among European engineering specialists, BITZER GmbH and Danfoss A/S exemplify the integrated manufacturing archetype through in-house foundry and power electronics capabilities. Emerson Electric Co. anchors North American positioning through wholesaler relationship density and technician training infrastructure. These three occupy distinct competitive vectors—BITZER in semi-hermetic industrial applications, Danfoss in variable-speed scroll platforms, and Emerson in commercial HVAC service networks—rather than direct product confrontation.
| Leading Market Players |
|---|
| Danfoss |
| Emerson Electric Co. |
| BITZER |
| Tecumseh Products Company LLC |
| Mitsubishi Electric Corporation |
| LG Electronics |
| Johnson Controls |
| Panasonic Corporation |
| Embraco LLC |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between European food retailers and compressor OEMs lock in supply access for transcritical CO₂ platforms while fixing price visibility through energy-performance contracting structures. These arrangements concentrate pricing power with integrated manufacturers possessing captive foundry and power electronics capabilities, while assembly-dependent competitors absorb commodity volatility in spot-procured rare earth inputs.
Pricing Analysis
After-sales service revenue tiers—spanning predictive maintenance subscriptions, extended warranty contracts, and parts replacement programs—now drive lifetime value capture beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates magnetic bearing centrifugal platforms from inverter-driven scrolls and fixed-speed rotary units. Cost compression in variable-speed scroll production is intensifying because permanent magnet motor inputs face Chinese rare earth processing concentration. Residential replacement buyers exhibit highest price sensitivity, while data center operators absorb premium positioning for oil-free platforms.
Supply Chain Analysis
China and Japan anchor rotary compressor manufacturing for household appliance OEMs, while Germany and the United States sustain semi-hermetic reciprocating foundry expertise. Permanent magnet materials for inverter motors draw from Chinese processing facilities, copper windings rest on Chilean and Peruvian mining output, and precision castings hinge on Bavarian engineering centers. Single-source vulnerability in rare earth magnet supply creates geographic concentration exposure. Distribution runs through wholesaler networks in North America and direct OEM relationships in European food retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms and vibration analytics subscriptions are expanding faster than hardware sales, reframing refrigerant compressors as a service-attach opportunity where recurring revenue streams displace transactional equipment margins.
For Market Incumbents: Shield semi-hermetic reciprocating margins by accelerating foundry automation in German engineering centers before scroll technology captures additional efficiency-sensitive segments. Deepen backward integration into power electronics through embedded systems talent acquisition or captive semiconductor partnerships, insulating variable-speed scroll production from rare earth price volatility. For New Entrants and Emerging Players: Anchor in India's commercial refrigeration retrofit wave where BIS certification requirements create compliance barriers for imported assemblies and domestic PLI incentives attract manufacturing investment. Target supermarket energy-performance contracting in Southeast Asian cold chain expansion, leveraging lower labor cost structures to undercut European OEM pricing on semi-hermetic units. For Investors and Strategic Acquirers: The market sits at a refrigerant transition phase that favors integrated manufacturers with dual-certification capabilities for both legacy and A2L/A3 refrigerant architectures. Five-to-ten year viability hinges on laboratory testing capacity ownership and predictive maintenance platform development. Watch refrigerant transition timeline acceleration as the inflection signal—compressed EPA SNAP and EU F-Gas Regulation schedules will strand fixed-capability assets faster than modeled.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Vibration analytics subscriptions capture recurring revenue from REWE and Albert Heijn cold storage networks. |
| Dual-Refrigerant Scroll Certification | R-32 and R-454B validation bridges 2025 production windows under EPA SNAP restrictions. |
| Backward Integration into Power Electronics | Captive semiconductor sourcing insulates Danfoss and BITZER from Chinese rare earth concentration. |
| Indian PLI Scheme Manufacturing Alignment | Gujarat and Tamil Nadu assembly investments exploit BIS certification barriers for imported units. |
| Magnetic Bearing Centrifugal Scale-Up | Oil-free platforms decompose traditional chiller service revenue models in Singapore data centers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and OEM technical documentation. Compressor engineering directors, cold chain logistics procurement leads, supermarket facility managers, and aftermarket service heads provided operational validation. EPA SNAP program records, EU F-Gas Regulation quota tracking, BIS certification databases, and MEE efficiency mandate disclosures supplied secondary triangulation. Bottom-up unit shipment modeling and top-down value chain analysis converged on segment-level estimates.
Segmentation dimensions modeled include compressor architecture type, refrigerant compatibility class, application vertical, end-user procurement sophistication, and technology tier across the analysis window. CAGRs derived from installed base replacement cycles, regulatory phase-down timelines, and cold chain capacity expansion pipelines. Input assumptions incorporated copper and rare earth price trajectory scenarios alongside inverter penetration curves in commercial HVAC retrofits.
Material uncertainties—accelerated refrigerant transition schedules, laboratory testing capacity bottlenecks, and rare earth export restriction escalations—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity input availability. Recalibration cycles align with material shifts in EPA and EU regulatory timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
HVAC Air Handling Units Market