
 Europe Heat Pump Market | 2026-2036
Europe Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Heat Pump Market Analysis
German equipment manufacturing is rebalancing toward larger-output heat pump systems for multi-family retrofits. Bosch Thermotechnology leverages its domestic production network to anchor supply for Central European utility-scale projects. Stiebel Eltron specializes in compact monobloc units optimized for the limited plant-room footprints common in Alpine residential buildings. Vaillant Group extends its service infrastructure across Benelux and France, competing on installation speed and aftermarket coverage.
A heat pump is a thermodynamic device that extracts thermal energy from ambient air, ground, or water sources and transfers it to indoor spaces via compression and refrigerant cycle operation, typically achieving coefficient of performance ratings between three and five under standard test conditions. Its primary commercial purpose is to deliver space heating and domestic hot water with substantially lower direct carbon emissions than combustion-based alternatives. Air source systems dominate unit volumes across the region due to lower upfront installation costs and minimal site disruption, though ground source configurations command premium margins in new-build segments where borehole drilling can be integrated into foundation work. Inverter technology leads the technology dimension by modulating compressor speed to match variable heat loads, reducing cycling losses in the temperate maritime climates prevalent across Western Europe.
The EU Green Deal, F-Gas Regulation, and CE marking under the Ecodesign Directive collectively mandate refrigerant transition to lower-GWP alternatives and enforce minimum seasonal performance factors for products entering the European market. EMA and national building codes in France, Germany, and Italy further shape demand by conditioning renovation subsidies on heat pump compatibility and primary energy factor thresholds. Stakeholders must monitor refrigerant supply chain readiness for R-32 and propane blends, as availability constraints could bottleneck production before the next tightening of F-Gas phase-down quotas.
Market Dynamics
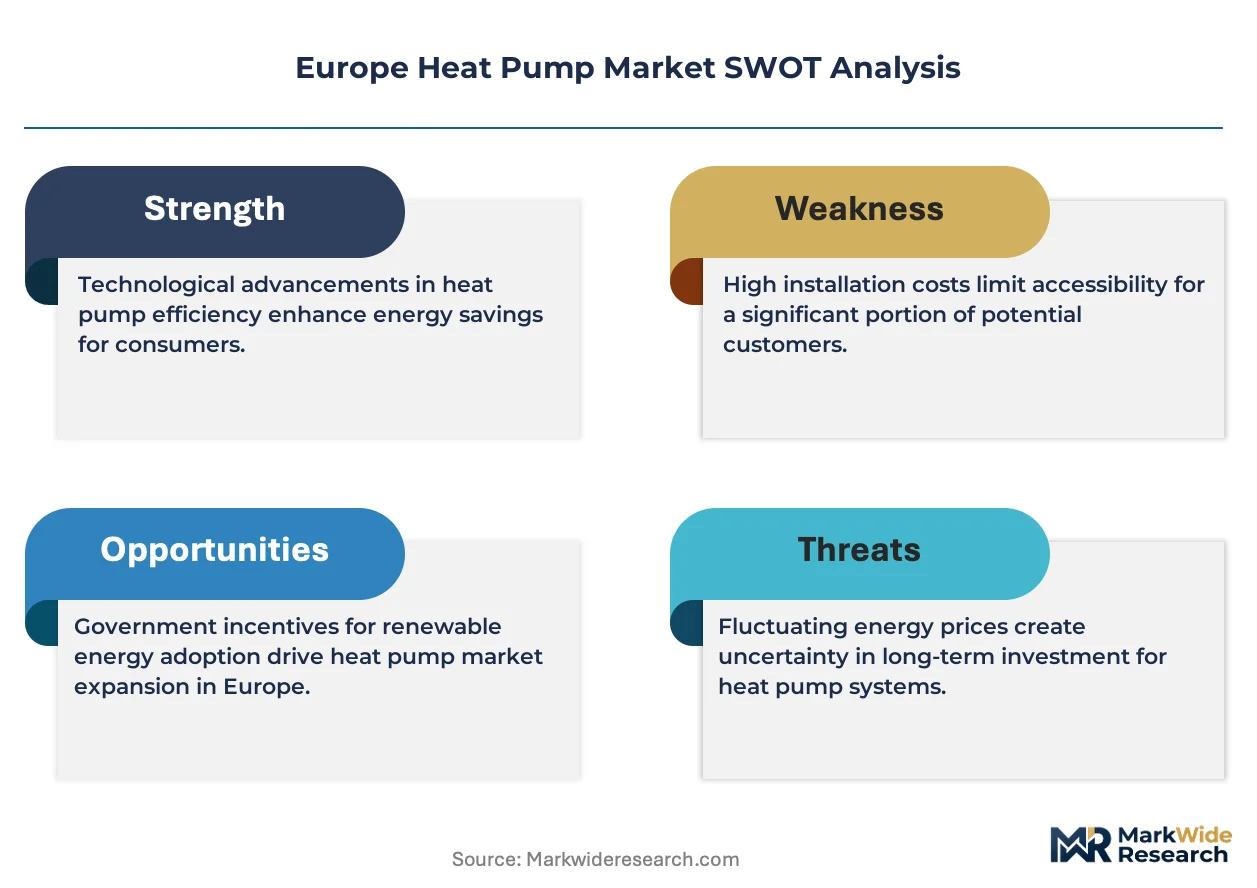
The F-Gas Regulation's phasedown of high-GWP refrigerants is compressing equipment redesign cycles while simultaneously constraining supply chains for compliant alternatives across European manufacturing bases.
Growth Catalysts
- EU Green Deal building renovation mandates:National governments in Germany, France, and Italy condition residential retrofit subsidies on fossil-fuel boiler replacement with heat pump systems, accelerating installed base turnover in aging building stock.
- Inverter-driven efficiency gains:Variable-speed compressor technology achieves seasonal performance factors above four in temperate maritime climates, satisfying Ecodesign Directive minimum thresholds while reducing household operating expenditure.
- Denmark and Sweden district heating integration:Large-output heat pumps feed low-temperature distribution networks in Nordic municipal systems, displacing biomass and natural gas peaking plants.
Market Restraints
- R-32 and propane supply concentration:Refrigerant production capacity for lower-GWP alternatives clusters among Chinese chemical manufacturers, exposing European OEMs to quota allocation bottlenecks ahead of F-Gas phase-down milestones.
- Ground source drilling cost structure:Borehole installation requires specialized geothermal contractors whose availability limits project throughput in new-build residential segments.
- Electrical panel upgrade requirements:Legacy residential infrastructure in Southern Europe lacks ampacity for heat pump operation, forcing ancillary investment that extends payback periods.
Strategic Opportunities
- Polish and Romanian residential penetration:These markets exhibit sub-ten-percent heat pump saturation in single-family housing, presenting first-mover positioning before building code harmonization accelerates.
- Hybrid heat pump-gas boiler systems:Dual-fuel configurations bridge cold-climate performance gaps while satisfying transitional regulatory frameworks in Benelux and Northern France.
- Utility-scale heat-as-a-service contracts:Energy retailers in Germany and Austria bundle equipment installation with long-term thermal output agreements, transferring performance risk from households to balance-sheet operators.
Industry Challenges
- Refrigerant handling certification gaps:Installation networks across Spain and Portugal lack sufficient F-gas qualified technicians to support deployment targets, constraining aftermarket service capacity.
- CE marking timeline compression:Ecodesign Directive test protocol updates require recertification of existing product portfolios within eighteen-month windows, diverting engineering resources from next-generation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Heat Pump Market |
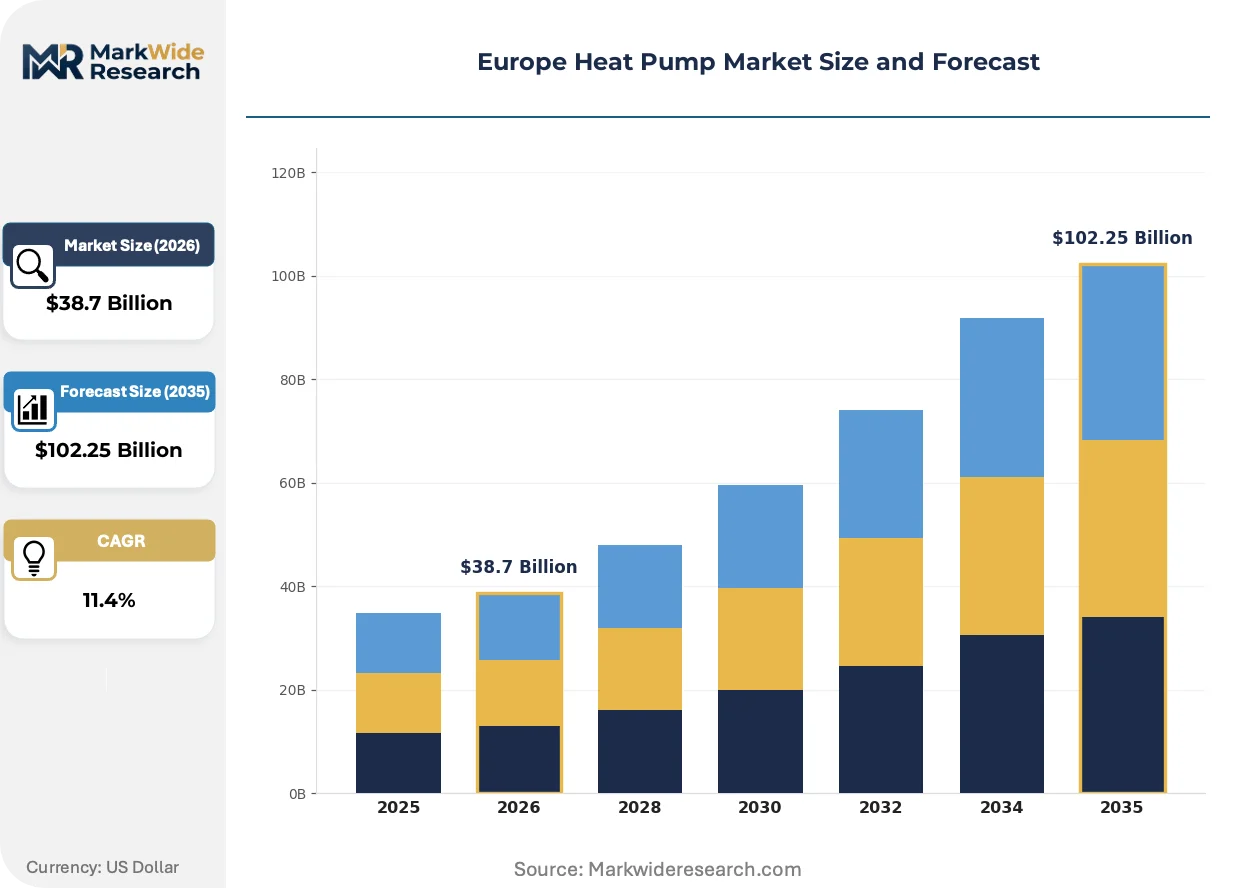
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Water Source, Hybrid End User: Residential, Commercial, Industrial, Agriculture Installation Type: New Build, Retrofit, Off-grid, Centralized Technology: Inverter, Non-inverter, Variable Speed, Geothermal |
| Companies Covered | Daikin Industries, Stiebel Eltron, Siemens Energy, MAN Energy Solutions, Bosch Thermotechnology, Vaillant Group, Viessmann Group, Carrier Global Corporation, NIBE Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Heat Pump Market Emerging Trajectories
Refrigerant chemistry, control systems, and procurement models are simultaneously evolving as OEMs navigate the F-Gas transition while buyers demand integrated thermal solutions rather than discrete equipment transactions.
CO2 transcritical heat pump cycles are rewriting performance expectations for domestic hot water production in multi-family buildings. German and Austrian housing associations specify these systems for centralized plant rooms where high output temperatures eliminate the need for auxiliary electric heating. The technology compresses operating cost differentials against gas boilers in high-density residential applications.
The F-Gas Regulation's 2027 quota tightening is forcing refrigerant inventory management restructuring across European supply chains. OEMs are dual-qualifying R-32 and propane blends to mitigate single-source dependency, while national regulators in France and Germany accelerate technician retraining timelines. Air-source residential units face the steepest compliance cost escalation due to charge volume sensitivity.
Aggregated procurement through housing cooperatives and municipal housing authorities is consolidating buyer power in German and Dutch urban markets. These entities negotiate fleet-scale installation contracts with standardized specifications, displacing traditional installer-led equipment selection. The model concentrates volume among OEMs capable of delivering synchronized multi-site rollouts.
Europe Heat Pump Market Segmentation
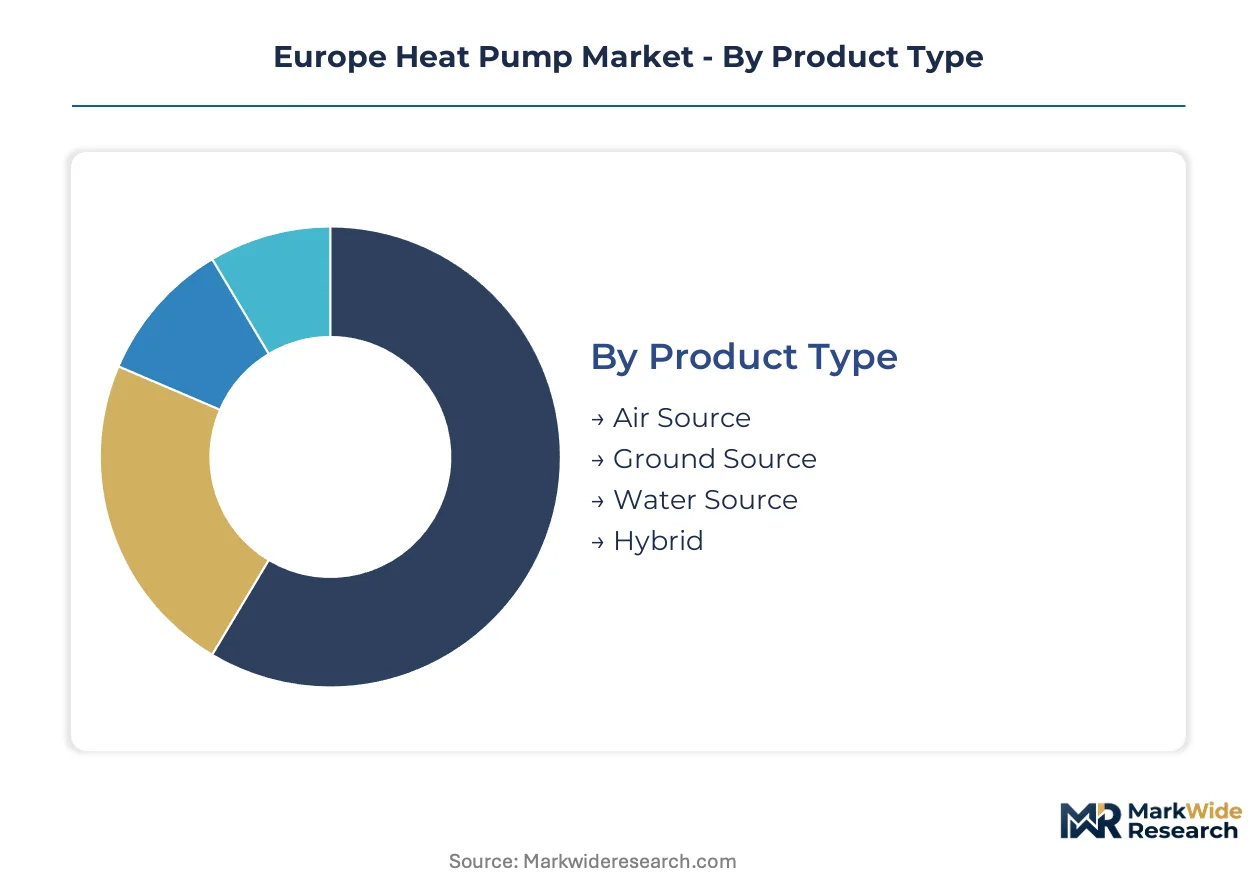
Segmentation in the Europe Heat Pump Market reveals how technology choices, building contexts, and customer requirements fragment demand across distinct equipment specifications and service models. Understanding these divisions exposes where margin concentrates and where volume expansion faces structural barriers.
Product Type:
Air source systems dominate unit volumes across the region while ground source configurations command premium margins in new-build segments.
- Air Source:These systems extract thermal energy from ambient air through vapor-compression cycles, achieving coefficient of performance ratings between three and four in temperate maritime climates. Demand concentrates in German and French residential retrofits where lower upfront installation costs and minimal site disruption accelerate fossil-fuel boiler replacement timelines.
- Ground Source:Borehole-based systems leverage stable subsurface temperatures to deliver higher seasonal performance factors, particularly in Nordic heating-degree-day environments. New-build residential developments in Denmark and Sweden integrate geothermal loops during foundation work, though specialized drilling contractor availability constrains project throughput.
- Water Source:Lake and river-based configurations serve waterfront commercial properties and district heating intakes in Alpine regions.
- Hybrid:Dual-fuel heat pump-gas boiler systems bridge cold-climate performance gaps in Benelux transitional regulatory frameworks.
Mature deployment sits with air source systems across Central European retrofits. Newer deployment is concentrated in ground source configurations within Nordic municipal housing projects.
End User:
Residential customers drive installed base turnover while commercial operators prioritize long-term thermal output contracts.
- Residential:Single-family and multi-family households across Germany, France, and Italy replace aging fossil-fuel boilers under EU Green Deal renovation mandates. Subsidy conditioning on primary energy factor thresholds accelerates heat pump compatibility assessments in aging building stock.
- Commercial:Office buildings, retail chains, and hospitality operators in German urban centers negotiate fleet-scale installation contracts through housing cooperatives and municipal authorities.
- Industrial:Process heat applications in food processing and pharmaceutical manufacturing exploit waste heat recovery integration.
- Agriculture:Greenhouse operators in the Netherlands deploy low-temperature distribution networks fed by large-output heat pumps displacing natural gas peaking plants.
Residential retrofits anchor current volume. Commercial heat-as-a-service contracting represents the steepest expansion trajectory among balance-sheet operators.
Installation Type:
New-build integration permits optimized system sizing while retrofit segments confront legacy infrastructure constraints.
- New Build:Construction-phase integration allows coordinated borehole drilling, optimized heat emitter specification, and seamless electrical panel sizing. German and Austrian housing associations specify CO2 transcritical systems for centralized plant rooms in multi-family developments.
- Retrofit:Existing building stock replacement faces ancillary upgrade requirements including electrical ampacity expansion and radiator resizing. Southern European markets exhibit particular friction due to legacy residential infrastructure limitations.
- Off-grid:Rural properties beyond natural gas network reach exploit heat pump economics against heating oil and propane alternatives.
- Centralized:District heating feed-in configurations serve Nordic municipal systems with large-output equipment feeding low-temperature distribution networks.
Retrofit deployment dominates current volumes across German and French markets. New-build specification is gaining share fastest in Austrian and Dutch urban housing developments.
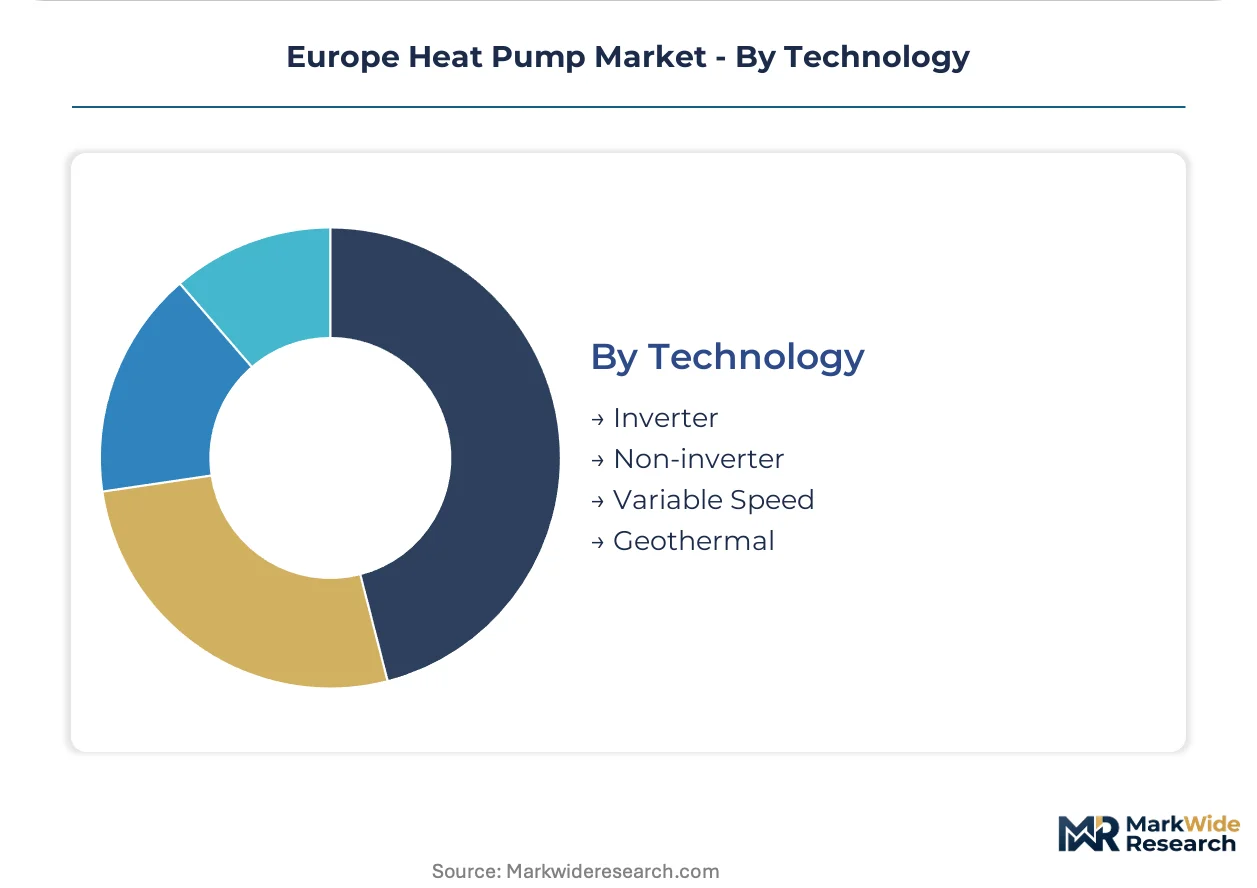
Technology:
Inverter modulation reduces cycling losses in variable-load applications while non-inverter legacy stock faces Ecodesign Directive phase-out.
- Inverter:Variable-speed compressor technology modulates output to match heat load fluctuations, achieving seasonal performance factors above four. Western European temperate maritime climates maximize efficiency gains from reduced cycling losses.
- Non-inverter:Fixed-speed compression cycles operate at full capacity with on-off control, suffering efficiency penalties under partial load conditions. Ecodesign Directive minimum thresholds and F-Gas Regulation compliance costs accelerate replacement timelines.
- Variable Speed:Advanced motor control algorithms extend modulation range beyond conventional inverter architectures.
- Geothermal:Ground-coupled heat exchanger optimization software improves borehole field thermal response prediction.
Non-inverter systems retain residual presence in price-sensitive Southern European segments. Inverter technology is climbing the fastest across German, French, and Benelux replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stable subsurface geology across the Nordic Basin and sedimentary formations beneath the North German Plain anchor ground-source deployment economics. Permafrost boundaries and fractured crystalline bedrock further differentiate installation feasibility across Scandinavian and Alpine territories.
Germany
Multi-family housing associations in North Rhine-Westphalia and Bavaria drive centralized plant-room specifications. The Federal Office for Economic Affairs and Export Control administers renovation subsidies conditioning payouts on heat pump compatibility assessments. Erfurt-based housing cooperatives negotiate fleet-scale CO2 transcritical contracts for 2025-2027 rollout tranches.
France
Alpine municipalities and Atlantic coastal retirement complexes generate divergent demand profiles for monobloc versus split-system architectures. ANSM building code amendments in 2024 tightened primary energy factor thresholds for renovation permits. Lyon housing authorities consolidate buyer power through aggregated procurement of standardized air-source units.
Sweden
District heating network operators in Stockholm and Malmö integrate large-output heat pumps as baseload displacement for biomass peaking plants. The Swedish Energy Agency coordinates municipal subsidy pools with EU Green Deal renovation milestone tracking. Gothenburg's municipal housing company pilots seawater-source configurations for waterfront residential clusters.
Netherlands
Greenhouse operators in Westland and horticulture zones around Aalsmeer deploy low-temperature distribution networks fed by industrial-scale equipment. Dutch building codes mandate fossil-fuel boiler phase-out timelines for existing residential stock by 2028. Eindhoven technical universities coordinate field trials with housing corporations for hybrid heat pump-gas boiler transitional systems.
Poland
Single-family housing in Masovian and Silesian Voivodeships exhibits sub-ten-percent heat pump penetration against coal-fired heating dominance. National building code harmonization with EU Ecodesign Directive thresholds accelerates from 2026. Krakow municipal authorities pilot air-source deployment in historic core districts with district heating network extension constraints.
Europe Heat Pump Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized refrigerant handling and compact system architectures. The vendor base distributes across three concentration tiers: integrated conglomerates with domestic appliance lineages, mid-scale specialists in monobloc and ground-source configurations, and regional fabricators serving utility-scale district heating tenders. Strategic differentiation concentrates on inverter control algorithm development and F-Gas compliance certification speed. Capacity expansion and backward integration into compressor manufacturing represent the dominant competitive moves.
Among German-origin producers, Bosch Thermotechnology GmbH, Stiebel Eltron GmbH & Co. KG, and Vaillant Group occupy positions within the premium-tier equipment segment. Bosch Thermotechnology exemplifies the conglomerate archetype leveraging appliance manufacturing scale. Stiebel Eltron represents specialist positioning in compact system architectures. Vaillant Group anchors the service infrastructure expansion model across adjacent Benelux and French territories. These three entities collectively illustrate how domestic production networks, specialized product focus, and aftermarket coverage define competitive positioning in Central European markets.
| Leading Market Players |
|---|
| Daikin Industries |
| Stiebel Eltron |
| Siemens Energy |
| MAN Energy Solutions |
| Bosch Thermotechnology |
| Vaillant Group |
| Viessmann Group |
| Carrier Global Corporation |
| NIBE Group |
| Others |
Supply Flow & Price Mechanics
R-32 refrigerant spot pricing cascades through European OEM cost structures into three distinct equipment tiers, with charge-volume sensitivity in air-source units amplifying margin compression ahead of F-Gas quota tightening. Chinese chemical manufacturers anchor refrigerant supply, concentrating pricing power among quota holders while European assemblers absorb reformulation costs.
Pricing Analysis
Warranty and service bundling separates premium German OEM offerings from unbundled economy-tier imports, with multi-year thermal output guarantees commanding 15-25% price premiums over bare-equipment transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking tier and inverter control sophistication. Pricing pressure stems from F-Gas compliance cost escalation in residential air-source segments. Single-family retrofit buyers in Southern Europe exhibit highest price sensitivity; municipal housing authorities in Germany and Netherlands demonstrate lowest.
Supply Chain Analysis
Reverse-logistics networks for refrigerant recovery and compressor remanufacturing remain underdeveloped across Southern European installation bases, creating aftermarket service bottlenecks. Manufacturing concentration clusters in Germany, China, and Japan, with compressor production drawing from Japanese and Chinese motor suppliers. Copper tubing, aluminum heat exchangers, and rare-earth permanent magnets constitute critical input dependencies. Single-source vulnerability sits with Chinese R-32 quota allocations. Distribution runs through specialized HVAC wholesalers and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Heat Pump Market operates as a cost-of-compliance story where F-Gas Regulation certification timelines erect barrier-to-entry moats favoring incumbents with established refrigerant handling networks and recertification bandwidth.
For Market Incumbents: Acquire F-gas qualified technician training capacity to lock in aftermarket service coverage ahead of 2027 quota tightening. Defensive consolidation should target compressor manufacturing assets to reduce exposure to Japanese and Chinese motor supply concentration. Emerging Polish and Romanian equipment fabricators threaten volume-tier positioning; backward integration into refrigerant inventory management mitigates single-source quota risk. For New Entrants and Emerging Players: Rural single-family households in Masovian and Silesian Voivodeships represent the most penetrable buyer archetype before Polish building code harmonization accelerates. White-space targets include hybrid heat pump-gas boiler transitional systems for Benelux cold-climate applications and compact monobloc units for Alpine plant-room constraints. Go-to-market execution should route through utility-scale heat-as-a-service contracting with German energy retailers. For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with propane blend qualification speed and municipal procurement relationships. Long-term viability centers on OEMs capable of synchronized multi-site rollout execution for housing cooperative aggregated procurement. Acquisition target archetype: inverter control algorithm developers with F-Gas recertification track records. Monitor Chinese refrigerant quota allocation announcements as inflection indicator for European OEM margin trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Dual-Qualification Investment | R-32 and propane blend certification mitigates single-source dependency ahead of F-Gas quota tightening. |
| Technician Training Network Expansion | F-gas qualified installer capacity in Spain and Portugal unlocks underserved retrofit demand. |
| Compressor Manufacturing Backward Integration | In-house motor production reduces exposure to Japanese and Chinese supply concentration. |
| Municipal Procurement Relationship Development | Aggregated housing authority contracts concentrate volume among synchronized rollout-capable OEMs. |
| CO2 Transcritical System Portfolio Addition | High-temperature output capability captures multi-family centralized plant-room specifications. |
Methodological Framework
EMA regulatory filings, EU Green Deal implementation databases, and F-Gas Regulation quota tracking formed the secondary backbone, supplemented by customs trade data for refrigerant and compressor import flows. Primary interviews with OEM product development directors, municipal housing authority procurement managers, F-gas certification body administrators, and geothermal drilling contractors combined with secondary validation. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against subsidy disbursement records.
Bottom-up modeling aggregated unit economics across air-source, ground-source, and hybrid system configurations, while top-down validation tracked EU renovation mandate spending allocations. Segmentation dimensions spanned product type, end-user category, installation context, and technology tier. CAGRs derived from installed base turnover rates and building code enforcement timelines. Forecast inputs incorporated F-Gas phase-down quota trajectories and national subsidy conditioning thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant chemistry transitions and electrical infrastructure upgrade pacing. Assumptions reflect current Ecodesign Directive test protocols and F-Gas Regulation enforcement intensity. Practitioners should monitor Chinese refrigerant quota allocation announcements and German federal subsidy renewal debates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Water Softener Equipment Market