
 HVAC Fan and Evaporator Coil Market | 2026-2036
HVAC Fan and Evaporator Coil Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Fan and Evaporator Coil Market Analysis
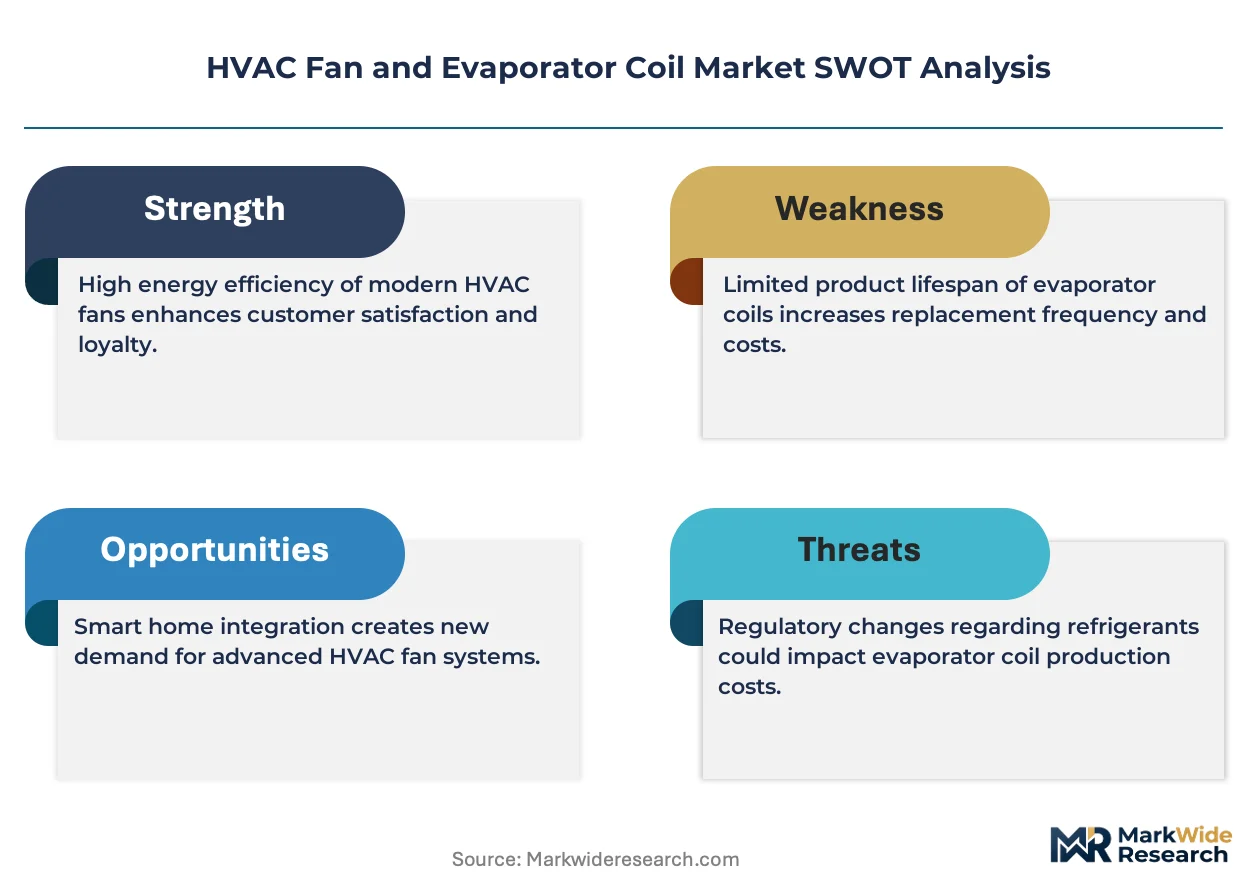
Aluminum is repositioning copper in evaporator coil construction as manufacturers seek cost stability and supply security. Carrier leverages vertical integration across compressor and coil production to protect margin structure. Daikin Industries anchors its position through proprietary microchannel coil technology and Asia-Pacific manufacturing scale.
HVAC fans and evaporator coils constitute forced-air heat exchange assemblies where refrigerant or chilled water circulates through finned tubing while fans drive air across the coil surface; typical aluminum fins range from 0.1 to 0.15 mm thickness with hydrophilic coatings to prevent moisture bridging. Centrifugal fans dominate commercial installations where static pressure requirements exceed 2.5 inches water gauge, while axial fans lead in compact rooftop units. Variable Speed Drive technology captures expanding margin pools as building codes tighten part-load efficiency requirements.
The EPA's AIM Act HFC phasedown, DOE minimum efficiency standards, and ASHRAE 90.1 updates collectively force refrigerant transitions and fan efficacy improvements across the supply chain. California Title 24 and similar state-level stretch codes accelerate demand for smart controls and energy-efficient configurations. Stakeholders must monitor refrigerant chemistry transitions and efficiency tier migrations to avoid stranded inventory and compliance gaps.
Market Dynamics
The EPA's AIM Act HFC phasedown is forcing refrigerant chemistry transitions across coil specifications while aluminum substitution in fin stock is compressing legacy copper supply dependencies.
Growth Catalysts
- Data center cooling infrastructure:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are expanding chiller and air-handling unit deployments. Coil and fan assemblies scale with rack density requirements.
- China's commercial real estate buildout:Tier-1 and Tier-2 cities are adding Class A office stock and semiconductor fabrication facilities. Local MEE efficiency mandates accelerate high-performance coil specification.
- Variable Speed Drive penetration:DOE fan efficacy standards and ASHRAE 90.1 updates are mandating part-load optimization. VSD-equipped centrifugal fans capture specification in commercial installations above 2.5 inches water gauge.
Market Restraints
- Copper price volatility:LME copper fluctuations above historical baselines compress margin predictability for manufacturers maintaining legacy coil architectures.
- Refrigerant transition friction:EPA SNAP rules and state-level HFC restrictions create inventory stranding risk for coils pre-charged with phasedown-scheduled chemistries.
- Supply concentration in aluminum fin stock:Chinese primary aluminum and rolled products dominate global coil input supply, exposing non-integrated assemblers to tariff and logistics disruption.
Strategic Opportunities
- India's cooling action plan:The country's CEA efficiency mandates and PLI scheme for white goods are opening specification windows for low-global-warming-potential coil platforms.
- Microchannel coil convergence:Brazed aluminum microchannel technology is penetrating commercial rooftop units previously served by round-tube-plate-fin designs.
- Smart control integration:California Title 24 and similar stretch codes are mandating networked fan and coil optimization, creating aftermarket sensor and control attachment revenue.
Industry Challenges
- Refrigerant handling certification:EPA Section 608 technician requirements and evolving state-level credentials extend field service training timelines and constrain installer capacity.
- Legacy building retrofit integration:Existing ductwork static pressure profiles and refrigerant line sets limit drop-in replacement of high-efficiency coil and fan assemblies without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Fan and Evaporator Coil Market |
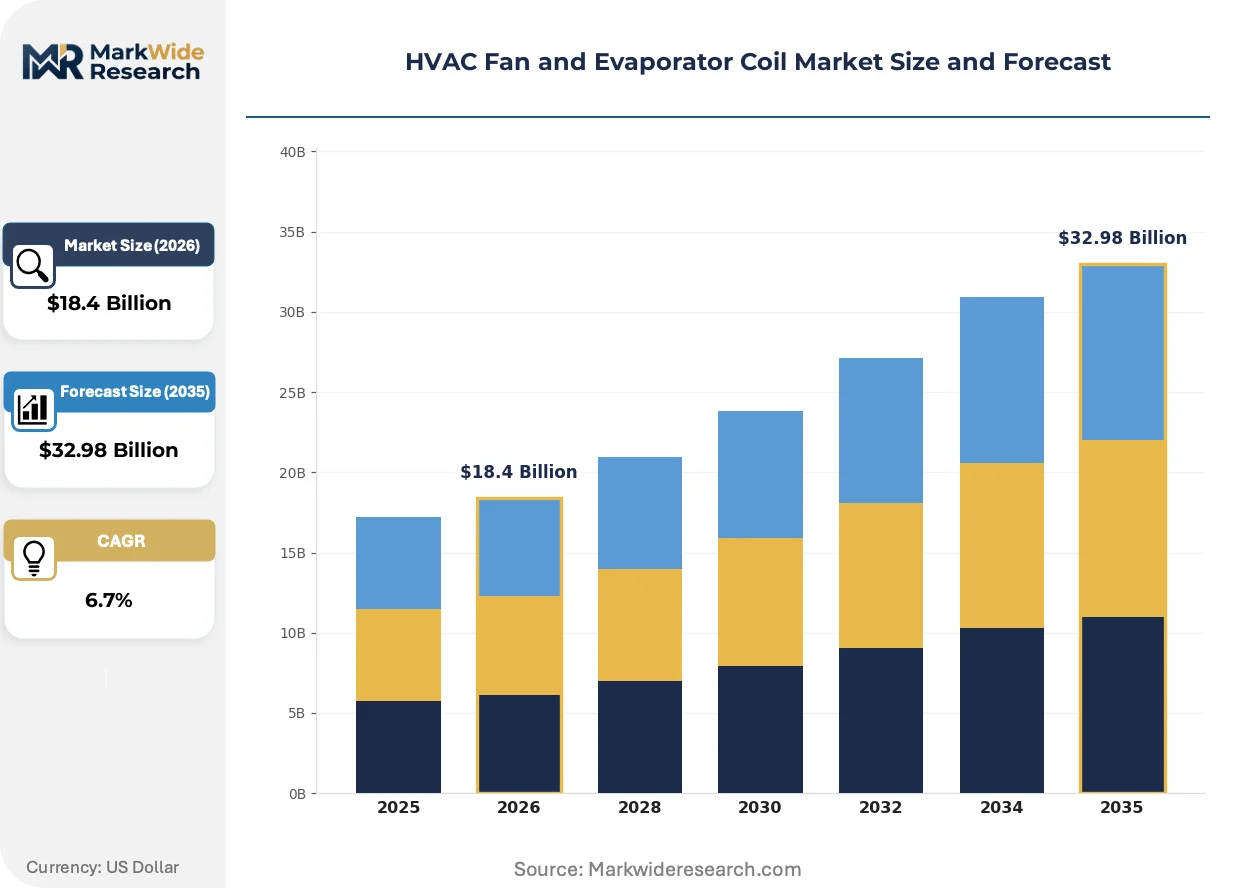
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $32.98 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Direct Expansion Coils, Chilled Water Coils End User: Residential Buildings, Commercial Properties, Industrial Facilities, Data Centers Installation Type: New Construction, Retrofit, Replacement, Maintenance Technology: Variable Speed Drive, Energy Efficient, Standard Efficiency, Smart Controls |
| Companies Covered | Johnson Controls, Mitsubishi Electric, Carrier, York International, Rheem Manufacturing, Trane Technologies, Lennox International, Goodman Manufacturing, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Fan and Evaporator Coil Market Emerging Trajectories
Refrigerant chemistry transitions, coil material substitution, and fan control intelligence are converging to redefine equipment specification criteria across commercial and industrial segments.
Microchannel heat exchanger technology is automating coil manufacturing throughput and refrigerant charge reduction. Data center and rooftop unit specifiers are adopting brazed aluminum platforms at accelerating pace. The technology is automating assembly labor out of coil production while enabling smaller form factors that compress shipping and installation costs.
The EPA's phasedown of HFC refrigerants under the AIM Act is eliminating R-410A and R-134a from new equipment specifications. Coil manufacturers must validate heat transfer performance with A2L mildly flammable alternatives including R-32 and R-454B. Commercial unitary equipment destined for California, New York, and Washington faces the most compressed compliance timelines as state-level regulations advance ahead of federal minimums.
Building owners are consolidating HVAC service procurement under performance-based contracts that unbundle equipment from energy outcome guarantees. Third-party energy service companies are displacing traditional distributor-installer relationships in the healthcare and education verticals. This shift is most pronounced in Germany and the Netherlands where CSRD reporting requirements are forcing facility managers to outsource carbon and cost accountability.
HVAC Fan and Evaporator Coil Market Segmentation
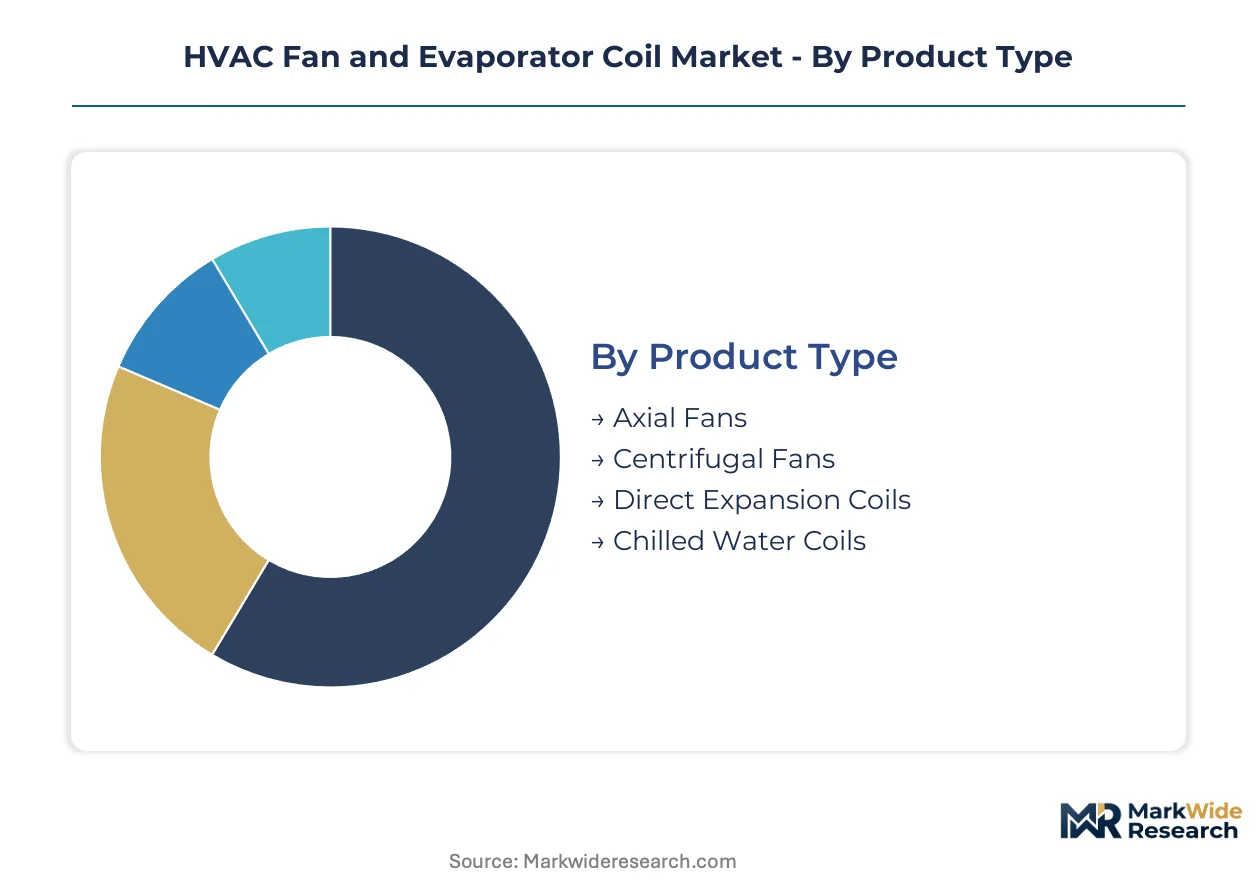
Segmentation in the HVAC fan and evaporator coil market reveals how regulatory pressure and application intensity reshape procurement patterns. Coil chemistry certifications and fan efficacy tiers create divergent compliance burdens across product categories.
Product Type:
EPA Section 608 technician certification applies to all refrigerant-bearing coils, while AMCA certification for fan performance separates commercial-grade from residential specifications. DOE minimum efficiency standards impose tiered testing protocols on centrifugal and axial fan platforms.
- Centrifugal Fans:These assemblies generate static pressure above 2.5 inches water gauge through forward-curved or backward-inclined impeller designs. Demand concentrates in Northern Virginia and Frankfurt hyperscale data centers where rack density requirements exceed 15 kW per cabinet. ASHRAE 90.1 fan efficacy mandates are compressing specification windows for non-VSD configurations.
- Direct Expansion Coils:Round-tube-plate-fin and microchannel architectures circulate refrigerant directly through finned aluminum tubing. China's semiconductor fabrication facilities in Shanghai and Beijing are specifying high-performance DX platforms to meet MEE efficiency mandates. The EPA's AIM Act HFC phasedown is forcing heat transfer validation with A2L alternatives including R-32 and R-454B.
- Axial Fans:Propeller-style impellers deliver high airflow at low static pressure for compact rooftop units and split-system outdoor coils.
- Chilled Water Coils:These heat exchangers circulate facility-generated chilled water rather than refrigerant, eliminating Section 608 handling requirements.
Centrifugal fans sit at the top of the volume ranking, with direct expansion coils climbing the fastest.
End User:
Cost tier stratification separates specification intensity across building categories. Data center operators prioritize thermal performance over first cost, while residential developers face compressed margin structures.
- Data Centers:Hyperscale operators in Singapore and Northern Virginia deploy precision air-handling units with redundant fan arrays and microchannel coils. Rack density trajectories above 20 kW per cabinet are forcing liquid-cooled and hybrid air-handling architectures. California Title 24 stretch codes mandate networked optimization controls.
- Commercial Properties:Class A office stock in Shanghai, Mumbai, and Dubai specifies variable-air-volume systems with VSD-equipped centrifugal fans. Germany's CSRD reporting requirements are consolidating service procurement under performance-based contracts with energy outcome guarantees.
- Industrial Facilities:Process cooling and warehouse climate control drive demand for heavy-duty coil coatings and corrosion-resistant fin stock.
- Residential Buildings:Split-system heat pumps and central air conditioners dominate unit volumes with standardized efficiency tiers.
Data centers command the steepest expansion trajectory, with commercial properties maintaining the largest installed base.
Installation Type:
Application context determines margin structure and technical complexity. New construction permits optimized system design, while retrofit faces legacy constraint integration.
- New Construction:Greenfield projects in China's Tier-2 cities and India's industrial corridors specify integrated fan-coil packages from ground-up design. MEE and CEA efficiency mandates accelerate high-performance platform adoption. Integrated design eliminates ductwork static pressure mismatches.
- Replacement:Drop-in coil and fan swaps address end-of-life equipment without structural modification. Existing refrigerant line sets and ductwork profiles constrain specification flexibility. Inventory stranding risk rises for coils pre-charged with phasedown-scheduled HFC chemistries.
- Retrofit:Building envelope and mechanical system upgrades require custom engineering to match legacy infrastructure.
- Maintenance:Coil cleaning, fan balancing, and refrigerant recovery services extend equipment operational life.
New construction captures the highest average transaction value, with replacement generating the most unit volume.
Technology:
Supply concentration in VSD and smart control platforms is restructuring competitive positioning. Component sourcing from Chinese and German drive manufacturers shapes availability.
- Variable Speed Drive:Electronically commutated motors and inverter-driven induction platforms enable part-load optimization. DOE fan efficacy standards and ASHRAE 90.1 updates mandate VSD penetration in commercial installations above specified horsepower thresholds. Frankfurt and Singapore data centers specify redundant VSD arrays.
- Smart Controls:Networked sensors and building management system integration enable demand-responsive operation. California Title 24 and New York stretch codes mandate automated fault detection and diagnostic capabilities. Third-party energy service companies attach sensor revenue streams.
- Energy Efficient:Premium efficiency motors and enhanced fin geometries meet but do not exceed baseline regulatory requirements.
- Standard Efficiency:Fixed-speed platforms with conventional motor technologies serve price-sensitive replacement segments.
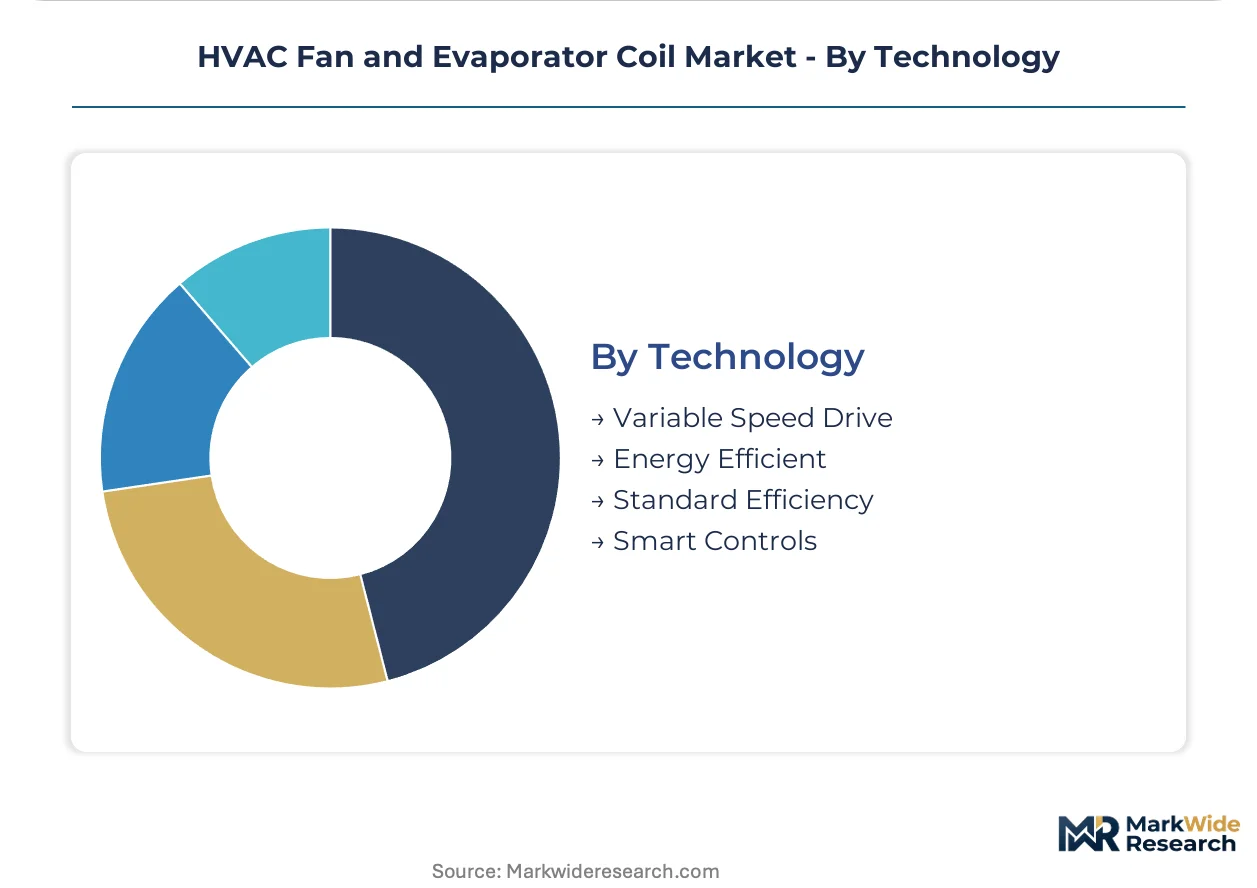
Variable speed drive platforms anchor current volume leadership, with smart controls gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's hyperscale data center corridor anchors global demand for high-static-pressure centrifugal fan arrays and microchannel coil assemblies. Frankfurt's Mainova district and Singapore's Tuas industrial zone replicate this infrastructure intensity. Local efficiency mandates and refrigerant transition timelines create divergent specification pressures across national markets.
United States
Northern Virginia's data center buildout consumes precision air-handling units with redundant fan configurations. The EPA's AIM Act HFC phasedown compresses R-410A coil inventory windows ahead of California's Title 24 stretch codes. Dallas-Fort Worth semiconductor fabrication facilities specify A2L-validated heat exchangers for cleanroom climate control.
China
Shanghai and Beijing semiconductor fabs drive demand for high-performance direct expansion coils under MEE efficiency mandates. The country's dual carbon goals accelerate aluminum microchannel adoption in commercial rooftop units. Yangtze River Delta manufacturing clusters integrate captive fin stock rolling with coil assembly operations.
Germany
Frankfurt's banking and data center verticals specify VSD-equipped centrifugal fans under CSRD reporting requirements. The EU F-Gas Regulation forces refrigerant chemistry transitions ahead of federal US timelines. Bavaria's industrial corridor concentrates chiller and air-handling unit procurement under performance-based energy service contracts.
India
Telangana and Karnataka electronics manufacturing clusters drive precision cooling demand for semiconductor packaging facilities. The CEA's efficiency mandates and PLI scheme for white goods open specification windows for low-GWP coil platforms. Delhi-NCR commercial real estate buildout concentrates variable-air-volume system deployments.
Singapore
Tuas industrial zone and digital infrastructure investments anchor Southeast Asian demand for high-density cooling solutions. The country's carbon tax regime accelerates smart control integration in commercial building retrofits. Biomedical manufacturing clusters in one-north specify redundant coil and fan configurations for continuous process cooling.
HVAC Fan and Evaporator Coil Market Vendor Landscape
Backward integration into compressor and coil production dominates the current landscape as manufacturers seek margin protection against aluminum and copper volatility. The vendor base structures across three tiers: integrated HVAC system houses with captive component production, specialized coil and fan fabricators serving original equipment channels, and regional assemblers dependent on merchant fin stock supply. Strategic archetypes include vertical integrators controlling upstream material conversion, technology licensors of microchannel brazing processes, and scale-driven commodity suppliers. M&A activity concentrates on coil technology specialists and VSD control platform acquisitions.
Among integrated system houses, Carrier and Daikin Industries exemplify the vertical integration archetype through captive supply of heat exchange components. Trane Technologies occupies a position within the premium-tier specification channel for data center and commercial building applications. These anchors represent divergent geographic emphases: North American market penetration, Asia-Pacific manufacturing scale, and European energy service contracting integration.
| Leading Market Players |
|---|
| Johnson Controls |
| Mitsubishi Electric |
| Carrier |
| York International |
| Rheem Manufacturing |
| Trane Technologies |
| Lennox International |
| Goodman Manufacturing |
| Daikin Industries |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between AMCA-validated commercial centrifugal fans and uncertified residential axial units manifests in both component sourcing economics and buyer procurement behavior. Premium-tier manufacturers source aluminum fin stock from captive Yangtze River Delta rolling operations while commodity assemblers draw from merchant Chinese supply exposed to tariff volatility.
Pricing Analysis
Input-cost pass-through from LME aluminum and copper fluctuations compresses margin predictability for non-integrated coil fabricators. Pricing stratifies across premium A2L-validated microchannel platforms, standard-efficiency round-tube-plate-fin configurations, and economy-tier fixed-speed residential units. Cost compression in the standard tier is intensifying because Chinese MEE efficiency mandates are accelerating high-performance specification. Data center operators exhibit the lowest price sensitivity while residential replacement buyers face the most constrained procurement budgets.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center demand in Northern Virginia and Singapore, while distributor networks serve fragmented commercial replacement markets. Manufacturing concentrates in China, Germany, and the United States. Raw material flows draw from Chinese primary aluminum, Chilean copper cathode, and German electrical steel. Single-source vulnerability in Chinese rolled aluminum fin stock exposes non-integrated assemblers to logistics disruption. Distribution runs through OEM captive supply, specialized HVAC distributors, and third-party energy service companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC fan and evaporator coil market functions as a geographic-arbitrage play where India's CEA efficiency mandates and PLI subsidies create cost-advantaged manufacturing against China's tightening environmental compliance burdens.
For Market Incumbents: Extend backward integration into aluminum fin stock rolling to defend against Chinese supply concentration and tariff exposure. Carrier and Daikin Industries exemplify this captive supply model. Prioritize A2L refrigerant validation investment ahead of California Title 24 and EPA AIM Act compliance deadlines to avoid inventory stranding. For New Entrants and Emerging Players: Mid-tier commercial property owners in India's Delhi-NCR corridor represent an underserved buyer archetype seeking performance-based energy service contracts rather than traditional equipment procurement. Microchannel coil technology licensing from German or Japanese patent holders offers a differentiated entry path. Target specification windows opened by India's cooling action plan efficiency mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where coil fabrication technology and VSD control platform capabilities fragment across regional assemblers unable to fund refrigerant transition R&D. Long-term viability favors acquirers of brazed aluminum microchannel specialists and smart control sensor platforms. Monitor EPA Section 608 technician certification expansion as an inflection indicator for field service capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Fin Stock | Captive Yangtze River Delta rolling capacity insulates margin structure against LME volatility. |
| A2L Refrigerant Validation Investment | EPA AIM Act and California Title 24 compliance requires heat transfer performance certification. |
| Microchannel Technology Licensing | German and Japanese patent holders enable coil charge reduction and form factor compression. |
| Smart Control Platform Acquisition | California Title 24 mandates networked fault detection and diagnostic capabilities. |
| Performance-Based Service Contract Expansion | Germany's CSRD reporting requirements consolidate procurement under energy outcome guarantees. |
Methodological Framework
Bottom-up data center and commercial building modeling reconciled against top-down aluminum fin stock and copper tube supply tracking forms the analytical core of this study. Primary interviews with HVAC OEM procurement directors, coil fabrication plant managers, EPA regulatory affairs specialists, and energy service company contracting officers combined with secondary validation from DOE efficiency standard filings, EPA SNAP rulemaking dockets, and AMCA certification databases. Triangulation across stakeholder perspectives and published regulatory timelines ensures segmentation integrity.
Input-output matrices linking refrigerant chemistry transitions, coil material substitution rates, and fan efficacy tier migrations drive volume and value projections across the analysis window. Segmentation dimensions include product architecture, end-use intensity, installation context, and control technology sophistication. CAGRs derive from regression against historical efficiency standard adoption curves and refrigerant phasedown timelines. Forecast inputs incorporate MEE mandate acceleration in China and CEA efficiency trajectory in India.
Underlying measurement precision varies by segment; data center specification volumes carry tighter precision than fragmented residential replacement flows. Forecasts reflect assumptions regarding refrigerant transition friction, aluminum substitution velocity, and tariff regime stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
HVAC System Analyzer Market