
 Agriculture Sprayers Market | 2026-2036
Agriculture Sprayers Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Sprayers Market Intelligence
Brazilian equipment manufacturing capacity is hardening as domestic foundries and hydraulic component makers expand output for tractor-mounted systems. Deere & Company leverages its integrated precision agriculture platform to bundle sprayers with subscription-based guidance software. AGCO Corporation sustains European market presence through Fendt-branded high-clearance sprayers engineered for narrow vineyard rows. Kubota Corporation anchors Asian demand with compact units tailored to Japan's fragmented rice paddy terrain.
Agriculture sprayers are pressurized application machines engineered to deliver crop protection chemicals, liquid fertilizers, and growth regulators at flow rates between 0.5 and 30 gallons per acre, with boom widths spanning 40 to 150 feet on ground units and payload capacities reaching 800 gallons on self-propelled models. Their primary commercial purpose is uniform, calibrated distribution of agrochemicals to maximize biological efficacy while minimizing off-target movement and input waste. Tractor-mounted sprayers occupy the dominant revenue position given their compatibility with existing farm power fleets across mid-scale operations. Drone sprayers represent the fastest-expanding technology segment as Chinese manufacturers drive down unit costs and regulators in Australia and Brazil create beyond-visual-line-of-sight frameworks for aerial application. Electric sprayers are gaining traction in European vineyards where noise restrictions and diesel phase-out timelines tighten operational constraints.
The EPA governs nozzle drift labeling under the Federal Insecticide, Fungicide, and Rodenticide Act, compelling manufacturers to validate droplet spectra through wind tunnel testing before claiming reduced-drift status. The EU Green Deal's Farm to Fork strategy targets 50% pesticide reduction, forcing sprayer makers to engineer ultra-low-volume systems and real-time variable-rate controls that apply chemicals only where sensors detect active pest pressure or weed infestation. Stakeholders must monitor how Brazil's ANVISA re-registration requirements for glyphosate formulations reshape nozzle and tank-mix compatibility specifications across Latin American supply chains.
Market Dynamics
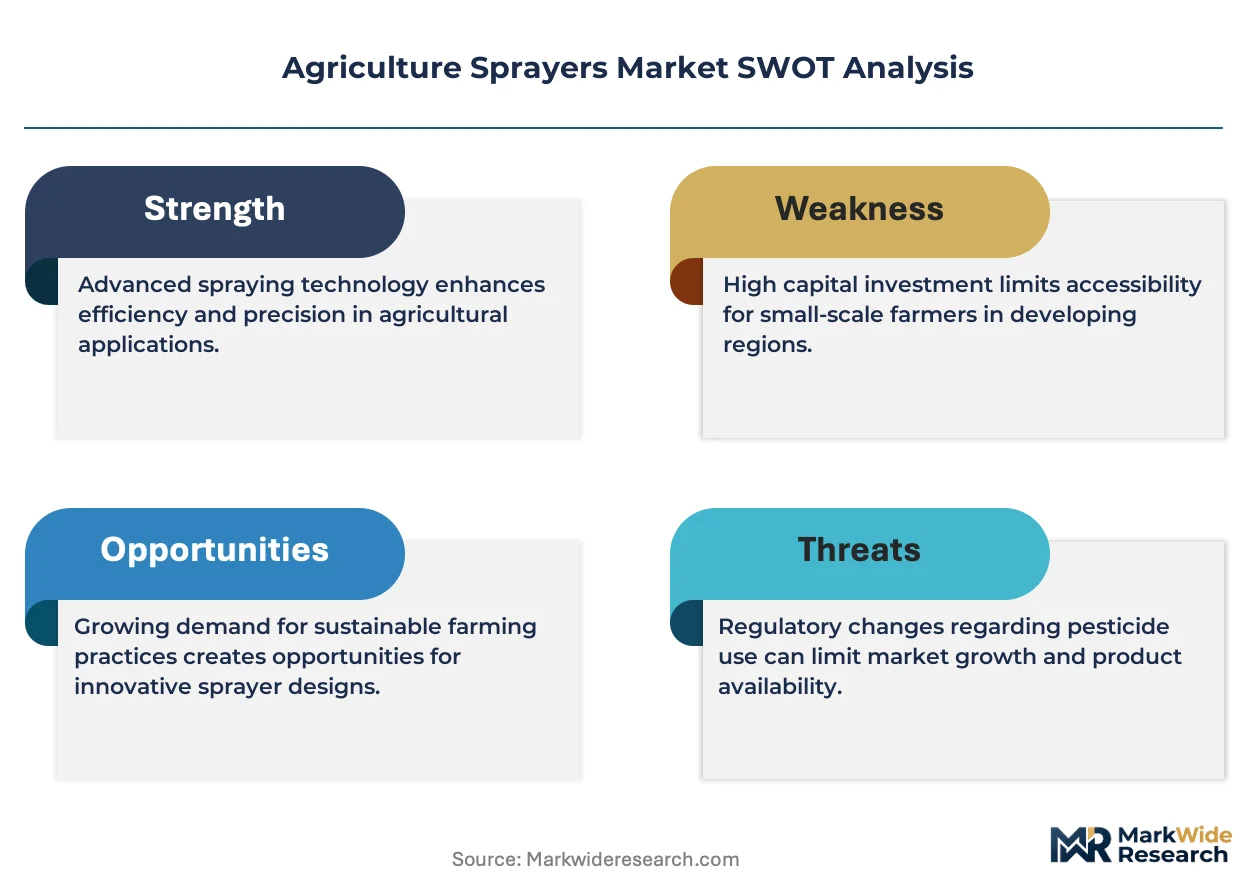
Precision agriculture platforms are compressing equipment replacement cycles as sensor-guided variable-rate application becomes the baseline expectation for crop input efficiency. This structural shift is forcing sprayer manufacturers to embed real-time data connectivity and automated boom section control as standard features rather than premium options.
Growth Catalysts
- EPA Drift Reduction Mandates:The EPA's revised nozzle certification requirements under FIFRA are compelling fleet operators to upgrade to wind tunnel-validated low-drift systems, creating replacement demand across existing installed bases.
- Brazilian Soybean Belt Mechanization:Large-scale farming operations in Mato Grosso are expanding self-propelled sprayer fleets to cover vast contiguous acreage with minimal labor input.
- LiDAR and multispectral sensing convergence:Real-time weed detection systems are enabling spot-spray application that reduces chemical volumes by targeting only infested zones.
Market Restraints
- Steel and aluminum input volatility:Boom fabrication and tank manufacturing face margin pressure from fluctuating commodity metal prices sourced through concentrated global suppliers.
- ANVISA re-registration timelines:Brazil's extended glyphosate review processes are creating uncertainty in tank-mix compatibility specifications and nozzle selection protocols.
- Drone payload limitations:Battery energy density constraints restrict aerial sprayers to sub-30-liter capacities, limiting economic viability for broadacre row crops.
Strategic Opportunities
- Australian BVLOS regulatory frameworks:Beyond-visual-line-of-sight permissions for agricultural drones are opening aerial application corridors previously restricted to manned aircraft.
- European vineyard electrification:Diesel phase-out mandates in France and Germany are creating demand for battery-electric compact sprayers with zero-emission operation.
- Subscription-based guidance bundling:Equipment-as-a-service models that combine hardware with precision agriculture software are penetrating mid-scale operations seeking to avoid capital outlay.
Industry Challenges
- Precision agriculture technician scarcity:Fleet operators struggle to recruit personnel capable of calibrating sensor arrays, interpreting NDVI data, and troubleshooting CAN bus connectivity issues.
- ISO 16119 compliance certification:Manufacturers face extended testing timelines and documentation burdens to achieve international sprayer safety and environmental performance standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Sprayers Market |
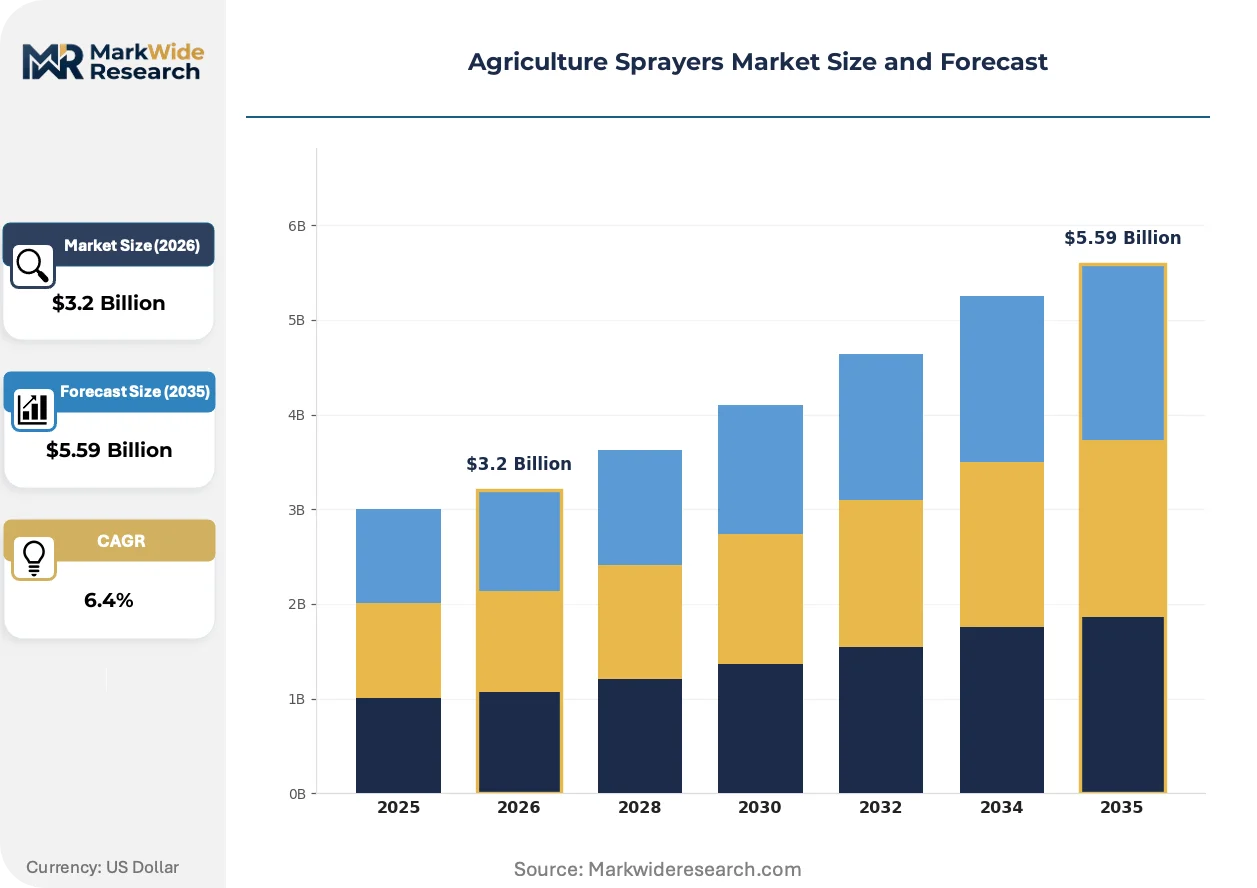
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Sprayers, Backpack Sprayers, Tractor-Mounted Sprayers, Aerial Sprayers Application: Pesticide Application, Fertilizer Spraying, Herbicide Application, Crop Dusting End User: Farms, Agricultural Cooperatives, Retailers, Landscaping Companies Technology: Mechanical Sprayers, Hydraulic Sprayers, Electric Sprayers, Drone Sprayers |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, DJI Technology Co., Ltd., Exel Industries, STIHL AG, Mahindra & Mahindra Ltd, Amazonen-Werke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Sprayers Market Strategic Shifts & Innovations
Autonomous navigation and artificial intelligence are converging to transform sprayer operation from human-driven sequential tasks to continuous unmanned execution. This technological inflection is redrawing competitive boundaries between traditional machinery manufacturers and software-native entrants.
Electrostatic nozzle technology is absorbing market share in specialty crop applications by reducing droplet drift through charged particle attraction to plant surfaces. California almond and grape producers are retrofitting existing booms with electrostatic systems at accelerating rates. This adoption is absorbing conventional hydraulic nozzle demand in high-value permanent crop segments where off-target movement carries severe economic penalties.
The EU Green Deal's Farm to Fork pesticide reduction targets are mandating 50% chemical volume cuts by 2035, forcing equipment redesign toward ultra-low-volume systems. Sprayer manufacturers are engineering pulse-width modulation controls and individual nozzle shutoff to meet these binding constraints. Vineyard and orchard operations across Spain and Italy are retrofitting fleets with variable-rate capabilities to maintain compliance eligibility for CAP subsidies.
Consolidated procurement by agricultural input retailers is displacing direct manufacturer-dealer relationships in North American row crop markets. Co-ops and regional distributors are negotiating fleet-scale sprayer purchases bundled with chemical volume commitments. This channel concentration is most visible across the US Corn Belt, where three input retailers now account for the majority of self-propelled unit placements.
Agriculture Sprayers Market Segmentation
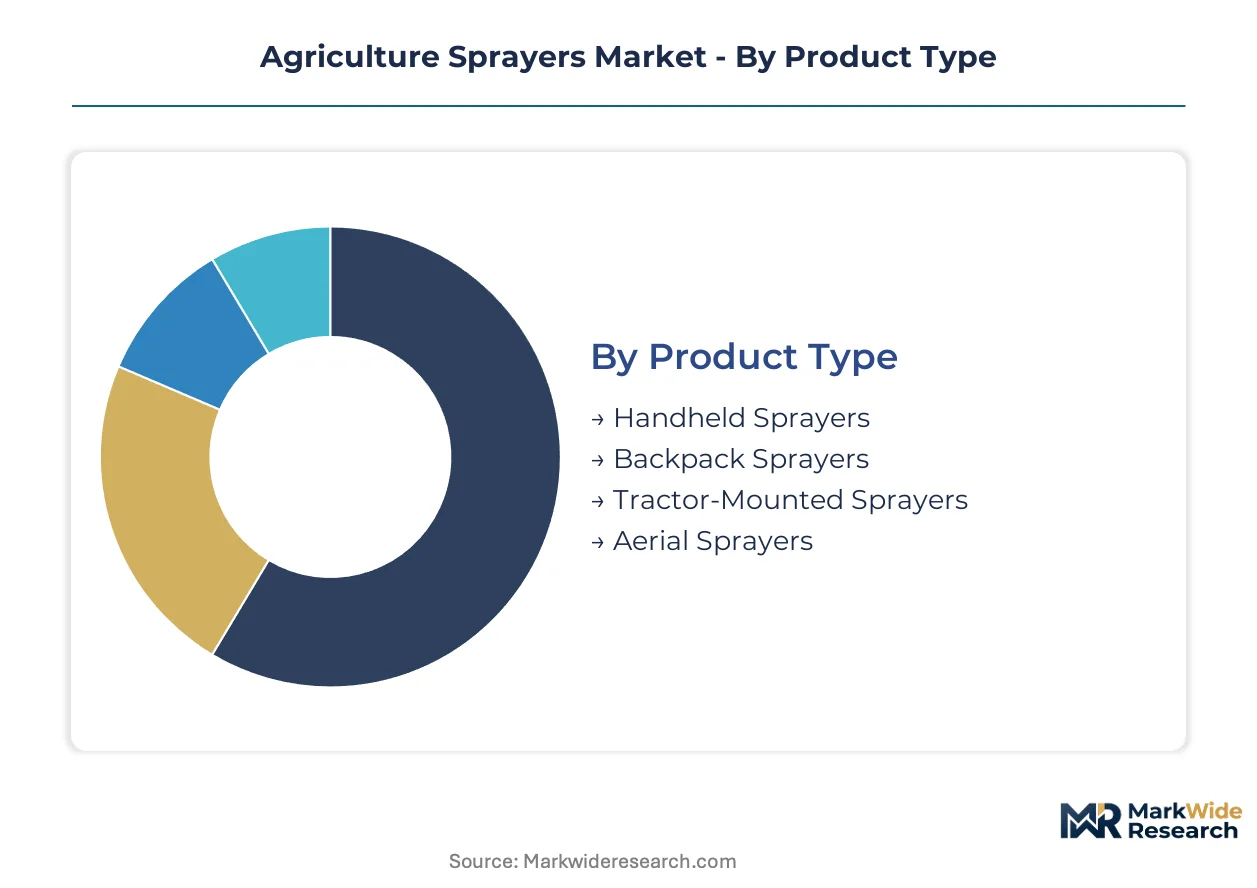
Equipment specification and application context determine sprayer procurement patterns across fragmented agricultural operations. Segmentation reveals how technology adoption splits between established mechanized systems and emerging autonomous platforms.
Product Type:
Volume concentration sits with tractor-compatible systems while premium pricing accrues to specialized aerial units.
- Tractor-Mounted Sprayers:These pressurized systems integrate with existing farm power fleets through three-point hitch or pull-type configurations, delivering 200-1200 gallon tank capacities with boom widths reaching 150 feet. Demand concentrates in Brazil's Mato Grosso soybean belt where large-scale operators require high-acreage daily throughput with minimal labor input. Fleet replacement cycles are compressing as precision agriculture platforms mandate real-time data connectivity as baseline specification.
- Aerial Sprayers:Manned aircraft and unmanned drone systems execute broadcast application over inaccessible or time-sensitive acreage, with payload capacities ranging from 30 liters on battery-electric drones to 800 gallons on fixed-wing agricultural aircraft. Australian and Brazilian regulators are creating beyond-visual-line-of-sight frameworks that expand aerial application corridors previously restricted to manned operations. Payload limitations and battery energy density constraints restrict drone economic viability for broadacre row crops.
- Handheld Sprayers:Portable manual-pressurized units serve smallholder vegetable plots and greenhouse operations with sub-5-gallon capacities.
- Backpack Sprayers:Shoulder-mounted systems dominate Southeast Asian rice paddy applications where terrain fragmentation prevents mechanized access.
Today's leader: Tractor-Mounted Sprayers. Tomorrow's challenger: Aerial Sprayers.
Application:
Input chemistry type dictates nozzle specification, tank material compatibility, and drift mitigation requirements across end-use scenarios.
- Pesticide Application:Insecticide and fungicide delivery demands droplet size control between 150-400 microns to optimize biological efficacy while minimizing off-target movement. California almond and grape producers are retrofitting existing booms with electrostatic systems at accelerating rates to satisfy EPA drift reduction mandates. Electrostatic nozzle technology reduces drift through charged particle attraction to plant surfaces.
- Herbicide Application:Glyphosate and dicamba formulations require coarse droplet spectra to prevent vapor drift damage to susceptible crops, driving demand for air-induction nozzles and pulse-width modulation controls. Brazil's ANVISA re-registration requirements for glyphosate formulations are reshaping tank-mix compatibility specifications across Latin American supply chains. Compatibility uncertainty is delaying fleet upgrade decisions.
- Fertilizer Spraying:Liquid nitrogen and micronutrient application requires corrosion-resistant tank materials and high-flow pump systems.
- Crop Dusting:Dry material broadcast from aerial platforms serves cover crop seeding and desiccant application in remote acreage.
Pesticide and herbicide applications generate equivalent revenue concentration, with fertilizer spraying gaining share fastest through variable-rate precision adoption.
End User:
Procurement scale separates direct agricultural operators from intermediary service providers and amenity managers.
- Farms:Owner-operators and corporate farming enterprises purchase equipment directly through manufacturer-dealer networks or consolidated agricultural input retailers. Co-ops and regional distributors are negotiating fleet-scale sprayer purchases bundled with chemical volume commitments across the US Corn Belt.
- Agricultural Cooperatives:Member-owned purchasing entities aggregate demand to secure volume pricing on self-propelled units, creating channel concentration that displaces direct manufacturer relationships. Three input retailers now account for the majority of self-propelled unit placements in North American row crop markets.
- Retailers:Agricultural input distributors maintain service fleets for custom application services.
- Landscaping Companies:Turf and ornamental managers specify compact units for golf course and municipal park maintenance.
Farms dominate installed base volume. Agricultural cooperatives are consolidating procurement fastest.
Technology:
Power source and control architecture differentiate mature hydraulic systems from emerging electric and autonomous platforms.
- Hydraulic Sprayers:Engine-driven piston and diaphragm pumps deliver consistent pressure across variable terrain, maintaining dominance in large-scale mechanized farming. Deere & Company leverages its integrated precision agriculture platform to bundle hydraulic sprayers with subscription-based guidance software. Real-time data connectivity and automated boom section control are becoming standard rather than premium features.
- Drone Sprayers:Battery-electric unmanned aerial vehicles with GPS-guided autonomous navigation are climbing the fastest as Chinese manufacturers drive down unit costs and regulators expand operational permissions. Payload capacities remain constrained to sub-30 liters, limiting economic viability for broadacre crops while specialty applications accelerate.
- Mechanical Sprayers:Hand-operated and PTO-driven systems serve cost-sensitive smallholder markets.
- Electric Sprayers:Battery-powered compact units are gaining traction in European vineyards where noise restrictions and diesel phase-out timelines tighten operational constraints.
Hydraulic systems anchor current revenue. Drone platforms are expanding most quickly through regulatory enablement and cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as compliance cost differentials between jurisdictions widen. Brazilian and Chinese producers exploit lower certification burdens to serve export markets, while European manufacturers absorb stricter EU Green Deal costs through premium positioning.
United States
California's Central Valley specialty crop producers are expanding precision spraying fleets to satisfy EPA drift reduction mandates under FIFRA. The EPA's wind tunnel-validated nozzle certification requirements are compelling fleet operators to upgrade existing installed bases. Fresno County almond growers are retrofitting electrostatic systems at accelerating rates to minimize off-target movement penalties.
Brazil
Mato Grosso soybean belt operations are expanding self-propelled sprayer fleets to cover vast contiguous acreage with minimal labor input. ANVISA's extended glyphosate re-registration timelines are creating uncertainty in tank-mix compatibility specifications and delaying fleet upgrade decisions. Domestic foundries and hydraulic component makers in São Paulo state are expanding output for tractor-mounted systems.
Germany
Diesel phase-out mandates are creating demand for battery-electric compact sprayers with zero-emission operation in vineyard applications. The EU Green Deal's Farm to Fork strategy targets pesticide reduction, forcing equipment redesign toward ultra-low-volume systems. Baden-Württemberg's precision agriculture equipment cluster is engineering pulse-width modulation controls for compliance-bound exports.
China
Domestic manufacturers are driving down drone sprayer unit costs through scale economies in Shenzhen and Dongguan electronics corridors. The country's dual carbon goals are accelerating battery-electric platform development for agricultural machinery. Yangtze River Delta component suppliers are capturing share in Asian aftermarket nozzle and pump replacement cycles.
Australia
Beyond-visual-line-of-sight regulatory frameworks are opening aerial application corridors previously restricted to manned aircraft. The TGA's alignment with agricultural chemical registration protocols supports precision spraying adoption in broadacre wheat belts. Queensland cotton producers are piloting LiDAR-guided spot-spray systems to reduce chemical volumes through real-time weed detection.
Agriculture Sprayers Market Key Industry Players
North American and European producers anchor the premium tier with integrated precision agriculture platforms; Chinese specialists hold the volume-driven drone segment through cost compression. The vendor base splits between consolidated machinery conglomerates with full-line portfolios and focused component specialists. Three archetypes dominate: full-line agricultural equipment manufacturers, unmanned aerial system pure-plays, and precision nozzle technology specialists. Capacity expansion in Brazilian foundries and strategic partnerships for software bundling represent the dominant competitive vectors.
Among diversified machinery conglomerates, Deere & Company and CNH Industrial N.V. exemplify the integrated platform archetype, while DJI Technology Co., Ltd. occupies a position within the unmanned aerial system tier. AGCO Corporation and Kubota Corporation represent regional market anchoring strategies through brand-specific configurations. Mahindra & Mahindra Ltd. sits within the emerging market tractor-mounted segment. Exel Industries and Amazonen-Werke exemplify European specialist positioning, while STIHL AG represents compact equipment diversification.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| DJI Technology Co., Ltd. |
| Exel Industries |
| STIHL AG |
| Mahindra & Mahindra Ltd |
| Amazonen-Werke |
| Others |
Cost & Logistics Intelligence
Precision agriculture technician concentration in Germany's Baden-Württemberg engineering cluster feeds directly into pricing-tier spreads, as labor-cost differentials between European specialist manufacturers and Brazilian volume producers create three distinct equipment positioning levels.
Pricing Analysis
Distributor margin structures in North American row crop markets favor consolidated agricultural input retailers negotiating fleet-scale purchases bundled with chemical volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates subscription-bundled precision platforms from bare-metal hydraulic units and Chinese-manufactured drone systems. Cost compression in economy-tier drone sprayers is intensifying because Shenzhen electronics corridors drive down battery and GPS module costs. Smallholder operators in Southeast Asian rice paddies exhibit highest price sensitivity, while California almond growers demonstrate lowest sensitivity due to off-target movement penalty exposure.
Supply Chain Analysis
Hydraulic pump and precision nozzle supply rests on German fluid engineering specialists, Chinese casting foundries, and Brazilian São Paulo-state component makers expanding output for tractor-mounted systems. Critical inputs include corrosion-resistant tank alloys, pulse-width modulation controllers, and wind tunnel-validated low-drift nozzle assemblies. Single-source vulnerability concentrates in European electrostatic charging system suppliers serving California specialty crop retrofits. Distribution runs through manufacturer-dealer networks for premium integrated platforms and consolidated co-op purchasing entities for mid-scale fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's ANVISA re-registration timeline uncertainty against Australia's TGA beyond-visual-line-of-sight regulatory clarity creates a geographic-arbitrage opportunity for equipment positioning and manufacturing footprint decisions.
For Market Incumbents: Extend precision agriculture software bundling into subscription-based equipment-as-a-service models to counter Chinese drone pure-plays driving unit cost compression. Secure backward integration into São Paulo-state hydraulic component capacity to defend margin position against domestic Brazilian foundry expansion. Prioritize ISO 16119 compliance certification investment to maintain European market access under tightening EU Green Deal enforcement timelines. For New Entrants and Emerging Players: Autonomous navigation software stacks offer entry wedge into Australian broadacre wheat belt operations where BVLOS permissions expand aerial application corridors. Target vineyard electrification demand in France's diesel phase-out zones as the most penetrable segment. Pursue co-development partnerships with Yangtze River Delta battery suppliers to bypass established hydraulic system incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among unmanned aerial system pure-plays facing payload limitation constraints against manned aircraft scale advantages. Long-term viability favors precision nozzle technology specialists with electrostatic retrofit capabilities serving California permanent crop markets. Watch ANVISA glyphosate re-registration resolution as inflection indicator for Latin American fleet upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Deere's subscription bundling with guidance software locks in mid-scale operator retention. |
| Electrostatic Nozzle Retrofit Programs | California almond growers accelerate adoption to satisfy EPA FIFRA drift reduction mandates. |
| Battery-Electric Compact Sprayer Development | German vineyard electrification responds to diesel phase-out timelines in Baden-Württemberg. |
| Beyond-Visual-Line-of-Sight Regulatory Engagement | Australian TGA frameworks expand aerial application corridors for Queensland cotton producers. |
| Domestic Foundry Capacity Expansion | São Paulo hydraulic component makers harden Brazilian supply chains against import volatility. |
Research Approach
Direct dialogue with precision agriculture equipment engineers, fleet maintenance directors at Mato Grosso soybean operations, EPA compliance officers, and European vineyard managers grounded qualitative findings in operational reality. Secondary validation drew from EPA FIFRA nozzle certification databases, ANVISA glyphosate registration filings, EU Green Deal Farm to Fork strategy documents, and Australian TGA aerial application regulatory notices. Bottom-up equipment shipment tallies and top-down agricultural input expenditure estimates were triangulated to anchor market sizing.
Bottom-up modeling traced unit economics across tractor-mounted, aerial, and handheld sprayer categories, while top-down analysis calibrated against national agricultural machinery import data and co-op procurement disclosures. Segmentation dimensions spanned product type, application chemistry, end-user procurement scale, and power source technology. CAGRs were derived from equipment replacement cycle compression rates and regulatory mandate implementation schedules. Forecast inputs incorporated LiDAR sensor cost curves and battery energy density improvement trajectories.
The model holds under steady regulatory implementation timelines; deviation in ANVISA re-registration resolution or EPA drift mandate enforcement intensity would shift replacement demand timing. Forecasts reflect assumptions about precision agriculture technician availability and Chinese drone export pricing stability. A small set of named triggers—BVLOS regulatory expansion pace, EU pesticide reduction binding targets, and Brazilian domestic content requirements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Driverless Tractor Market