
 South America Agrochemicals Market | 2026-2036
South America Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agrochemicals Market Analytics
Direct-to-farm distribution in Brazil is tilting toward consolidated ag-retail networks with embedded agronomic services. Bayer AG leverages its seed-chemistry integration to sustain channel control across Mato Grosso soybean belts. Syngenta Group anchors its position through digital farming platforms bundled with crop protection packages. UPL Ltd. competes via generic herbicide portfolios priced for mid-scale Brazilian cooperatives.
Agrochemicals comprise synthetic and biological substances formulated for crop protection and plant nutrition, including active ingredients such as glyphosate, neonicotinoids, and NPK compounds manufactured through chemical synthesis or fermentation processes. These inputs serve to control weeds, pests, and diseases while optimizing yield output in commercial agriculture. Herbicides command the largest product-type revenue pool given soybean monoculture dependency across Brazil and Argentina, while liquid formulations capture share from granular alternatives due to precision application compatibility with drone and self-propelled sprayer fleets. Fertilizer demand concentrates in high-phosphorus blends for Paraguay's expanding corn-soy rotations.
ANVISA in Brazil and SENASA in Argentina govern maximum residue limits and product re-registration cycles, forcing reformulation toward lower-toxicity active ingredients. ANMAT in Argentina and Colombia's ICA administer import permits that delay market entry for novel molecules. REACH-equivalent frameworks remain fragmented across Mercosur, complicating multi-country registration strategies. Stakeholders must monitor regulatory divergence between national agencies to anticipate product pipeline viability and portfolio rebalancing requirements.
Market Dynamics
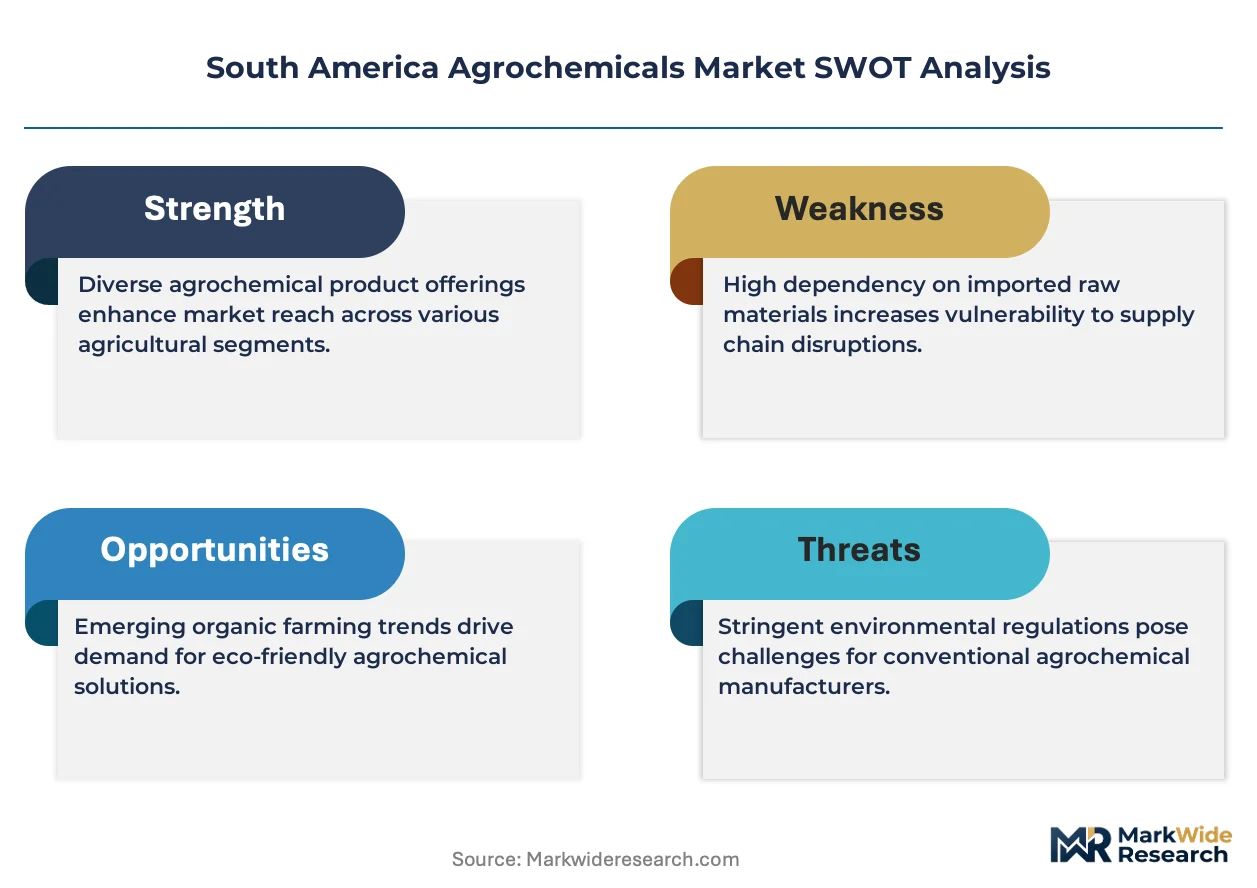
IBAMA's tightened pesticide registration requirements in Brazil are compressing product pipeline timelines and forcing active ingredient reformulation toward lower-toxicity chemistries across the region's largest agrochemical consumer.
Growth Catalysts
- Herbicide intensity in Brazilian soybean belts:Glyphosate-resistant weed proliferation is accelerating tank-mix complexity and per-hectare application volumes in Mato Grosso and Goiás states.
- ANVISA residue limit harmonization:Brazil's national health surveillance agency is aligning maximum residue limits with Codex standards, enabling export crop certification for EU-bound soy and corn shipments.
- Precision application hardware penetration:Self-propelled sprayer fleets with pulse-width modulation nozzles are expanding addressable market for liquid formulation herbicides and fungicides.
Market Restraints
- Active ingredient import concentration:Chinese-manufactured glyphosate technical and neonicotinoid intermediates dominate Brazilian formulator supply, creating foreign exchange and tariff exposure.
- SENASA re-registration bottlenecks:Argentina's national food safety and quality service mandates multi-year toxicological review cycles that stall novel molecule commercialization.
- Biological substitution pressure:Bacillus-based biofungicides and entomopathogenic nematodes are capturing specialty crop segments in Chile's Central Valley, eroding synthetic share in high-value horticulture.
Strategic Opportunities
- Paraguay's corn-soy frontier expansion:Eastern Paraguay's mechanized row-crop conversion is generating first-time fertilizer and herbicide demand from previously pasture-dominated land.
- Digital agronomy bundling:Variable-rate prescription platforms paired with crop protection packages are penetrating mid-scale Argentine cooperatives in Buenos Aires province.
- Biopesticide registration fast-tracks:Brazil's CONAMA resolution 492 creates accelerated pathways for microbial and botanical active substances, shortening time-to-market versus synthetics.
Industry Challenges
- Formulation chemist scarcity:Brazil's specialized workforce for adjuvant and controlled-release fertilizer engineering remains concentrated in São Paulo's industrial corridor, constraining regional production scale-up.
- Multi-country registration coordination:Mercosur's fragmented REACH-equivalent frameworks force redundant toxicological dossier preparation for Brazil, Argentina, and Paraguay markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agrochemicals Market |
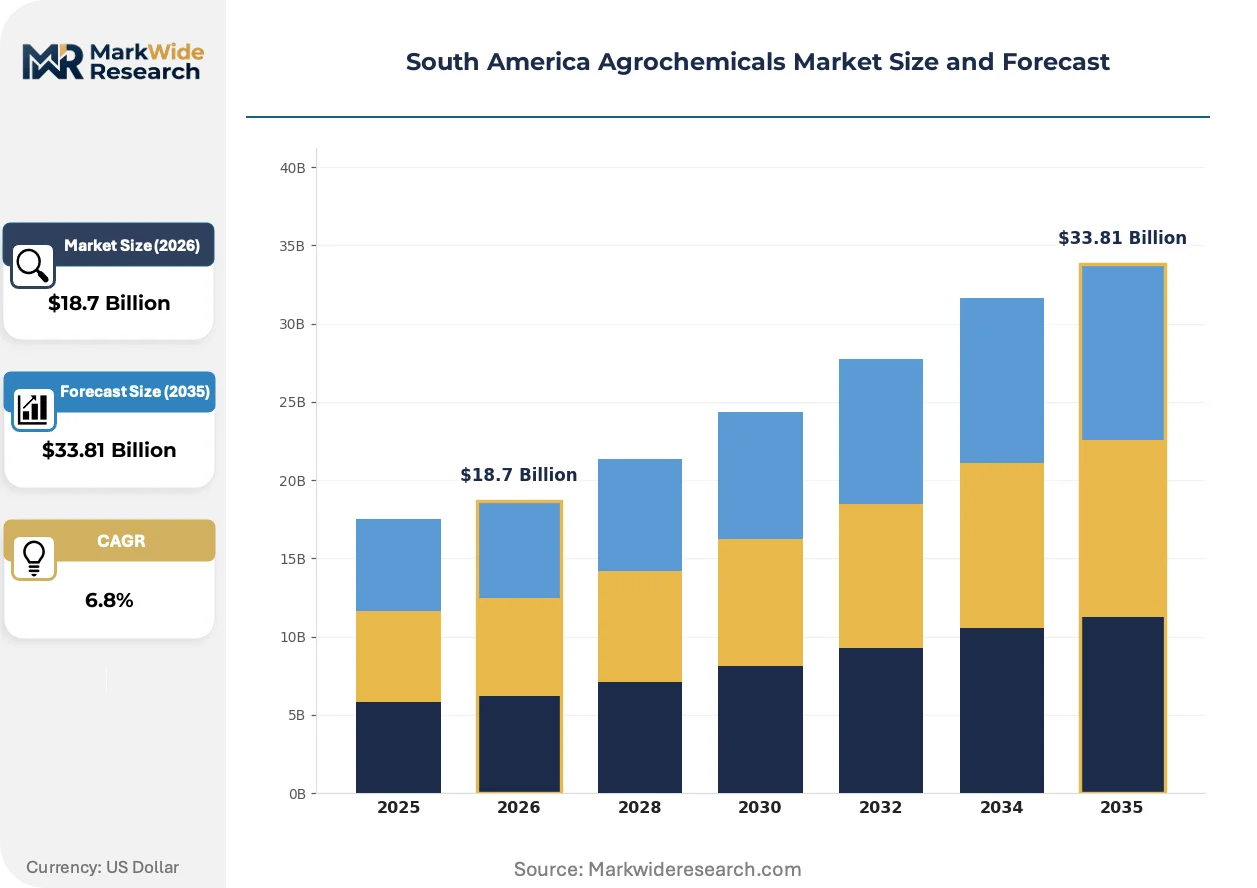
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Fertilizers End Use Industry: Crops, Horticulture, Turf & Ornamental, Forestry Formulation Type: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | BASF SE, Corteva Agriscience, FMC Corporation, Bayer AG, Syngenta Group, ADAMA Agricultural Solutions Ltd., UPL Ltd., Nufarm, Yara International, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agrochemicals Market Evolving Landscape
Biological-synthetic co-formulation is disrupting traditional chemistry-first portfolios, while regulatory compression and distribution consolidation are rewriting go-to-market economics across the Southern Cone.
RNA interference crop protection is hybridizing conventional insecticide modes of action. Bayer and Syngenta field trials in Brazil's Cerrado target fall armyworm and soybean looper through sprayable dsRNA formulations. Large-scale grain operations in Mato Grosso are piloting these chemistries under IBAMA provisional registrations, compressing reliance on pyrethroid and diamide rotations.
ANVISA's updated toxicological re-evaluation schedule is accelerating active ingredient phase-outs. The agency's 2024 priority list targets paraquat and 2,4-D formulations for carcinogenicity reassessment, forcing Brazilian formulators toward glyphosate alternatives and glufosinate-ammonium blends. Soybean seed treatment segments are responding with accelerated neonicotinoid replacement trials using fluopyram and sedaxane combinations.
Ag-retail consolidation is compressing independent distributor margins. Brazil's top five agricultural input cooperatives now control direct-to-farm channels across 60% of planted area in Rio Grande do Sul and Paraná, unbundling technical advisory from product supply. Argentine Pampas operations mirror this shift, with AFA and ACA cooperatives embedding precision agronomists into membership structures, displacing traditional commission-based sales representative networks.
South America Agrochemicals Market Segmentation
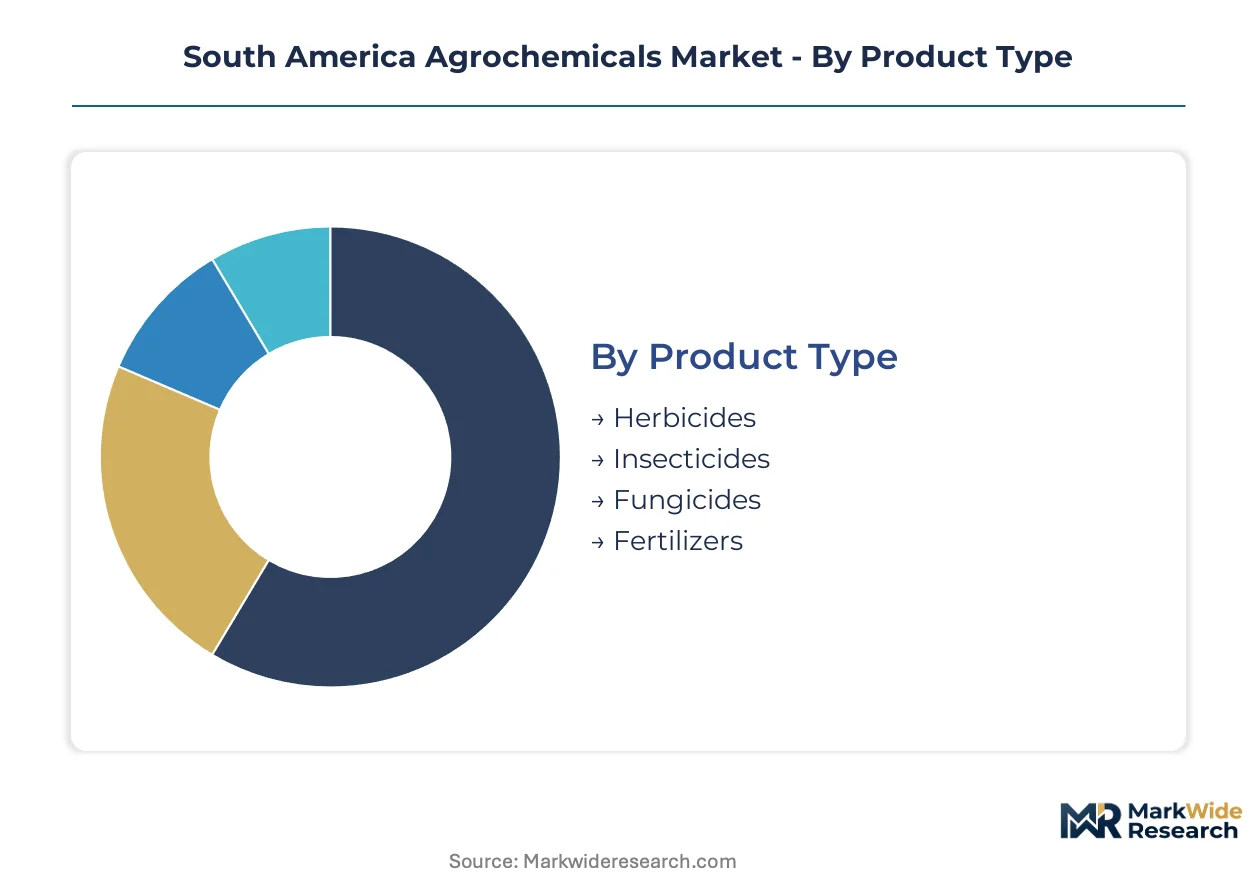
Agrochemical purchasing patterns across the Southern Cone diverge sharply by crop system, application technology, and channel access. Segmentation reveals where formulation investments concentrate and which customer types command pricing power.
Product Type:
Mature chemistries dominate volume, while biological co-formulations emerge fastest.
- Herbicides:Glyphosate, glufosinate-ammonium, and 2,4-D formulations constitute the largest revenue pool, driven by soybean monoculture dependency across Mato Grosso and Goiás. Tank-mix complexity is accelerating with resistant weed proliferation, expanding per-hectare application volumes.
- Fertilizers:NPK compounds and high-phosphorus blends anchor Paraguay's expanding corn-soy rotations. Brazilian formulators are integrating controlled-release coatings to reduce leaching losses in Cerrado sandy soils.
- Insecticides:Neonicotinoid seed treatments face phase-out pressure from ANVISA residue reviews, with diamide and pyrethroid alternatives capturing replacement demand.
- Fungicides:Triazoles and strobilurins protect soybean rust and corn leaf blight in Argentina's Pampas region, where humid summers intensify disease pressure.
Herbicides retain volume leadership; fertilizers hold the steepest expansion curve.
End Use Industry:
Commercial scale determines input intensity, from mechanized row crops to precision-managed specialty systems.
- Crops:Soybean, corn, and wheat operations across Brazil's Center-West and Argentina's Buenos Aires province consume over three-quarters of regional agrochemical volume. Self-propelled sprayer fleets and variable-rate application are standard on farms exceeding 1,000 hectares.
- Horticulture:Chile's Central Valley and São Paulo's protected vegetable belts demand residue-compliant formulations for EU export certification. Biological fungicides and bioinsecticides are penetrating strawberry and tomato systems fastest.
- Turf & Ornamental:Golf course maintenance and urban landscaping in São Paulo and Santiago drive specialty herbicide demand for warm-season grass management.
- Forestry:Eucalyptus and pine plantations across southern Brazil and Uruguay apply aerial-sprayed herbicides for establishment-phase weed control.
Crops command absolute tonnage; horticulture delivers the highest margin per hectare.
Formulation Type:
Liquid formats align with precision hardware, while granular alternatives persist in fertilizer base applications.
- Liquid:Suspension concentrates and soluble liquids dominate Brazilian soybean belts, compatible with pulse-width modulation nozzles and drone sprayers. Formulators are optimizing viscosity for cold-water mixing in Mato Grosso dry-season conditions.
- Emulsifiable Concentrate:Oil-based carriers penetrate waxy weed cuticles in Cerrado grass species, though solvent regulations are tightening under CONAMA resolutions.
- Granular:Controlled-release fertilizer prills remain standard for Paraguay's first-time corn adopters lacking liquid application equipment.
- Powder:Wettable powders persist in smallholder potato and bean systems in Colombia's Andean highlands where water access constrains mixing logistics.
Liquid formulations capture share fastest; granular retains fertilizer dominance.
Distribution Channel:
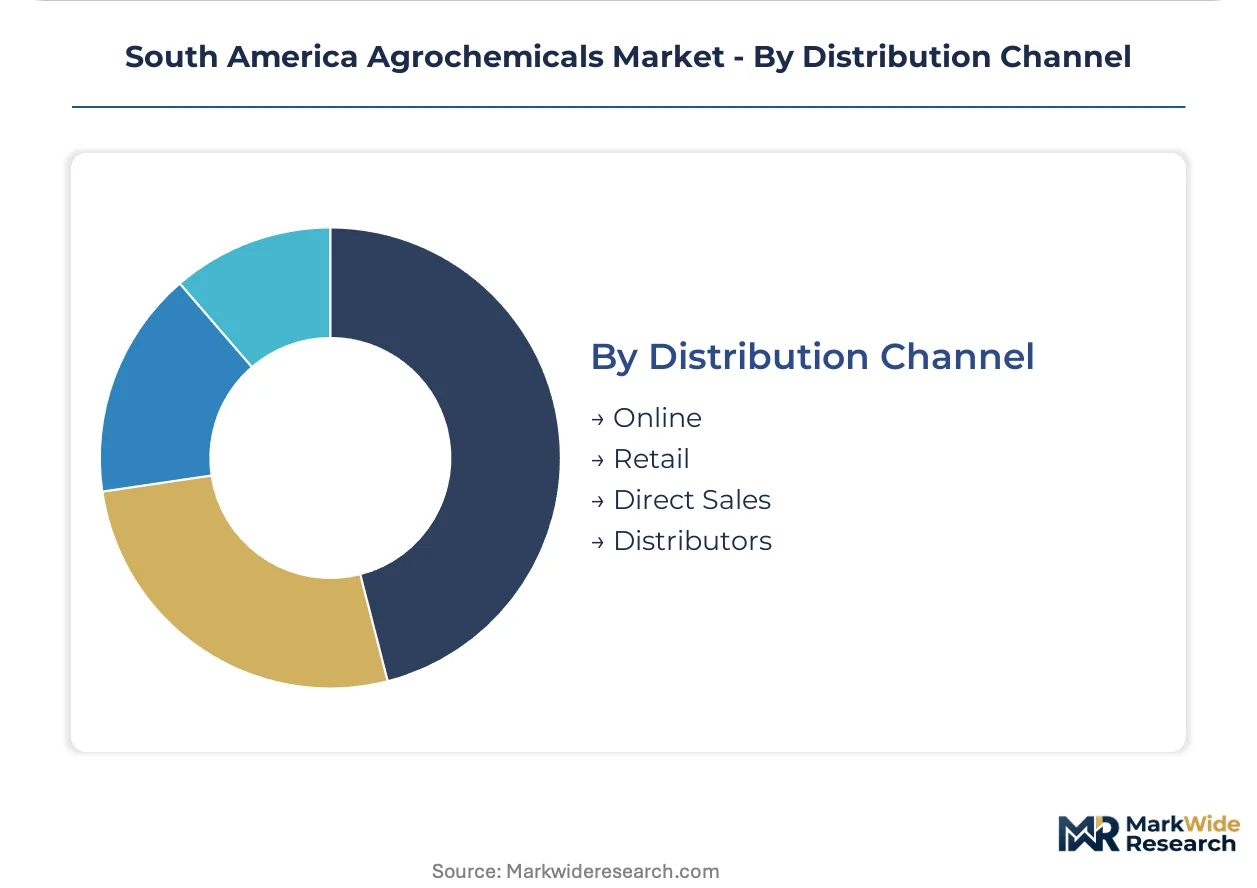
Channel power is consolidating around agronomic service bundling, squeezing transactional intermediaries.
- Direct Sales:Brazil's top five agricultural cooperatives now control 60% of planted area in Rio Grande do Sul and Paraná, embedding precision agronomists into membership structures and displacing commission-based representatives.
- Distributors:Independent ag-retail networks in Argentina's Pampas are consolidating into regional chains with captive formulation blending facilities.
- Retail:Traditional farm supply stores serve smallholders in northeastern Brazil's fragmented cotton and bean systems where cooperative density remains low.
- Online:E-commerce platforms are penetrating mid-scale Brazilian cooperatives for generic herbicide procurement, though technical advisory remains offline.
Direct sales absorb volume leadership; online channels climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paraná-Paraguay waterway and Santos port complex underpin South America's agrochemical trade corridors, channeling formulated products into Brazil's interior soybean belts and Argentine grain terminals.
Brazil
Soybean monoculture across Mato Grosso and Goiás drives glyphosate and glufosinate-ammonium consumption, with resistant weed proliferation accelerating tank-mix complexity. ANVISA's toxicological re-evaluation schedule targets paraquat and 2,4-D for carcinogenicity review, forcing formulators toward alternative chemistries. São Paulo's industrial corridor concentrates adjuvant engineering and controlled-release fertilizer manufacturing, though specialized workforce scarcity constrains regional production scale-up.
Argentina
The Pampas region's large-scale grain operations concentrate fertilizer demand, particularly high-phosphorus blends for corn-wheat rotations. SENASA mandates multi-year toxicological review cycles for novel molecule registration, stalling commercialization timelines for innovative active ingredients. Buenos Aires province hosts AFA and ACA cooperatives embedding precision agronomists into membership structures, displacing traditional commission-based sales networks.
Paraguay
Eastern Paraguay's mechanized corn-soy frontier expansion generates first-time agrochemical demand from previously pasture-dominated land. The country's national agricultural regulator administers import permits that delay market entry for novel molecules. The Alto Paraná and Canindeyú departments concentrate new row-crop conversion, with cooperatives establishing captive formulation blending facilities to serve first-time adopters.
Chile
The Central Valley's specialty horticulture systems demand residue-compliant formulations for EU export certification, with strawberry and tomato operations leading biological fungicide adoption. The country's national food safety authority governs maximum residue limits for export crops. Metropolitan Santiago and surrounding protected vegetable belts host precision-managed operations piloting Bacillus-based biofungicides and entomopathogenic nematodes.
Colombia
Andean highland potato and bean systems persist with wettable powder formulations where water access constrains liquid mixing logistics. The Colombian Agricultural Institute administers import permits and product registration, creating regulatory friction for new entrants. Cundinamarca and Boyacá departments concentrate smallholder production, with traditional farm supply stores serving fragmented cotton and bean systems where cooperative density remains low.
South America Agrochemicals Market Competitive Landscape
On the supply side, the industry is consolidating around integrated seed-chemistry platforms and digital agronomy bundling, with distribution power concentrating in cooperative networks that embed technical advisory into membership structures. Three strategic archetypes dominate: multinational conglomerates with seed-chemistry integration, generic specialists competing on price for mid-scale cooperatives, and regional formulators with captive blending facilities. M&A activity targets cooperative networks with direct-to-farm channel control, while portfolio diversification accelerates toward biological-synthetic co-formulations.
Within the multinational tier, Bayer AG, Syngenta Group, and BASF SE exemplify integrated platform strategies. Bayer leverages seed-chemistry integration to sustain channel control across Mato Grosso soybean belts. Syngenta anchors market position through digital farming platforms bundled with crop protection packages. BASF occupies a position within the specialty formulation segment, with particular strength in fungicide and seed treatment chemistries. These three entities represent contrasting approaches to the region's tightening regulatory environment and consolidating distribution landscape.
| Leading Market Players |
|---|
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| Bayer AG |
| Syngenta Group |
| ADAMA Agricultural Solutions Ltd. |
| UPL Ltd. |
| Nufarm |
| Yara International |
| Others |
Value Network & Pricing Analysis
The Santos port complex anchors South American agrochemical trade corridors, with freight cost volatility from Chinese technical ingredient shipments feeding into tiered pricing structures that separate multinational branded formulations from generic alternatives and concentrate margin pressure on mid-scale Brazilian cooperatives lacking captive blending capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates multinational seed-chemistry bundles from regional formulator portfolios and unbranded generic imports. Price differentiation hinges on agronomic service bundling and ANVISA registration tier, with biological co-formulations commanding certification premiums. Cost compression in the generic tier is intensifying because Chinese glyphosate technical supply faces foreign exchange exposure. Mid-scale Brazilian cooperatives exhibit highest price sensitivity; integrated multinational accounts show lowest.
Supply Chain Analysis
Upstream feedstock dependence draws from Chinese-manufactured glyphosate technical, neonicotinoid intermediates, and Indian-sourced generic active ingredients. Raw material dependencies center on petrochemical-derived adjuvants, phosphate rock for fertilizer base, and fermentation feedstocks for biological actives. Single-source vulnerability concentrates in Chinese technical supply for Brazilian formulators. Distribution runs through consolidated ag-retail cooperatives with embedded agronomic advisory displacing independent commission-based networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity in São Paulo's industrial corridor constrains regional production scale-up, creating competitive advantage for players with captive technical talent pipelines and forcing portfolio decisions toward less labor-intensive biological manufacturing processes.
For Market Incumbents: Pre-empt biological substitution pressure by accelerating RNA interference field trials under IBAMA provisional registrations before diamide and pyrethroid resistance spreads across Mato Grosso soybean belts. Anchor channel control through precision agronomist embedding in cooperative membership structures, displacing commission-based representative networks before generic competitors replicate the service bundling model. For New Entrants and Emerging Players: Eastern Paraguay's first-time corn-soy adopters lacking liquid application equipment represent the most penetrable entry point for granular fertilizer and wettable powder herbicide portfolios. Chile's Central Valley strawberry and tomato operations seeking EU export certification offer biological fungicide white-space with lower registration barriers than Brazilian synthetics. Pursue fast-track CONAMA resolution 492 pathways for microbial active substances to compress time-to-market versus ANVISA synthetic reviews. For Investors and Strategic Acquirers: Regional formulators with captive blending facilities in Alto Paraná and Canindeyú departments offer acquisition exposure to Paraguay's mechanized frontier expansion without Brazilian regulatory complexity. Long-term viability rests on biological-synthetic co-formulation capability buildout and cooperative network channel control. Watch ANVISA's paraquat and 2,4-D phase-out timeline as inflection indicator for glufosinate-ammonium and alternative chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Reduces Chinese technical supply dependence and foreign exchange exposure for Brazilian formulators. |
| Biological-Synthetic Co-Formulation Development | Aligns product pipelines with CONAMA 492 fast-track pathways and ANVISA residue limit harmonization. |
| Precision Agronomist Embedding in Cooperatives | Locks channel control in Rio Grande do Sul and Paraná as direct-to-farm consolidation accelerates. |
| Granular Fertilizer Capacity in Eastern Paraguay | Serves first-time corn-soy adopters lacking liquid application equipment in Alto Paraná. |
| RNA Interference Field Trial Expansion | Positions portfolios for fall armyworm resistance management under IBAMA provisional registrations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study, combining primary interviews with agronomic service directors at Brazilian cooperatives, formulation chemists in São Paulo's industrial corridor, SENASA regulatory affairs specialists, and Paraguayan import permit administrators with secondary validation from ANVISA toxicological re-evaluation schedules, IBAMA registration databases, and customs trade data for Chinese technical ingredient flows. Bottom-up volume modeling across herbicide, fertilizer, insecticide, and fungicide segments triangulated against top-down macroeconomic agricultural input intensity benchmarks.
Calibration against historical adoption curves for precision application hardware and biological penetration rates in Chilean horticulture anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, crop system, formulation technology, and distribution channel access. CAGRs were derived from intensity-per-hectare trajectories in soybean monoculture belts and corn-soy rotation expansion frontiers, with cross-reference to ANVISA phase-out schedules and resistant weed proliferation patterns.
Stress conditions across Chinese technical supply disruption, Brazilian real depreciation, and ANVISA accelerated re-evaluation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cooperative consolidation velocity and biological registration pathway efficiency. Cross-checking against SENASA import permit processing durations and Paraguayan land conversion cadastral data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Egypt Agrochemicals Market