
 Driverless Tractor Market | 2026-2036
Driverless Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Driverless Tractor Market Foresight
North American autonomous implement manufacturing is hardening as Deere & Company leverages its precision-ag software stack to dominate integrated tractor-automation systems. CNH Industrial N.V. anchors its position through deep dealer networks and proprietary guidance platforms. Kubota Corporation competes in compact autonomous utility segments, particularly in orchard and vineyard applications where maneuverability constraints favor smaller footprints.
A driverless tractor constitutes a self-propelled agricultural vehicle capable of executing field operations without onboard human intervention, typically integrating differential GPS positioning within sub-inch accuracy, Lidar obstacle detection arrays, and hydraulic implement control via ISO 11783 ISOBUS protocols. Its primary commercial purpose centers on reducing per-acre labor input while maintaining consistent tillage depth and seeding precision across extended operating windows. GPS-based guidance systems currently occupy the largest installed base, though computer vision segments are expanding fastest as convolutional neural networks enable real-time crop-weed discrimination and path planning in unstructured row environments. Electric power source configurations command premium positioning among sustainability-focused cooperative buyers, while diesel-hybrid architectures sustain volume leadership in heavy-draft soil tillage where torque density requirements remain prohibitive for pure battery platforms.
The EPA governs emissions certification for autonomous diesel powertrains, while the FAA coordinates on unmanned aerial system integration with ground-based tractor fleets for coordinated field mapping. ISO 12100 machinery safety standards and ISO 18497 agricultural automation protocols shape product liability frameworks and cross-border market access for OEMs. Stakeholders must monitor evolving NHTSA jurisdiction questions as autonomous agricultural vehicles encounter public roadway transit between non-contiguous parcels.
Market Dynamics
Farm consolidation across the US Corn Belt is compressing equipment procurement cycles as multi-thousand-acre operators replace fragmented owner-operator fleets with centrally managed autonomous tillage systems.
Growth Catalysts
- Labor scarcity economics:Chronic seasonal worker shortages in US row-crop agriculture force permanent substitution toward unmanned field platforms.
- ISO 18497 certification pathways:Standardized agricultural automation protocols reduce OEM liability exposure and accelerate cross-border equipment approvals.
- Sub-inch GPS accuracy:RTK correction networks now blanket major production regions, enabling repeatable seeding and cultivation without human steering intervention.
Market Restraints
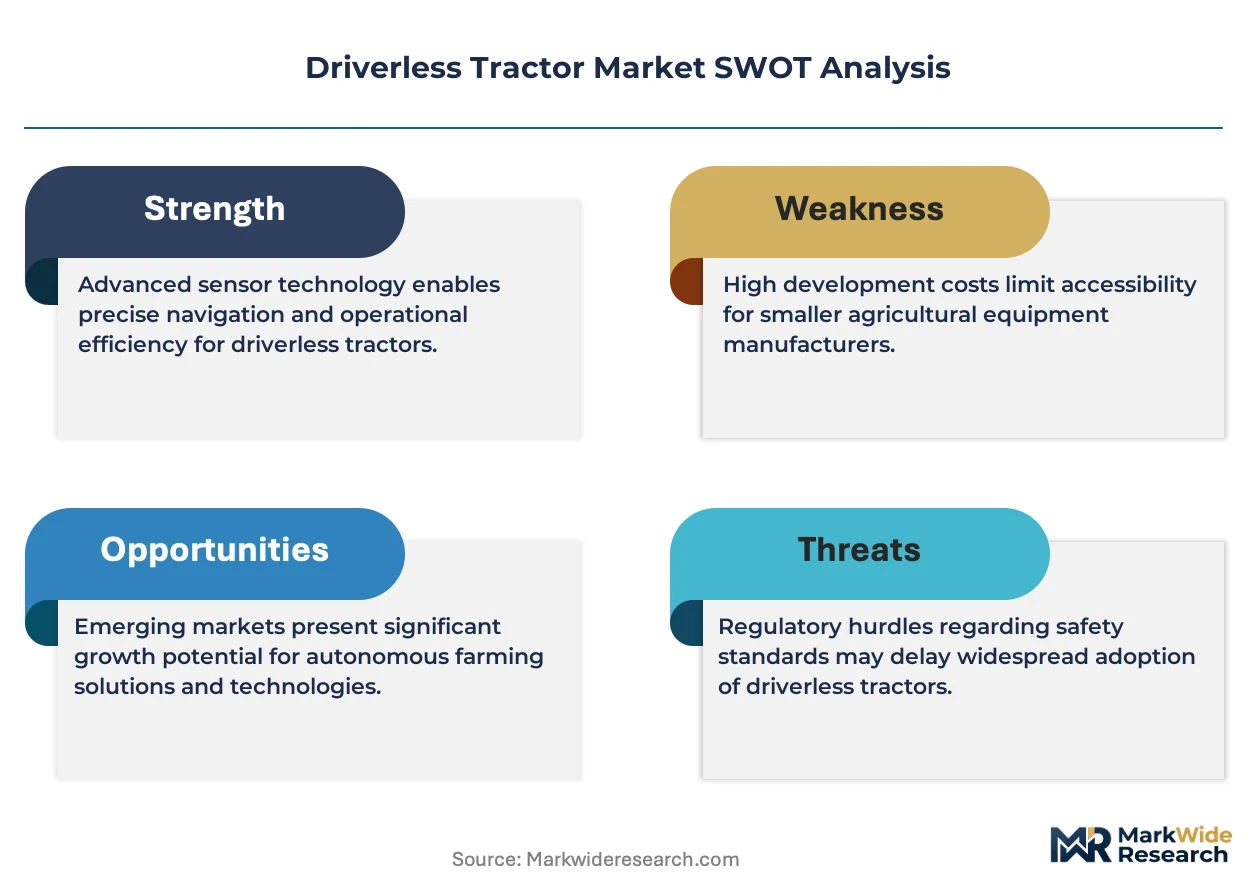
- LiDAR sensor cost concentration:Solid-state obstacle detection arrays remain import-dependent from Asian photonics suppliers, creating input price volatility.
- Diesel torque density requirements:Heavy-draft primary tillage operations exceed current battery-electric powertrain capabilities, locking in hybrid complexity.
- NHTSA roadway jurisdiction uncertainty:Autonomous tractor transit between non-contiguous parcels triggers unresolved motor vehicle classification disputes.
Strategic Opportunities
- Orchard and vineyard automation:Compact platform demand in California and Washington state remains underpenetrated relative to row-crop saturation.
- IRA clean energy incentives:Battery-electric and hydrogen fuel cell powertrains qualify for production tax credits that narrow total cost of ownership gaps.
- Computer vision convergence:Real-time convolutional neural networks for crop-weed discrimination are merging with guidance systems to enable selective cultivation.
Industry Challenges
- Mechatronics technician scarcity:Rural dealer networks lack sufficient trained personnel to service hydraulic-software-electrical integrated systems.
- ISOBUS legacy integration:Older implement fleets without ISO 11783 protocol compatibility require expensive retrofitting or replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driverless Tractor Market |
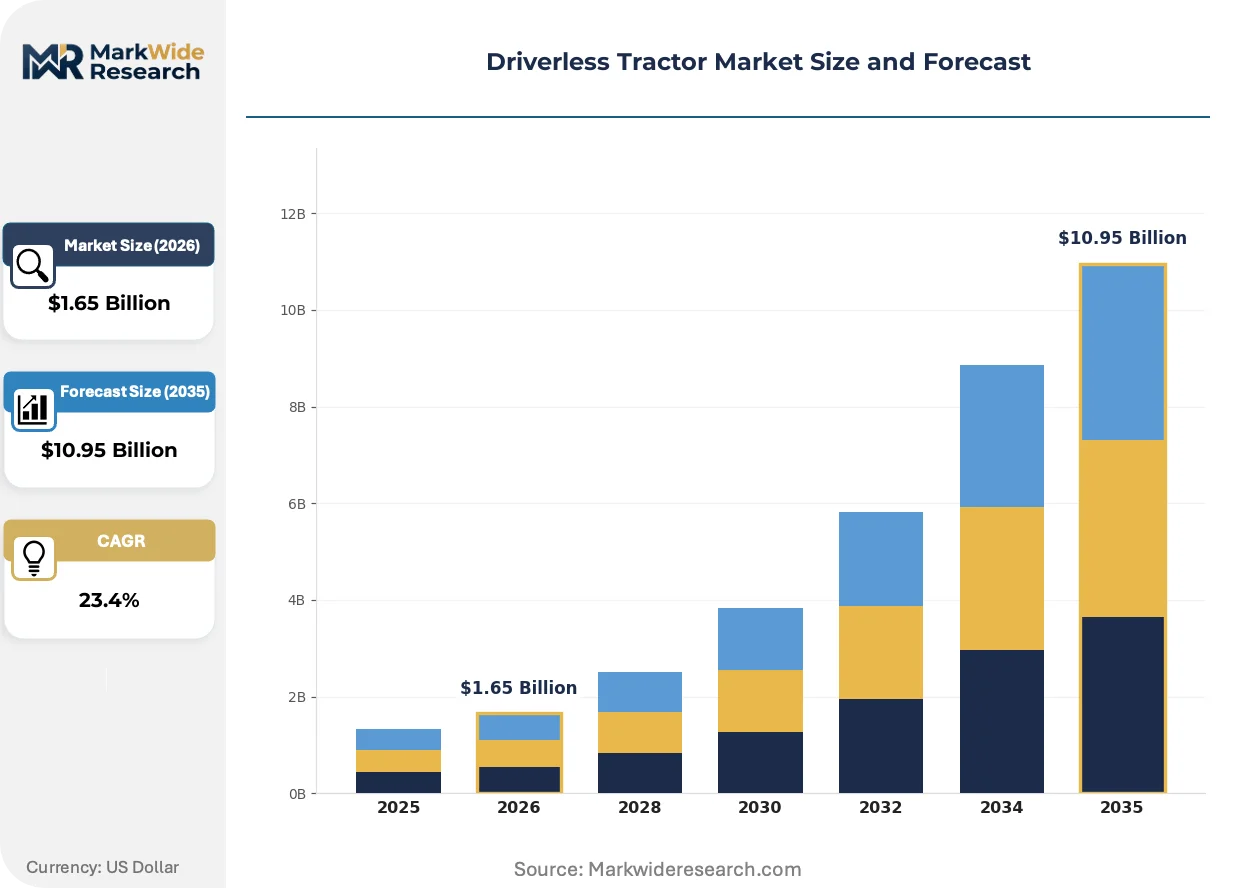
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Lidar, Radar, Computer Vision Application: Agricultural Automation, Precision Farming, Crop Management, Soil Tillage End User: Farmers, Agricultural Contractors, Co-operatives, Research Institutions Power Source: Electric, Diesel, Hybrid, Hydrogen |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, Mahindra & Mahindra Ltd., CLAAS KGaA mbH, SDF Group, Yanmar Holdings Co., Ltd., Monarch Tractor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driverless Tractor Market Shifts & Advancements
Autonomous tractor development is pivoting from guidance automation toward full task autonomy, with perception systems and powertrain electrification commanding parallel engineering investment.
Battery-electric powertrains are electrifying compact utility segments first, where duty cycles and torque demands align with current lithium-ion energy density. California Central Valley vegetable growers are piloting all-electric autonomous platforms for transplanting and cultivation. This voltage transition is compressing maintenance intervals and fuel logistics while displacing small diesel engines from specialty crop operations.
EPA Tier 5 emissions pre-rulemaking is tightening particulate and NOx limits for agricultural diesel engines above 175 horsepower. Engine manufacturers face redesign costs that favor hybrid architectures over conventional combustion. Heavy-draft tillage equipment in the US Corn Belt will bear the steepest compliance burden, accelerating interest in alternative powertrains.
Cooperative buying consortia are aggregating procurement volume to negotiate fleet pricing and shared autonomy infrastructure. Equipment dealers in Iowa and Illinois are losing direct customer relationships to these pooled purchasing entities. This channel compression is most advanced where farm consolidation has concentrated ownership into fewer decision-making units.
Driverless Tractor Market Segmentation
Technology architecture and powertrain configuration determine procurement economics for autonomous tractor fleets. Application specificity and end-user scale dictate automation depth requirements across divergent agricultural operations.
Technology:
Positioning and perception systems differentiate on accuracy thresholds, cost curves, and environmental robustness.
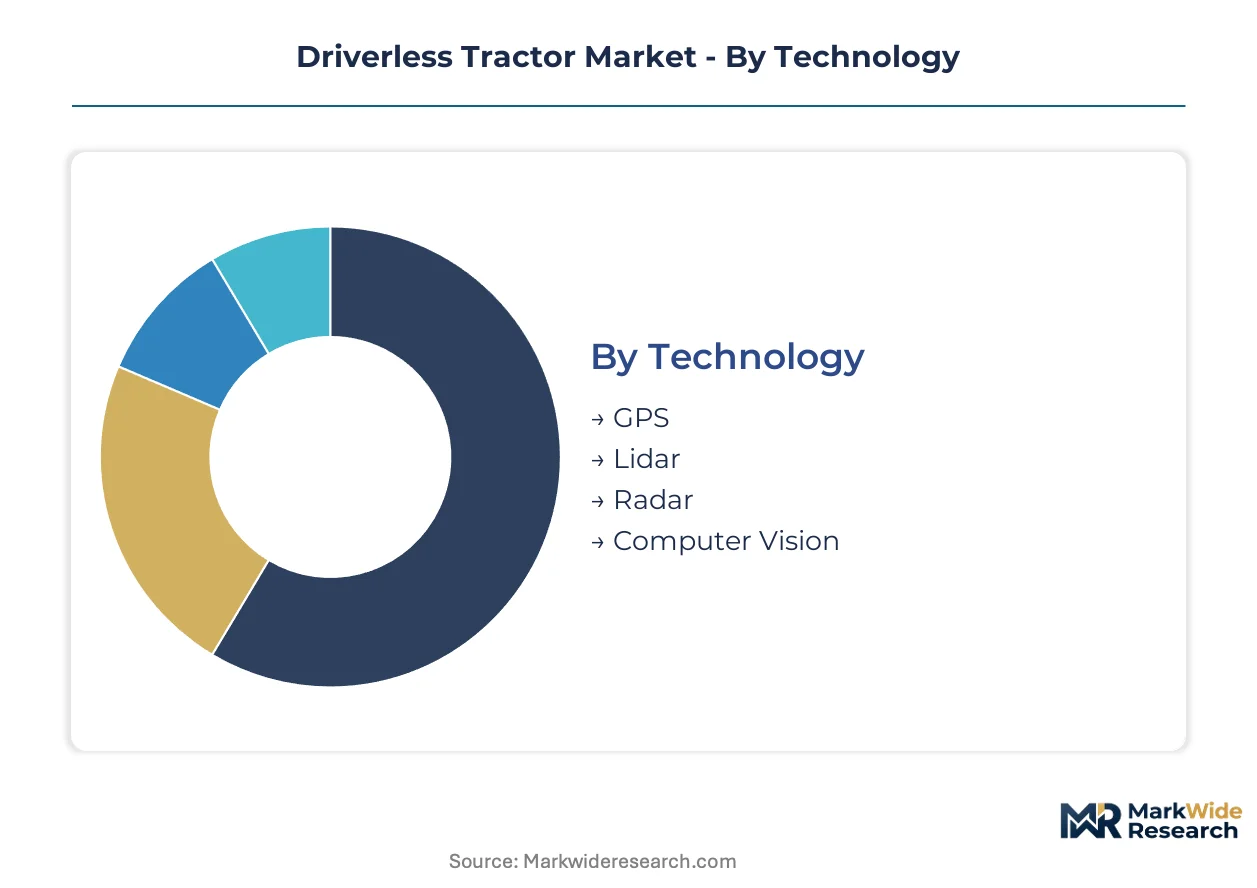
- GPS:Real-Time Kinematic correction networks deliver sub-inch positioning accuracy for repeatable seeding and cultivation passes. US Corn Belt operators deploy RTK-guided fleets across multi-thousand-acre contiguous parcels where baseline repeatability drives yield consistency.
- Computer Vision:Convolutional neural networks enable real-time crop-weed discrimination and adaptive path planning in unstructured row environments. California specialty crop growers pilot vision-guided platforms for selective cultivation where GPS alone fails in dense canopy conditions.
- Lidar:Solid-state photonic arrays provide 360-degree obstacle detection with centimeter-range precision for collision avoidance.
- Radar:Millimeter-wave sensors penetrate dust, fog, and crop residue where optical systems degrade.
GPS leads on scale; computer vision leads on momentum.
Application:
Task specificity determines sensor payload, implement compatibility, and software autonomy level.
- Agricultural Automation:End-to-end unmanned field execution spanning tillage through harvest with minimal human oversight. Large-scale Iowa and Illinois operators deploy full-autonomy fleets for 24-hour planting windows during compressed spring intervals.
- Soil Tillage:Primary and secondary tillage operations demand high-draft torque and consistent depth control across variable soil conditions.
- Precision Farming:Variable-rate input application guided by real-time biomass sensing and prescription maps.
- Crop Management:Mid-season cultivation, scouting, and intervention tasks requiring selective actuation.
Agricultural automation captures the largest equipment procurement volumes; soil tillage commands the highest per-unit capital intensity.
End User:
Ownership structure shapes fleet sizing, financing mechanisms, and service contract preferences.
- Farmers:Owner-operators and family partnerships purchasing 1-3 units for direct operational control. Nebraska and Kansas wheat producers favor owned autonomous platforms for harvest logistics flexibility.
- Co-operatives:Pooled purchasing entities aggregating volume for fleet pricing and shared infrastructure. Iowa and Illinois cooperative consortia now procure 20-50 unit blocks with centralized maintenance depots.
- Agricultural Contractors:Custom service providers charging per-acre for seasonal tillage and planting execution.
- Research Institutions:University extension programs and USDA facilities testing next-generation autonomy protocols.
Farmers anchor current installed base; co-operatives are expanding most aggressively.
Power Source:
Torque density requirements and duty cycle profiles segment powertrain selection across implement classes.
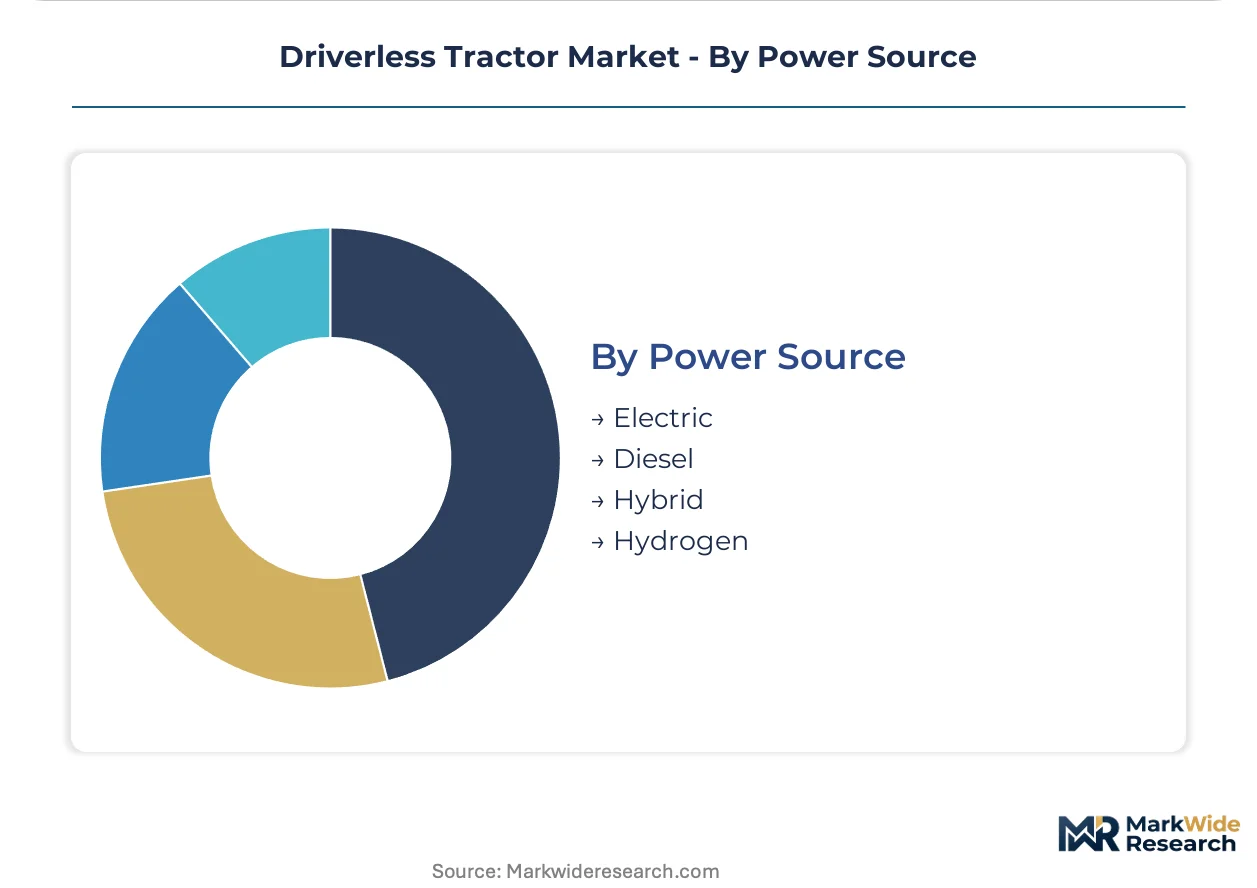
- Diesel:Compression-ignition engines dominate heavy-draft primary tillage where instantaneous torque exceeds 400 horsepower. EPA Tier 5 pre-rulemaking is forcing redesign costs that compress manufacturer margins.
- Hybrid:Diesel-electric architectures balance torque density with fuel efficiency gains for extended operating windows. Illinois and Indiana operators pilot hybrid platforms for fall tillage where runtime duration matters more than absolute power.
- Electric:Battery-electric powertrains penetrate compact utility segments with intermittent duty cycles. California Central Valley vegetable growers deploy all-electric autonomous units for transplanting and cultivation within IRA credit-eligible procurement frameworks.
- Hydrogen:Fuel cell prototypes target mid-horsepower ranges where battery energy density falls short and diesel faces regulatory pressure.
Diesel retains volume leadership; electric platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting autonomous tractor development investment toward regions with streamlined certification pathways and concentrated agricultural mechanization demand.
United States
The US Corn Belt drives procurement volume as Iowa and Illinois operators consolidate thousand-acre holdings into centrally managed autonomous fleets. EPA Tier 5 pre-rulemaking is forcing diesel powertrain redesigns that favor hybrid architectures. Illinois cooperative consortia now procure 20-50 unit blocks with shared maintenance depots in Des Moines and Peoria corridors.
Germany
Precision engineering heritage supports high-autonomy tillage system development for Eastern European export markets. CE marking under EU machinery directives shapes product liability frameworks for cross-border sales. Baden-Württemberg industrial clusters around Stuttgart host specialized sensor integration facilities serving OEM automation programs.
Japan
Compact autonomous utility platforms address labor scarcity in mountainous rice cultivation and orchard operations. METI funding for smart agriculture initiatives accelerates domestic field-testing protocols. Kubota Corporation anchors development activity in Osaka-Kobe manufacturing corridors for Asian export markets.
Brazil
Cerrado region soy and corn expansion creates demand for heavy-draft autonomous tillage in consolidated latifundia operations. ANVISA agrochemical application regulations intersect with autonomous spraying system certification. São Paulo state equipment distributors pilot fleet-service models for 10,000-hectare sugarcane estates.
India
Smallholder consolidation into farmer producer organizations creates pooled procurement demand for compact autonomous platforms. BIS machinery safety standards govern domestic manufacturing certification requirements. Punjab and Haryana wheat-rice belt cooperatives trial sub-inch GPS-guided seeding systems with shared RTK infrastructure.
Driverless Tractor Market Competitive Landscape
North American producers anchor the integrated-systems tier; European and Asian specialists hold differentiated positions in compact utility and precision-implement segments. Market structure concentrates around three strategic archetypes: full-stack automation integrators leveraging proprietary software-hardware combinations; dealer-network anchors protecting regional service relationships; and compact-platform specialists exploiting maneuverability constraints in specialty crop applications. Dominant competitive moves include cooperative buying consortia aggregating procurement volume for fleet pricing, and strategic partnerships between OEMs and RTK correction network providers.
Among the integrated-systems tier, Deere & Company and CNH Industrial N.V. represent full-stack automation approaches, while Kubota Corporation exemplifies compact-platform specialization for constrained-environment applications. These anchors occupy positions reflecting divergent scale-versus-maneuverability trade-offs across row-crop and specialty-crop demand segments.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra Ltd. |
| CLAAS KGaA mbH |
| SDF Group |
| Yanmar Holdings Co., Ltd. |
| Monarch Tractor |
| Others |
Supply & Pricing Matrix
Powertrain electrification in compact utility segments is compressing maintenance cost structures while redrawing supplier geography away from Midwest engine foundries toward Asian battery cell and Korean power electronics manufacturing corridors. This voltage transition simultaneously elevates capital intensity for OEMs and concentrates procurement leverage among buyers qualifying for IRA production tax credits.
Pricing Analysis
Distributor margins on autonomous tractor systems typically range 12-18 percent for integrated guidance platforms, with cooperative consortia extracting 8-12 percent volume discounts on 20-plus unit fleet orders. Three-tier pricing structure across premium, standard, and economy levels separates full-stack automation bundles from guidance-only retrofits and basic GPS-steering add-ons. Cost compression in diesel-hybrid architectures is intensifying because EPA Tier 5 pre-rulemaking forces engine redesign expenses onto manufacturers. Price sensitivity concentrates among owner-operators purchasing 1-3 units, while cooperative buyers prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Solid-state LiDAR arrays rest on Taiwanese and Chinese photonics suppliers, with Japanese precision optics manufacturers anchoring high-accuracy sensor subassemblies. Lithium-ion cell supply draws from South Korean and Chinese producers, while German and US semiconductor fabricators source perception processing chips. Single-source vulnerability in Asian LiDAR component supply creates tariff exposure and logistics chokepoint risk during ocean freight disruptions. Distribution runs through dealer networks in Iowa and Illinois corridors, though cooperative consortia are compressing channel relationships toward direct OEM fleet contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 5 compliance costs in the US Corn Belt run 15-25 percent above equivalent certification in Brazil's Cerrado region, creating arbitrage incentive for manufacturers to stage heavy-draft platform assembly in South American production corridors.
For Market Incumbents: Cement full-stack automation dominance by deepening proprietary RTK network integration and locking cooperative consortia into multi-year service contracts. Capacity addition in São Paulo state manufacturing corridors defends margin position against Brazilian latifundia demand capture. Certification investment in ISO 18497 agricultural automation protocols reduces liability exposure as NHTSA jurisdiction questions over roadway transit remain unresolved. For New Entrants and Emerging Players: Direct-to-cooperative digital sales channels bypass entrenched dealer networks and capture procurement volume aggregation in Des Moines and Peoria corridors. Orchard and vineyard automation in California Central Valley and Washington state offers the most penetrable white-space target, with compact electric platforms qualifying for IRA credits. Go-to-market positioning should emphasize per-acre operational cost reduction rather than capital expenditure substitution. For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor integration firms because autonomous tractor OEMs lack in-house photonics capabilities and face import-dependency concentration. Long-term viability across the analysis window hinges on computer vision convergence with guidance systems for selective cultivation applications. Acquisition target archetype: compact-platform specialists with California regulatory relationships and METI-funded Japanese field-test credentials. Watch NHTSA autonomous vehicle classification rulings as the primary inflection indicator for cross-parcel transit revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| RTK Network Partnership | Deere's proprietary correction infrastructure locks cooperative buyers into recurring subscription revenue streams. |
| Battery Supply Agreement | Korean cell manufacturer contracts secure IRA credit eligibility for California vegetable grower deployments. |
| Computer Vision Acquisition | Convolutional neural network specialists enable real-time crop-weed discrimination in unstructured canopy environments. |
| Brazilian Manufacturing Footprint | São Paulo assembly avoids EPA Tier 5 compliance burden for Cerrado latifundia export demand. |
| Cooperative Fleet Contracting | Iowa and Illinois consortia procurement compresses dealer margins while scaling autonomous infrastructure utilization. |
Research Methodology
Multiple input streams — OEM product development executives, cooperative procurement managers, RTK network operators, and agricultural extension specialists — were reconciled against secondary validation from EPA regulatory filings, FAA unmanned system guidance documents, SEC 10-K equipment revenue disclosures, and USDA farm consolidation databases. Bottom-up unit shipment estimates from state-level dealer inventory data were triangulated with top-down agricultural mechanization expenditure models across the Corn Belt and California Central Valley production regions.
Data-stream reconciliation anchored volume and value outputs across technology architecture, powertrain configuration, application specificity, and end-user ownership structure dimensions. CAGRs were derived from fitted growth curves calibrated to farm consolidation velocity and labor substitution economics throughout the projection horizon. Industry-specific forecast inputs incorporated RTK network coverage expansion timelines and EPA Tier 5 pre-rulemaking implementation trajectories.
The model assumes a particular technology adoption path; alternative pathways for battery-electric powertrain penetration in heavy-draft tillage would alter the outlook if lithium-ion energy density breakthroughs displace diesel-hybrid architectures faster than baseline assumptions. Forecasts embed assumptions regarding NHTSA jurisdiction resolution and cooperative buying consortia formation velocity. A small set of named triggers — solid-state LiDAR cost curves, IRA credit extension decisions, and Brazilian ANVISA spraying certification timelines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Automated Turf Harvester Market