
 South America Utility Tractor Market | 2026-2036
South America Utility Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
South America Utility Tractor Market Analytics
Argentina's SENASA phytosanitary certification requirements for imported agricultural machinery is consolidating compliance costs for new entrants. Deere & Company leverages its Brazilian manufacturing footprint to sustain localized content advantages. AGCO Corporation anchors its regional position through dedicated distribution in Argentina's Pampas grain belt. Kubota Corporation differentiates via compact tractor specialization for mid-tier Brazilian horticulture operations.
A utility tractor denotes a self-propelled agricultural vehicle typically rated between 40 and 140 engine horsepower, featuring three-point hitch hydraulic systems and power-take-off shafts designed to operate mounted implements across varied terrain. Its primary commercial purpose centers on mechanizing soil preparation, crop establishment, and residue management for mixed-use farming enterprises. Diesel-powered 4WD tractors dominate unit volumes across South American procurement channels, while electric propulsion platforms represent the fastest-growing fuel-type category as rural electrification expands. Tillage and planting applications command the largest share of implement attachment spending, with harvesting-related configurations capturing premium margin pools due to seasonal intensity and specialized header requirements.
Brazil's INMETRO certification mandates and Argentina's IRAM safety standards shape product homologation timelines for imported equipment. ANVISA oversight of operator exposure limits and Mercosur harmonization protocols on exhaust emissions increasingly influence engine architecture decisions by manufacturers. Stakeholders must monitor regulatory divergence between Brazilian state-level environmental licensing and federal import tariff schedules to optimize regional supply chain positioning.
Market Dynamics
Mechanization mandates across South American grain belts are compressing replacement cycles for mid-horsepower equipment as diesel-emission protocols force engine architecture redesigns ahead of seasonal planting windows.
Growth Catalysts
- PROTRATOR rural credit expansion:Brazil's subsidized financing program lowers capital barriers for Mato Grosso soybean operators consolidating acreage.
- Horticulture mechanization:Mid-tier Brazilian vegetable producers are scaling tractor fleets to meet supermarket contract specifications for planting precision.
- Precision-farming subsidies:Argentina's INTA technology agency funds GPS-guided implement adoption across the Pampas grain belt.
Market Restraints
- Diesel price volatility:Mercosur fuel-tax harmonization failures expose Brazilian operators to exchange-rate-driven input cost swings.
- Import dependency concentration:SENASA phytosanitary certification bottlenecks concentrate compliance expertise among established distributors.
- Electric range limitation:Battery energy density constraints restrict electric tractor deployment to sub-100-horsepower applications below 4-hour duty cycles.
Strategic Opportunities
- Paraguay expansion corridor:Underpenetrated Chaco region soybean frontiers lack established equipment service networks.
- Telematics-irrigation convergence:Connected tractor platforms integrating soil-moisture sensors command premium positioning in water-stressed Cerrado zones.
- Digital auction channels:Online secondary-market platforms are shortening equipment turnover timelines for Argentine cash-constrained cooperatives.
Industry Challenges
- Certification timeline compression:INMETRO homologation queues delay new model launches across Brazilian state environmental licensing jurisdictions.
- After-sales technician scarcity:Hydraulic diagnostics expertise concentrates in legacy dealer networks serving southern Brazil's established farm belts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Utility Tractor Market |
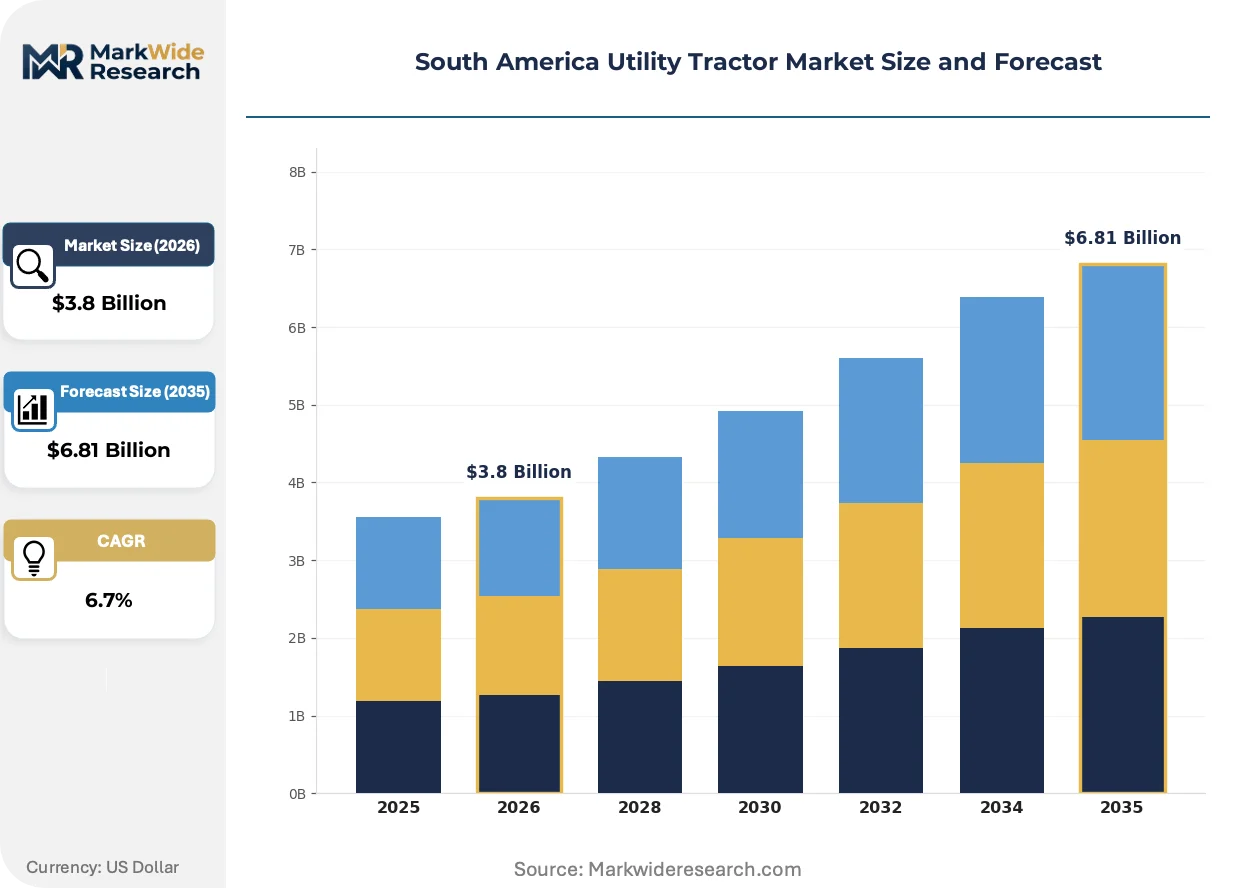
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4WD Tractors, 2WD Tractors, Compact Tractors, Garden Tractors End User: Agriculture, Landscaping, Forestry, Construction Fuel Type: Diesel, Gasoline, Electric, Biodiesel Application: Tillage, Planting, Harvesting, Soil Cultivation |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Mahindra & Mahindra Ltd, CLAAS KGaA mbH, Kubota Corporation, Massey Ferguson, Tractors and Farm Equipment Limited, International Tractors Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Utility Tractor Market Evolving Landscape
Telematics integration and powertrain electrification are compressing the traditional boundaries between tractor hardware and farm-management software across South American procurement channels.
ISOBUS III protocol implementation is unifying implement-tractor communication standards across Brazilian large-scale operations. Mato Grosso grain producers adopting these systems reduce setup times between tillage and planting configurations. Equipment manufacturers are unifying proprietary hydraulic architectures around this open standard to capture fleet-standardization contracts.
Mercosur's tightening diesel-emission protocols are forcing turbocharged exhaust-gas-recirculation adoption across 75-140 horsepower segments. Engine suppliers must redesign combustion chambers to meet nitrogen-oxide limits while maintaining torque curves for heavy tillage. Argentine distributors report extended pre-order timelines as manufacturers validate after-treatment systems for regional fuel-sulfur content.
Cooperative procurement consortia are displacing individual farm purchasing across Argentina's Pampas region. Pooled equipment-sharing agreements reduce per-hectare capital intensity for mid-tier grain producers. This model concentrates most visibly in Buenos Aires province where credit-access constraints favor fractional ownership over full fleet acquisition.
South America Utility Tractor Market Segmentation
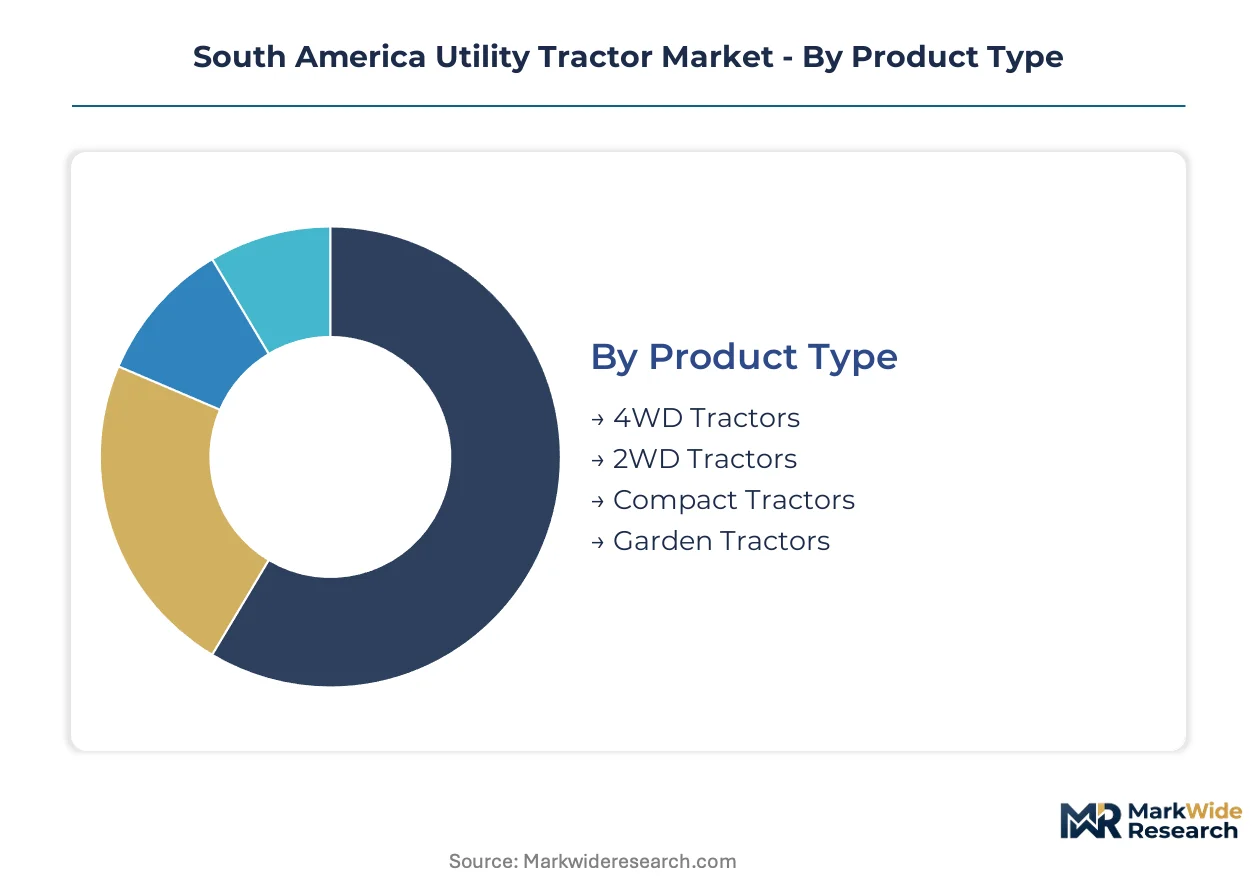
Utility tractor procurement patterns across South America diverge sharply by operational scale and terrain demands. Buyers in Brazil's consolidated soybean belt prioritize horsepower and hydraulic capacity, while Argentine horticulture operators optimize for maneuverability and fuel efficiency.
Product Type:
Capital intensity and field conditions dictate platform selection across Mercosur grain belts.
- 4WD Tractors:Articulated chassis with hydrostatic transmission and differential lock systems handle heavy tillage in Mato Grosso's clay-heavy Cerrado soils. PROTRATOR credit expansion accelerates fleet upgrades toward these platforms ahead of emission compliance deadlines.
- Compact Tractors:Sub-50-horsepower units with hydrostatic drive and mid-mount mower compatibility serve São Paulo state vegetable cooperatives. Supermarket contract specifications for planting precision drive replacement cycles in these operations.
- 2WD Tractors:Mechanical transmission platforms dominate smallholder soy operations in Paraguay's eastern departments where capital constraints limit 4WD adoption.
- Garden Tractors:Lawn-and-garden configurations with belt-driven implements address estate maintenance and municipal landscaping contracts in southern Brazil's urban periphery.
Volume sits with 4WD Tractors; growth tilts toward Compact Tractors.
End User:
Customer archetypes determine attachment specifications and service network requirements.
- Agriculture:Mixed-crop enterprises across Argentina's Pampas require three-point hitch versatility for rapid implement changeover between wheat and soybean rotations. INTA precision-farming subsidies compress replacement timelines for GPS-ready platforms.
- Forestry:Winch-equipped tractors with reinforced frames and protective cabs operate in Chile's southern timber concessions where slope gradients exceed 15 percent.
- Landscaping:Municipal maintenance fleets in Brazilian state capitals specify front-loader compatibility and turf-tire configurations for median and park maintenance.
- Construction:Backhoe-loader tractor combinations serve rural road maintenance contracts across Bolivia's Altiplano region where dedicated construction equipment remains scarce.
Revenue concentrates in Agriculture; Forestry expands most quickly on mechanization mandates.
Fuel Type:
Energy security and emission protocols reshape powertrain architecture decisions.
- Diesel:Turbocharged direct-injection engines with exhaust-gas recirculation dominate 75-140 horsepower segments. Mercosur nitrogen-oxide limits force combustion chamber redesigns validated for regional fuel-sulfur content.
- Electric:Battery-electric platforms with 4-hour duty cycles and fast-charge capability penetrate Brazilian horticulture operations near grid-connected packing facilities. ANVISA operator exposure limits accelerate zero-emission adoption in enclosed greenhouse environments.
- Gasoline:Carbureted and port-fuel-injection engines persist in sub-40-horsepower garden tractor segments where capital constraints outweigh fuel efficiency concerns.
- Biodiesel:B20-B100 compatible injection systems align with Brazil's national biofuel mandate and PROINFA rural energy incentives.
Unit shipments favor Diesel; steepest expansion trajectory belongs to Electric.
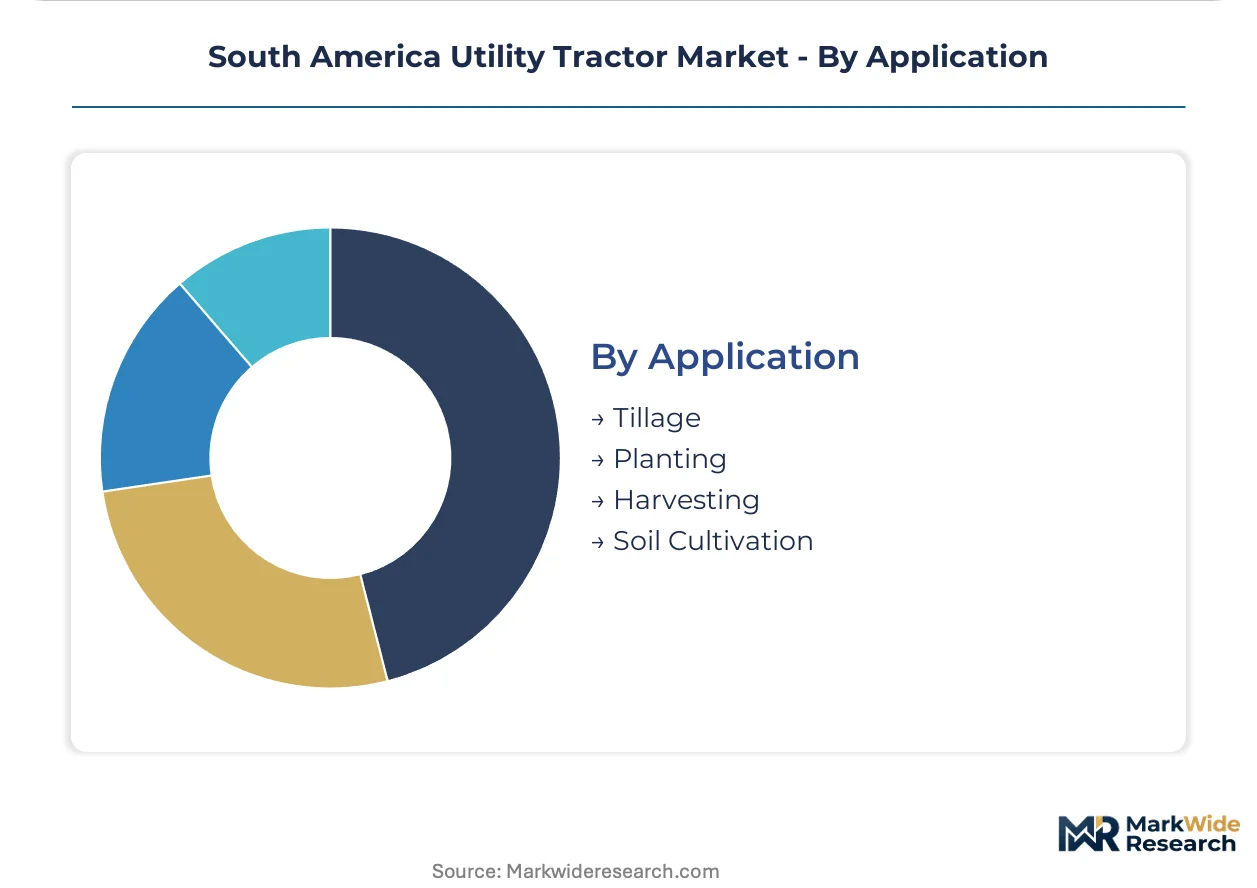
Application:
Seasonal intensity and implement specialization drive attachment spending patterns.
- Tillage:Heavy disc and subsoiler operations demand 100+ horsepower with closed-center hydraulic systems. Mato Grosso operators replace aging fleets ahead of compressed planting windows.
- Planting:Precision seeding with variable-rate fertilization requires ISOBUS III compatibility and hydraulic flow matching. Argentine cooperatives pool equipment to spread capital costs across pooled acreage.
- Harvesting:Header tractors and transport configurations command premium margins due to seasonal intensity and specialized PTO requirements.
- Soil Cultivation:Secondary tillage and residue management with chisel plows and field cultivators utilize mid-horsepower platforms in rotation-intensive systems.
Equipment hours accumulate fastest in Tillage; margin capture peaks in Harvesting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's MATOPIBA agricultural frontier tax incentives concentrate equipment procurement in consolidated soybean operations across the Cerrado biome. Argentina's Pampas grain belt and Chile's southern timber concessions anchor secondary demand poles.
Brazil
Mato Grosso state operators replace aging fleets ahead of compressed planting windows for second-crop soybeans. PROTRATOR rural credit expansion lowers capital barriers for consolidated acreage holders. Rondonópolis machinery clusters serve as distribution hubs for Cerrado-wide equipment deployment.
Argentina
INTA precision-farming subsidies compress replacement timelines for GPS-ready platforms across Buenos Aires province. SENASA phytosanitary certification requirements consolidate compliance expertise among established distributors. Rosario grain corridor cooperatives pool equipment-sharing agreements to reduce per-hectare capital intensity.
Chile
Southern timber concessions in Los Ríos and Los Lagos regions drive winch-equipped tractor demand for slope gradients exceeding 15 percent. CONAF forestry mechanization mandates accelerate fleet standardization. Valdivia equipment depots anchor service networks for radiata pine harvesting operations.
Paraguay
Chaco region soybean frontiers lack established equipment service networks despite expanding acreage. Capital constraints limit 4WD adoption among smallholder operators in eastern departments. Ciudad del Este distribution channels capture cross-border procurement from Brazilian agribusiness investors.
Uruguay
Pasture renovation cycles in Paysandú and Colonia departments sustain mid-horsepower replacement demand. Banco República agricultural credit lines favor equipment modernization for dairy expansion. Mercedes machinery retailers serve mixed-crop enterprises across the western livestock belt.
South America Utility Tractor Market Competitive Landscape
North American producers anchor one tier; Japanese specialists hold compact-tractor positioning; Indian manufacturers penetrate value segments. The vendor base structures around three strategic archetypes: full-line agricultural equipment conglomerates, compact-tractor specialists, and emerging-market value players. M&A activity concentrates on distribution network consolidation, while portfolio diversification moves target precision-farming technology integration.
Among full-line agricultural equipment conglomerates, Deere & Company and AGCO Corporation exemplify the integrated-platform archetype with established Mercosur manufacturing footprints. Kubota Corporation occupies a distinct position within the compact-tractor specialization tier. These three anchors represent divergent strategic postures toward emission compliance timelines and precision-farming technology bundling across Brazilian and Argentine procurement channels.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Mahindra & Mahindra Ltd |
| CLAAS KGaA mbH |
| Kubota Corporation |
| Massey Ferguson |
| Tractors and Farm Equipment Limited |
| International Tractors Limited |
| Others |
Value Network & Pricing Analysis
Diesel engine block castings and turbocharger assemblies flow from Brazilian foundries through three distinct pricing tiers before reaching Mato Grosso soybean operators. Steel price volatility in Mercosur markets compresses margins on mid-horsepower platforms while PROTRATOR credit subsidies absorb downstream cost pressure for consolidated acreage holders.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to GPS-ready platforms ordered within sixty days of planting windows across Brazil's Cerrado. Three-tier pricing structure across premium, standard, and economy levels reflects ISOBUS III certification grade, hydraulic flow capacity, and bundled telematics service contracts. Cost compression in economy-tier mechanical-transmission units is intensifying because Argentine cooperatives prioritize capital preservation over precision features. Smallholder operators in Paraguay's eastern departments exhibit highest price sensitivity; large consolidated farms in Mato Grosso show least elasticity due to productivity-linked financing.
Supply Chain Analysis
Refurbishment flows from southern Brazil's legacy dealer networks feed secondary-market channels serving Argentine cash-constrained cooperatives. Component manufacturing concentrates in Brazil, Argentina, and Japan; axle assemblies and hydraulic pumps draw from these production hubs. Supply chain vulnerability rests on single-source dependency for electronic control modules validated to INMETRO emission protocols. Distribution runs through Rondonópolis machinery clusters anchoring Cerrado-wide deployment and Rosario grain corridor cooperatives pooling fractional ownership agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification is displacing diesel architectures in sub-100-horsepower segments as battery energy density crosses operational thresholds for Brazilian horticulture operations.
For Market Incumbents: Deploy telematics-irrigation convergence platforms to capture premium positioning in water-stressed Cerrado zones. Backward integration into hydraulic pump manufacturing reduces exposure to single-source electronic control module bottlenecks. Counter emerging Indian value players by accelerating ISOBUS III certification timelines ahead of INMETRO queue compression. For New Entrants and Emerging Players: ANVISA operator exposure limits in Brazil open a window for zero-emission compact tractor penetration near grid-connected packing facilities. Target Paraguay's underpenetrated Chaco region soybean frontiers where established service networks remain absent. Pursue cooperative procurement consortia in Buenos Aires province as the primary go-to-market channel, offering fractional ownership models that reduce per-hectare capital intensity. For Investors and Strategic Acquirers: Extended pre-order timelines for turbocharged exhaust-gas-recirculation platforms is the leading indicator that emission compliance investments are concentrating competitive advantage among full-line manufacturers. Long-term viability favors vertically integrated producers with captive Brazilian manufacturing footprints and validated after-treatment systems for regional fuel-sulfur content. Monitor PROTRATOR credit allocation shifts as the signal for acreage consolidation velocity and fleet replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Systems | Captive production of pumps and valves insulates margin from single-source electronic module bottlenecks. |
| ISOBUS III Platform Standardization | Open-protocol compatibility reduces setup times between tillage and planting configurations for Mato Grosso operators. |
| Telematics-Irrigation Convergence | Soil-moisture sensor integration commands premium positioning in water-stressed Brazilian Cerrado zones. |
| Cooperative Procurement Partnership | Equipment-sharing agreements reduce per-hectare capital intensity for Argentine mid-tier grain producers. |
| Electric Powertrain Certification | ANVISA zero-emission validation accelerates adoption in enclosed Brazilian greenhouse environments. |
Research Methodology
Multi-period observation of PROTRATOR credit disbursement patterns and INMETRO homologation queue lengths anchored the trend analysis, supplemented by interviews with fleet managers at consolidated Mato Grosso soybean operations, hydraulic diagnostics technicians in southern Brazil's established dealer networks, procurement leads at Argentine cooperative consortia, and aftermarket service heads across Paraguay's emerging Chaco frontier. Secondary validation drew from ANVISA operator exposure filings, INTA precision-farming subsidy disbursement records, Mercosur emission protocol harmonization documents, and customs trade data on agricultural machinery imports. Bottom-up unit shipment modeling triangulated against top-down acreage mechanization rate projections.
Segment-weighting applied horsepower tier, fuel type architecture, and end-use application intensity across the projection horizon. The analytical framework modeled 4WD versus compact versus 2WD platform splits, diesel versus electric versus biodiesel-compatible powertrain shares, and agriculture versus forestry versus landscaping end-use concentrations. CAGRs derived from replacement cycle compression rates tied to emission compliance deadlines and precision-farming subsidy expiration schedules. Regional production cluster capacity and phytosanitary certification timeline assumptions informed geographic allocation.
The model assumes a particular technology adoption path; alternative pathways for battery-electric platforms with extended duty cycles would alter the outlook for diesel dominance in mid-horsepower segments. Forecasts reflect assumptions regarding PROTRATOR credit continuity, Mercosur emission protocol enforcement timing, and regional fuel-sulfur content stability. Practitioners should monitor INMETRO queue compression rates, diesel-biodiesel price spreads, and electric grid expansion timelines in Brazilian horticulture corridors for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market