
 Global Autonomous Tractor Market | 2026-2036
Global Autonomous Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autonomous Tractor Market Analysis
The EU Green Deal is expanding compliance requirements for precision agriculture equipment across European farmland. John Deere leverages its integrated autonomy stack to sustain technology leadership in North American row-crop operations. AGCO Corporation anchors its competitive position through specialized retrofit kits that extend conventional tractors into semi-autonomous platforms.
An autonomous tractor is a self-propelled agricultural vehicle equipped with GPS guidance, Lidar, computer vision, and machine learning systems that execute tillage, planting, spraying, and harvesting without continuous human operator presence. These platforms typically operate at sub-inch accuracy through RTK-GPS correction and process multispectral camera feeds to adjust implement depth and speed in real time. Driverless tractors currently dominate commercial deployment due to proven reliability in controlled field geometries, while machine learning segments attract the fastest R&D allocation as neural networks improve obstacle recognition in unstructured crop canopies. Electric tractors occupy a nascent but expanding niche where battery energy density constraints limit continuous high-draw operations.
The US Department of Transportation and the EU's Machinery Directive (2006/42/EC) jointly shape market access through divergent safety certification pathways for unmanned ground vehicles. Japan's Ministry of Economy, Trade and Industry (METI) promotes domestic field robotics through targeted R&D consortia that accelerate JIS standard development for autonomous agricultural machinery. Stakeholders must monitor how Brazil's national agricultural regulator adapts its type-approval framework to address liability allocation between equipment OEMs and fleet operators during unmanned night shifts.
Market Dynamics
Labor shortages across Brazil's soy belt and the US Midwest are compressing adoption timelines for driverless tillage fleets, while EU farm digitization mandates force hardware refresh cycles that reshape equipment procurement patterns.
Growth Catalysts
- EU Green Deal farm digitization mandates:Compliance deadlines force European grain cooperatives to replace legacy fleets with GPS-guided platforms certified under Machinery Directive 2006/42/EC.
- RTK-GPS correction networks:Public and private base station rollouts across Kansas, Iowa, and Nebraska enable sub-inch accuracy without proprietary subscription locks.
- Brazilian labor migration patterns:Rural workforce outflows from Mato Grosso and Goiás soy regions accelerate unmanned night-shift deployment to maintain planting windows.
Market Restraints
- Lidar sensor cost concentration:Dependence on solid-state lidar supply from East Asian component fabs creates input price volatility for Tier 1 autonomy integrators.
- Battery energy density ceilings:Lithium-ion pack limitations restrict continuous high-draw electric tractor operations to sub-8-hour cycles without mid-field swapping infrastructure.
- Jurisdictional liability fragmentation:Divergent unmanned ground vehicle safety certifications between NHTSA pathways and EU type-approval delay cross-border fleet standardization.
Strategic Opportunities
- Indian Punjab-Haryana wheat corridor:Fragmented landholdings below 2 hectares present retrofit kit penetration potential as METI-funded consortia demonstrate scaled-down autonomy stacks.
- 5G private network convergence:Edge-computing offload from onboard GPUs to field-side base stations reduces per-unit hardware costs for computer vision processing.
- USDA Conservation Reserve Program incentives:Precision tillage compliance bonuses reward sub-inch accuracy adoption, creating subsidy-aligned demand pull for RTK-equipped fleets.
Industry Challenges
- Field robotics technician scarcity:Mechatronics programs at US land-grant universities graduate insufficient talent to service expanding autonomous fleets across the Corn Belt.
- ISO 18497 functional safety certification timelines:Agricultural machinery safety validation cycles stretch 18-24 months, delaying product launches behind software update velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autonomous Tractor Market |
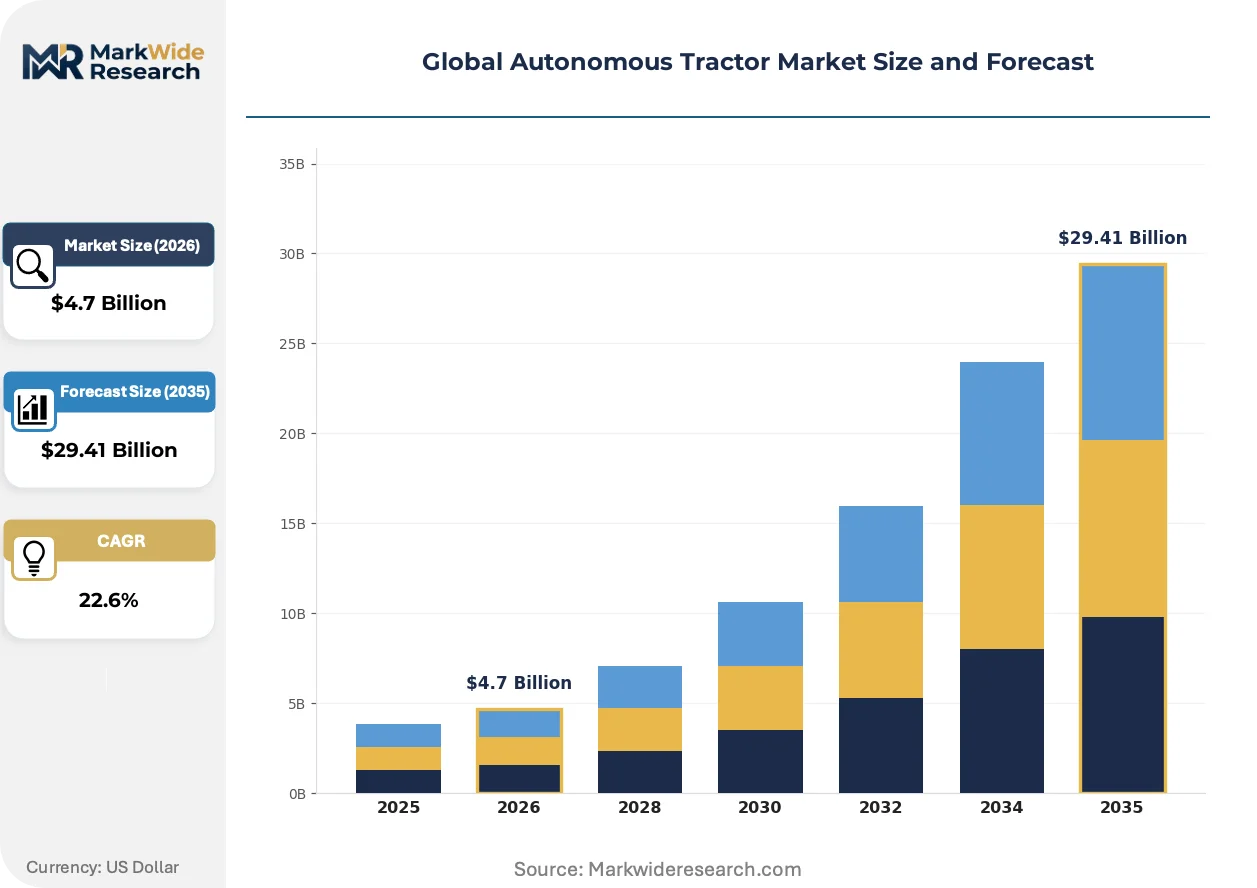
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driverless Tractors, Electric Tractors, Hybrid Tractors, Robotic Tractors Technology: GPS Guidance, Lidar, Computer Vision, Machine Learning End User: Farms, Agricultural Contractors, Research Institutions, Government Agencies Deployment: On-field Operations, Off-field Operations, Crop Monitoring, Precision Agriculture |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra Ltd, Yanmar Co., Ltd., SDF Group, TYM Corporation, Claas KGaA mbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autonomous Tractor Market Emerging Trajectories
Machine learning inference at the edge is compressing obstacle detection latency, while regulatory divergence between Washington and Brussels fragments certification strategies, and Brazilian fleet operators pioneer unmanned night-shift models that reshape service contract structures.
Neural network-based crop canopy segmentation is overtaking rule-based computer vision for real-time implement depth adjustment. Large-scale Iowa and Illinois row-crop operators now specify deep-learning perception stacks in RFPs, displacing legacy Lidar-dominant architectures within three-year replacement cycles. This compression is forcing Tier 1 suppliers to reallocate R&D from hardware to software-defined perception pipelines.
The EU AI Act's risk classification framework for autonomous agricultural machinery triggers mandatory conformity assessments for systems above defined autonomy thresholds. German and French equipment manufacturers now embed explainability modules into decision-logging architectures to satisfy audit requirements. North American exporters face parallel compliance burdens, with Kansas-based OEMs adapting control software for dual certification pathways.
Fleet operators in Brazil's Mato Grosso region now contract autonomy-as-a-service through third-party fleet management platforms rather than capitalizing equipment directly. This unbundling shifts balance-sheet risk to specialized agricultural technology lessors who maintain sensor calibration and software update schedules. Similar structures are emerging in Australia's wheat belt, where drought-driven cash-flow constraints favor operational expenditure models over asset ownership.
Global Autonomous Tractor Market Segmentation
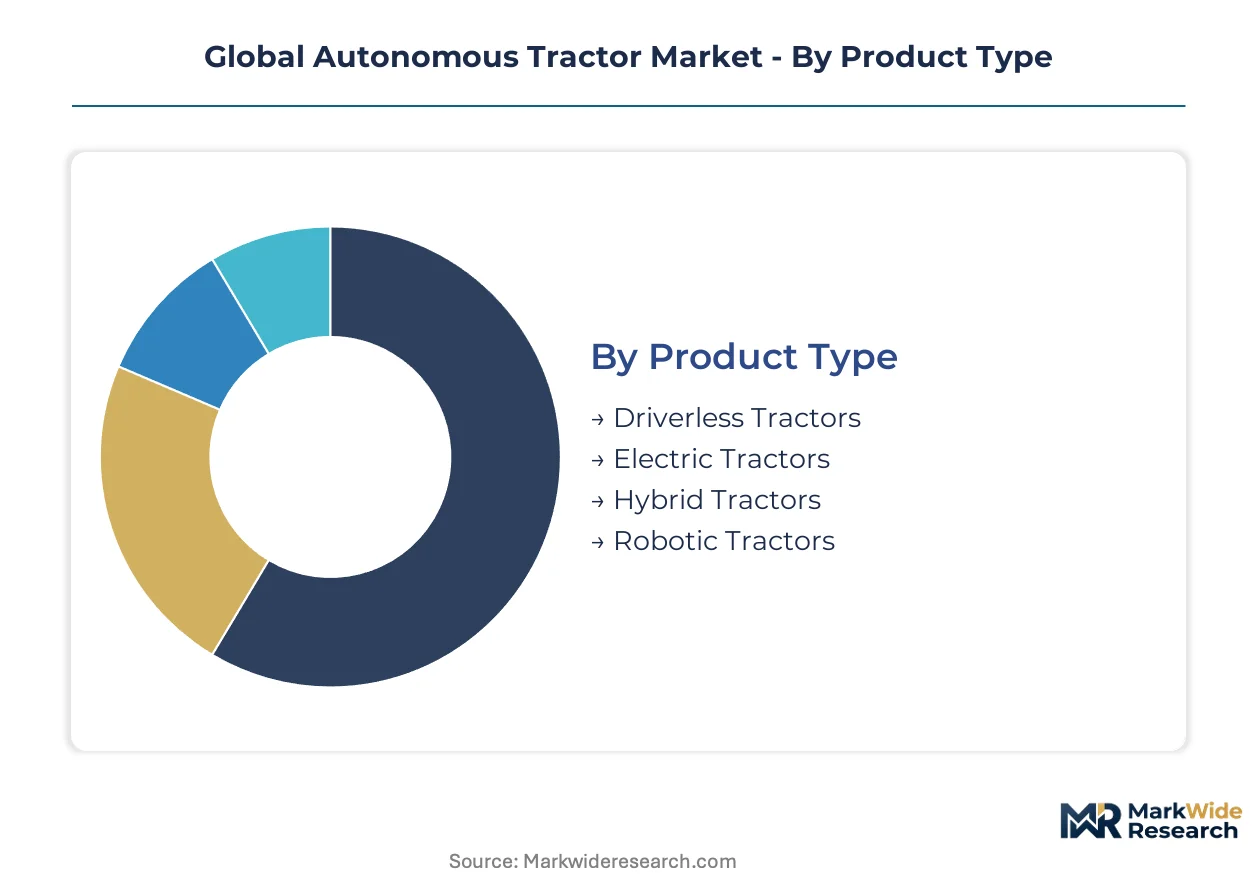
Segmentation reveals how autonomy technology diffuses across powertrain architectures, sensor modalities, and operational models. Each dimension exposes distinct supply chain vulnerabilities and customer willingness-to-pay thresholds that reshape vendor strategies.
Product Type:
Supply concentration in diesel-electric powertrain components and solid-state lidar fabs creates divergent margin structures across autonomous tractor architectures.
- Driverless Tractors:Diesel or CNG-powered platforms with full cab-delete configurations dominate commercial deployment through proven reliability in controlled field geometries. John Deere and AGCO Corporation anchor production in Iowa and Kansas manufacturing clusters where Tier 1 autonomy integrators co-locate final assembly.
- Electric Tractors:Battery-electric architectures face lithium-ion pack energy density ceilings that restrict continuous high-draw operations to sub-8-hour cycles without mid-field swapping infrastructure. CATL and BYD cell supply concentration from East Asian fabs creates input price volatility for European and North American OEMs attempting electrified autonomy stacks.
- Hybrid Tractors:Range-extended electric platforms with onboard generators bridge the gap between diesel reliability and electrification mandates, finding traction in EU Green Deal compliance scenarios where Machinery Directive 2006/42/EC certification complexity favors transitional architectures.
- Robotic Tractors:Compact sub-50hp units designed for specialty crop rows and vineyard configurations operate through swarm coordination rather than single-unit autonomy, with METI-funded Japanese consortia driving scaled-down stack development for fragmented Asian landholdings.
Today's leader: Driverless Tractors. Tomorrow's challenger: Electric Tractors.
Technology:
Cost tier differentiation separates subscription-based RTK-GPS correction networks from capital-intensive sensor fusion stacks requiring specialized calibration labor.
- GPS Guidance:RTK-corrected positioning delivers sub-inch accuracy through public and private base station networks across Kansas, Iowa, and Nebraska, displacing proprietary subscription locks and democratizing entry-level autonomy access for mid-scale grain operators.
- Lidar:Solid-state and mechanical spinning units provide 3D point-cloud mapping for obstacle detection in unstructured crop canopies, though dependence on East Asian component fabs creates supply risk that Tier 1 integrators mitigate through dual-sourcing strategies and strategic inventory buffers.
- Computer Vision:Multispectral and RGB camera arrays process real-time implement depth adjustment through rule-based algorithms, occupying a mid-cost tier between GPS-only and full sensor fusion configurations in Brazilian Mato Grosso soy belt procurement patterns.
- Machine Learning:Neural network-based perception pipelines now dominate RFP specifications from Iowa and Illinois row-crop operators, compressing obstacle detection latency through edge inference and displacing legacy Lidar-dominant architectures within three-year replacement cycles.
Machine Learning is gaining share fastest. GPS Guidance retains volume dominance.
End User:
Customer type determines whether autonomy deploys as owned capital equipment or operational expenditure through third-party fleet management platforms.
- Farms:Large-scale grain operations in the US Midwest and Brazil's expanding soy belt accelerate procurement of GPS-guided fleets to compress planting windows and mitigate rural workforce outflows, with direct ownership models prevailing where balance sheet capacity supports depreciation schedules.
- Agricultural Contractors:Custom tillage and planting service providers adopt semi-autonomous retrofit kits to reduce labor headcount while maintaining equipment utilization rates across dispersed customer fields, with AGCO Corporation's specialized conversion platforms anchoring this segment.
- Research Institutions:University extension services and USDA Agricultural Research Service stations validate autonomous implement configurations for Conservation Reserve Program compliance, generating field trial data that shapes subsidy-aligned demand specifications.
- Government Agencies:National agricultural regulators and farm digitization program administrators in EU member states procure demonstration fleets to validate Machinery Directive conformity assessment pathways, with German and French equipment manufacturers embedding explainability modules to satisfy EU AI Act audit requirements.
Farms command current procurement volume. Agricultural Contractors represent the steepest expansion trajectory.
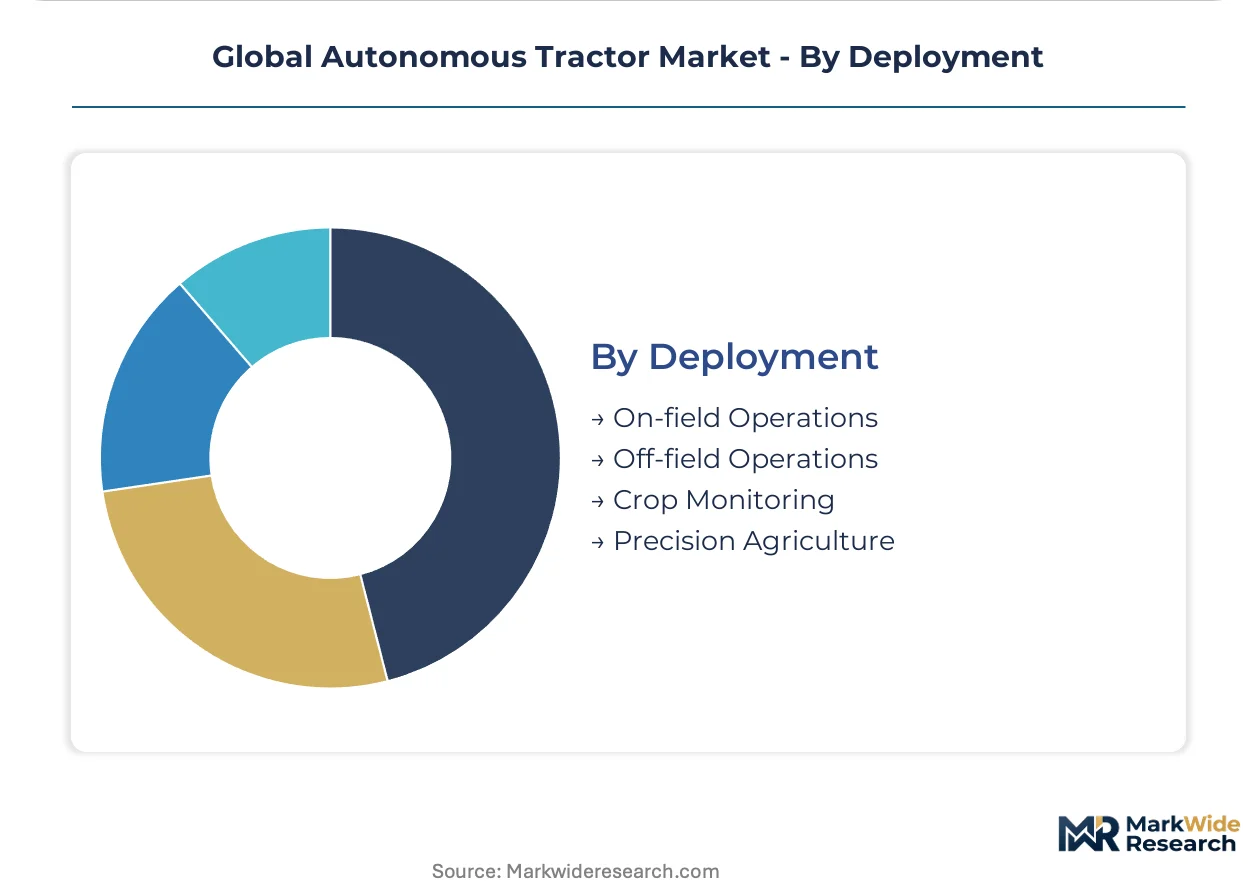
Deployment:
Application maturity separates proven on-field tillage operations from emerging precision agriculture service models requiring novel liability frameworks.
- On-field Operations:Tillage, planting, spraying, and harvesting executed without continuous human operator presence constitute the commercial core, with Brazil's Mato Grosso region pioneering unmanned night-shift deployment to maintain seasonal planting windows.
- Off-field Operations:Yard logistics, equipment transport, and maintenance bay automation remain underdeveloped due to unstructured obstacle environments and jurisdictional liability fragmentation between NHTSA and EU type-approval pathways.
- Crop Monitoring:Autonomous platforms equipped with multispectral sensors generate vegetation index maps for variable-rate input prescriptions, though this application often deploys through smaller robotic units rather than full-size tractor platforms.
- Precision Agriculture:Integrated autonomy stacks combining real-time implement control with sub-inch accuracy positioning enable outcome-based service contracts where agricultural technology lessors assume yield risk rather than equipment performance risk.
On-field Operations anchor revenue today. Precision Agriculture reshapes contract structures tomorrow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mechatronics talent concentrates in Midwestern US land-grant universities, German precision engineering corridors, and Japanese robotics clusters. These workforce pools anchor regional competitive advantages in autonomous tractor development.
United States
Large-scale grain operators across Iowa, Illinois, and Kansas compress planting windows through GPS-guided fleet procurement. USDA Conservation Reserve Program incentives reward sub-inch accuracy adoption, creating subsidy-aligned demand pull. The Iowa-Nebraska manufacturing corridor hosts final assembly clusters where Tier 1 autonomy integrators co-locate with OEM production facilities.
Germany
EU Green Deal farm digitization mandates force hardware refresh cycles across Bavarian and North Rhine-Westphalian grain cooperatives. Machinery Directive 2006/42/EC compliance deadlines accelerate replacement of legacy fleets with certified autonomous platforms. Stuttgart-based equipment manufacturers embed explainability modules to satisfy EU AI Act audit requirements for high-risk autonomous systems.
Brazil
Rural workforce outflows from Mato Grosso and Goiás soy regions accelerate unmanned night-shift deployment to maintain seasonal planting windows. ANVISA adaptation of type-approval frameworks addresses liability allocation between equipment OEMs and fleet operators during unmanned operations. São Paulo-based agricultural technology lessors pioneer autonomy-as-a-service contracts that shift balance-sheet risk from farm operators to specialized fleet management platforms.
Japan
METI-funded consortia accelerate JIS standard development for autonomous agricultural machinery through targeted R&D programs. Fragmented landholdings below 2 hectares in rural prefectures drive scaled-down autonomy stack development for compact robotic tractors. Nagoya-area precision equipment manufacturers supply swarm-coordination technologies for vineyard and specialty crop configurations.
India
Punjab-Haryana wheat corridor fragmentation creates retrofit kit penetration potential as Japanese consortium demonstrations validate scaled-down autonomy stacks. BIS certification pathways for unmanned ground vehicles remain under development, creating regulatory uncertainty for OEM market entry. Karnataka-based agricultural equipment assemblers explore technology licensing arrangements to bridge capability gaps in sensor fusion and edge computing.
Global Autonomous Tractor Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the autonomous tractor value chain. The market structure concentrates around integrated OEMs controlling full autonomy stacks, Tier 1 integrators supplying sensor fusion modules, and specialized retrofit providers extending conventional platforms. Three archetypes dominate: full-stack vertically integrated manufacturers, component-specialized autonomy integrators, and aftermarket conversion specialists. Competitive dynamics center on M&A activity consolidating sensor supply chains and strategic partnerships bridging software-hardware capability gaps.
Within the integrated OEM tier, John Deere and AGCO Corporation exemplify contrasting strategic positions. Deere anchors North American row-crop dominance through proprietary autonomy stack control, while AGCO occupies the retrofit-specialist vector with semi-autonomous conversion platforms. Kubota Corporation represents the Asia-Pacific scale-driven archetype, leveraging manufacturing footprint across Japanese and Southeast Asian production bases. These three players collectively illustrate how geographic origin and organizational structure shape competitive positioning without predetermining technology outcomes.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra Ltd |
| Yanmar Co., Ltd. |
| SDF Group |
| TYM Corporation |
| Claas KGaA mbH |
| Others |
Supply Flow & Price Mechanics
Family-owned Midwestern equipment manufacturers anchor production clusters in Iowa and Kansas, translating generational balance-sheet discipline into pricing rigidity that resists commodity swings even as East Asian component supply tightens.
Pricing Analysis
Bundled hardware-software subscriptions separate from unbundled retrofit kit procurement across customer archetypes. Tiered pricing separates full-stack autonomy platforms from GPS-guidance-only configurations, with certification grade under EU Machinery Directive 2006/42/EC commanding meaningful premiums. Cost compression in entry-level GPS tiers intensifies because public RTK network expansion eliminates proprietary subscription locks. Large-scale grain cooperatives in the US Midwest exhibit lowest price sensitivity, while fragmented holdings in India's wheat corridor demonstrate acute cost consciousness.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 autonomy integrators now mandate multi-supplier qualification for solid-state lidar modules and lithium-ion battery cells. Manufacturing concentrates in China, South Korea, and Japan for sensor components and energy storage systems. Raw material dependencies span rare-earth magnet supply for electric drivetrains, high-purity silicon for lidar receivers, and cobalt-nickel cathode formulations. Single-source vulnerability runs through East Asian solid-state lidar fabs. Distribution runs through OEM captive dealer networks and third-party agricultural equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Autonomous Tractor Market compounds steadily as labor shortages across Brazil's soy belt and the US Midwest create irreversible substitution pressure toward unmanned platforms.
For Market Incumbents: Cement technology leadership through captive control over RTK-GPS correction infrastructure and edge-computing silicon. Invest in ISO 18497 functional safety certification ahead of EU AI Act enforcement timelines. Defend against emerging retrofit specialists by embedding software update dependencies into hardware architectures.
For New Entrants and Emerging Players: Begin with scaled-down autonomy stacks for sub-50hp robotic tractors targeting Japan's fragmented vineyard holdings and India's sub-2-hectare wheat corridor. Agricultural contractors represent the most penetrable customer segment, with autonomy-as-a-service contracts enabling operational expenditure positioning against incumbent capital sales models.
For Investors and Strategic Acquirers: Valuations sit cheapest among Tier 1 autonomy integrators lacking downstream OEM relationships but possessing sensor fusion IP. Long-term viability centers on software-defined perception pipelines displacing hardware-heavy Lidar architectures. Watch neural network inference latency benchmarks as the inflection signal separating acquisition targets from stranded technology bets.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Module Acquisition | Captures machine learning perception IP ahead of Lidar displacement cycles. |
| RTK-GPS Infrastructure Partnership | Locks in sub-inch accuracy service revenue across Kansas and Nebraska grain belts. |
| EU AI Act Compliance Certification | Enables market access for high-risk autonomous system classifications in Germany and France. |
| Autonomy-as-a-Service Platform Launch | Shifts balance-sheet risk to Brazilian agricultural technology lessors in Mato Grosso. |
| Edge-Computing Silicon Development | Reduces onboard GPU costs through field-side base station inference offload. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 autonomy integrators, agricultural contractor fleet managers, and USDA extension service directors with secondary validation against SEC filings, customs trade data, EU Machinery Directive conformity assessment databases, and ISO standard development records. Bottom-up equipment shipment estimates triangulated against top-down farm digitization budget allocations.
Historical reference periods anchored the forecast window through documented procurement cycles and regulatory compliance deadlines. Segmentation modeling spanned powertrain architecture, sensor modality, operational deployment, and end-user ownership structure across the projection horizon. CAGRs derived from equipment replacement velocity and technology substitution elasticities, with neural network adoption curves and RTK network coverage expansion serving as primary forecast inputs.
Caveats apply where lithium-ion battery energy density breakthroughs or East Asian lidar supply disruptions could materially shift the outlook. Deviation in EU AI Act enforcement timelines or Brazilian ANVISA liability framework finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
South America Agricultural Sprayers Market