
 Agricultural Food Grade Rubber Conveyor Belt Market | 2026-2036
Agricultural Food Grade Rubber Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Food Grade Rubber Conveyor Belt Market Outlook
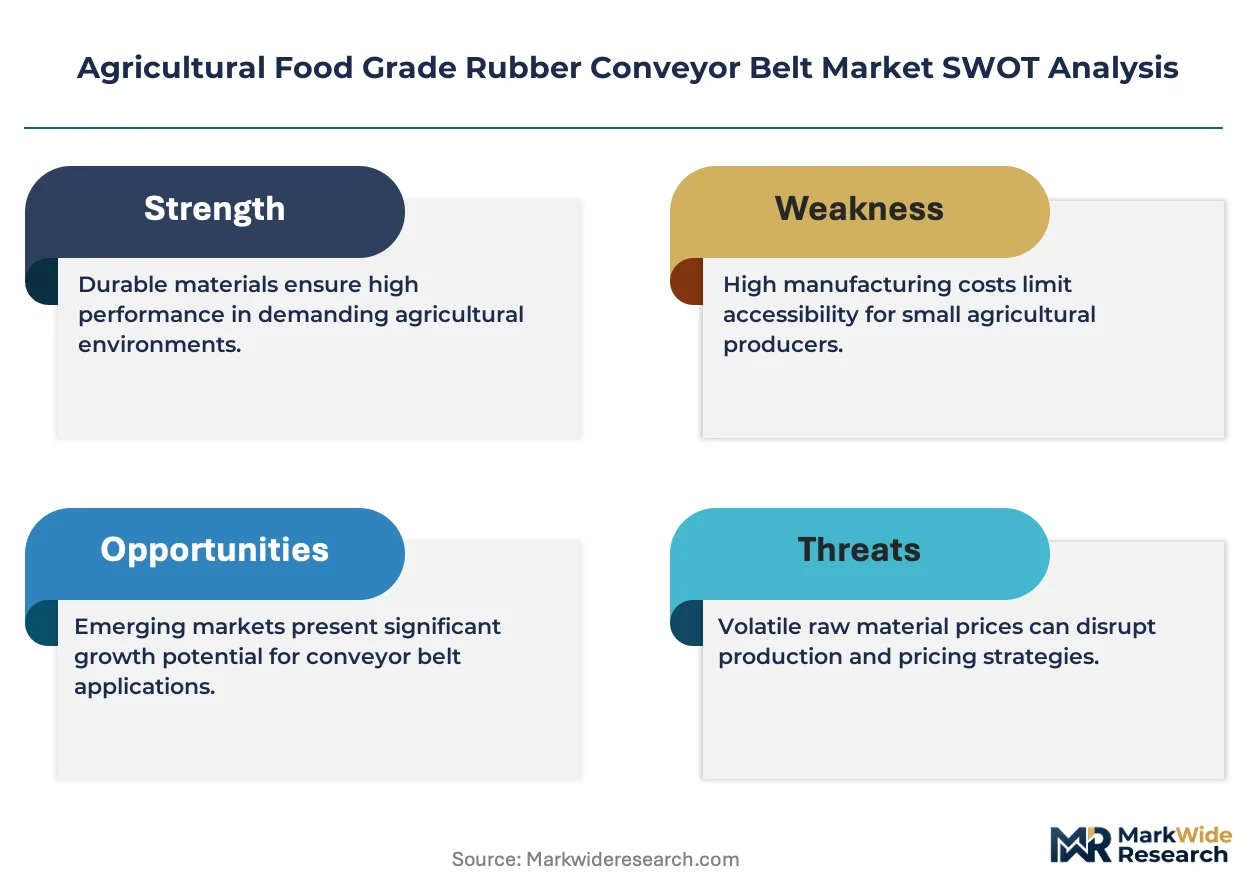
The EU Green Deal's Farm to Fork sustainability targets is repositioning procurement criteria across European grain cooperatives toward belts with verified recycled content and lower lifecycle carbon footprints. Continental AG leverages its integrated rubber compounding operations to control raw material quality from polymer sourcing through vulcanization. Bridgestone Corporation anchors its position through specialized fabric-reinforced designs engineered for high-tension grain elevator applications. Intralox differentiates via modular plastic alternatives that compete directly with rubber belts in sanitary washdown environments.
Agricultural food grade rubber conveyor belts are elastomeric fabric-reinforced endless loops manufactured with natural or synthetic rubber compounds, typically featuring multi-ply cotton, polyester, or nylon carcasses with working tensions between 160 and 800 newtons per millimeter, designed to transport harvested crops and processed foodstuffs without contamination or material degradation. Solid woven constructions dominate high-abrasion grain transport installations where belt longevity under silica-rich loads determines total cost of ownership. Polyurethane segments are capturing share in dairy and produce handling where thermal stability and chemical resistance justify premium positioning over conventional rubber. The rubber category itself remains the volume anchor across bulk commodity applications where cost per meter and field repairability sustain its incumbent status.
FDA Title 21 CFR compliance for direct food contact surfaces and EU Regulation 1935/2004 on materials intended for food contact shape product formulation requirements, migration testing protocols, and market access conditions for belt manufacturers serving regulated channels. USDA-FSIS sanitation standards for meat and poultry facilities further narrow acceptable belt architectures to designs supporting daily hygienic disassembly and high-pressure cleaning regimes. BIS certification requirements under India's Food Safety and Standards Authority mandate equivalent material safety documentation for imported belting entering the country's expanding cold chain infrastructure. Stakeholders must monitor how diverging national implementation timelines for food-contact substance inventories reshape competitive access across major agricultural export corridors.
Market Dynamics
The FDA's updated Food Safety Modernization Act requirements for sanitary conveying surfaces are compelling processors to upgrade legacy installations, compressing replacement cycles and elevating specification thresholds across grain handling infrastructure.
Growth Catalysts
- FSMA Sanitary Surface Mandates:FDA Title 21 CFR compliance requirements for direct food contact are accelerating belt replacement in commercial milling operations. Processors must eliminate porous legacy constructions that harbor bacterial contamination.
- Brazilian Grain Elevator Modernization:Large-scale infrastructure investments in Mato Grosso's soybean belt are generating concentrated demand for high-tension fabric-reinforced designs engineered for silica-rich bulk loads.
- Solid Woven Abrasion Resistance:Multi-ply cotton and polyester carcasses with working tensions between 160 and 800 newtons per millimeter are extending operational lifespans in high-wear grain transport applications.
Market Restraints
- Natural Rubber Price Volatility:Raw material cost swings in polymer sourcing disrupt margin stability for compounders lacking captive supply arrangements or integrated vulcanization operations.
- Modular Plastic Substitution:Intralox and competing modular plastic alternatives are capturing share in sanitary washdown environments where thermal stability and chemical resistance justify premium positioning over conventional rubber.
- EU Migration Testing Burden:EU Regulation 1935/2004 compliance protocols impose extended certification timelines and documentation requirements that constrain speed-to-market for new compound formulations.
Strategic Opportunities
- India Cold Chain Expansion:BIS certification requirements under FSSAI are creating structured entry pathways for compliant belting manufacturers as the country's agricultural export infrastructure modernizes.
- Recycled Content Verification:EU Green Deal Farm to Fork sustainability targets are repositioning procurement criteria toward belts with verified lifecycle carbon footprints and circular material credentials.
- Polyurethane Thermal Performance:Dairy and produce handling segments present white space where polyurethane segments justify premium positioning through superior chemical resistance and thermal stability characteristics.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Diverging national implementation timelines for food-contact substance inventories force manufacturers to maintain parallel compliance documentation for FDA, EFSA, and FSSAI regimes simultaneously.
- Legacy System Integration Friction:High-tension grain elevator retrofits require precise tensioning system recalibration and pulley alignment that extends installation downtime beyond standard maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Food Grade Rubber Conveyor Belt Market |
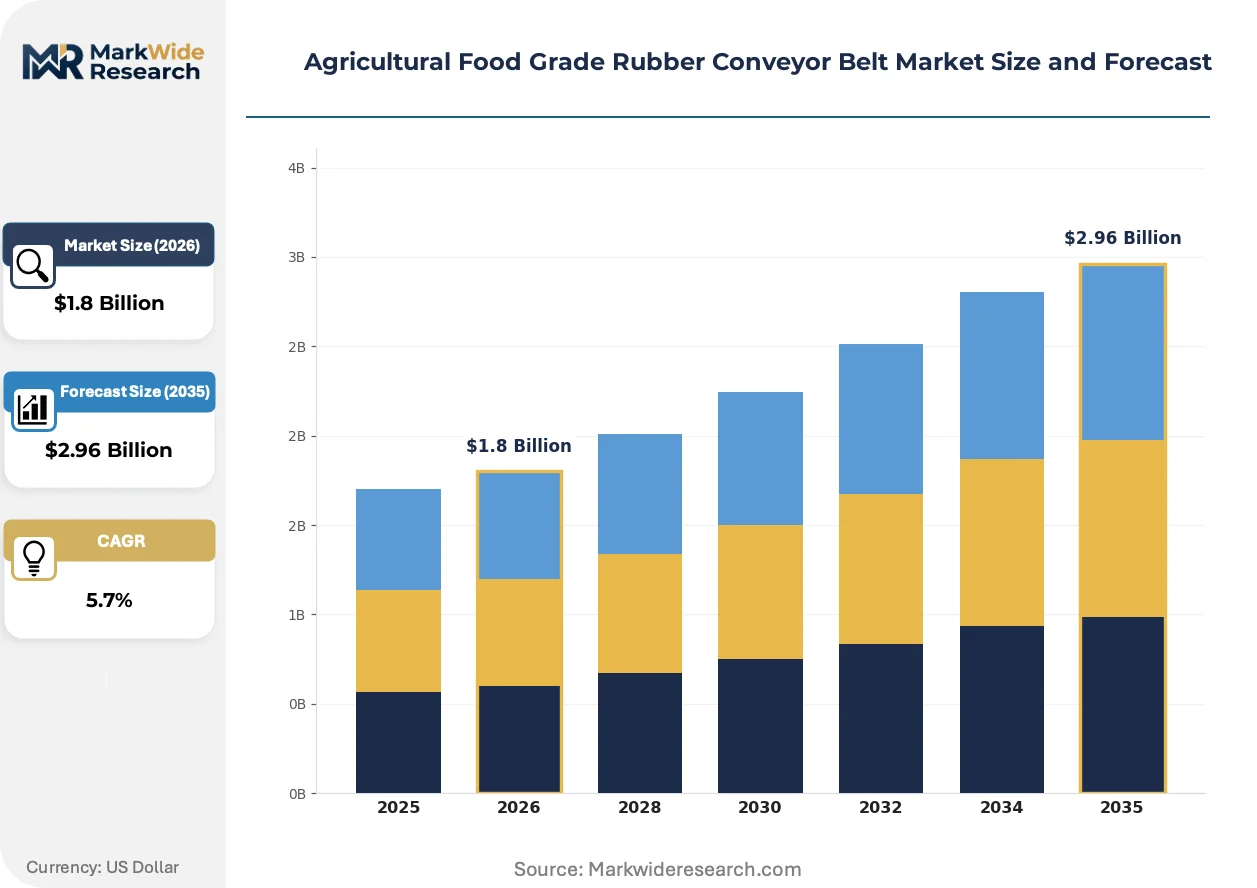
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Woven, PVC Coated, Polyurethane, Rubber End User: Agriculture, Food Processing, Warehousing, Logistics Application: Crop Handling, Grain Transport, Packaging, Bulk Material Distribution Channel: Direct Sales, Retail, E-Commerce, Distributors |
| Companies Covered | Intralox, Bridgestone Corporation, Continental AG, Goodyear Rubber Products, Inc., Trelleborg Slovenija D.O.O, Fenner Group, Habasit AG, Bando Chemical Industries, Ltd., Ammeraal Beltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Food Grade Rubber Conveyor Belt Market Strategic Shifts
Digital compound formulation tools and modular belt architectures are compressing product development cycles while sustainability verification protocols are rewiring procurement evaluation criteria across agricultural processing channels.
Thermoplastic polyurethane hybrid constructions are decentralizing the traditional rubber-dominated landscape in temperature-sensitive applications. Dairy cooperatives and fresh produce packers in Northern Europe are adopting these materials at accelerating rates to meet washdown intensity requirements. The technology is decentralizing specification authority from bulk commodity buyers toward sanitary-process engineers with distinct performance priorities.
EU Green Deal sustainability disclosure mandates are forcing compounders to document cradle-to-grave carbon intensity and recycled content percentages. REACH registration requirements for novel rubber additives are extending material qualification timelines by 18-24 months. European grain cooperatives are responding by consolidating supplier relationships with vertically integrated manufacturers capable of providing verified lifecycle documentation.
Grain elevator operators are unbundling belt procurement from installation and maintenance service contracts, treating these as separate spend categories with distinct vendor qualification criteria. This pattern is displacing the traditional bundled supply model in North American commercial milling operations. The shift is most visible across the US Midwest where cooperative buying groups are centralizing specification development while decentralizing installation execution to regional contractors.
Agricultural Food Grade Rubber Conveyor Belt Market Segmentation
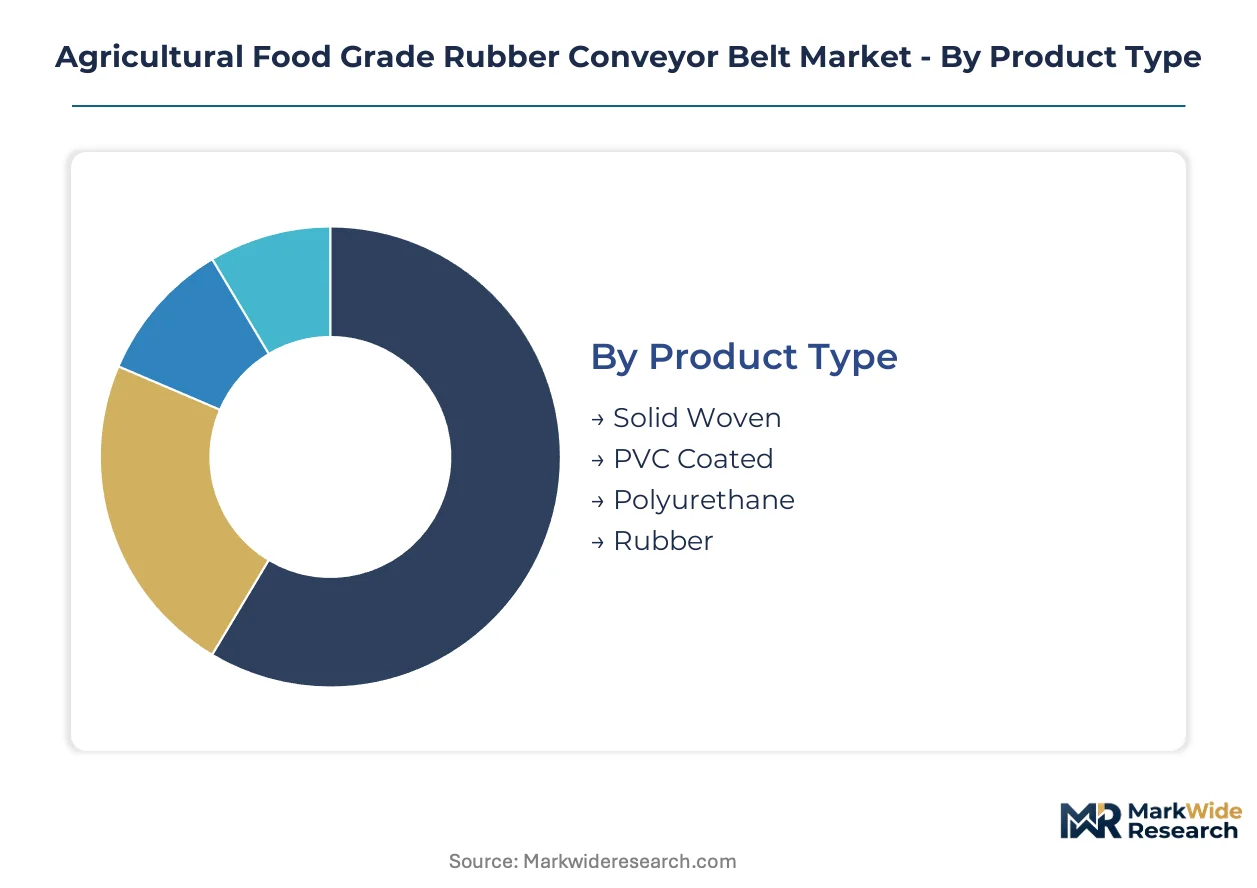
Segmentation in agricultural food grade rubber conveyor belts reveals how specification requirements diverge across crop types, processing intensities, and regulatory exposure levels. Procurement patterns in grain elevators differ fundamentally from dairy cooperatives or fresh produce packers.
Product Type:
Customization intensity spans from commodity rubber formulations to engineered polymer hybrids, with specification depth correlating directly to end-use regulatory scrutiny and thermal stress exposure.
- Solid Woven:Multi-ply cotton and polyester carcasses deliver working tensions between 160 and 800 newtons per millimeter. Demand concentrates in Brazil's Mato Grosso soybean belt where silica-rich grain loads accelerate wear cycles and total cost of ownership calculations dominate procurement.
- Polyurethane:Thermoplastic hybrid constructions provide superior chemical resistance and thermal stability for washdown-intensive environments. Dairy cooperatives in Northern Europe specify these materials to meet EU Green Deal sustainability disclosure mandates while satisfying daily hygienic disassembly requirements.
- PVC Coated:Synthetic polymer overlays on fabric substrates serve moderate-duty crop handling with cost-sensitive positioning.
- Rubber:Natural and synthetic elastomer compounds remain the volume anchor across bulk commodity applications where field repairability sustains incumbent status.
Leading the category by volume: Rubber. Expanding most quickly: Polyurethane.
End User:
Customer archetypes range from price-driven bulk commodity handlers to specification-intensive sanitary processors, with regulatory exposure determining margin architecture and service bundling preferences.
- Agriculture:Grain elevator operators and crop handling facilities prioritize abrasion resistance and tension ratings over surface finish specifications. Brazilian infrastructure investments in soybean logistics are modernizing handling systems and compressing replacement cycles.
- Food Processing:Milling operations and packaged food manufacturers face FDA Title 21 CFR compliance mandates for direct food contact surfaces. FSMA sanitary surface requirements are compelling processors to eliminate porous legacy constructions that harbor bacterial contamination.
- Warehousing:Cold storage and distribution centers require belts supporting temperature cycling and mechanical durability for palletized goods movement.
- Logistics:Third-party fulfillment operators balance acquisition cost against maintenance accessibility across multi-client material streams.
Fastest-growing demand segment: Food Processing. Highest volume concentration: Agriculture.
Application:
Functional requirements stratify by material abrasiveness, throughput velocity, and contamination risk exposure, with specification authority residing differently in each use case.
- Grain Transport:High-tension fabric-reinforced designs engineered for silica-rich bulk loads dominate commercial milling infrastructure. Solid woven constructions extend operational lifespans where abrasive mineral content determines maintenance scheduling and capital planning.
- Crop Handling:Fresh produce and root vegetable processing demands surface finishes compatible with gentle product handling and rapid hygienic turnover. Polyurethane segments justify premium positioning through thermal stability during washdown cycles.
- Packaging:Final-stage conveying requires precise speed control and surface friction coefficients for label adhesion and package stability.
- Bulk Material:Aggregate and unprocessed agricultural commodities tolerate heavier wear profiles and less frequent surface sanitization protocols.
Steepest expansion trajectory: Crop Handling. Volume anchor: Grain Transport.
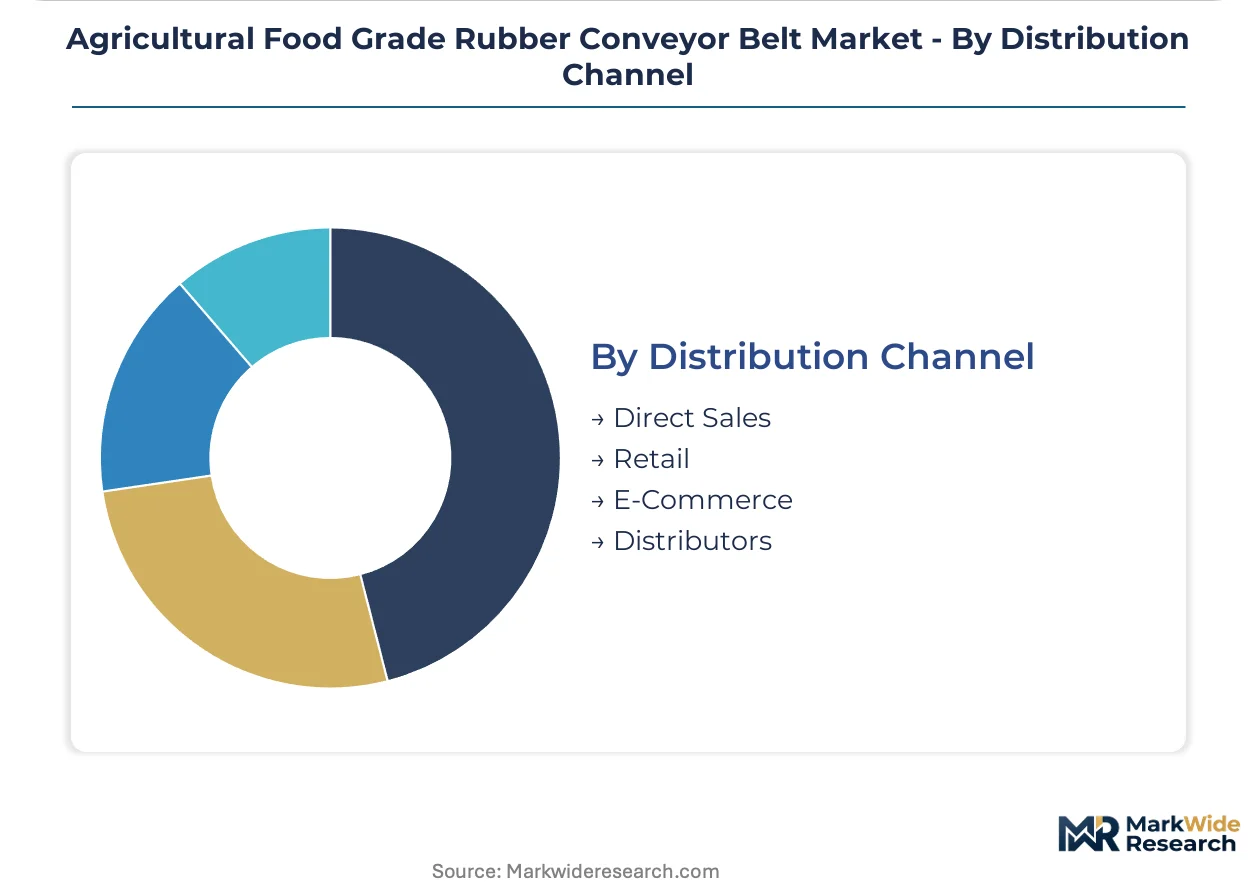
Distribution Channel:
Channel selection reflects purchase scale, technical specification complexity, and the unbundling of procurement from installation services across cooperative buying groups.
- Direct Sales:Large-scale grain cooperatives and multinational food processors negotiate directly with compounders capable of providing verified lifecycle documentation and custom formulation. EU Green Deal sustainability verification requirements favor relationships with vertically integrated manufacturers.
- Distributors:Regional belting specialists maintain inventory depth and field engineering capacity for emergency replacement scenarios. US Midwest cooperative buying groups centralize specification development while decentralizing installation execution to these regional channels.
- E-Commerce:Standard-width replacement belts and maintenance consumables migrate to digital procurement platforms for smaller maintenance operations.
- Retail:Limited to emergency spares and narrow-width agricultural applications with minimal technical specification requirements.
Dominant by transaction value: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso's soybean belt anchors procurement intensity for high-tension fabric-reinforced designs, while regulatory divergence across major agricultural export corridors reshapes supplier access conditions.
Brazil
Large-scale grain elevators in Mato Grosso and Goiás are modernizing handling infrastructure at accelerating rates. ANVISA's food-contact material regulations are tightening documentation requirements for imported belting entering Brazilian cold chain networks. São Paulo-based distributors are consolidating specification authority for cooperative buying groups across the Center-West agricultural corridor.
United States
Commercial milling operations throughout the Midwest are compressing replacement cycles under FDA Food Safety Modernization Act mandates. USDA-FSIS sanitation standards for meat and poultry facilities are narrowing acceptable belt architectures to hygienic-disassembly designs. Iowa and Illinois grain cooperatives are unbundling procurement from installation services, treating these as separate vendor qualification categories.
Germany
EU Green Deal Farm to Fork sustainability targets are repositioning procurement criteria toward verified recycled content and lifecycle carbon documentation. REACH registration requirements for novel rubber additives are extending material qualification timelines for compounders serving European grain cooperatives. Bavarian and North Rhine-Westphalia processing clusters are consolidating supplier relationships with vertically integrated manufacturers capable of providing cradle-to-grave verification.
India
Cold chain infrastructure expansion is generating structured demand for BIS-certified belting under FSSAI food safety mandates. The country's agricultural export corridor modernization is concentrating specification development in Maharashtra and Gujarat processing hubs. Mumbai and Ahmedabad distributors are capturing share from direct sales channels through inventory depth and regional field engineering capacity.
China
Grain handling infrastructure upgrades across the Northeast Plain and Yangtze River Delta are sustaining volume demand for solid woven constructions. SAMR food-contact material standards are converging toward FDA-equivalent migration testing protocols for export-oriented processors. Shandong Province rubber compounding clusters are integrating vulcanization operations to control raw material quality from polymer sourcing through finished belt production.
Agricultural Food Grade Rubber Conveyor Belt Market Competitive Environment
The competitive structure tilts toward integrated compounders with captive rubber sourcing and vulcanization capabilities. Tiered positioning separates vertically integrated manufacturers capable of lifecycle documentation from regional fabricators competing on field repairability and emergency replacement velocity. Three archetypes dominate: polymer-to-belt integrators controlling formulation quality, modular plastic specialists competing in sanitary washdown niches, and regional distributors capturing unbundled installation services. Capacity expansion and sustainability verification partnerships constitute the dominant competitive moves across the vendor base.
Among integrated compounders, Continental AG exemplifies the polymer-to-belt archetype through its controlled rubber compounding operations. Bridgestone Corporation anchors the high-tension fabric-reinforced segment with specialized designs for grain elevator applications. Intralox occupies a distinct position representing modular plastic alternatives that compete directly with rubber constructions in thermal-stability-sensitive environments. These three companies collectively illustrate how material technology specialization and vertical integration depth determine competitive positioning across regulatory-intensive agricultural processing channels.
| Leading Market Players |
|---|
| Intralox |
| Bridgestone Corporation |
| Continental AG |
| Goodyear Rubber Products, Inc. |
| Trelleborg Slovenija D.O.O |
| Fenner Group |
| Habasit AG |
| Bando Chemical Industries, Ltd. |
| Ammeraal Beltech |
| Others |
Value Chain & Pricing Dynamics
Natural rubber futures on the Singapore Exchange and Tokyo Commodity Exchange cascade through compounder cost structures into three distinct pricing tiers across agricultural food grade rubber conveyor belt procurement. Silica-rich grain transport specifications in Brazil's Mato Grosso soybean belt command premium positioning tied to abrasion resistance outcomes, while standard FDA-compliant formulations serve mid-tier milling operations and economy-grade constructions address price-sensitive bulk commodity handlers.
Pricing Analysis
Value-based pricing anchored to operational uptime and total cost of ownership calculations dominates high-tension grain elevator applications where belt longevity determines capital planning cycles. Three-tier pricing structure across premium polyurethane thermal-performance specifications, standard solid-woven FDA-compliant constructions, and economy-grade multi-ply rubber formulations reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because of modular plastic substitution pressure from Intralox and competing thermoplastic alternatives. Grain cooperatives in the US Midwest exhibit highest price sensitivity, while dairy cooperatives in Northern Europe prioritize thermal stability over acquisition cost.
Supply Chain Analysis
Brazil's ANVISA local-content documentation mandates for food-contact materials are reshaping sourcing patterns toward domestic distributors with verified supply chain transparency. Manufacturing gravity centers on Germany, China, and the United States where integrated compounders control captive rubber sourcing through vulcanization operations. Raw material dependencies draw from Southeast Asian natural rubber plantations, synthetic polymer feedstocks from petrochemical complexes, and fabric carcass textiles from textile manufacturing regions. Single-source vulnerability concentrates in natural rubber supply channels exposed to climate-induced harvest volatility. Distribution runs through direct sales relationships with large-scale grain cooperatives alongside regional distributor networks providing emergency replacement inventory depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural food grade rubber conveyor belt market sits in a material-transition phase as thermoplastic polyurethane hybrids displace conventional rubber in washdown-intensive dairy and produce handling segments. This technology displacement creates divergent strategic imperatives across incumbent compounders, emerging material specialists, and capital allocators evaluating sector exposure.
For Market Incumbents: Lock in sustainability verification partnerships with EU grain cooperatives demanding cradle-to-grave carbon documentation under Farm to Fork mandates. Deepen backward integration into rubber compounding operations to insulate margin stability from Singapore Exchange natural rubber futures volatility. Prioritize certification investment for BIS-compliant constructions serving India's expanding cold chain infrastructure against emerging regional fabricators.
For New Entrants and Emerging Players: Begin with polyurethane thermal-performance specialization targeting Northern European dairy cooperatives where daily hygienic disassembly requirements justify premium positioning over incumbent rubber constructions. The most penetrable white space sits in temperature-cycling cold storage applications across Maharashtra and Gujarat processing hubs where BIS certification creates structured entry pathways. Pursue regional distributor partnerships rather than direct sales channel establishment to accelerate field engineering credibility.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier compounders with captive vulcanization capabilities in Shandong Province and North Rhine-Westphalia processing clusters where REACH registration timelines constrain new formulation introduction. Long-term viability across the analysis window hinges on verified recycled content credentials and circular material recovery infrastructure. Monitor EU Green Deal implementation velocity as the primary inflection indicator for sustainability-premium realization in procurement criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive polymer sourcing insulates Continental AG and Bridgestone from Singapore Exchange futures volatility. |
| Sustainability Verification Partnership | EU grain cooperatives consolidate supplier relationships with manufacturers providing cradle-to-grave carbon documentation. |
| Polyurethane Thermal Performance R&D | Dairy cooperatives in Northern Europe specify hybrid constructions for washdown intensity compliance. |
| BIS Certification Pathway Investment | FSSAI mandates create structured entry for compliant belting into Maharashtra and Gujarat cold chain hubs. |
| Regional Distributor Network Expansion | US Midwest cooperative buying groups decentralize installation execution to inventory-heavy regional channels. |
Study Parameters
Independent corroboration across compounder technical directors, grain elevator maintenance managers, and dairy cooperative procurement leads underwrites the qualitative findings in this study. Primary interviews with plant engineers at commercial milling operations, regulatory affairs specialists navigating FDA Title 21 CFR compliance, and aftermarket service heads at regional belting distributors combined with secondary validation from SEC 10-K filings of listed compounders, customs trade data on rubber belting imports, and ANVISA food-contact material registration databases. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition across product type segments—solid woven, polyurethane, PVC coated, and rubber constructions—drives the analytical framework over the projection horizon. End-user segmentation modeling incorporates agriculture, food processing, warehousing, and logistics demand patterns alongside application-specific throughput requirements for grain transport and crop handling. CAGRs derive from replacement cycle compression analysis under FSMA mandates and infrastructure modernization trajectories in Brazil's Center-West agricultural corridor. Migration testing protocol timelines under EU Regulation 1935/2004 and BIS certification pathways under FSSAI inform regulatory-access assumptions.
Underlying measurement precision varies by segment; polyurethane thermal-performance specifications carry tighter precision than commodity rubber formulations given concentrated buyer concentration in Northern European dairy cooperatives. Forecasts reflect assumptions on natural rubber price stability, regulatory implementation timelines, and modular plastic substitution velocity that could materially revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Power Tiller Market