
 Pesticide Detection Market | 2026-2036
Pesticide Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Pesticide Detection Market Analytics
Food testing laboratories are redrawing demand patterns in pesticide detection as commercial labs outpace government-run facilities in instrument procurement. Agilent Technologies leverages its chromatography portfolio to anchor positions in high-throughput food safety workflows. Thermo Fisher Scientific sustains R&D intensity across mass spectrometry platforms for multi-residue screening. Eurofins Scientific competes through geographic density of accredited testing sites, particularly across European agricultural corridors.
Pesticide detection encompasses analytical methods and instrumentation designed to identify, quantify, and monitor chemical residues in agricultural commodities, environmental matrices, and food products, typically achieving detection thresholds at parts-per-billion concentrations through chromatographic separation coupled with mass-selective detection. Its primary industrial purpose is to verify compliance with maximum residue limits and prevent contaminated products from entering commercial distribution. Liquid chromatography dominates installed base volumes due to versatility with polar and thermally labile compounds, while mass spectrometry captures expanding share as laboratories adopt multi-class screening protocols. Biosensors represent the fastest-growing technology segment, driven by demand for portable field-deployable units that reduce reliance on centralized laboratory infrastructure.
EFSA maximum residue level regulations, EPA tolerance assessments under FIFRA, and FDA enforcement through the Food Safety Modernization Act collectively shape instrument specifications, validation requirements, and laboratory accreditation standards across jurisdictions. These frameworks mandate documented analytical performance, traceable calibration, and periodic proficiency testing that directly determine market access for detection system vendors. Stakeholders must monitor evolving regulatory harmonization between Codex Alimentarius guidelines and national enforcement thresholds to anticipate procurement cycles and technology refresh timelines.
Market Dynamics
EFSA's tightening maximum residue level enforcement is compressing detection thresholds and forcing laboratories across Germany, France, and the Netherlands to retire legacy chromatography systems before standard depreciation cycles conclude. This regulatory acceleration is redrawing equipment procurement timelines and vendor competitive positioning.
Growth Catalysts
- Multi-residue screening protocols:Agricultural testing laboratories in Germany are consolidating compound classes into single analytical runs. This operational compression drives demand for high-resolution mass spectrometry platforms.
- EU Green Deal sustainable agriculture targets:National food safety authorities must verify reduced chemical input claims. EFSA-mandated residue documentation expands testing volumes across member states.
- Biosensor field deployment:Portable electrochemical detection units are penetrating vineyard and orchard operations in France. On-site screening reduces centralized laboratory sample backlogs.
Market Restraints
- Helium supply concentration:Gas chromatography systems depend on helium carrier gas sourced primarily from Qatar and Russia. Price volatility and export restriction risks threaten analytical continuity.
- Reference material scarcity:Certified pesticide standards for emerging agrochemicals face production bottlenecks. European Reference Materials inventory gaps delay method validation timelines.
- LC-MS/MS capital intensity:Triple quadrupole systems require seven-figure euro investments excluding facility retrofit costs. Small commercial laboratories in Portugal and Greece face financing barriers.
Strategic Opportunities
- Poland agricultural corridor expansion:Centralized grain export terminals along the Vistula River lack on-site residue verification. Mobile testing units can capture pre-shipment inspection contracts.
- AI-assisted spectral interpretation:Machine learning algorithms trained on EFSA compound libraries are converging with benchtop mass spectrometry. Reduced analyst training requirements expand addressable user base.
- Organic certification premium testing:Prohibited substance verification commands price multiples above conventional residue screening. Accredited laboratories in Denmark and Austria capture margin expansion.
Industry Challenges
- Analytical chemist specialization gaps:Mass spectrometry method development requires expertise in both chromatographic separation and ionization optimization. Vocational training pipelines in Spain and Italy fail to match retirement outflows.
- Proficiency testing coordination complexity:EFSA-mandated interlaboratory comparisons demand synchronized sample distribution across decentralized national reference laboratories. Logistics failures invalidate accreditation status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pesticide Detection Market |
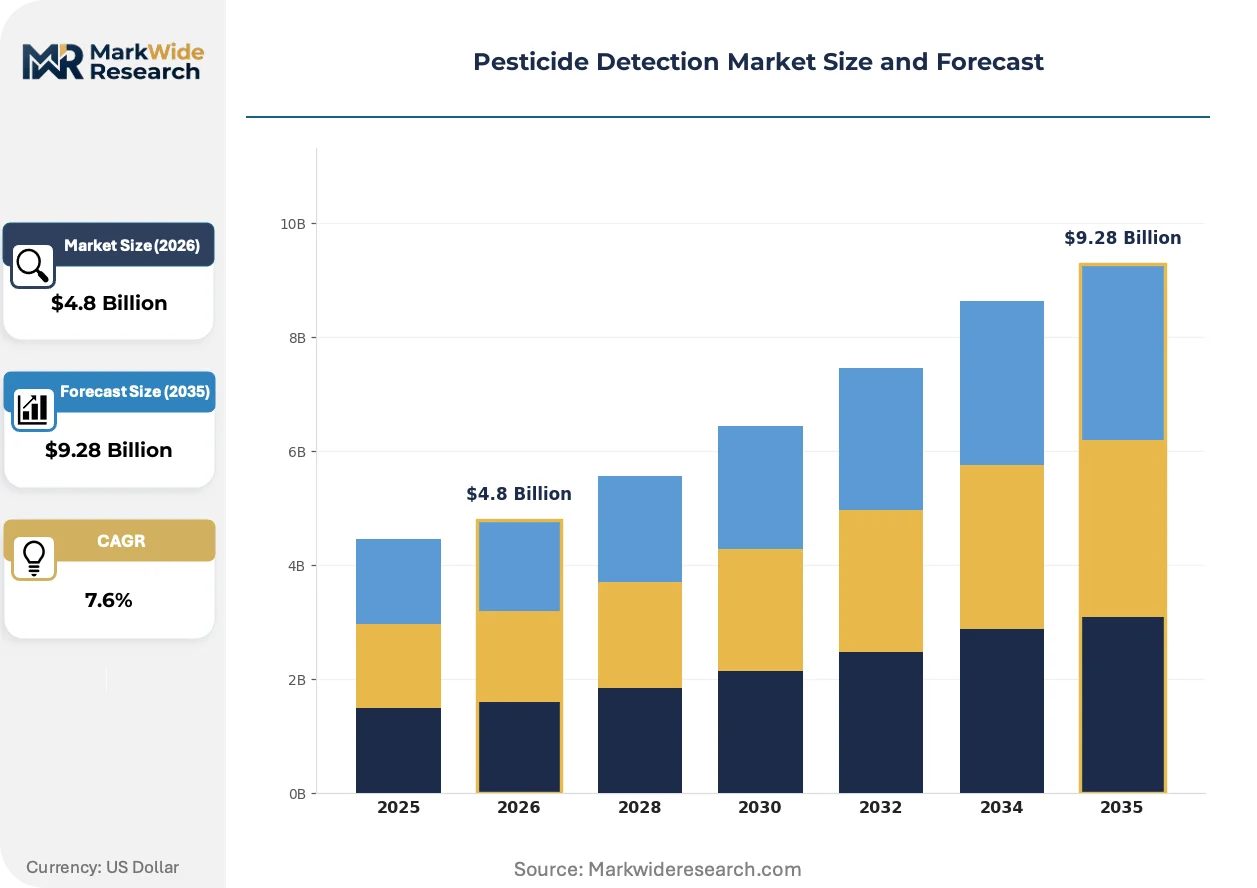
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
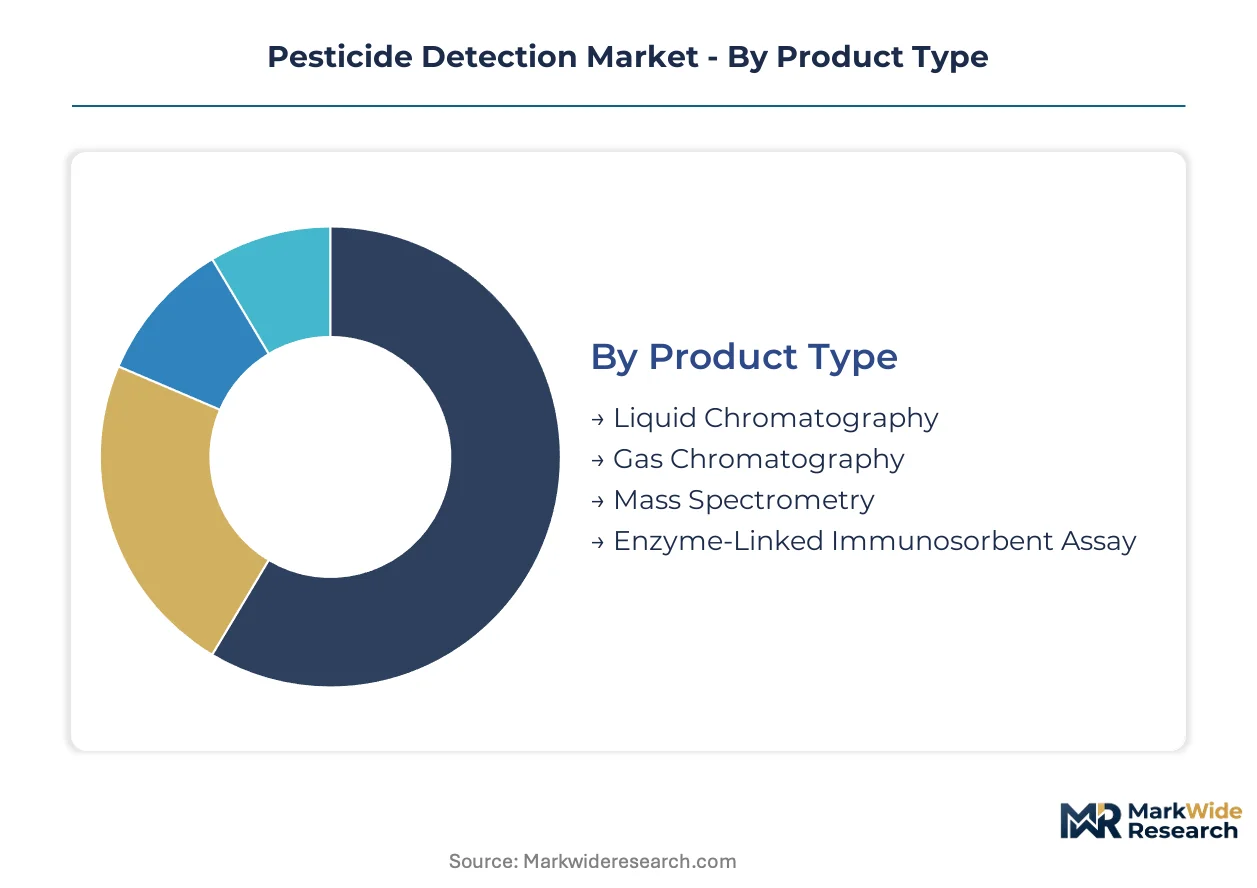
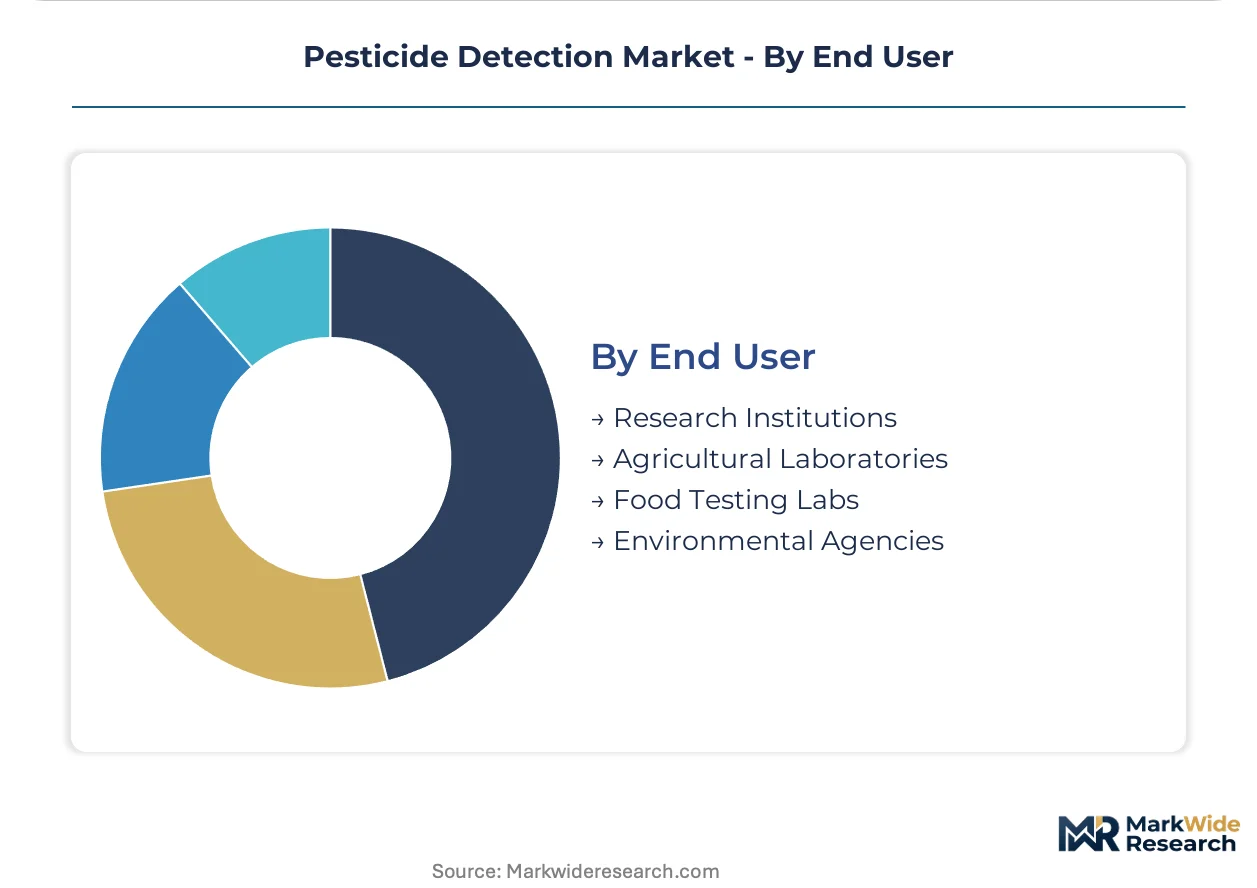
| Segmentation | Product Type: Liquid Chromatography, Gas Chromatography, Mass Spectrometry, Enzyme-Linked Immunosorbent Assay Technology: Optical Sensing, Biosensors, Chemical Sensors, Spectroscopy Application: Agricultural Testing, Soil Analysis, Water Quality, Food Safety End User: Research Institutions, Agricultural Laboratories, Food Testing Labs, Environmental Agencies |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Waters Corporation, Shimadzu Corporation, Sciex, Renka Bio, SGS, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pesticide Detection Market Evolving Landscape
Biosensor architectures and regulatory data requirements are compressing the traditional laboratory-to-field boundary in pesticide detection workflows. Equipment vendors and testing service providers are repositioning around speed-to-result and decentralized verification capabilities.
Electrochemical biosensor arrays incorporating aptamer-based recognition elements are miniaturizing detection footprints from benchtop systems to handheld devices. Wine cooperatives in Bordeaux and olive oil processors in Andalusia are piloting these units for pre-harvest screening. The technology is miniaturizing the analytical workflow from centralized laboratories to agricultural collection points, compressing result turnaround from days to hours.
EFSA's 2023 guidance on cumulative risk assessment mandates combined exposure modeling across pesticide mixtures. Food safety authorities in Belgium and the Netherlands must now validate multi-compound quantitative methods rather than single-residue protocols. High-resolution accurate mass spectrometry platforms are displacing nominal mass systems in accredited laboratories facing expanded analyte lists.
Commercial testing laboratories are unbundling instrument procurement from service contracts. German retail chains and Dutch agricultural cooperatives now lease detection capacity through per-sample pricing rather than capital acquisition. This consumption-based model concentrates purchasing power with Eurofins and SGS, squeezing independent regional laboratories in Bavaria and Saxony that lack scale for competitive unit economics.
Pesticide Detection Market Segmentation
Pesticide detection procurement channels diverge sharply by analytical sophistication required. Capital-intensive chromatography systems flow through direct vendor relationships with centralized laboratories, while portable biosensors penetrate agricultural cooperatives through distribution partnerships.
Product Type:
Direct sales dominate high-value chromatography and mass spectrometry installations, while immunoassay kits move through reagent distributors serving smaller laboratories.
- Liquid Chromatography:Reversed-phase and hydrophilic interaction columns separate polar pesticide metabolites thermally unstable for gas-phase analysis. German food safety authorities in Berlin and Munich drive centralized procurement of ultra-high-pressure systems for EFSA compliance verification.
- Mass Spectrometry:Triple quadrupole and high-resolution accurate mass platforms enable multi-residue screening with definitive compound identification. Agricultural testing laboratories in France and the Netherlands are displacing nominal mass systems to meet expanded analyte list mandates.
- Gas Chromatography:Electron capture and nitrogen-phosphorus detection target organochlorine and organophosphorus residues in fatty matrices. Helium supply constraints from Qatar and Russia threaten operational continuity for installed base systems.
- Enzyme-Linked Immunosorbent Assay:Antibody-based colorimetric screening provides cost-effective preliminary results for high-volume sample queues. Portuguese and Greek commercial laboratories deploy these kits as frontline filters before confirmatory chromatography.
By volume, Liquid Chromatography leads installed base counts across European food testing networks. By growth pace, Mass Spectrometry is climbing the fastest as multi-residue protocols consolidate analytical workflows.
Technology:
Cost tiers separate field-deployable electrochemical units from laboratory-grade optical platforms, with spectroscopy commanding premium positioning for regulatory documentation.
- Biosensors:Aptamer-functionalized electrochemical transducers achieve parts-per-billion sensitivity without chromatographic separation. Wine cooperatives in Bordeaux and olive oil processors in Andalusia pilot handheld units for pre-harvest screening.
- Spectroscopy:Infrared and Raman systems provide non-destructive fingerprinting for rapid identification. High capital requirements restrict adoption to accredited reference laboratories in Denmark and Austria.
- Optical Sensing:Fluorescence and absorbance-based detection enables real-time monitoring in continuous flow configurations. Water treatment facilities along the Rhine River corridor integrate these sensors for surface water surveillance.
- Chemical Sensors:Metal-oxide semiconductor and polymer-based arrays detect volatile organic compound signatures. Vineyard operations in Champagne deploy portable units for soil fumigant residue verification.
By maturity, Spectroscopy holds established positions in regulatory reference methods. By expansion trajectory, Biosensors are gaining share fastest as decentralized testing reduces laboratory infrastructure dependence.
Application:
Customer type determines validation rigor, with food safety applications demanding full analytical documentation and soil analysis permitting rapid screening approaches.
- Food Safety:Quantitative residue verification in fruits, vegetables, cereals, and animal products against EFSA maximum residue limits. Retail chains in Germany and the Netherlands mandate third-party laboratory certification for supplier compliance.
- Agricultural Testing:Pre-harvest and post-harvest screening of raw commodities for export qualification. Grain export terminals along Poland's Vistula River lack on-site verification capacity, creating mobile testing opportunities.
- Water Quality:Surface water, groundwater, and drinking water monitoring for pesticide runoff and leaching. Belgium's national environmental agency operates networked sampling stations for watershed contamination tracking.
- Soil Analysis:Persistent pesticide residue detection in agricultural land undergoing organic certification conversion. Austrian organic farming cooperatives commission comprehensive soil panels for prohibited substance verification.
By regulatory stringency, Food Safety commands highest analytical standards. By volume expansion, Agricultural Testing is accelerating as export documentation requirements multiply.
End User:
Procurement scale concentrates with food testing laboratories, while research institutions drive technology validation for subsequent commercial adoption.
- Food Testing Labs:Accredited commercial and government facilities performing regulatory compliance screening. Eurofins and SGS consolidate purchasing power through consumption-based service contracts, squeezing independent regional competitors.
- Agricultural Laboratories:Cooperative and private testing services supporting farmer advisory programs. Bavarian and Saxony regional laboratories face financing barriers to triple quadrupole system acquisition.
- Environmental Agencies:National and regional authorities monitoring ecosystem contamination and enforcing water quality directives. EFSA-mandated interlaboratory comparisons strain logistics coordination across decentralized national reference laboratories.
- Research Institutions:Universities and government research centers developing novel detection methodologies and validating emerging compound protocols. Spanish and Italian academic pipelines fail to match mass spectrometry specialist retirement outflows.
By instrument procurement value, Food Testing Labs dominate capital deployment. By methodological influence, Research Institutions shape subsequent commercial technology trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in pesticide detection infrastructure, connecting agricultural testing laboratories across Germany, Austria, and the Netherlands through integrated sample logistics networks.
Germany
Bavarian grain export terminals and Berlin's centralized food safety authority drive demand for ultra-high-pressure liquid chromatography systems. EFSA-mandated maximum residue level enforcement compels equipment upgrades ahead of standard depreciation cycles. The Munich-Stuttgart laboratory corridor concentrates accredited testing capacity for retail chain compliance programs.
France
Bordeaux wine cooperatives and Champagne vineyard operations pilot handheld biosensor units for pre-harvest screening. ANSM coordination with EFSA guidance shapes validation requirements for multi-residue protocols. The Rhône-Alpes agricultural belt hosts expanding commercial laboratory networks serving export documentation.
Netherlands
Rotterdam port authority pre-shipment inspection mandates and Dutch agricultural cooperative testing volumes sustain high-throughput mass spectrometry deployment. EFSA cumulative risk assessment requirements force method validation across expanded analyte lists. The Wageningen research cluster anchors technology transfer to commercial testing services.
Poland
Vistula River grain export terminals lack on-site residue verification capacity, creating mobile testing opportunities for pre-shipment contracts. EU Green Deal sustainable agriculture targets expand national testing volumes under EFSA oversight. The Poznań-Łódź agricultural corridor attracts accredited laboratory expansion.
Spain
Andalusian olive oil processors deploy electrochemical biosensors for soil fumigant residue verification. Spanish analytical chemist training pipelines fail to match mass spectrometry specialist retirement outflows. The Valencia-Murcia horticulture belt concentrates food safety laboratory demand for export certification.
Pesticide Detection Market Competitive Landscape
Concentration sits with diversified analytical instrumentation conglomerates and specialized testing service providers. The vendor base stratifies across three tiers: chromatography system manufacturers, mass spectrometry platform developers, and accredited testing laboratory networks. Strategic moves center on consumption-based service contract expansion and AI-assisted spectral interpretation technology licensing.
Among diversified instrumentation manufacturers, Agilent Technologies, Thermo Fisher Scientific, and Waters Corporation exemplify the chromatography-mass spectrometry convergence archetype. These entities occupy positions spanning benchtop systems to high-resolution accurate mass platforms. Within the testing services tier, Eurofins Scientific and SGS represent the geographic density model, anchoring competitive positioning through distributed accredited site networks rather than capital equipment sales.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Waters Corporation |
| Shimadzu Corporation |
| Sciex |
| Renka Bio |
| SGS |
| Eurofins Scientific |
| Others |
Value Network & Pricing Analysis
Helium-to-hydrogen carrier gas substitution in gas chromatography systems is simultaneously redrawing supply geography toward Eastern European hydrogen electrolyzer clusters and compressing per-analysis pricing economics for legacy GC-MS installations across German and French food safety laboratories.
Pricing Analysis
Volume-discount tiering structures separate multinational testing chains from independent regional laboratories. Three-tier pricing stratifies across premium certified-reference-laboratory rates, standard commercial-lab throughput pricing, and economy-tier portable biosensor per-sample fees. Cost compression in standard-tier chromatography services is intensifying because Eurofins and SGS negotiate enterprise-scale consumption contracts with instrument vendors. Small agricultural cooperatives in Portugal and Greece exhibit highest price sensitivity, while Berlin's centralized food safety authority commands lowest unit costs through consolidated procurement.
Supply Chain Analysis
Strategic helium stockpiling preferences among German and Dutch reference laboratories contrast with just-in-time reagent sourcing for immunoassay kits. Critical component supply concentrates in Germany, Japan, and the United States for high-resolution mass spectrometry platforms. Manufacturing draws from specialized ion source suppliers in Bavaria, detector fabrication facilities in Kyoto prefecture, and vacuum system producers in Massachusetts. Single-source vulnerability in helium carrier gas from Qatar and Russia threatens analytical continuity. Distribution runs through direct vendor relationships for capital equipment and reagent distributors for consumable kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA cumulative risk assessment mandates represent a regulatory inflection compressing detection thresholds and forcing technology refresh cycles, positioning the pesticide detection market for sustained high-growth disruption as laboratories retire nominal-mass systems ahead of standard depreciation timelines.
For Market Incumbents: Shield installed base positions through captive helium buffer stock arrangements and backward integration into certified reference material production. Agilent Technologies and Thermo Fisher Scientific must preempt hydrogen carrier gas validation investments before Eastern European electrolyzer capacity matures. Channel control over reagent supply agreements locks out emerging biosensor competitors from method validation workflows.
For New Entrants and Emerging Players: Anchor in Poland's Vistula River grain corridor where mobile testing units capture pre-shipment inspection contracts absent from incumbent laboratory networks. Polish agricultural cooperatives lack accredited on-site verification capacity. Portable electrochemical biosensor deployment through cooperative purchasing consortia bypasses capital intensity barriers facing independent regional laboratories.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European testing laboratory roll-ups consolidating Bavarian and Saxony regional competitors. Five-to-ten-year viability hinges on AI-assisted spectral interpretation technology licensing revenue streams displacing analyst-dependent service margins. The signal to watch is EFSA guidance expansion beyond pesticide mixtures into veterinary drug residue cumulative assessment.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Spectral Interpretation Licensing | Machine learning convergence with benchtop mass spectrometry reduces analyst training requirements and expands addressable user base. |
| Helium Buffer Stock Strategic Reserve | Preemptive carrier gas inventory insulates German reference laboratories from Qatar and Russia supply disruption risks. |
| Mobile Testing Unit Geographic Expansion | Pre-shipment inspection contracts in Poland's Vistula corridor capture volume absent from centralized laboratory networks. |
| Certified Reference Material Backward Integration | In-house production of pesticide standards closes European Reference Materials inventory gaps delaying validation timelines. |
| Consumption-Based Service Contract Conversion | Per-sample pricing models concentrate purchasing power with Eurofins and SGS against independent regional competitors. |
Research Methodology
Initial hypotheses were tested against primary input from analytical chemistry laboratory directors, EFSA regulatory affairs specialists, agricultural cooperative procurement managers, and chromatography system vendor account executives and refined through secondary validation against EFSA guidance documents, EPA tolerance assessment filings, EU Green Deal implementation reports, and customs trade data for analytical instrument imports. Bottom-up instrument installation counts triangulated against top-down market size estimates derived from vendor revenue disclosures.
Variance decomposition across technology segments, application types, and end-user categories shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, technology platform, application rigor, and end-user procurement scale. CAGRs were derived from installed base replacement cycles, regulatory mandate implementation timelines, and technology adoption curve analysis. Industry-specific forecast inputs encompass EFSA maximum residue level revision schedules and helium supply contract renewal patterns.
Material uncertainties — EFSA regulatory acceleration beyond modeled thresholds, helium export restriction events, and biosensor field-deployment reliability failures — sit outside the modeled envelope. Forecasts reflect assumptions regarding laboratory capital expenditure continuity and proficiency testing coordination logistics. Revision becomes warranted when EFSA cumulative risk assessment guidance expansion crosses thresholds forcing simultaneous multi-compound method validation across member state reference laboratories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Plant Disease Diagnostic Market