
 Agricultural Haying and Forage Machinery Market | 2026-2036
Agricultural Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Haying and Forage Machinery Market Intelligence
North American OEM supply chains for haying equipment is hardening around domestic casting and axle capacity. Deere & Company leverages its integrated drivetrain manufacturing to control lead times on self-propelled windrowers. CLAAS anchors European demand through its dominance in high-density large square balers. AGCO Corporation competes across multiple price tiers through its distributed brand architecture spanning Fendt, Massey Ferguson, and Challenger lines.
Agricultural haying and forage machinery encompasses mechanical systems designed to cut, condition, rake, ted, bale, and transport herbaceous crops at moisture levels between 15% and 65% wet basis, with throughput rates scaling from 20 to over 100 tonnes per hour depending on implement width and tractor power. These systems serve the primary commercial purpose of preserving nutritional value in grass-legume mixtures and crop residues for ruminant livestock feed. Balers generate the deepest margin pools due to precision knotter technology and density control systems that command replacement part revenues across machine life cycles. Mowers and conditioners lead unit volumes where dairy operations prioritize rapid wilting to minimize field losses. Tedder demand accelerates in organic farming applications where wide swath dispersal reduces reliance on chemical desiccants.
EPA Tier 4 Final and EU Stage V emission frameworks force engine downsizing and after-treatment packaging that reshapes hood geometry and weight distribution on self-propelled platforms. OSHA agricultural equipment guarding standards and ISO 4254 safety specifications dictate shielding and emergency stop architectures that influence industrial design priorities. Stakeholders must monitor how precision agriculture integration—yield mapping on balers, moisture sensing on mowers—creates data monetization opportunities beyond hardware sales.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission mandates are forcing powertrain redesigns that compress hood geometries and redistribute weight on self-propelled windrowers, fundamentally altering how manufacturers package after-treatment systems without sacrificing field performance.
Growth Catalysts
- Commercial Dairy Expansion:Large-scale operations in the Upper Midwest are mechanizing forage harvesting fleets to secure consistent feed quality across seasonal variations. This operational imperative drives replacement cycles and fleet standardization.
- Precision Agriculture Integration:Yield mapping on balers and moisture sensing on mowers creates data monetization pathways beyond hardware margins. Equipment vendors bundle analytics subscriptions with capital sales.
- Organic Farming Transition:Tedder demand accelerates where wide swath dispersal replaces chemical desiccants. European organic certification requirements amplify mechanical conditioning adoption.
Market Restraints
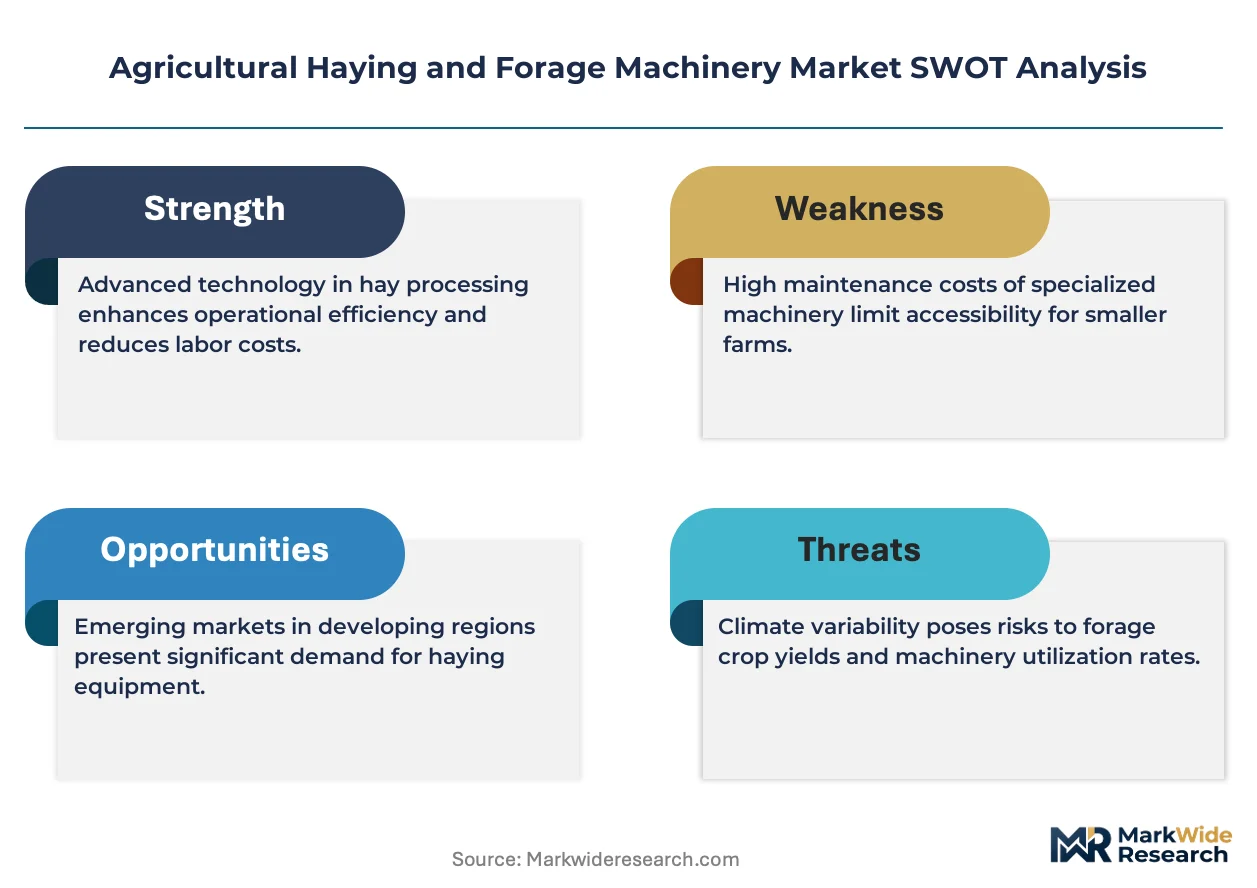
- After-Treatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add $15,000-$25,000 to self-propelled platform base costs. Price elasticity constrains mid-tier buyer conversion.
- Domestic Casting Capacity Limits:North American axle and transmission housing foundries operate at utilization rates above 85%. Lead time extensions freeze OEM production scheduling flexibility.
- Battery Energy Density Constraints:Current lithium-ion configurations cannot sustain 12-hour haying operations without mid-day charging infrastructure. Electrification timelines remain speculative.
Strategic Opportunities
- Autonomous Swathing Systems:GPS-guided windrowers converging with machine vision enable unmanned overnight operations. Dairy cooperatives in Denmark pilot 24-hour cutting windows.
- Remanufactured Component Channels:Knotter assemblies and density control systems generate recurring revenue through certified rebuild programs. Dealer networks capture service retention.
- Carbon Credit Stacking:Reduced tillage forage systems qualify for USDA Conservation Reserve Program incentives. Equipment financing bundles credit verification services.
Industry Challenges
- Embedded Software Expertise Gap:Hydraulic control firmware and ISOBUS protocol implementation require mechatronics engineers. Rural equipment dealerships struggle to recruit qualified technicians.
- ISO 4254 Compliance Timelines:Emergency stop architectures and PTO guarding redesigns demand validation testing that extends product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Haying and Forage Machinery Market |
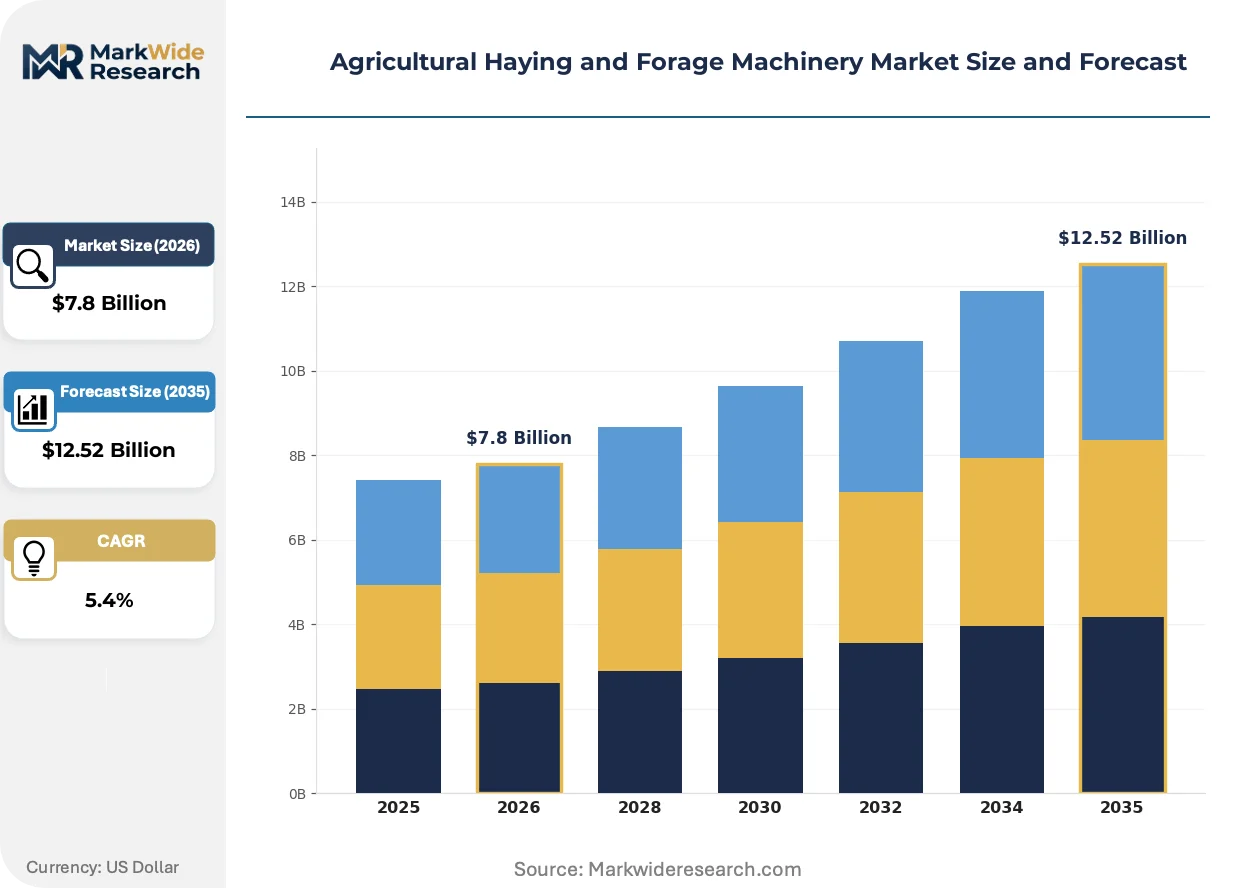
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balers, Mowers, Rakes, Tedders Technology: Conventional, Round, Square, Vertical End User: Commercial Farms, Livestock Operations, Cooperatives, Contractors Application: Dairy, Beef, Grain Production, Organic Farming |
| Companies Covered | Kubota Corporation, CLAAS, Deere & Company, New Holland, Vermeer Corporation, AGCO Corporation, Krone North America, Case IH, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Haying and Forage Machinery Market Strategic Shifts & Innovations
Digital sensing layers are penetrating mechanical haying equipment at an accelerating pace, converting traditional implements into data collection nodes that feed herd management software and farm enterprise resource planning systems.
Preservative application systems are converging with real-time moisture sensors to enable automated additive dosing during baling. Large dairy operations in Wisconsin and Minnesota deploy these integrated platforms to reduce dry matter losses below 8%. The technology is compressing traditional wilting windows from 48 hours to 24 hours, allowing second-cutting schedules to tighten.
EU Stage V non-road emission standards are compelling engine downsizing below 175 horsepower on mid-range self-propelled units. Manufacturers repackage after-treatment hardware beneath operator platforms rather than behind cooling stacks. This regulatory pressure most severely affects Italian and German OEMs serving mixed-crop livestock regions where power-to-weight ratios determine field efficiency.
Consolidated dairy cooperatives are unbundling equipment procurement from dealer service contracts. Buyers negotiate direct manufacturer pricing on baler fleets while sourcing maintenance through independent hydraulic shops. This channel fragmentation concentrates in the Netherlands and Denmark where cooperative buying power exceeds individual farm scale.
Agricultural Haying and Forage Machinery Market Segmentation
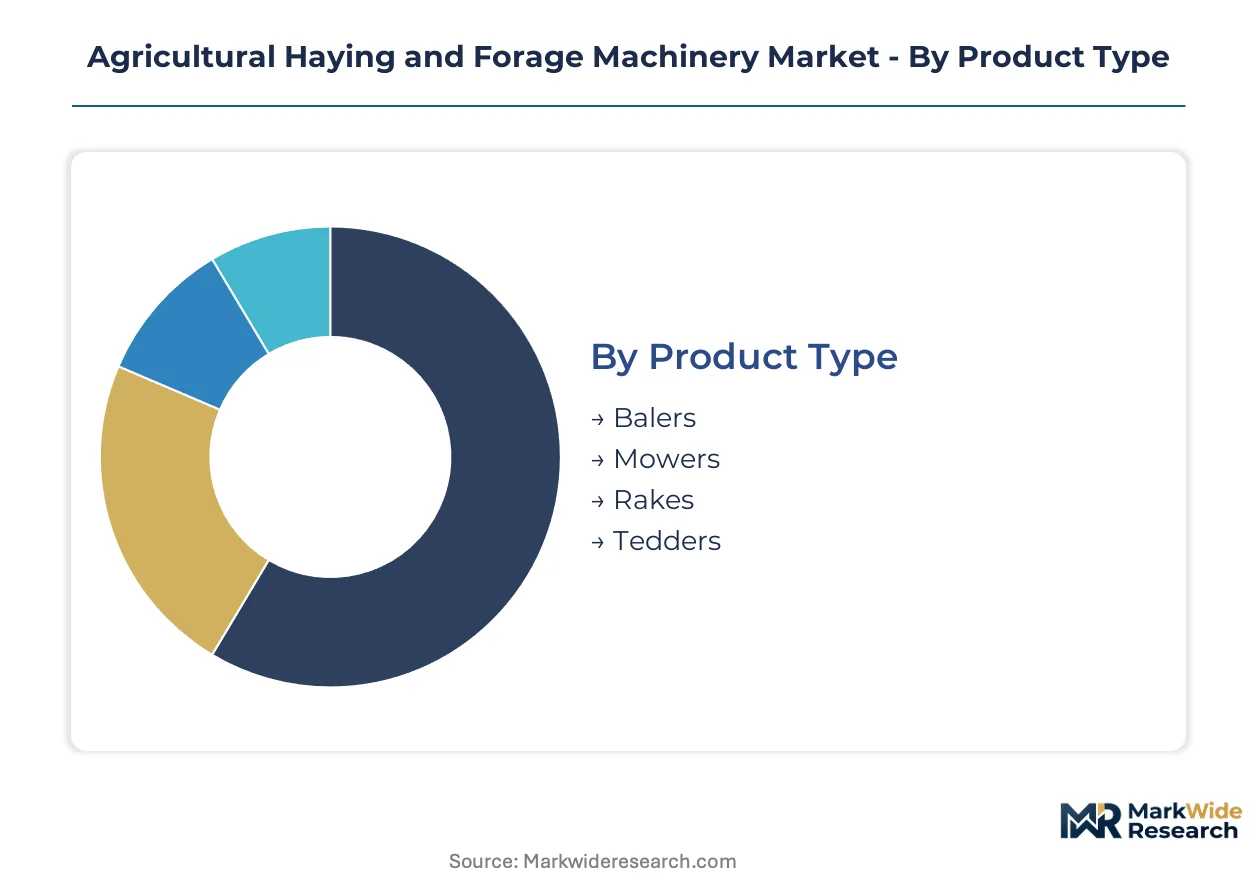
Segmentation in haying and forage machinery reveals how equipment specifications align with operational scale, crop type, and regulatory environment. Manufacturers configure product architectures around distinct moisture windows, bale density requirements, and fleet integration protocols that vary sharply across dairy, beef, and organic systems.
Product Type:
Standardization dominates at the entry level where tractor-drawn implements serve mixed livestock operations, while customization intensifies in self-propelled platforms where cutting width and conditioning systems must match specific crop matrices.
- Balers:Knotter precision and density control systems define commercial value, with large square configurations commanding premium positioning in export hay markets. Dairy operations in Wisconsin and Minnesota prioritize preservative integration to compress wilting windows below 24 hours.
- Mowers:Disc and sickle-bar architectures serve distinct crop conditions, with disc systems displacing traditional platforms in rocky terrain. Upper Midwest alfalfa producers drive specification demands for rapid conditioning to minimize respiration losses.
- Rakes:Rotary and wheel-rake designs segment by crop residue tolerance and ground contour following.
- Tedders:Wide swath dispersal systems accelerate organic adoption where chemical desiccant restrictions apply.
Leading the category by volume: Mowers. Expanding most quickly: Balers with integrated sensing layers.
Technology:
Cost tier stratification separates precision agriculture-enabled platforms from mechanical-only systems, with mid-range buyers facing acute trade-offs between automation depth and capital recovery timelines.
- Conventional:Mechanical control systems without ISOBUS integration serve price-sensitive contractors and smaller livestock operations. These platforms dominate secondary equipment markets where depreciation cycles extend beyond 15 years.
- Round:Variable chamber designs adapt to moisture fluctuations across grass-legume mixtures, with net-wrap systems displacing twine in commercial dairy applications. Beef cattle backgrounding operations in the Great Plains favor round bales for field storage logistics.
- Square:High-density large square configurations anchor export hay and dairy TMR ration consistency requirements.
- Vertical:Specialized pick-up and feeding systems integrate with mixer wagons in confined feeding operations.
Round technology holds the largest installed base. Square platforms gain share fastest in dairy consolidation zones.
End User:
Customer type determines procurement channel structure, with cooperatives and contractors driving fleet standardization while commercial farms prioritize equipment-herd management software integration.
- Commercial Farms:Owner-operated dairies above 500 head standardize on manufacturer-direct purchasing with bundled analytics subscriptions. These buyers specify ISOBUS compatibility and telematics integration as baseline requirements.
- Livestock Operations:Beef cattle feedlots and backgrounding yards prioritize throughput over precision, favoring wider cutting widths and simpler maintenance protocols.
- Cooperatives:Consolidated buying power in Denmark and the Netherlands unbundles equipment procurement from dealer service contracts.
- Contractors:Custom harvesters amortize capital across multiple farm clients, driving demand for rapid field-to-field transport configurations.
Commercial Farms represent the deepest revenue pool. Cooperatives show the steepest procurement volume growth.
Application:
Geography and certification requirements segment demand, with organic farming mandates in Europe and USDA Conservation Reserve Program incentives in the United States reshaping equipment specification patterns.
- Dairy:Nutritional consistency requirements drive investment in moisture sensing, preservative application, and bale weight uniformity. Large operations mechanize to secure year-round feed quality across seasonal variations.
- Beef:Extensive grazing systems prioritize field storage durability and handling efficiency over precision metrics. Backgrounding yards in Nebraska and Kansas favor robust twine systems for outdoor storage.
- Grain Production:Crop residue harvesting for cattle feed integrates with combine operations, requiring compatible header widths and transport logistics.
- Organic Farming:Mechanical conditioning replaces chemical desiccants, accelerating tedder and wide-swath mower adoption under EU organic certification frameworks.
Dairy commands the highest equipment specification intensity. Organic Farming shows the fastest technology refresh rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alfalfa cultivation in the Upper Midwest of the United States anchors commercial haying equipment demand. Dairy consolidation and corn silage production in Wisconsin, Minnesota, and Iowa drive fleet mechanization. Export hay markets in the Pacific Northwest and California's Central Valley command premium large square baler specifications.
United States
Commercial dairies above 500 head in Wisconsin and Minnesota standardize on self-propelled windrowers with integrated moisture sensing. EPA Tier 4 Final emission standards compel after-treatment packaging that redistributes weight on mid-range platforms. The Upper Midwest machinery corridor stretching from Moline, Illinois to Fargo, North Dakota concentrates OEM assembly and axle foundry capacity.
Germany
Mixed-crop livestock regions in Bavaria and Lower Saxony demand high-density large square balers for dairy TMR ration consistency. EU Stage V non-road emission standards force engine downsizing below 175 horsepower on self-propelled units. The Baden-Württemberg industrial cluster around Stuttgart anchors precision knotter manufacturing and hydraulic control system development.
France
Grass-legume mixtures in Normandy and Brittany drive disc mower-conditioner adoption for rapid wilting. EU organic certification requirements accelerate mechanical tedder deployment to replace chemical desiccants. The Auvergne-Rhône-Alpes region around Lyon concentrates forage equipment distribution networks serving consolidated dairy cooperatives.
Netherlands
Intensive dairy operations in Friesland and Gelderland unbundle equipment procurement from dealer service contracts through cooperative buying power. REACH chemical regulations influence preservative application system specifications on baler fleets. The Eindhoven-Arnhem corridor hosts ISOBUS protocol development for precision agriculture integration.
Denmark
Cooperative dairy structures in Jutland pilot GPS-guided autonomous swathing systems for 24-hour cutting windows. Danish organic farming mandates amplify wide-swath tedder demand across Zealand and Funen. The Aarhus-Tjele agricultural research cluster validates machine vision convergence with haying equipment automation.
Agricultural Haying and Forage Machinery Market Key Industry Players
Global majors compete with regional champions across emission compliance architectures and precision agriculture integration depth. Market structure concentrates around integrated drivetrain manufacturers, distributed brand holding companies, and specialized baler technology developers. Three archetypes dominate: full-line agricultural OEMs with captive foundry capacity, precision haying specialists with knotter technology leadership, and regional fabricators serving price-sensitive contractor segments. Competitive moves center on remanufactured component channel development and autonomous system pilot partnerships with dairy cooperatives.
Among full-line agricultural OEMs, Deere & Company and CLAAS exemplify contrasting integration strategies. Deere leverages in-house axle and transmission manufacturing to compress lead times on self-propelled platforms. CLAAS anchors European positioning through large square baler density control specialization. AGCO Corporation occupies a distributed architecture position across multiple price tiers through its Fendt, Massey Ferguson, and Challenger brand portfolio. These three represent how scale, regional focus, and brand stratification compete for commercial dairy fleet standardization decisions.
| Leading Market Players |
|---|
| Kubota Corporation |
| CLAAS |
| Deere & Company |
| New Holland |
| Vermeer Corporation |
| AGCO Corporation |
| Krone North America |
| Case IH |
| CNH Industrial |
| Others |
Cost & Logistics Intelligence
Cooperative unbundling of dealer service contracts in the Netherlands and Denmark forces manufacturers to restructure warranty offerings and compress margin pools on base equipment sales. This procurement shift compels OEMs to absorb after-treatment cost burdens while extracting recurring revenue through certified rebuild programs and analytics subscriptions.
Pricing Analysis
Warranty bundling varies sharply across buyer tiers: commercial dairies above 500 head negotiate manufacturer-direct pricing with unbundled maintenance, while mid-tier livestock operators face all-inclusive dealer packages. Three-tier pricing structure across premium, standard, and economy levels segments by precision agriculture integration depth and ISOBUS compatibility. Cost compression in mid-range self-propelled platforms intensifies because EPA Tier 4 Final after-treatment systems add fifteen to twenty-five thousand dollars to base configurations. Contractors and mixed livestock operations exhibit the highest price sensitivity, while consolidated cooperatives prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cooperative demand in Denmark and the Netherlands, while traditional dealer networks serve dispersed Upper Midwest dairy operations. Axle and transmission housing production draws from the United States, Germany, and Japan, with North American foundries operating above eighty-five percent utilization. High-grade steel, hydraulic control systems, and precision knotter assemblies constitute critical component dependencies. Single-source vulnerability concentrates in European engine after-treatment suppliers serving EU Stage V compliance requirements. Distribution runs through manufacturer-owned assembly facilities in Moline, Baden-Württemberg, and Aarhus, with regional parts depots maintaining dealer inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in agricultural haying and forage machinery is concentrating around captive control of axle foundry capacity and precision knotter technology. Players are racing to secure upstream manufacturing assets and downstream service retention channels.
For Market Incumbents: Lock in foundry capacity through long-term offtake agreements with Upper Midwest casting facilities before utilization rates harden further. Deepen backward integration into hydraulic control firmware development to offset mechatronics technician scarcity at rural dealerships. Defend against cooperative procurement unbundling by embedding analytics subscriptions into capital sales contracts. For New Entrants and Emerging Players: Capture autonomous swathing pilot opportunities with Danish dairy cooperatives piloting twenty-four-hour cutting windows. White-space exists in remanufactured knotter channel development for independent hydraulic shops serving price-sensitive contractors. Go-to-market positioning should emphasize carbon credit verification services bundled with equipment financing for USDA Conservation Reserve Program participants. For Investors and Strategic Acquirers: Re-rating potential sits with precision haying specialists given convergence of machine vision and GPS-guided automation. Long-term viability favors OEMs with integrated drivetrain manufacturing and established dealer service networks. Watch for inflection signals in dairy cooperative consolidation velocity across the Upper Midwest and Jutland peninsula.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Axle Foundry Capacity | Captive supply of transmission housings compresses lead times for self-propelled windrower platforms. |
| Autonomous Swathing System Pilot Partnership | GPS-guided overnight operations with Danish cooperatives validate machine vision convergence. |
| Remanufactured Component Channel Development | Certified rebuild programs for knotter assemblies generate recurring service revenue retention. |
| Precision Agriculture Analytics Subscription Bundle | Yield mapping and moisture sensing data monetizes beyond hardware margins for dairy fleet sales. |
| Carbon Credit Verification Service Integration | USDA Conservation Reserve Program incentive bundling differentiates financing for reduced tillage systems. |
Research Approach
Trade association filings, EPA certification databases, and EU Stage V compliance registries formed the secondary backbone for equipment specification and emission technology tracking. Primary interviews with agricultural OEM product managers, cooperative procurement officers, and rural dealership service heads validated production capacity constraints and procurement pattern shifts. Customs data on axle and transmission housing trade flows supplemented foundry utilization estimates. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against dairy herd consolidation trends.
Bottom-up modeling aggregated individual product category trajectories across balers, mowers, and self-propelled windrowers, while top-down analysis anchored aggregate market expansion to livestock feed demand and replacement cycle dynamics. Segmentation dimensions spanned product type, precision agriculture technology tier, end-user scale, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical equipment shipment patterns and forward-looking dairy consolidation projections. Forecast inputs incorporated foundry capacity utilization rates and organic certification penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density breakthroughs and autonomous equipment regulatory frameworks. Forecasts reflect base assumptions around emission standard continuity and cooperative buying power consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market