
 Captan Fungicide Market | 2026-2036
Captan Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Captan Fungicide Market Analytics
Market Dynamics
A capital-intensity divergence between integrated multinationals and regional formulators is redrawing competitive boundaries in the captan fungicide sector. Syngenta AG leverages its backward integration into active ingredient synthesis to sustain cost advantages across wettable powder and liquid formulations. BASF SE anchors its position through proprietary adjuvant technologies that enhance captan rainfastness, while UPL Ltd. competes aggressively on price in distributor networks across emerging agricultural economies.
Product and Application Landscape
Captan is a non-systemic phthalimide fungicide with approximately 50% chlorine content by molecular weight, functioning as a broad-spectrum contact protectant that inhibits spore germination through sulfhydryl group interference in fungal enzymes. Liquid formulations command premium positioning due to ease of tank-mixing and reduced operator exposure, whereas wettable powder variants retain dominance among cost-sensitive vegetable growers in developing markets. Application demand clusters heavily in fruit crops, where captan's pre-harvest interval flexibility supports intensive spray programs for stone fruit and berry production; ornamental applications represent a smaller but stable margin pool tied to nursery certification requirements.
Regulatory Environment and Outlook
The EPA governs captan tolerances under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU's REACH framework and pending Sustainable Use Regulation scrutinize its ecotoxicological profile for aquatic invertebrates. Brazil's ANVISA maintains distinct maximum residue limits that diverge from Codex Alimentarius standards, creating compliance complexity for exporters serving multiple destination markets. Stakeholders must monitor regulatory divergence between jurisdictions as a decisive factor in formulation investment and geographic prioritization.
Market Dynamics
The EPA's re-registration review for chlorinated pesticides is compressing formulation innovation timelines as residue tolerance protocols tighten across multiple jurisdictions simultaneously.
Growth Catalysts
- Post-harvest disease protocols:Specialty fruit producers in California's Central Valley are expanding captan applications for post-harvest fungal control, creating sustained demand for wettable powder formulations with extended residual activity.
- REACH framework scrutiny:The EU's pending Sustainable Use Regulation is accelerating substitution away from higher-risk fungicides, redirecting grower preference toward captan's established ecotoxicological profile.
- Humid subtropical pressure:Citrus and apple growers in Brazil's São Paulo state face escalating fungal disease incidence, concentrating procurement volumes for contact protectant chemistries.
Market Restraints
- Chlorine feedstock volatility:Captan's 50% chlorine content by molecular weight exposes formulators to caustic soda and chlorine gas price swings tied to energy-intensive chlor-alkali production.
- Aquatic ecotoxicity thresholds:The EU's REACH framework and EFSA aquatic invertebrate standards are constraining application windows near watersheds, limiting use in riparian orchard zones.
- Systemic fungicide competition:Triazole and strobilurin chemistries with curative activity are displacing captan in intensive spray programs where post-infection control is prioritized over prevention.
Strategic Opportunities
- ANVISA MRL harmonization gaps:Brazil's maximum residue limits diverge from Codex Alimentarius standards, creating compliance complexity that rewards formulators with multi-jurisdiction regulatory dossier capabilities.
- Adjuvant technology convergence:Proprietary rainfastness enhancers combined with drift reduction agents are opening premium positioning for liquid formulations in high-rainfall production zones.
- Nursery certification channels:Ornamental propagation facilities face tightening phytosanitary export requirements, generating stable margin pools for captan-based dip treatments in vegetative cutting certification programs.
Industry Challenges
- Residue analytical capacity:Commercial laboratories face backlogs in multi-residue screening for chlorinated phthalimide metabolites, delaying harvest clearance decisions for export-bound fruit shipments.
- Tank-mix incompatibility protocols:Captan's sulfhydryl reactivity creates formulation instability with alkaline pesticides and certain foliar fertilizers, requiring operator training investments and spray program redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Captan Fungicide Market |
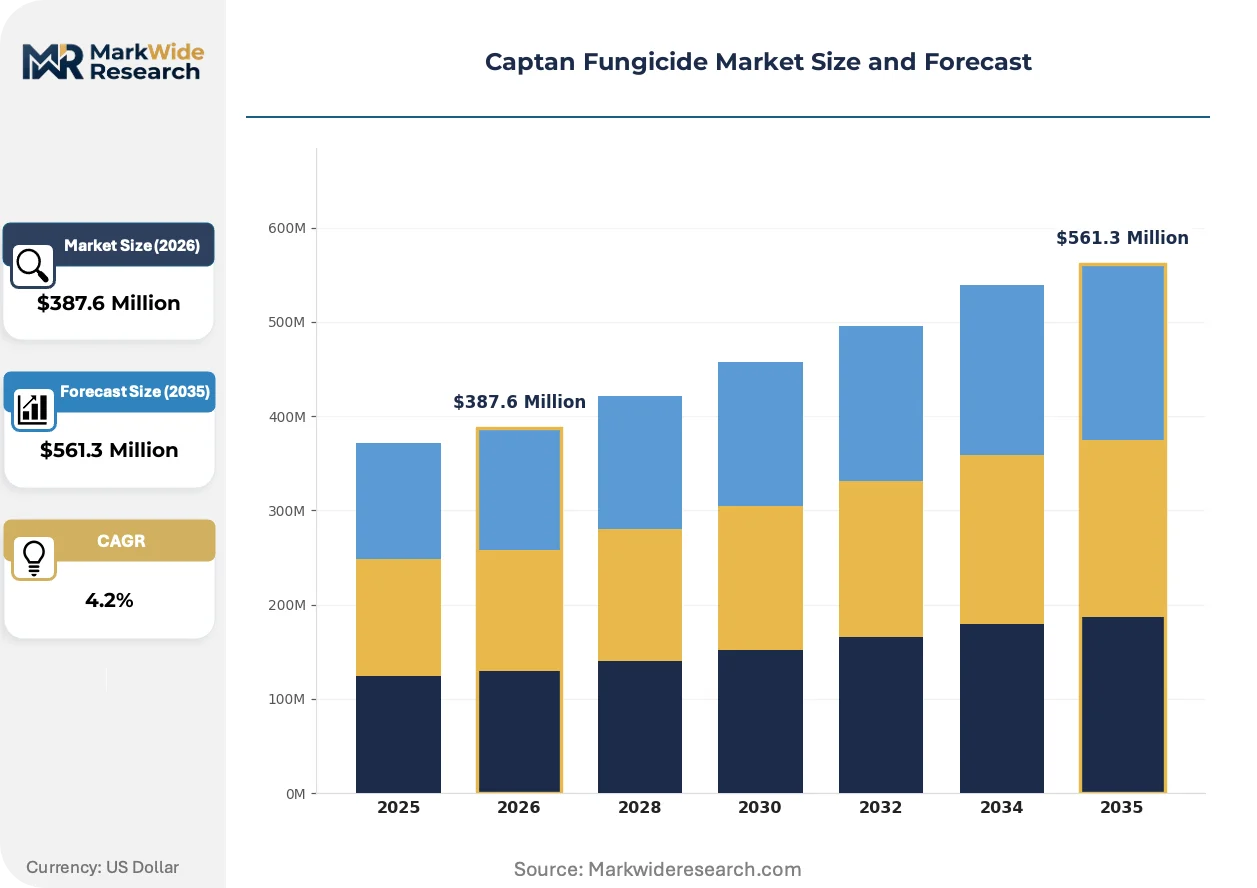
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $561.3 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wettable Powder, Granules, Liquid, Emulsifiable Concentrate Application: Fruit Crops, Vegetables, Ornamentals, Turf End User: Agricultural Producers, Home Gardeners, Lawn Care Professionals, Nurseries Distribution Channel: Online Retail, Agricultural Supply Stores, Direct Sales, Distributor Networks |
| Companies Covered | Syngenta AG, BASF SE, Bayer AG, Corteva Inc., FMC Corporation, Adama Agricultural Solutions Ltd., Nufarm Ltd., Sumitomo Chemical Company, UPL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Captan Fungicide Market Evolving Landscape
Formulation chemistry and application technology are converging to extend captan's utility window amid tightening residue standards and labor cost pressures in perennial crop systems.
Microencapsulation technology using polymer wall systems is extending captan release kinetics and reducing dermal operator exposure. Stone fruit growers in Washington State and Italian Emilia-Romagna are adopting these formulations for compressed pre-harvest intervals. The technology is displacing conventional wettable powders in high-value export-oriented production systems where residue compliance margins have narrowed.
The EPA's residue tolerance recalibration under FIFRA Section 3 is compressing maximum permissible levels for chlorinated fungicides on pome and stone fruits. This regulatory tightening is forcing reformulation investments and label expansion into minor crops to sustain active ingredient volumes. Brazilian citrus exporters serving EU destination markets are most affected, accelerating adoption of buffer zone modeling software and drift mitigation equipment.
Consolidation among distributor cooperatives in California's Central Valley is compressing supplier negotiation cycles and unbundling technical advisory services from product procurement. Large grower-shipper organizations are establishing direct supply relationships with formulators, bypassing traditional retail agronomy channels. This pattern is most visible in table grape and berry operations where spray program customization drives input selection decisions.
Captan Fungicide Market Segmentation
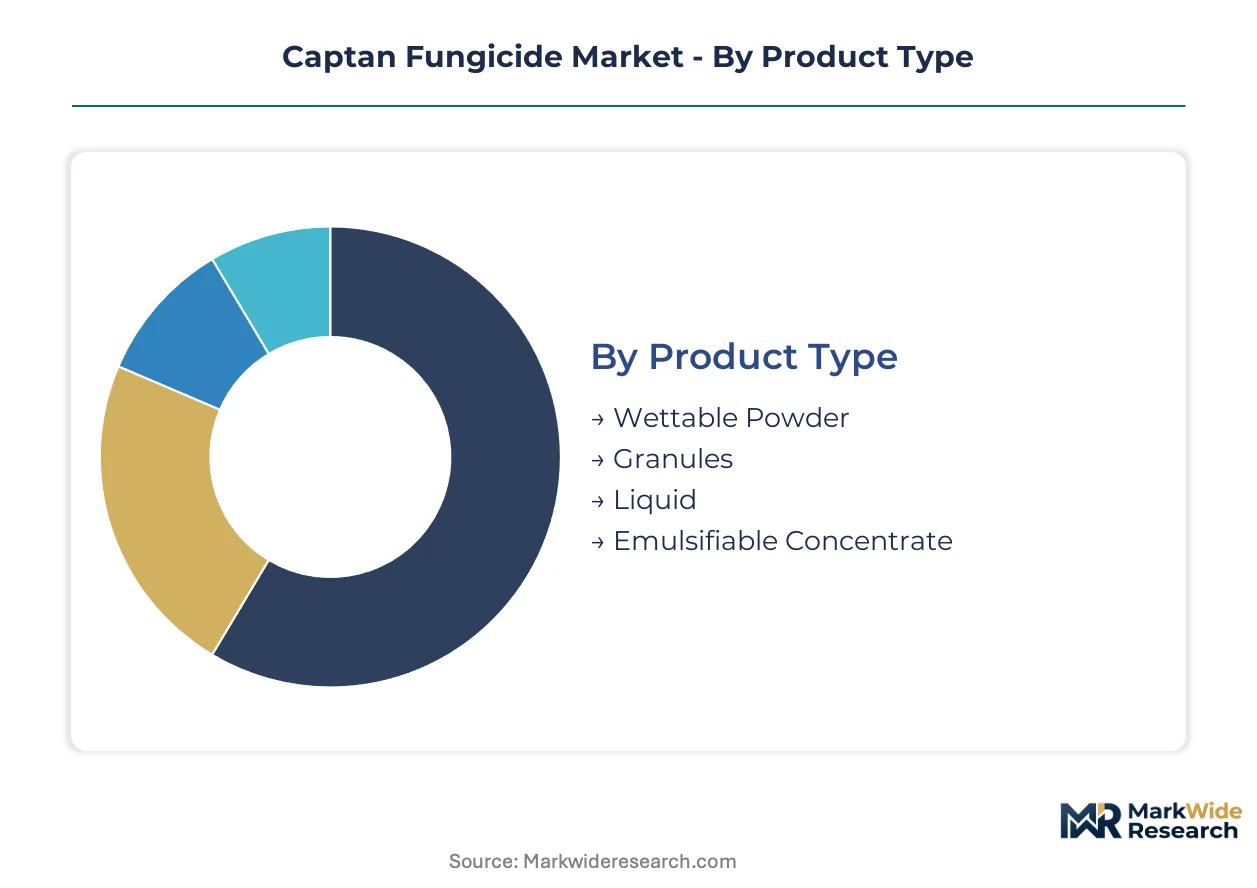
Captan fungicide procurement patterns diverge sharply across formulation types and user profiles, with regulatory residue limits and application infrastructure dictating segment profitability. Understanding these fault lines reveals where formulators can defend margin and where price competition dominates.
Product Type:
EPA tolerance recalibration under FIFRA and EFSA aquatic invertebrate standards are compressing permissible residue levels, advantaging formulations with controlled release kinetics and reduced drift potential.
- Liquid:Suspension concentrate formulations enable precise tank-mixing with reduced operator dermal exposure. California stone fruit exporters and Brazilian citrus growers serving EU markets concentrate procurement here, driven by compressed pre-harvest interval requirements and residue compliance margins.
- Wettable Powder:Fine particle dispersions of captan technical with wetting agents and dispersants retain cost advantages in volume applications. India's vegetable belt and Southeast Asian tropical fruit regions sustain demand despite mixing labor intensity and inhalation exposure concerns.
- Granules:Clay-based carriers with captan coating for soil incorporation applications.
- Emulsifiable Concentrate:Oil-based solutions requiring emulsification before application, dominant in legacy orchard spray programs.
Established volume favors wettable powder; emerging adoption favors liquid.
Application:
Application economics track crop value density and spray program intensity, with high-value perennial systems commanding premium formulation investments.
- Fruit Crops:Pome and stone fruit production in Washington State, Italian Emilia-Romagna, and Chile's Central Valley anchor global captan consumption. Multiple protective applications through bloom and fruit development create sustained demand for rainfast formulations with extended residual activity.
- Vegetables:Solanaceous and cucurbit crops in open-field systems drive cost-optimized procurement. Short production cycles and lower per-hectare input budgets favor wettable powder formulations and generic sourcing through distributor cooperatives.
- Ornamentals:Nursery propagation and landscape maintenance generate stable demand for dip treatments and foliar protectants tied to phytosanitary certification requirements.
- Turf:Golf course and sports field management in humid climates sustains niche demand for broad-spectrum contact protection against dollar spot and brown patch.
Margin concentration clusters in fruit crops; volume expansion is climbing fastest in vegetables.
End User:
Scale economies and technical advisory access separate professional agricultural systems from consumer channels.
- Agricultural Producers:Commercial farming operations with spray program optimization capabilities and residue testing budgets. Direct relationships with formulators are displacing retail channels in California's Central Valley and São Paulo state.
- Nurseries:Vegetative propagation facilities requiring certified disease-free stock for export markets. Phytosanitary protocol compliance drives captive demand for captan-based dip treatments in cutting certification programs.
- Lawn Care Professionals:Commercial turf management contractors servicing golf courses and municipal properties.
- Home Gardeners:Consumer retail segment with price-sensitive, low-volume purchasing patterns.
Technical complexity favors agricultural producers; regulatory certification requirements favor nurseries.
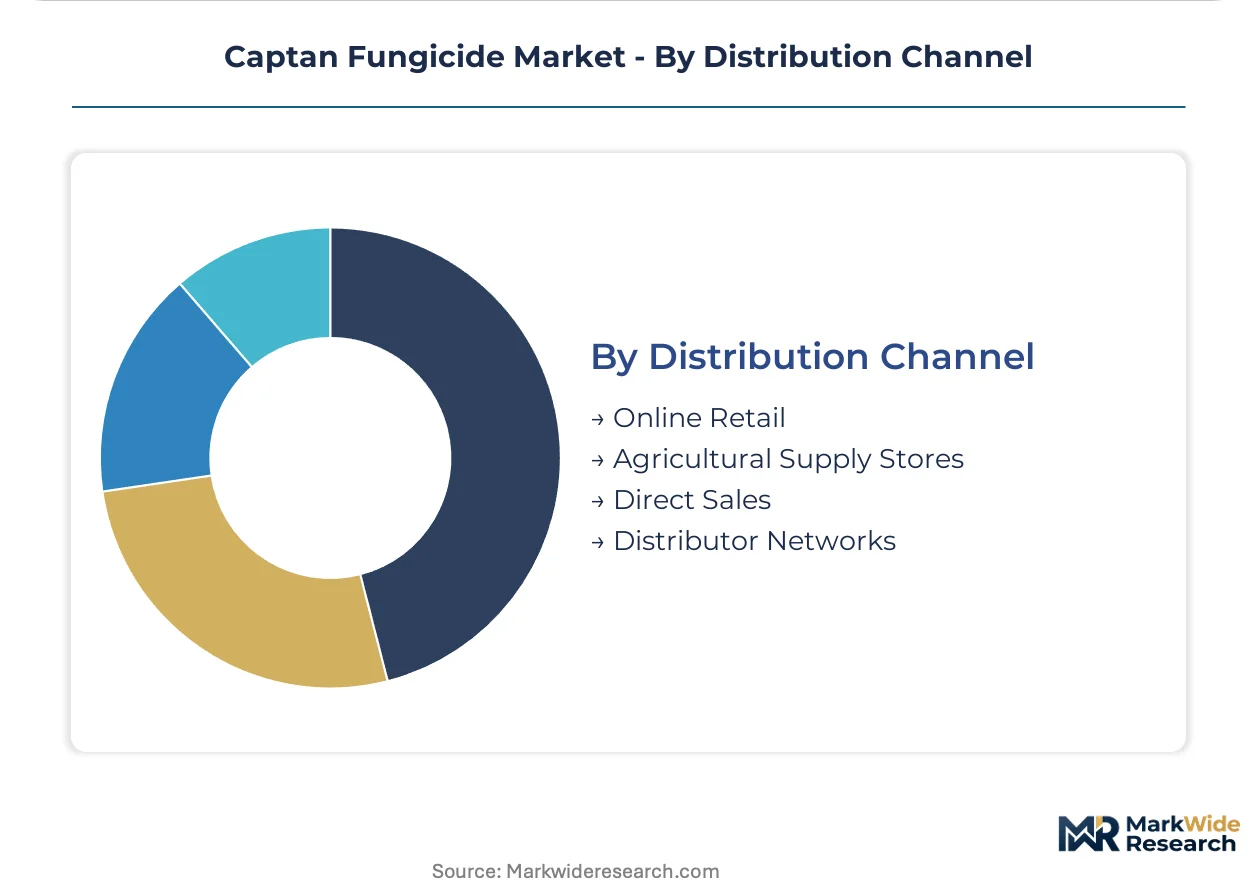
Distribution Channel:
Channel selection reflects spray program customization needs and procurement scale, with consolidation reshaping intermediary economics.
- Distributor Networks:Regional cooperatives and independent agricultural retailers dominate emerging market access. UPL Ltd. and generic competitors anchor volume through price-aggressive positioning in Brazil, India, and Southeast Asia.
- Direct Sales:Large grower-shipper organizations in California and Pacific Northwest table grape operations are bypassing retail agronomy channels. Customized spray program design and volume pricing terms drive this procurement shift.
- Agricultural Supply Stores:Branded retail outlets with technical advisory services for mid-scale producers.
- Online Retail:E-commerce platforms capturing home gardener and small-scale professional demand.
Volume concentration sits with distributor networks; margin capture is shifting fastest toward direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazil's São Paulo citrus belt while California's Central Valley growers face compressed margins from tightening EPA residue protocols.
United States
California's Central Valley stone fruit exporters drive wettable powder procurement for post-harvest disease programs. EPA's FIFRA Section 3 re-registration review tightens maximum residue limits for chlorinated fungicides. Washington State's Yakima Valley apple growers adopt microencapsulated formulations to meet compressed pre-harvest intervals.
Brazil
São Paulo state citrus and apple growers face escalating fungal pressure from humid subtropical climate patterns. ANVISA maintains maximum residue limits diverging from Codex Alimentarius standards, creating compliance complexity for EU-bound exports. Direct supply relationships between grower-shippers and formulators are displacing traditional distributor channels in the Ribeirão Preto cluster.
India
Maharashtra and Gujarat vegetable belts sustain cost-optimized wettable powder demand for solanaceous and cucurbit crops. FSSAI residue monitoring protocols are tightening for export-oriented production zones. The Nashik grape-growing region concentrates procurement volumes for contact protectant chemistries serving Middle Eastern destination markets.
Italy
Emilia-Romagna's pome and stone fruit production anchors European captan consumption through intensive protective spray programs. EFSA aquatic invertebrate standards under REACH constrain application windows near Po River watersheds. The Ferrara-Bologna orchard corridor drives adoption of rainfast liquid formulations for high-value export-oriented cherry and peach operations.
China
Shandong Peninsula apple and pear producers expand protective fungicide applications amid rising fungal disease incidence. MEE environmental monitoring is tightening discharge standards for chlorinated pesticide production facilities. The Yantai-Weihai fruit belt concentrates demand for generic wettable powder formulations serving domestic fresh consumption markets.
Captan Fungicide Market Competitive Landscape
Concentration sits with integrated multinationals controlling active ingredient synthesis and proprietary adjuvant technologies. The vendor base stratifies across three tiers: backward-integrated global suppliers with captive chlor-alkali feedstock access, regional formulators competing on price in distributor networks, and generic specialists serving cost-sensitive vegetable markets. Strategic moves center on regulatory dossier capabilities for multi-jurisdiction compliance and adjuvant technology licensing to extend formulation rainfastness.
Within the integrated multinational tier, Syngenta AG and BASF SE exemplify divergent competitive positioning. Syngenta leverages in-house production of captan technical to sustain cost advantages across wettable powder and suspension concentrate formulations. BASF anchors its position through proprietary adjuvant technologies enhancing rainfastness, commanding premium positioning in high-rainfall production zones. UPL Ltd. occupies the price-aggressive vector, competing through distributor network density across Brazil, India, and Southeast Asian emerging markets.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer AG |
| Corteva Inc. |
| FMC Corporation |
| Adama Agricultural Solutions Ltd. |
| Nufarm Ltd. |
| Sumitomo Chemical Company |
| UPL Ltd. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day active ingredient inventory cycles in chlor-alkali feedstock procurement tether captan formulators to volatile caustic soda pricing, compressing margin buffers for regional players lacking backward integration into chlorine gas production while rewarding integrated multinationals with captive supply economics.
Pricing Analysis
The customization-premium spread between proprietary rainfastness-enhanced liquid formulations and commodity wettable powders spans three performance tiers: premium suspension concentrates with microencapsulation technology, standard emulsifiable concentrates for legacy orchard programs, and economy wettable powders for cost-sensitive vegetable markets. Price differentiation hinges on adjuvant sophistication and residue compliance certification grade, with Brazilian citrus exporters and California stone fruit growers absorbing premiums for EU-export-ready formulations. Cost compression in the wettable powder tier is intensifying because Indian and Chinese generic manufacturers are expanding capacity. Agricultural producers in developing markets exhibit highest price sensitivity, while nursery certification programs show lowest elasticity due to phytosanitary compliance requirements.
Supply Chain Analysis
Chlor-alkali capacity concentration in China, the United States, and Germany anchors global captan technical production, with caustic soda and chlorine gas feedstock drawing from energy-intensive electrolysis operations vulnerable to natural gas price spikes. Phthalic anhydride and tetrahydrophthalimide intermediates source from petrochemical complexes in East Asia and the Middle East. Single-source vulnerability in chlorine gas transport infrastructure poses structural risk, particularly for European formulators dependent on Rhine barge networks. Distribution runs through bifurcated channels: direct sales to large grower-shippers in California and São Paulo, and distributor cooperatives serving fragmented vegetable belts across South and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captan fungicide demand sits in early-cycle expansion as post-harvest disease protocols penetrate specialty fruit operations beyond traditional pre-harvest applications, with California Central Valley stone fruit exporters and Brazilian citrus grower-shippers extending spray programs into handling and storage phases.
For Market Incumbents: Shield formulation portfolios from EPA residue tolerance recalibration by accelerating microencapsulation R&D investments and expanding label claims into minor crops. Backward integration into active ingredient synthesis remains the priority lever against chlorine feedstock volatility. Channel control through direct supply relationships with large grower-shippers in California's Central Valley defends margin against distributor cooperative consolidation.
For New Entrants and Emerging Players: ANVISA-Brazil regulatory fast-track for generic wettable powder formulations opens white-space access in São Paulo state's citrus belt, where procurement is shifting from distributor networks toward direct formulator relationships. The most penetrable segment lies in cost-optimized vegetable applications across India's Maharashtra and Gujarat belts. A go-to-market angle anchored in FSSAI export certification support for Middle Eastern destination markets differentiates against incumbent technical advisory bundling.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agrochemical parents divesting legacy fungicide portfolios under REACH framework pressure. Long-term viability over the projection horizon rests on regulatory dossier depth for multi-jurisdiction residue compliance and adjuvant technology IP. The signal to watch is EFSA aquatic invertebrate standard tightening, which would accelerate displacement of conventional formulations and reward rainfastness patent holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Captive chlorine gas supply insulates margin from energy price volatility in European and Asian production zones. |
| Microencapsulation Formulation Launch | Extended release kinetics satisfy compressed pre-harvest intervals for Washington State apple exporters. |
| ANVISA-EU Dual Regulatory Dossier Investment | Multi-jurisdiction compliance capability captures Brazilian citrus grower-shipper procurement shifting toward direct supply. |
| Rainfastness Adjuvant Technology Licensing | Proprietary polymer systems command premium positioning in high-rainfall Italian Emilia-Romagna cherry operations. |
| Nursery Certification Channel Partnership | Phytosanitary dip treatment programs generate stable margin pools in vegetative cutting export markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with agrochemical formulator technical directors, Brazilian citrus grower-shipper procurement managers, and Indian distributor cooperative operators; and secondary validation through EPA FIFRA registration databases, ANVISA residue limit publications, EFSA scientific opinions, and customs trade flow records. Bottom-up triangulation against top-down market sizing cross-checked active ingredient volume estimates with formulation shipment data.
Across the projection horizon, the analytical framework modeled demand by formulation type, crop application intensity, and regional regulatory cluster, with CAGRs derived from acreage expansion rates and spray program frequency trends in perennial fruit systems. Forecast inputs incorporated chlor-alkali capacity utilization rates and REACH framework substitution elasticity parameters for contact protectant chemistries.
Decision-makers should treat outputs as directional under base assumptions of stable EPA re-registration timelines and continued Brazilian humid subtropical climate patterns; material deviation in regulatory tolerance recalibration or El Niño intensity would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA aquatic ecotoxicity standards and ANVISA-Codex MRL harmonization negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Grape Fungicides Market
Crop Protection
Isoxaflutole Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
South America Fungicide Market
Crop Protection
Fumigation Service Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Pest Control Services Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Europe Nematicide Market
Crop Protection
IPM Pheromones Market
Crop Protection
Dicamba Market
Crop Protection
North America Molluscicides Market
Crop Protection
Herbicides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Tembotrione Market
Crop Protection
Propiconazole Market