
 India Tractor Market | 2026-2036
India Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
India Tractor Market Insights
High-strength steel is broadening chassis durability benchmarks across the India tractor landscape. Mahindra & Mahindra leverages its foundry network to control casting costs on transmission housings. TAFE anchors southern India through its Coimbatore manufacturing complex and dedicated dealer infrastructure. Escorts Agri Machinery differentiates via precision hydraulics developed at its Faridabad engineering center.
A tractor is a self-propelled agricultural vehicle delivering engine power through a mechanical hitch or power take-off shaft to pull implements, perform tillage, or transport loads; Indian models typically range from 15 HP orchard units to 75 HP heavy-field configurations with three-cylinder diesel engines and constant-mesh gearboxes. Diesel technology dominates installed capacity due to torque reliability and rural fuel availability, while electric prototypes from established players signal a technology transition path. The agricultural end-user segment absorbs the majority of unit volume, though construction applications in road-building and brick kilns represent a margin-accretive sub-category. Distribution runs through dealer networks in rural hinterlands, with direct sales gaining traction among institutional buyers and cooperative farming societies.
BIS certification governs safety and emission standards for domestic tractor manufacturing, while the CEA regulates electrical components in emerging electric variants. India's PLI scheme for farm mechanization subsidizes precision agriculture equipment, channeling investment toward automated transmission and telematics integration. Stakeholders must monitor state-level subsidy disbursement rhythms and groundwater regulation tightening in western India, as these policy levers determine replacement cycles and horsepower preferences.
Market Dynamics
India's tractor market is experiencing structural pressure from the PLI scheme for farm mechanization, which channels capital toward precision agriculture equipment and accelerates technology transfer from established manufacturers to tier-2 component suppliers across the northern and western agricultural belts.
Growth Catalysts
- State-level subsidy disbursement:Punjab and Haryana extend capital support for 40-50 HP utility tractors, compressing replacement cycles for smallholder farmers engaged in precision tillage operations.
- Groundwater regulation tightening:Western India's tightening extraction limits in Maharashtra and Gujarat are shifting horsepower preferences toward more efficient mid-range configurations suited to water-stressed sugarcane and cotton districts.
- High-strength steel adoption:Advanced metallurgy in chassis construction extends equipment lifespan and reduces total cost of ownership for owner-operators in high-utilization farming zones.
Market Restraints
- Diesel engine dependency:Rural fuel infrastructure locks installed capacity into compression-ignition technology, delaying electric prototype commercialization despite torque reliability advantages.
- Foundry supply concentration:Transmission housing casting capacity clusters around established manufacturing complexes, creating input bottlenecks for emerging assemblers seeking cost parity.
- BIS certification timelines:Safety and emission compliance testing extends product launch windows, particularly for variants incorporating telematics or automated transmission systems.
Strategic Opportunities
- Construction application expansion:Road-building and brick kiln operators present margin-accretive demand outside traditional agricultural end-use, with distinct financing and service requirements.
- Cooperative farming societies:Institutional buyers in Gujarat and Maharashtra are consolidating procurement through direct sales channels, bypassing traditional dealer networks for volume discounts.
- Telematics-hydraulics convergence:Integration of precision control systems with remote monitoring creates aftermarket service revenue streams for engineering centers developing localized solutions.
Industry Challenges
- Constant-mesh gearbox expertise:Mechanical transmission engineering talent concentrates at legacy manufacturing hubs, constraining product development velocity for new entrants.
- Three-cylinder diesel optimization:Powertrain calibration for 15-75 HP range requirements demands specialized testing infrastructure, elevating capex thresholds for certification-ready production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Tractor Market |
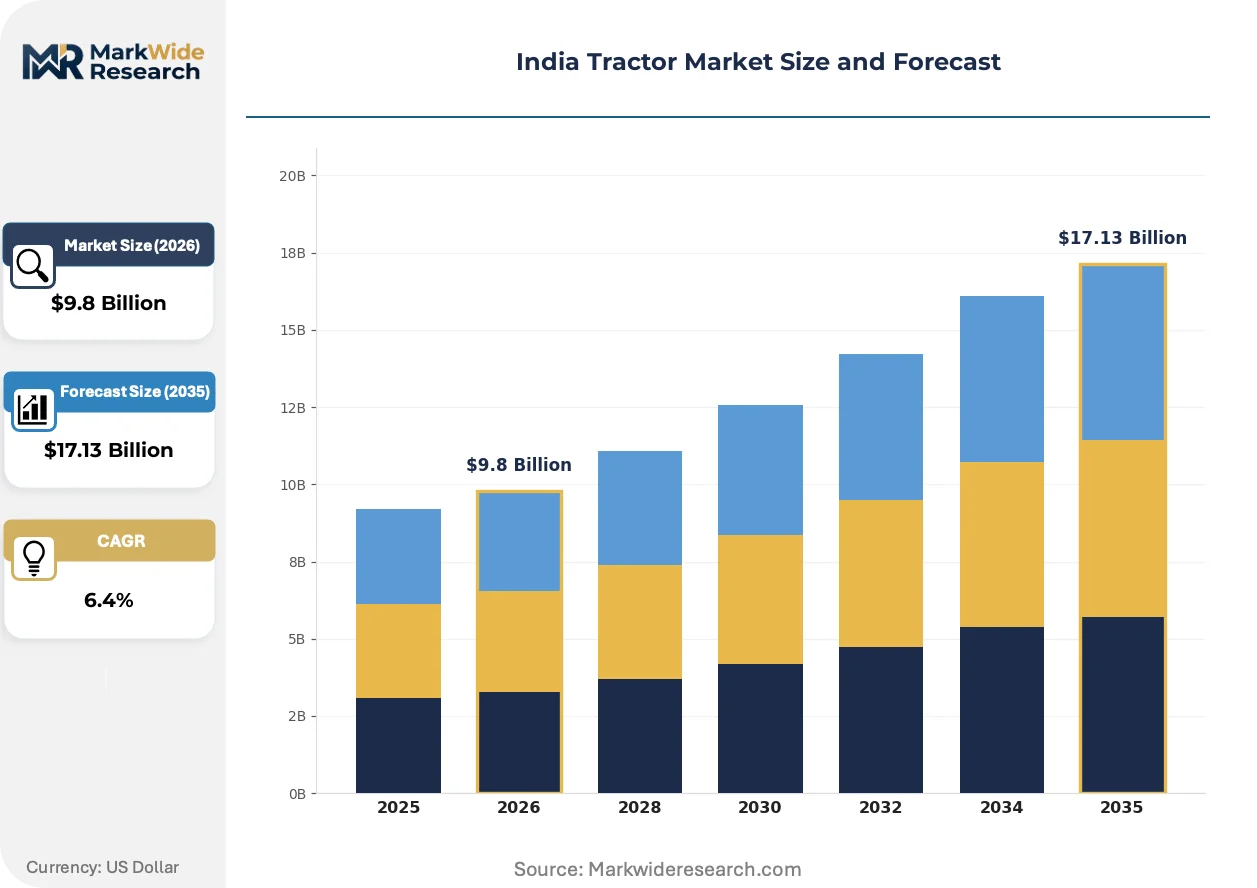
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2WD, 4WD, Compact, Utility Technology: Electric, Diesel, Hybrid, Gasoline End User: Agricultural, Construction, Horticultural, Forestry Distribution Channel: Direct Sales, Dealers, Online, Rental |
| Companies Covered | Escorts Agri Machinery, John Deere, Mahindra & Mahindra, Massey Ferguson, Kubota Agricultural Machinery India, TAFE (Tractors and Farm Equipment Limited), Swaraj, Indo Farm Equipment Limited, Sonalika International Tractors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Tractor Market Trends and Innovations
Electrification pathways and precision control systems are restructuring competitive advantage in Indian tractor manufacturing, with implications for component sourcing, distribution economics, and aftermarket service architecture.
Battery-electric powertrains are electrifying the technology roadmap for established manufacturers developing orchard and light-field configurations. State transport corporations and large farming cooperatives in Tamil Nadu and Karnataka are piloting 15-25 HP units for short-radius operations. This shift is compressing the traditional diesel engine supply chain while opening captive charging infrastructure opportunities.
India's PLI scheme for farm mechanization is mandating automated transmission and telematics integration as subsidy eligibility conditions. Domestic manufacturers must reconfigure engineering priorities to capture incentive disbursements, accelerating technology transfer from captive R&D centers to production lines. The 40-50 HP utility segment faces the steepest compliance curve given its volume concentration.
Direct procurement by institutional buyers is fragmenting the dealer-centric distribution model that has dominated rural hinterlands. Cooperative farming societies in Maharashtra's sugarcane belt now negotiate volume contracts with manufacturers, unbundling financing and service components previously embedded in retail transactions. This behavioral shift is most visible in western India where land consolidation and credit access enable collective purchasing power.
India Tractor Market Segmentation
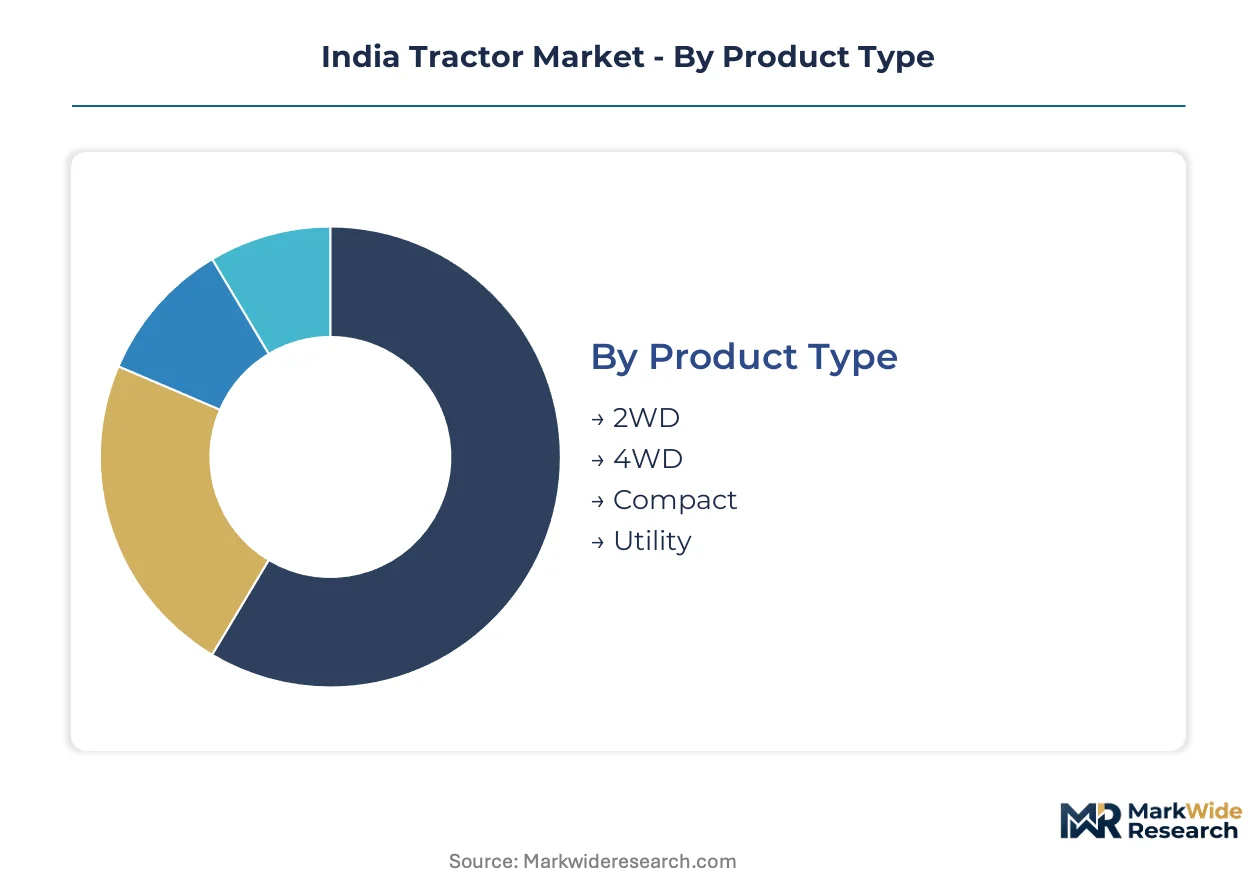
Tractor segmentation in India maps equipment specifications to distinct operational economics across soil conditions, crop cycles, and financing access. Understanding these divides reveals where technology transfer and subsidy capture concentrate.
Product Type:
Drive configuration and chassis scale determine field maneuverability, fuel efficiency, and implement compatibility across India's varied agricultural topography.
- 2WD:Two-wheel-drive tractors dominate volume through mechanical simplicity and lower capital outlay. Demand clusters in Punjab's wheat-rice rotation and Haryana's paddy belt where dry-field traction requirements remain moderate and state subsidies compress replacement cycles for smallholder farmers.
- 4WD:Four-wheel-drive configurations deliver superior pull in wet-field conditions and heavy tillage. Adoption is climbing fastest in Maharashtra's sugarcane districts and Gujarat's black cotton soils where waterlogged monsoon fields and deep plowing requirements reward traction investment.
- Compact:Narrow-track designs suit orchard inter-row operations and terraced holdings. Vineyard and tea estate operators in Karnataka and Tamil Nadu specify these for slope stability.
- Utility:Mid-range horsepower platforms balance agricultural primary use with construction secondary applications. Brick kiln and road contractors in western India favor these for equipment versatility.
Mature deployment sits with 2WD. Newer deployment is concentrated in 4WD.
Technology:
Powertrain selection reflects torque requirements, fuel infrastructure density, and regulatory pressure on emissions compliance.
- Diesel:Compression-ignition engines command installed base through torque reliability and rural fuel availability. BIS emission standards govern particulate limits, with manufacturers calibrating three-cylinder architectures for 15-75 HP duty cycles.
- Electric:Battery-electric prototypes target 15-25 HP orchard and light-field configurations. State transport corporations and farming cooperatives in Tamil Nadu pilot short-radius units with captive charging infrastructure.
- Hybrid:Parallel electric-diesel architectures remain developmental, with engineering centers testing load-balancing for variable draft applications.
- Gasoline:Spark-ignition variants occupy marginal share in hobby farming and estate maintenance where capital constraints are lighter and utilization hours are low.
Volume concentration remains with diesel. Technology transition investment flows toward electric.
End User:
Application context shapes horsepower specification, financing structure, and service interval requirements.
- Agricultural:Crop production absorbs majority unit volume across tillage, planting, and transport operations. Smallholder farmers in the Indo-Gangetic Plain drive 40-50 HP utility demand through precision tillage requirements.
- Construction:Road-building and brick kiln applications generate margin-accretive demand with distinct financing profiles and higher utilization intensity. Equipment spec emphasizes three-point hitch adaptability for non-agricultural implements.
- Horticultural:Orchard and vineyard operators specify narrow-track compact units for inter-row clearance. Karnataka's coffee estates and Maharashtra's grape belts concentrate this demand.
- Forestry:Logging and plantation maintenance requires reinforced chassis and winch compatibility. Northeastern India and Western Ghats plantation companies specify these for slope extraction.
Replacement cycle velocity is highest in agricultural. Margin per unit is strongest in construction.
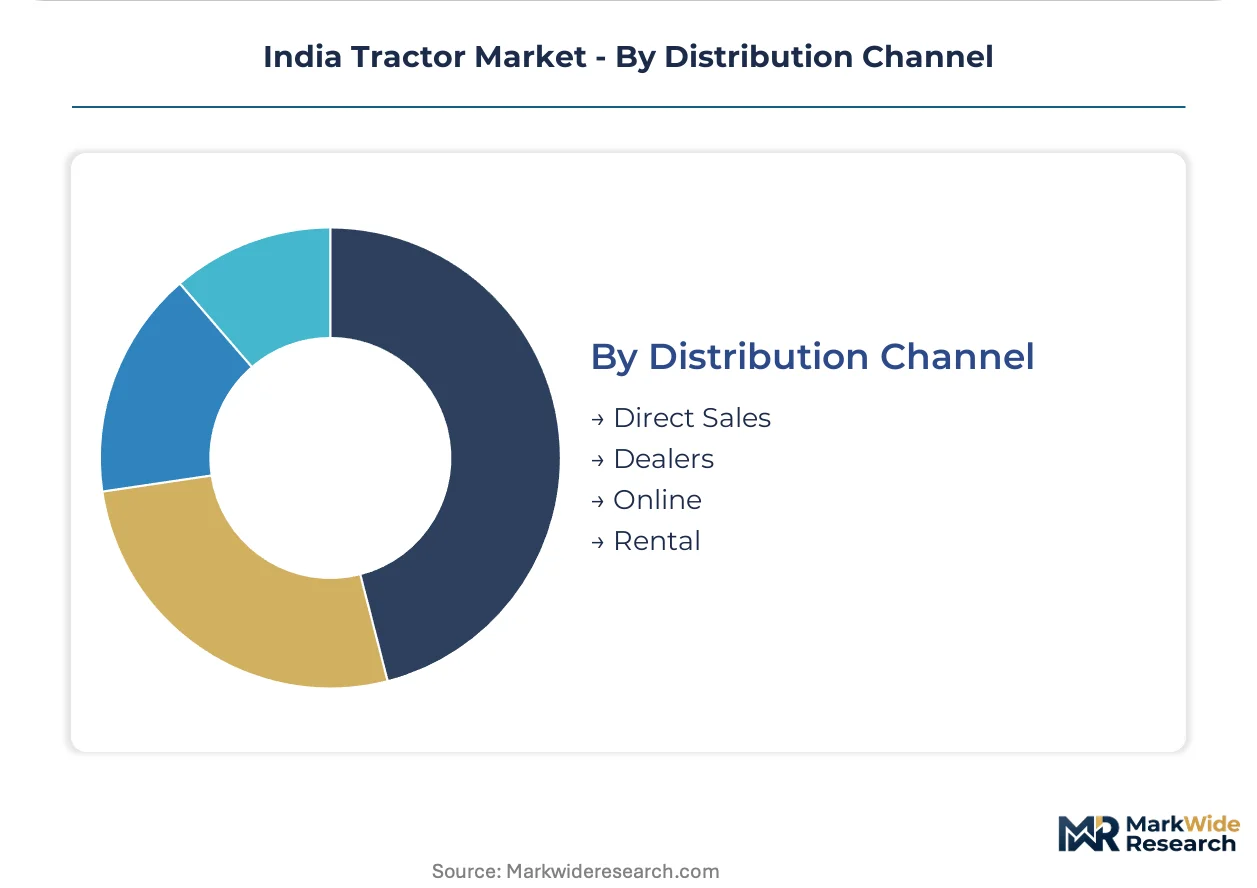
Distribution Channel:
Channel selection determines financing bundling, service proximity, and price transparency for distinct buyer profiles.
- Dealers:Rural dealership networks dominate smallholder transactions through embedded financing and field service proximity. TAFE's Coimbatore complex anchors southern India through dedicated dealer infrastructure.
- Direct Sales:Institutional buyers and cooperative farming societies in Gujarat and Maharashtra negotiate volume contracts unbundling financing from equipment procurement.
- Online:Digital platforms gain traction for specification comparison and lead generation, though physical fulfillment remains dealer-dependent.
- Rental:Equipment leasing serves seasonal demand spikes and capital-constrained operators in fragmented landholding regions.
Transaction depth is greatest through dealers. Procurement efficiency gains concentrate in direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Indo-Gangetic belt and western India, where state subsidy programs and crop-specific mechanization requirements drive replacement cycles for utility tractors.
Maharashtra
Sugarcane cooperatives in western Maharashtra drive 40-50 HP utility tractor procurement through collective financing arrangements. The state's groundwater regulation tightening under the Maharashtra Water Resources Regulatory Authority shifts horsepower preferences toward efficient mid-range configurations. Pune and Nashik districts host manufacturing clusters where transmission housing foundries supply tier-2 component networks.
Gujarat
Cotton-growing districts in Saurashtra and Kutch generate concentrated demand for four-wheel-drive tractors suited to black cotton soils and water-stressed conditions. The Gujarat government's capital subsidy schemes for farm mechanization compress replacement cycles for smallholder farmers. Anand and Rajkot industrial corridors anchor foundry and precision machining capacity for transmission components.
Punjab
Wheat-rice rotation farming in the Indo-Gangetic Plain sustains volume demand for two-wheel-drive utility tractors through state-level capital support programs. The Punjab Agricultural University extension network influences precision tillage equipment specifications among smallholder operators. Ludhiana and Mandi Gobindgarh concentrate sheet metal fabrication and gear manufacturing for the northern supply base.
Haryana
Paddy belt farmers in Karnal and Kurukshetra districts leverage subsidized credit for 40-50 HP tractor replacements on compressed cycles. The Haryana government’s farm mechanization incentives channel investment toward automated transmission integration. Faridabad hosts engineering centers developing precision hydraulics and telematics solutions for the utility segment.
Karnataka
Coffee estates and vineyard operators in the Western Ghats specify compact narrow-track tractors for inter-row orchard operations. The Karnataka State Agricultural Marketing Board facilitates direct procurement by cooperative societies, bypassing traditional dealer networks. Mysore and Mandya districts concentrate compact tractor assembly and dedicated dealer infrastructure for southern markets.
India Tractor Market Competitive Landscape
Capacity expansion dominates the current landscape as established manufacturers scale transmission housing foundries and precision machining operations to capture PLI scheme disbursements. The vendor base exhibits tiered concentration: integrated domestic conglomerates with captive component supply, mid-scale specialists focused on regional dealer networks, and emerging assemblers dependent on tier-2 sourcing. Two strategic archetypes anchor positioning—vertically integrated foundry operators controlling casting costs, and engineering-centered developers of precision hydraulics and telematics. Competitive moves concentrate on geographic expansion through dedicated dealer infrastructure and technology licensing for automated transmission integration.
Among integrated domestic manufacturers, Mahindra & Mahindra and TAFE occupy positions exemplifying the foundry-control archetype, leveraging Coimbatore and western India manufacturing complexes for transmission housing supply chain capture. Escorts Agri Machinery represents the engineering-specialist vector, with development activity concentrated at Faridabad precision hydraulics centers. John Deere and Kubota Agricultural Machinery India sit within the technology-licensing tier, transferring automated transmission and telematics platforms through joint development arrangements with domestic component suppliers.
| Leading Market Players |
|---|
| Escorts Agri Machinery |
| John Deere |
| Mahindra & Mahindra |
| Massey Ferguson |
| Kubota Agricultural Machinery India |
| TAFE (Tractors and Farm Equipment Limited) |
| Swaraj |
| Indo Farm Equipment Limited |
| Sonalika International Tractors |
| Others |
Pricing and Supply Chain Analysis
Cooperative farming societies in Maharashtra and Gujarat concentrate procurement power through direct volume contracts, locking in contract-based long-term offtake pricing that unbundles financing from equipment acquisition. This buyer archetype's collective negotiating strength compresses dealer margins while rewarding manufacturers with captive foundry capacity.
Pricing Analysis
Volume concentration in the 40-50 HP utility segment generates thin margins offset by aftermarket service revenue, while construction applications command premium-mid-economy pricing differentiation based on three-point hitch adaptability and utilization intensity. Price differentiation hinges on high-strength steel chassis certification and precision hydraulics integration. Cost compression in the 2WD entry tier is intensifying because tier-2 component suppliers compete for PLI scheme eligibility. Smallholder farmers in Punjab and Haryana exhibit highest price sensitivity, whereas brick kiln operators in western India prioritize equipment versatility over capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with transmission housing foundries clustered around Coimbatore and Faridabad manufacturing complexes, where captive casting capacity constrains emerging assemblers. Component sourcing draws from India for precision-machined gears, China for electronic control modules, and domestic steel mills for high-strength chassis plate. Tariff exposure on imported telematics hardware elevates input costs for automated transmission integration. Distribution runs through rural dealership networks anchored by TAFE's southern India infrastructure and Mahindra's northern India foundry complexes, with direct sales channels gaining share among institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India tractor market sits in a technology-transition phase as battery-electric powertrains displace three-cylinder diesel dominance in orchard and light-field configurations, with PLI scheme mandates accelerating automated transmission and telematics integration as subsidy conditions.
For Market Incumbents: Anchor defensive positioning through backward integration into transmission housing foundries to control casting costs against tier-2 supply bottlenecks, while accelerating precision hydraulics R&D at Faridabad engineering centers to capture telematics-hydraulics convergence revenue. The threat of electric prototype commercialization by technology-licensing joint ventures demands automated transmission certification investment to maintain PLI eligibility. For New Entrants and Emerging Players: Battery-electric 15-25 HP orchard configurations offer a technology-first wedge into Karnataka coffee estates and Maharashtra grape belts where captive charging infrastructure pilots create localized demand pockets. The most penetrable segment sits with compact narrow-track tractors for terraced holdings in southern India, accessible through cooperative society direct procurement channels unbundled from established dealer financing. For Investors and Strategic Acquirers: The window for entry favors engineering-centered developers of precision hydraulics and telematics with Faridabad or Pune R&D footprints, positioned for acquisition by integrated foundry operators seeking vertical capability expansion. Long-term viability over the next decade hinges on PLI scheme disbursement rhythms and groundwater regulation enforcement velocity in western India. The signal to monitor is state-level subsidy condition tightening toward mandatory automated transmission integration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive transmission housing casting reduces tier-2 dependency for PLI-eligible manufacturers. |
| Telematics Platform Integration | Remote monitoring convergence with precision hydraulics creates aftermarket service revenue at Faridabad engineering centers. |
| Electric Powertrain Development | Battery-electric 15-25 HP prototypes target Karnataka and Tamil Nadu cooperative pilot programs. |
| Direct Sales Channel Buildout | Volume contract negotiation with Maharashtra sugarcane societies bypasses dealer margin capture. |
| High-Strength Steel Certification | BIS chassis compliance extends equipment lifespan and reduces total cost of ownership claims. |
Research Methodology
Multi-period observation of state-level subsidy disbursement rhythms, groundwater regulation enforcement patterns, and PLI scheme technology transfer flows anchored the trend analysis, supplemented by interviews with tractor OEM procurement heads, tier-2 foundry operators, cooperative farming society managers, and BIS certification officers. Secondary validation drew from Ministry of Agriculture mechanization statistics, CEA electrical component filings, state water regulatory authority extraction limit notifications, and customs data on high-strength steel imports. Bottom-up unit volume modeling triangulated against top-down value aggregation across the analysis window.
Segment-weighting applied differential growth assumptions across 2WD, 4WD, compact, and utility drive configurations, with technology splits between diesel, electric, hybrid, and gasoline powertrains, and end-use weighting across agricultural, construction, horticultural, and forestry applications. CAGRs derived from fitted trend extrapolation moderated by policy inflection assumptions. Industry-specific forecast inputs incorporated PLI scheme disbursement schedules and Maharashtra Water Resources Regulatory Authority enforcement trajectories.
Several conditions sit outside the modeled scope, including abrupt BIS certification timeline extensions, diesel fuel subsidy withdrawal, and electric charging infrastructure buildout delays beyond state transport corporation pilot programs. Forecasts reflect documented assumptions on technology transition velocity and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market