
 North America Plowing and Cultivating Machinery Market | 2026-2036
North America Plowing and Cultivating Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plowing and Cultivating Machinery Market Analytics
Specialty crop acreage in California and Florida is realigning equipment preferences toward narrower-profile cultivators and precision tillage systems. Deere & Company dominates North American distribution through its integrated dealer network and precision agriculture platform. Kubota Corporation anchors the mid-horsepower tractor segment with compact utility models favored by horticultural operators. AGCO Corporation differentiates through its Fendt and Challenger brands in high-horsepower tillage applications.
Plowing and cultivating machinery comprises soil preparation equipment designed to fracture, invert, or aerate topsoil prior to planting, with working widths ranging from sub-meter vineyard units to fifteen-meter folding plows for prairie grain operations. The primary commercial purpose is to create uniform seedbed conditions while managing residue, controlling weeds, and optimizing moisture retention across diverse soil textures. Tractors constitute the value anchor of the product mix, though cultivators represent the fastest-growing category as strip-till and reduced-tillage practices expand. Automatic guidance and variable-rate technology command premium positioning, while manual and semi-automatic systems retain share among smaller agricultural cooperatives and commercial growers with limited capital replacement budgets.
The EPA enforces Tier 4 Final and forthcoming Stage V-aligned emissions standards that elevate engine costs and compress margins for equipment lacking after-treatment integration. OSHA and the USDA's Natural Resources Conservation Service shape operator safety protocols and conservation compliance requirements that influence tillage intensity and machinery specification. Health Canada and PMRA coordinate pesticide-tillage interaction guidelines that affect cultivation timing and equipment selection in cross-border operations. Stakeholders must monitor evolving carbon accounting frameworks and conservation program incentives that could accelerate electric powertrain adoption or shift acreage toward minimum-till systems requiring fundamentally different tooling configurations.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing equipment replacement cycles across the Corn Belt and Canadian Prairie provinces, forcing manufacturers to absorb after-treatment costs while large-scale operators delay fleet turnover until compliance economics stabilize.
Growth Catalysts
- USDA Conservation Reserve Program incentives:Federal payments for reduced-till practices accelerate strip-till and minimum-till machinery adoption in Iowa and Illinois.
- Strip-till technology maturation:Precision nutrient placement systems reduce fertilizer overlap, cutting input costs for commercial corn and soybean operations.
- Alberta and Saskatchewan acreage consolidation:Farm size growth above 5,000 acres creates demand for fifteen-meter folding implements and high-horsepower tractor pairings.
Market Restraints
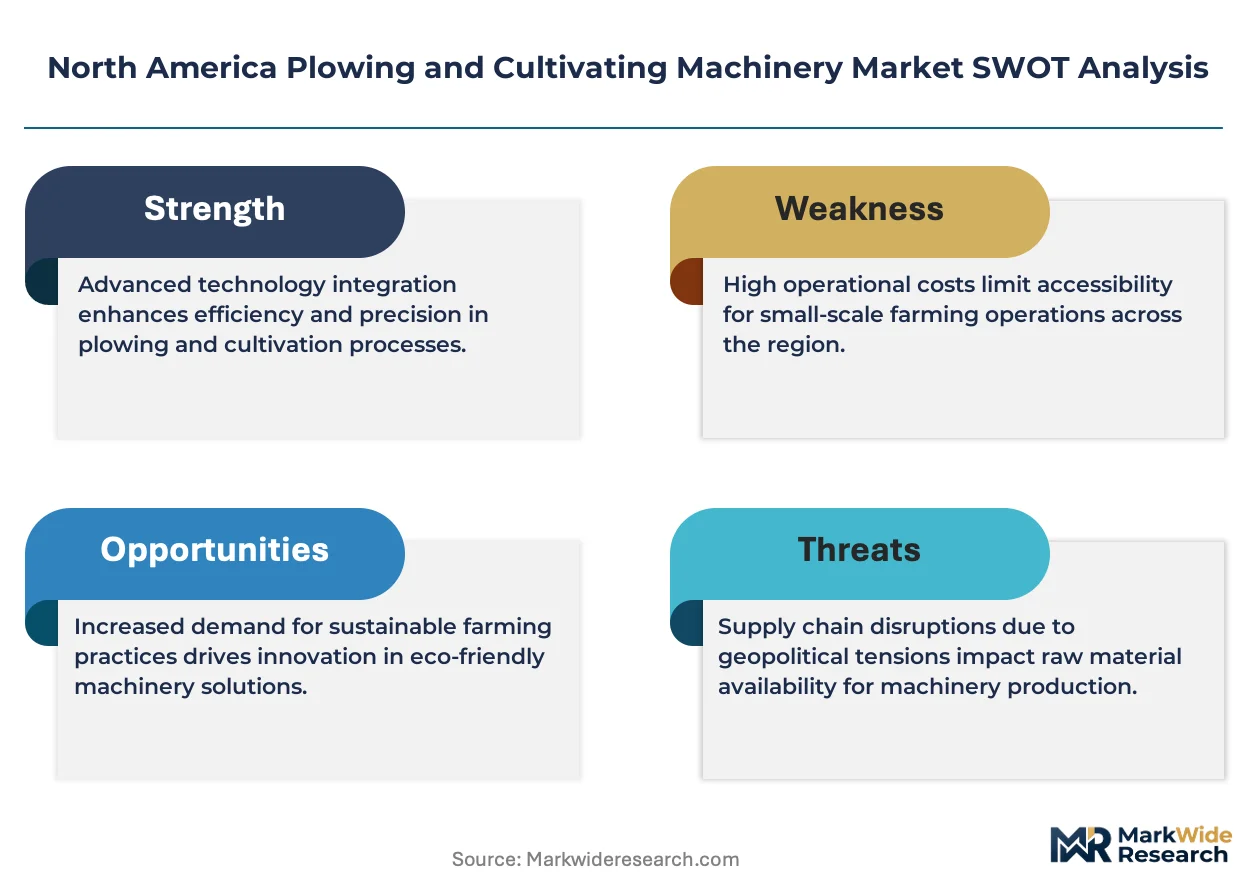
- Steel and aluminum input volatility:Frame and implement cost fluctuations compress OEM margins on mid-range cultivator lines.
- Deere dealer network concentration:Integrated distribution in the US Upper Midwest limits price competition for precision tillage packages.
- Manual transmission residual demand:Smaller cooperatives in Manitoba and North Dakota resist premium automation, slowing average selling price recovery.
Strategic Opportunities
- Electric powertrain pilots in California specialty crops:Vineyard and orchard operators test battery-electric compact tractors for tillage in emission-sensitive zones.
- Texas High Plains cotton expansion:New irrigation development creates first-time demand for bed-shaping cultivators in previously uncultivated regions.
- Telematics-enabled predictive maintenance:Real-time wear monitoring shifts aftermarket revenue from parts sales to subscription-based uptime guarantees.
Industry Challenges
- Precision agriculture technician scarcity:Dealer networks struggle to hire ISOBUS diagnostics specialists across rural Nebraska and Kansas.
- Legacy hydraulic system integration:Retrofit compatibility gaps delay adoption of automated implement control on 2015-2019 tractor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plowing and Cultivating Machinery Market |
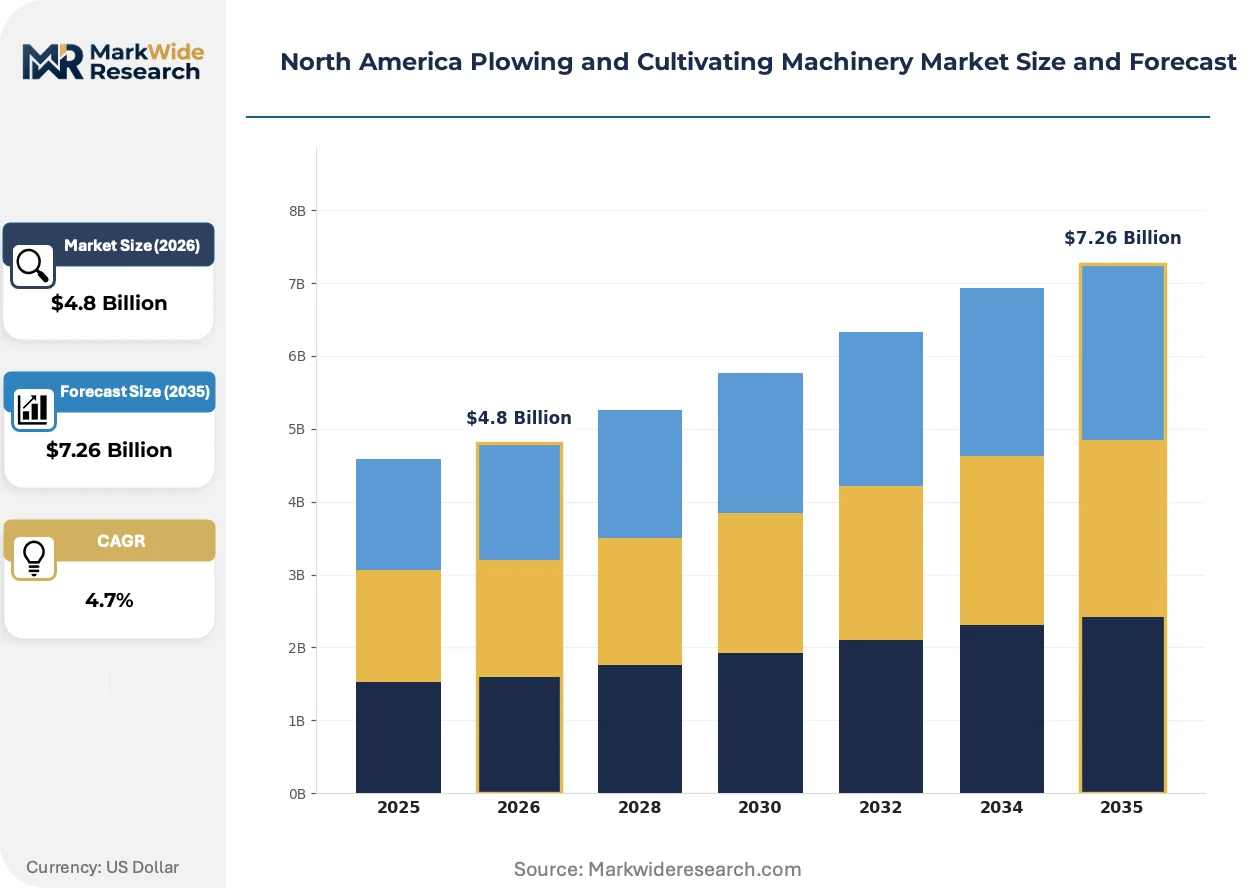
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harrows, Cultivators Application: Agriculture, Horticulture, Landscaping, Orchard Management End User: Farmers, Agricultural Cooperatives, Landscaping Companies, Commercial Growers Technology: Automatic, Semi-Automatic, Manual, Electric |
| Companies Covered | Kubota Corporation, CLAAS Group, Deere & Company, Kinze Manufacturing, Mahindra & Mahindra, CNH Industrial, Kuhn Group, Great Plains Manufacturing, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plowing and Cultivating Machinery Market Evolving Landscape
Control system convergence is compressing the gap between premium and mid-tier equipment functionality, while emissions compliance costs and shifting tillage philosophies restructure buyer priorities across North American agricultural regions.
ISOBUS universal terminal architecture is unifying tractor-implement communication protocols, eliminating proprietary display fragmentation. Mid-scale operators in Ohio and Indiana now specify open-standard controllers that interchange across brands, compressing Deere's historical software lock-in advantage and enabling Kubota and AGCO dealers to compete for precision tillage attachments.
EPA enforcement of Tier 4 Final and impending Stage V alignment for cross-border Canadian operations elevates diesel after-treatment costs by fifteen to twenty-five percent on equivalent horsepower ratings. Engine manufacturers integrate selective catalytic reduction and diesel particulate filters as standard, while large prairie grain operations in Saskatchewan extend replacement cycles to amortize compliance premiums over additional seasons.
Equipment-as-a-service contracting is displacing traditional loan financing for tillage fleets in corporate farming operations. CHS and Growmark-affiliated enterprises in Illinois and Iowa now lease complete cultivation systems with bundled telemetry and seasonal maintenance, transferring residual value risk to OEM captive finance arms and compressing regional bank equipment lending volumes.
North America Plowing and Cultivating Machinery Market Segmentation
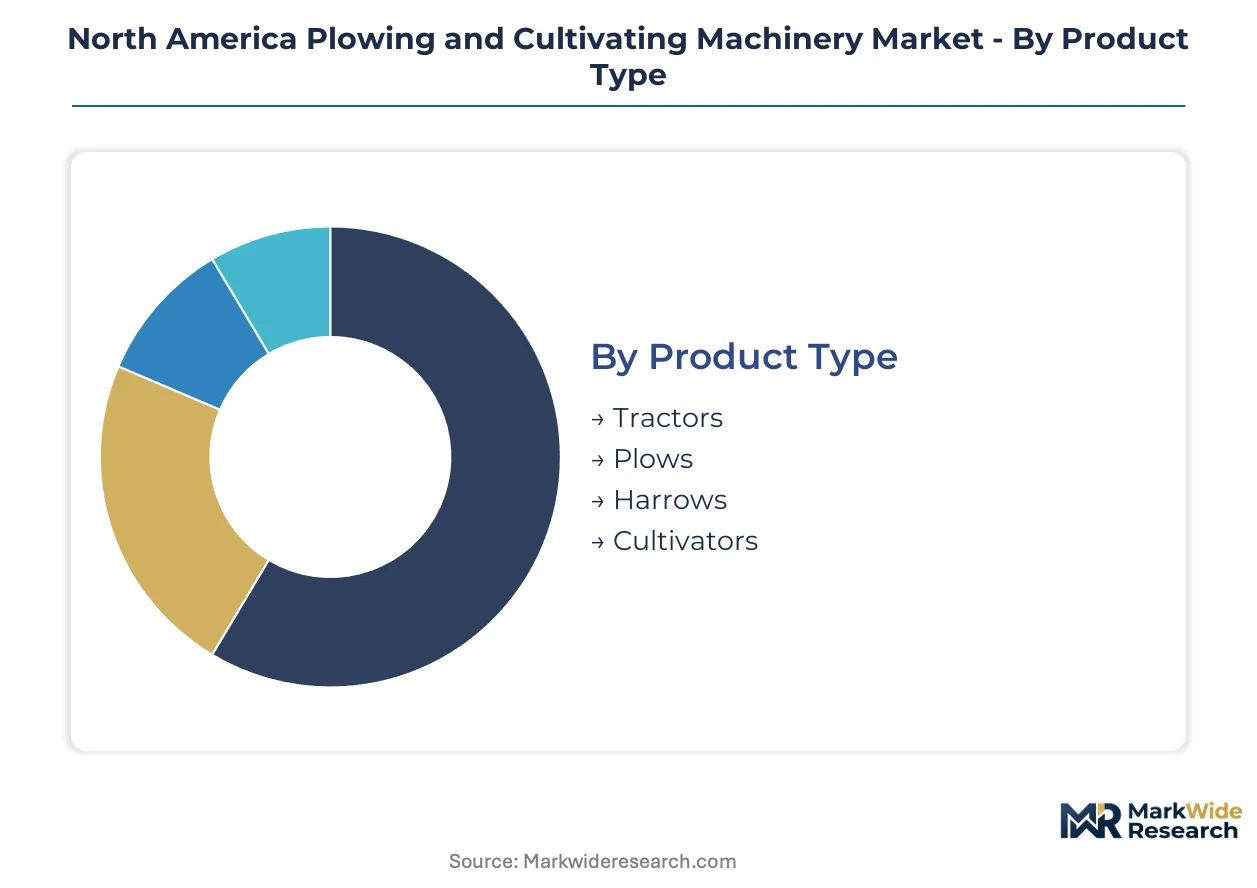
Equipment specification varies sharply across North American farming operations, from prairie grain systems requiring fifteen-meter folding implements to California vineyard units demanding sub-meter precision. Segmentation reveals how technology tiers and application intensity reshape procurement patterns across the Corn Belt and Canadian Prairie provinces.
Product Type:
Standalone tractor systems anchor capital deployment, while mounted implements function as embedded attachments whose specification depends on prime mover selection.
- Tractors:High-horsepower row-crop models dominate prairie grain operations, with EPA Tier 4 Final after-treatment integration elevating base costs. Demand concentrates in Iowa and Illinois where farm size expansion above 2,000 acres necessitates 300+ horsepower units for multi-implement cultivation sequences.
- Cultivators:Strip-till and reduced-tillage configurations are displacing conventional full-field systems across the Corn Belt. Precision nutrient placement variants reduce fertilizer overlap, cutting input costs for commercial corn and soybean operations in Nebraska and Kansas.
- Plows:Moldboard and disc configurations serve residue-intensive rotations in Manitoba and North Dakota.
- Harrows:Secondary tillage tools complete seedbed preparation in conservation-tillage transitions.
Volume placements concentrate in Tractors; the faster expansion belongs to Cultivators.
Application:
Cost tier stratification separates commodity grain systems from premium-priced specialty crop equipment requiring precision depth control.
- Agriculture:Large-scale row-crop and small-grain operations drive the core equipment base. Corn Belt states and Canadian Prairie provinces generate replacement demand as consolidation accelerates machinery turnover cycles.
- Orchard Management:Narrow-profile cultivators and precision tillage systems serve tree fruit and nut operations. California Central Valley and Washington Yakima Valley growers specify vineyard-compatible units with sub-meter working widths for between-row cultivation.
- Horticulture:Compact utility tractor pairings support vegetable and nursery operations in Florida and Texas.
- Landscaping:Light-duty tillage attachments serve municipal and commercial grounds maintenance.
Revenue concentration sits with Agriculture; Orchard Management is climbing the fastest.
End User:
Customer type determines financing structure and technology adoption velocity, from cooperative fleet standardization to individual operator capital constraints.
- Farmers:Individual owner-operators in the US Upper Midwest and Canadian Prairie provinces represent the volume base. Manual transmission residual preference among smaller Manitoba and North Dakota operators slows premium automation penetration.
- Agricultural Cooperatives:CHS and Growmark-affiliated enterprises in Illinois and Iowa now lease complete cultivation systems with bundled telemetry, transferring residual value risk to OEM captive finance arms.
- Commercial Growers:Corporate farming operations in California and Florida specify precision tillage packages with ISOBUS universal terminal architecture.
- Landscaping Companies:Light-duty equipment demand follows municipal contract awards and commercial development cycles.
Unit volume flows through Farmers; Agricultural Cooperatives are expanding most quickly.
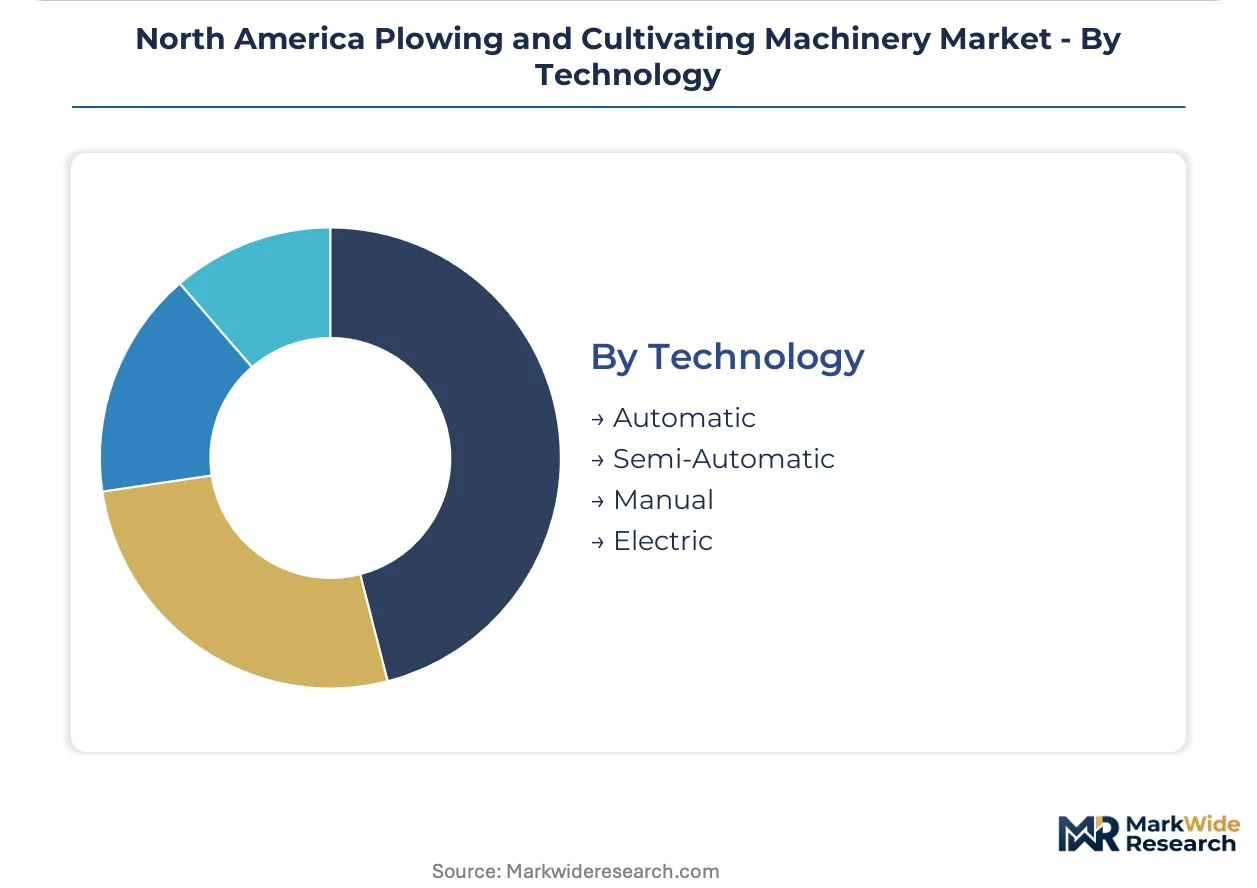
Technology:
Maturity gradients separate established hydraulic systems from emerging electric powertrains still in pilot deployment.
- Automatic:ISOBUS-compatible guidance and variable-rate control systems command premium positioning. Open-standard controllers now interchange across brands, compressing proprietary software lock-in advantages.
- Semi-Automatic:Hydraulic depth control with manual override retains share among mid-scale Ohio and Indiana operators balancing precision needs against capital constraints.
- Manual:Basic mechanical adjustment systems persist in smaller cooperatives and limited-budget commercial operations.
- Electric:Battery-electric compact tractors are undergoing vineyard and orchard testing in California emission-sensitive zones.
Current installations cluster in Automatic; Electric holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the Corn Belt and Canadian Prairie provinces, while demand spreads across specialty crop regions in California and Florida. Manufacturing clusters align with large-scale grain operations, creating geographic specialization between commodity and precision equipment.
United States
Iowa and Illinois drive replacement demand as farm sizes exceed 2,000 acres and operators seek 300+ horsepower tractors for multi-implement sequences. The USDA Conservation Reserve Program incentivizes strip-till adoption, redirecting procurement toward precision nutrient placement systems. Nebraska and Kansas form a secondary cluster where ISOBUS-compatible guidance systems command premium positioning.
Canada
Alberta and Saskatchewan acreage consolidation above 5,000 acres generates demand for fifteen-meter folding implements paired with high-horsepower tractors. Health Canada and PMRA coordinate pesticide-tillage interaction guidelines that affect cultivation timing in cross-border operations. Manitoba retains manual transmission preference among smaller cooperatives, slowing automation penetration.
California
Specialty crop acreage in the Central Valley realigns equipment preferences toward narrower-profile cultivators and precision tillage systems. EPA emissions enforcement elevates after-treatment costs, prompting vineyard and orchard operators to pilot battery-electric compact tractors. The state's emission-sensitive zones accelerate electric powertrain testing for between-row cultivation.
Texas
New irrigation development in the High Plains creates first-time demand for bed-shaping cultivators in previously uncultivated cotton regions. Corporate farming operations specify precision tillage packages with bundled telemetry and seasonal maintenance. The state's expansion of irrigated acreage attracts equipment-as-a-service contracting models.
Florida
Horticultural operators favor compact utility tractor pairings for vegetable and nursery operations. The state's year-round growing season compresses machinery replacement cycles compared to northern grain regions. Commercial growers specify ISOBUS universal terminal architecture to enable cross-brand implement interchange.
North America Plowing and Cultivating Machinery Market Competitive Landscape
Top-tier vendors anchor integrated distribution networks, while mid-tier specialists compete on open-standard compatibility and regional service density. The market exhibits tiered concentration with a dominant integrated player commanding precision agriculture platforms. Three archetypes define competitive positioning: full-line manufacturers with captive finance arms, regional specialists in compact and mid-horsepower segments, and precision technology integrators. Consolidation pressure manifests through dealer network expansion and equipment-as-a-service contracting displacement of traditional bank lending.
Among Japanese-headquartered manufacturers, Kubota Corporation occupies a position exemplifying mid-horsepower specialization for horticultural operators. Deere & Company represents the integrated platform archetype with precision agriculture capabilities. AGCO Corporation sits within the multi-brand portfolio tier, differentiating through distinct brand positioning across horsepower segments. These three anchors illustrate how geographic origin and structural approach shape competitive strategy in North American distribution.
| Leading Market Players |
|---|
| Kubota Corporation |
| CLAAS Group |
| Deere & Company |
| Kinze Manufacturing |
| Mahindra & Mahindra |
| CNH Industrial |
| Kuhn Group |
| Great Plains Manufacturing |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
Hot-rolled steel coil indices and aluminum LME benchmarks cascade through North American plowing and cultivating machinery supply chains, compressing OEM margins on mid-range cultivator lines while elevating entry costs for Tier 4 Final after-treatment integration. Farm equipment manufacturers absorb input volatility through three-tier pricing structures across premium precision-agriculture packages, standard ISOBUS-compatible systems, and economy manual-transmission configurations.
Pricing Analysis
Margin tightening in mid-horsepower tractor tiers reflects EPA Tier 4 Final after-treatment cost absorption by manufacturers competing for Corn Belt replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates Deere's integrated precision platforms from Kubota's open-standard mid-range offerings and Mahindra's value-positioned manual lines. Price differentiation hinges on ISOBUS certification grade and bundled telemetry service contracts. Smaller cooperatives in Manitoba and North Dakota exhibit highest price sensitivity, while corporate farming operations in California accept premium positioning for emission-compliant electric pilot programs.
Supply Chain Analysis
Welding technician scarcity across Iowa and Illinois manufacturing clusters constrains frame fabrication capacity for fifteen-meter folding implements demanded by prairie grain operations. Steel and aluminum sourcing concentrates in United States, Mexico, and Canada under USMCA tariff preferences. Component dependencies include selective catalytic reduction systems from German suppliers, hydraulic valve blocks from Japanese tier-1s, and precision guidance sensors from Israeli technology providers. Single-source vulnerability in diesel after-treatment modules creates procurement risk for cross-border Canadian operations. Distribution runs through Deere's captive dealer network, Kubota's horticultural specialist channels, and AGCO's multi-brand independent dealerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American plowing and cultivating machinery functions as a cost-of-compliance market where EPA Tier 4 Final emissions standards erect durable barrier-to-entry moats favoring manufacturers with integrated after-treatment engineering and captive finance arms.
For Market Incumbents: Anticipate prolonged replacement cycle compression in Saskatchewan and Alberta by extending equipment-as-a-service contracting to transfer residual value risk from prairie grain operators. Deepen backward integration into hydraulic system production to offset tier-1 supplier pricing power. Defend against Kubota's open-standard ISOBUS challenge by accelerating proprietary display lock-in through bundled telemetry subscriptions. For New Entrants and Emerging Players: Begin with California vineyard and orchard electric powertrain pilots where emission-sensitive zones create first-mover tolerance for premium pricing. Target Texas High Plains cotton expansion regions for bed-shaping cultivator introduction alongside irrigation infrastructure deployment. Pursue cooperative fleet standardization opportunities in Illinois and Iowa where CHS and Growmark affiliates seek alternatives to Deere dealer concentration. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision technology integrators with ISOBUS diagnostics capabilities in Nebraska and Kansas where technician scarcity constrains dealer service capacity. Long-term viability centers on electric powertrain transition readiness and conservation-tillage tooling portfolios aligned with USDA incentive programs. Monitor Alberta acreage consolidation velocity as inflection indicator for fifteen-meter implement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Transfers residual value risk to OEM captive finance arms in Illinois and Iowa corporate farming operations. |
| Electric Powertrain Pilot Expansion | Positions vineyard and orchard suppliers for California emission zone compliance ahead of mandate acceleration. |
| ISOBUS Diagnostics Specialist Training | Addresses precision agriculture technician scarcity constraining Nebraska and Kansas dealer service capacity. |
| Backward Integration into Hydraulics | Reduces tier-1 supplier dependency for automated implement control on legacy 2015-2019 tractor fleets. |
| Conservation-Tillage Tooling Portfolio | Captures USDA Conservation Reserve Program incentives redirecting Iowa and Illinois procurement toward strip-till systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North American plowing and cultivating machinery assessment. Primary interviews with OEM product planning directors, dealer network operations managers, agricultural cooperative procurement leads, and precision agriculture technician training coordinators cross-validated demand patterns and technology adoption timelines. Secondary sources encompassed EPA enforcement databases, USDA conservation program disbursement records, AEM equipment shipment statistics, and Canadian farm cash receipt series. Bottom-up unit shipment modeling and top-down macroeconomic elasticity checks triangulated volume and value outputs.
Segment-level granularity modeled product type at equipment category resolution, application intensity across commodity grain and specialty crop operations, technology tier from manual through electric powertrain, and end-user financing structure from individual ownership through cooperative leasing. CAGRs derived from historical replacement cycle analysis, farm size expansion elasticity, and emissions compliance cost pass-through coefficients. Industry-specific forecast inputs included prairie grain acreage consolidation rates in Alberta and Saskatchewan, California specialty crop irrigation development permits, and Texas High Plains cotton ginning capacity expansion.
Underlying measurement precision varies by segment; tractor replacement demand in Iowa and Illinois carries tighter precision than electric powertrain pilot volumes in California vineyards where fleet testing remains nascent. Forecasts reflect assumptions regarding EPA Stage V alignment timing, steel input cost stabilization, and conservation program incentive continuity. Material deviation in emissions enforcement stringency, commodity price volatility, or federal conservation funding authorization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
North America Haying and Forage Machinery Market