
 Two-Wheeler Tractors Market | 2026-2036
Two-Wheeler Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Tractors Market Analytics
Leasing and asset-light ownership models are reshaping competitive dynamics in the Two-Wheeler Tractors Market, enabling smaller agricultural contractors and hobby farmers to access premium equipment without capital outlay. BCS S.p.A. leverages its vertically integrated manufacturing base in Northern Italy to control component quality and lead times. Grillo SpA anchors its position through specialized vineyard and orchard configurations that dominate Mediterranean terrain. Tracmaster Ltd. competes via compact diesel-electric hybrid systems designed for UK allotment and smallholding segments.
Two-wheeler tractors are self-propelled agricultural machines typically powered by single-cylinder or twin-cylinder engines rated between 8 and 20 horsepower, featuring a walk-behind or ride-on operator position with power-take-off drives for mounted implements. These machines perform primary soil cultivation, seedbed preparation, and inter-row maintenance on plots below five hectares where full-size tractors prove economically inefficient. Compact tractors and garden tractors lead unit volumes across European hobby farming, while diesel technology still commands the majority of installed base despite electric systems posting the fastest growth in municipal and organic-certified applications. Utility tractors concentrate margin pools through higher attachment compatibility and longer replacement cycles among commercial contractors.
EU Stage V emission regulations enforced by the European Commission, CE marking requirements under the Machinery Directive, and national type-approval standards administered by Germany's KBA collectively elevate compliance costs and filter non-compliant imports from lower-cost manufacturing origins. The F-Gas Regulation and emerging national restrictions on internal combustion equipment in urban green spaces are accelerating electric powertrain development timelines. Stakeholders must monitor subsidy thresholds for electrified farm equipment across France, Germany, and Italy, as these programs will determine which technology configurations achieve viable total-cost-of-ownership parity against legacy diesel platforms.
Market Dynamics
Diesel-to-electric powertrain transitions and EU Stage V emission compliance deadlines are compressing manufacturer R&D timelines while fragmenting the supplier base into specialized electrification partners and legacy engine houses.
Growth Catalysts
- Hobby Farming Expansion:Northern Italian and French smallholders below five hectares are replacing manual cultivation with compact mechanized solutions, creating sustained replacement demand for walk-behind equipment.
- CE Marking Harmonization:Machinery Directive alignment across EU member states reduces cross-border certification friction for Bologna- and Reggio Emilia-based manufacturers exporting vineyard configurations.
- F-Gas Regulation Phase-Down:Restrictions on hydrofluorocarbon-based cooling systems in agricultural equipment accelerate electric motor adoption as thermal management requirements simplify.
Market Restraints
- Battery Cell Supply Concentration:Lithium-ion pack sourcing dependence on East Asian cell manufacturers exposes European assemblers to freight cost volatility and duty uncertainty.
- Steel and Aluminum Input Volatility:Chassis and implement fabrication costs fluctuate with commodity exchange pricing, compressing margin buffers for mid-tier equipment tiers.
- Substitution by Compact Four-Wheel Tractors:Sub-25 horsepower four-wheel units from Japanese and South Korean manufacturers encroach on two-wheeler territory in orchard applications above three hectares.
Strategic Opportunities
- Underpenetrated Polish Smallholding Segment:Post-Common Agricultural Policy restructuring has fragmented land ownership in Mazovia and Greater Poland without corresponding mechanization penetration.
- Municipal Electric Mandates:Urban green space maintenance contracts in German cities now specify zero-emission equipment, opening dedicated procurement channels for battery-powered tillers.
- Attachment Ecosystem Convergence:Power-take-off standardization between two-wheel tractors and handheld professional landscaping tools enables cross-brand accessory revenue streams.
Industry Challenges
- Electrification Skill Gap:Field service technician training lags behind battery-electric deployment, leaving dealer networks dependent on manufacturer direct support for high-voltage system repairs.
- Stage V Certification Timeline Compression:Parallel-track diesel exhaust after-treatment and electric platform development strains engineering resources at sub-50 million euro revenue manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Tractors Market |
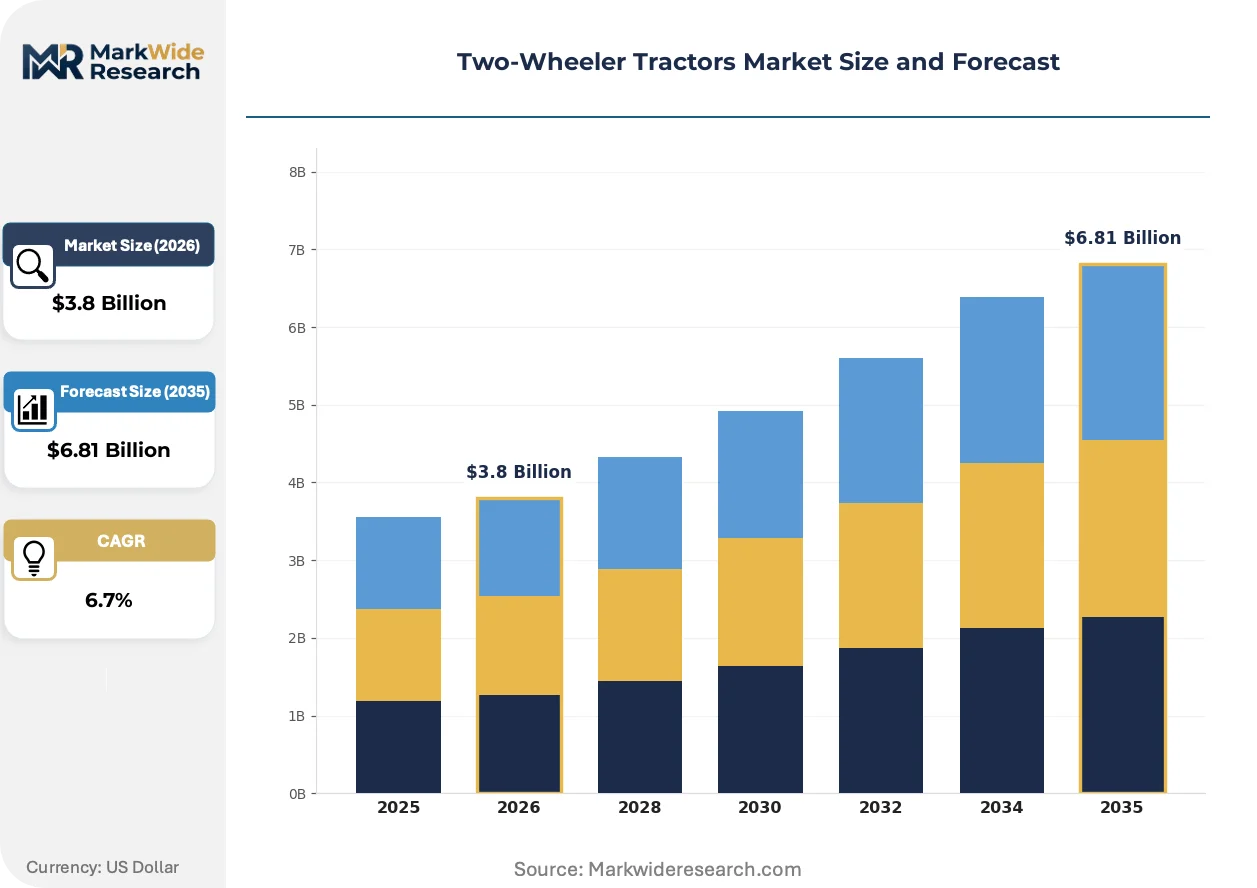
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Garden Tractors, Standard Tractors, Utility Tractors End User: Agricultural Contractors, Hobby Farmers, Commercial Farms, Government Agencies Technology: Electric, Diesel, Gasoline, Hybrid Application: Land Preparation, Planting, Harvesting, Soil Cultivation |
| Companies Covered | BCS S.p.A., Grillo SpA, Tracmaster Ltd., Bertolini, Diesse, Gink, Mcculloch, Benassi, Davies Implement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Tractors Market Evolving Landscape
Powertrain electrification and digital implement control are redefining equipment specifications, while regulatory emission deadlines force simultaneous investment in competing technical architectures.
Brushless permanent-magnet motors with integrated inverters are replacing air-cooled diesel engines in sub-12 horsepower tillers, offering instant torque for cultivation depth control. Organic-certified vineyards in Tuscany and Provence are adopting these configurations to eliminate exhaust contamination risks during flowering periods. Conventional single-cylinder Lombardini and Yanmar engine architectures are rendering obsolete for new municipal and premium agricultural procurement specifications.
EU Stage V and F-Gas Regulation convergence is forcing parallel after-treatment and battery-electric development tracks. Manufacturers must certify both diesel particulate filter-equipped platforms and lithium-ion alternatives within compressed windows. Italian and French equipment assemblers face the steepest compliance cost escalation, driving consortium-based testing pool arrangements to spread type-approval expenses.
Equipment-as-a-service contracting is displacing outright purchase for seasonal vineyard contractors in Champagne and Bordeaux regions. Leasing providers now bundle maintenance, seasonal storage, and attachment rotation into per-hectare cultivation agreements. This model concentrates most visibly among French viticulture cooperatives managing fragmented parcel ownership through shared machinery pools.
Two-Wheeler Tractors Market Segmentation
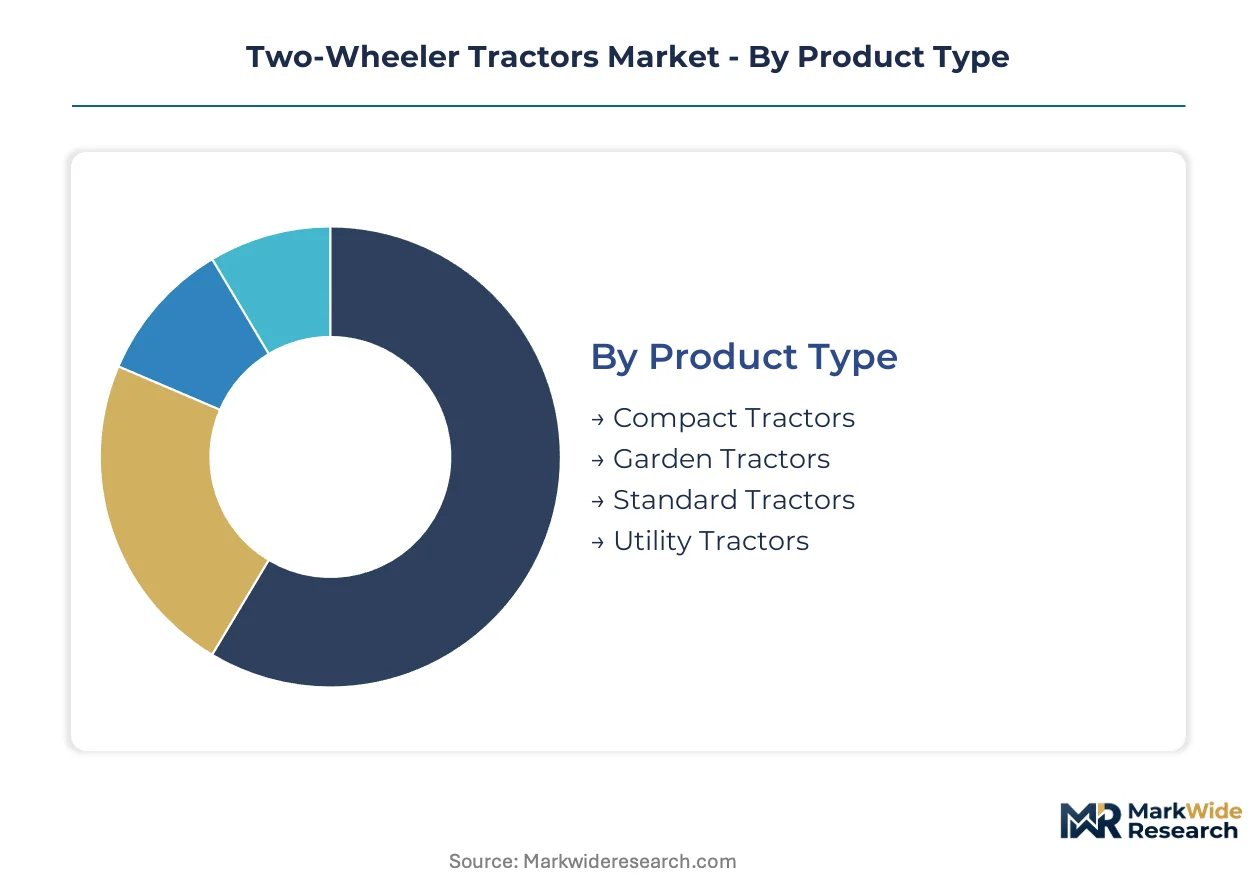
Segmentation in the Two-Wheeler Tractors Market reveals how equipment specifications diverge across cultivation scale, operator skill, and regulatory exposure. Understanding these splits enables manufacturers to align powertrain investments with procurement patterns that vary sharply between municipal tender requirements and smallholder replacement cycles.
Product Type:
Cost tier stratification separates equipment categories by horsepower rating, attachment compatibility, and replacement cycle length.
- Compact Tractors:Walk-behind units rated 8-12 horsepower dominate hobby farming applications across Italian and French smallholdings below three hectares. Demand concentrates in Northern Italy's Emilia-Romagna region, where BCS S.p.A. and Grillo SpA anchor manufacturing clusters serving vineyard inter-row maintenance. CE marking harmonization under the Machinery Directive reduces export friction for these configurations into adjacent EU markets.
- Garden Tractors:Ride-on platforms with expanded implement mounts target UK allotment operators and German Schrebergarten associations. Procurement runs through specialty dealers rather than agricultural distributors, creating distinct margin structures and seasonal inventory cycles tied to spring planting windows.
- Standard Tractors:Mid-range walk-behind units serve Polish and Romanian smallholders transitioning from manual cultivation.
- Utility Tractors:Heavy-duty configurations with three-point hitch compatibility target commercial contractors requiring year-round deployment.
Compact Tractors command the established base. The steepest expansion runs through Garden Tractors.
End User:
Customer type determines financing structure, service interval expectations, and attachment portfolio breadth.
- Agricultural Contractors:Seasonal operators in Champagne and Bordeaux viticulture regions prioritize equipment-as-a-service contracts bundling maintenance, storage, and implement rotation. Leasing providers structure per-hectare agreements that shift capital burden from fragmented parcel owners to machinery pool cooperatives.
- Hobby Farmers:Italian and French smallholders below five hectares drive replacement demand for walk-behind diesel and emerging electric configurations. These operators favor dealer proximity over specification optimization, concentrating procurement within 50 kilometers of Bologna and Reggio Emilia machinery clusters.
- Commercial Farms:Orchard operations above three hectares face substitution pressure from sub-25 horsepower four-wheel tractors.
- Government Agencies:Municipal green space departments in German cities now specify zero-emission equipment under urban maintenance mandates.
Agricultural Contractors capture margin concentration. Hobby Farmers deliver volume velocity.
Technology:
Powertrain architecture divides the installed base between legacy combustion platforms and electrification trajectories shaped by emission deadlines.
- Electric:Brushless permanent-magnet motors with integrated inverters replace air-cooled diesel in sub-12 horsepower tillers, offering instant torque for cultivation depth control. Organic-certified vineyards in Tuscany and Provence adopt these configurations to eliminate exhaust contamination risks during flowering periods.
- Diesel:Single-cylinder Lombardini and Yanmar architectures still command the majority of installed base but face obsolescence for new municipal and premium agricultural procurement specifications under EU Stage V deadlines.
- Gasoline:Lighter-duty configurations persist in consumer garden segments with lower utilization intensity.
- Hybrid:Diesel-electric systems from UK assemblers target allotment segments requiring extended runtime without charging infrastructure.
Diesel retains the installed base majority. Electric gains share fastest where municipal mandates and organic certification intersect.
Application:
Functional use case determines implement specification, seasonal demand concentration, and operator training requirements.
- Soil Cultivation:Primary tillage and seedbed preparation constitute the core use case for two-wheeler tractors across European smallholdings. Italian manufacturers optimize weight distribution and PTO torque curves for rocky Mediterranean terrain and clay-heavy Northern European soils.
- Land Preparation:Initial plot clearing and drainage establishment demand higher-horsepower configurations with reinforced chassis.
- Planting:Precision seeding attachments require calibrated PTO speed control and depth adjustment mechanisms.
- Harvesting:Specialized potato lifters and root crop diggers extend seasonal utilization windows for contractor fleets.
Soil Cultivation anchors equipment specification. Land Preparation shows the steepest expansion trajectory as underpenetrated Eastern European smallholders mechanize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy thresholds for electrified farm equipment in France, Germany, and Italy are determining which technology configurations achieve viable total-cost-of-ownership parity against legacy diesel platforms. These national programs are reshaping procurement patterns across European smallholding segments.
Italy
Hobby farmers across Emilia-Romagna and Tuscany are replacing manual cultivation with compact mechanized solutions, creating sustained replacement demand for walk-behind equipment. The Machinery Directive's CE marking harmonization reduces cross-border certification friction for Bologna- and Reggio Emilia-based manufacturers. BCS S.p.A. and Grillo SpA anchor a dense machinery cluster around these cities, dominating vineyard inter-row maintenance configurations for Mediterranean terrain.
France
Equipment-as-a-service contracting is displacing outright purchase for seasonal vineyard contractors in Champagne and Bordeaux viticulture regions. Leasing providers structure per-hectare agreements bundling maintenance, storage, and implement rotation. National subsidy programs for electrified agricultural equipment are accelerating electric powertrain adoption among organic-certified vineyards in Provence.
Germany
Municipal green space departments in German cities now specify zero-emission equipment under urban maintenance mandates, opening dedicated procurement channels for battery-powered tillers. KBA-administered national type-approval standards elevate compliance costs and filter non-compliant imports. The F-Gas Regulation phase-down accelerates electric motor adoption as thermal management requirements simplify.
United Kingdom
UK allotment operators and German Schrebergarten associations drive demand for ride-on garden tractors with expanded implement mounts. Tracmaster Ltd. competes via compact diesel-electric hybrid systems designed for smallholding segments requiring extended runtime without charging infrastructure. Procurement runs through specialty dealers rather than agricultural distributors.
Poland
Post-Common Agricultural Policy restructuring has fragmented land ownership in Mazovia and Greater Poland without corresponding mechanization penetration. Mid-range walk-behind units serve Polish smallholders transitioning from manual cultivation. This underpenetrated segment presents expansion opportunity for manufacturers with distribution networks capable of reaching dispersed rural operators.
Two-Wheeler Tractors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates manufacturing expertise in Northern Italian industrial clusters while fragmenting distribution through regional dealer networks. The vendor base separates into vertically integrated manufacturers with captive component supply, specialized vineyard-equipment fabricators, and hybrid-system assemblers targeting allotment segments. Two competitive moves dominate: consortium-based testing pool arrangements to spread EU Stage V type-approval expenses, and equipment-as-a-service contracting models that shift capital burden from fragmented parcel owners to machinery pool cooperatives.
Within the vertically integrated tier, BCS S.p.A. and Grillo SpA represent archetypal Northern Italian manufacturers leveraging geographic concentration around Bologna and Reggio Emilia to control component quality and lead times. Tracmaster Ltd. occupies a position among UK-based fabricators specializing in hybrid powertrain configurations. These three companies exemplify how regional manufacturing clusters align with distinct customer segments—vineyard contractors, hobby farmers, and allotment operators—through differentiated equipment specifications.
| Leading Market Players |
|---|
| BCS S.p.A. |
| Grillo SpA |
| Tracmaster Ltd. |
| Bertolini |
| Diesse |
| Gink |
| Mcculloch |
| Benassi |
| Davies Implement |
| Others |
Value Network & Pricing Analysis
Undercapacity at European lithium-ion cell plants is forcing equipment assemblers toward premium pricing tiers while compressing margin buffers for mid-tier configurations. This utilization squeeze simultaneously elevates procurement costs for battery-electric platforms and strengthens pricing power for diesel-equipment incumbents with captive engine supply.
Pricing Analysis
Certification level under EU Stage V and CE marking directives creates the primary spread between premium vineyard configurations and economy tillers. Three-tier pricing structure separates emission-compliant electric platforms from diesel particulate filter-equipped units and legacy combustion models. Cost compression in the economy tier is intensifying because Polish and Romanian smallholders prioritize acquisition price over specification optimization. Hobby farmers in Italy and France exhibit lowest price sensitivity due to dealer proximity premiums and attachment ecosystem lock-in.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk profiles for battery cell procurement. Manufacturing concentrates in Italy, Germany, and China, with chassis fabrication anchored in Emilia-Romagna and powertrain components sourced from East Asian cell manufacturers. Steel and aluminum input volatility rests on commodity exchange pricing swings. Distribution runs through regional dealer networks rather than agricultural distributors, concentrating inventory cycles around spring planting windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU Stage V certification requirements and CE marking harmonization erect structural barriers that favor incumbents with established type-approval expertise and testing pool consortium access.
For Market Incumbents: Entrench position through backward integration into permanent-magnet motor production and battery pack assembly, reducing exposure to East Asian cell supply volatility. Deepen certification investment in parallel diesel after-treatment and electric platform tracks to maintain procurement eligibility across municipal and premium agricultural tenders. Channel control in Northern Italian machinery clusters remains the critical lever against Japanese and South Korean four-wheel tractor substitution.
For New Entrants and Emerging Players: Establish a beachhead in Poland's underpenetrated Mazovia and Greater Poland smallholding segments, where post-CAP land fragmentation has outpaced mechanization penetration. Target equipment-as-a-service contracting models for Eastern European agricultural contractors, mirroring French viticulture cooperative structures. Go-to-market execution should emphasize dealer network partnerships over direct distribution, leveraging existing regional service infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Stage V compliance cost escalation will strain sub-50 million euro revenue manufacturers into testing pool arrangements or exit. Acquisition targets cluster among specialized vineyard-equipment fabricators with CE marking expertise and hybrid-system assemblers serving UK allotment segments. Monitor subsidy threshold adjustments in France, Germany, and Italy as the inflection signal determining electric platform total-cost-of-ownership parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium-Based Testing Pool Formation | Spreads EU Stage V type-approval expenses across Bologna- and Reggio Emilia-based manufacturers facing compressed certification timelines. |
| Equipment-as-a-Service Contracting | Shifts capital burden from fragmented French viticulture parcel owners to machinery pool cooperatives in Champagne and Bordeaux regions. |
| Powertrain Electrification Investment | Positions brushless permanent-magnet configurations for German municipal zero-emission mandates and organic-certified Tuscan vineyard procurement. |
| Attachment Ecosystem Standardization | Enables cross-brand accessory revenue streams through power-take-off convergence between two-wheel tractors and handheld landscaping tools. |
| Dealer Network Capacity Expansion | Captures Polish smallholder replacement demand in Mazovia and Greater Poland through proximity-based service coverage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Machinery Directive guidance documents, KBA type-approval registers, and national electrified equipment subsidy program filings. Interviews with Northern Italian manufacturing executives, German municipal procurement officers, French viticulture cooperative managers, and Polish agricultural machinery distributors informed demand-side validation. Secondary sources include EU F-Gas Regulation implementation reports, customs trade data on chassis and implement imports, and SEC filings from listed equipment manufacturers. Bottom-up unit shipment estimates triangulate against top-down addressable smallholding acreage calculations.
Forecast inputs incorporate powertrain technology transition curves, subsidy program renewal trajectories, and emission compliance deadline effects across the projection horizon. Segmentation dimensions span product type, end user category, powertrain architecture, and regional regulatory cluster. CAGRs derive from fitted adoption curves weighted by replacement cycle timing and penetration rate differentials. Industry-specific inputs include vineyard mechanization intensity indices and municipal green space maintenance contract specifications.
Sensitivities concentrate around battery cell supply disruption, steel and aluminum commodity price spikes, and subsidy program cancellation risks. Forecasts reflect assumptions on emission regulation enforcement continuity and Eastern European smallholder mechanization progression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market