
 Vietnam Agricultural Machinery Market | 2026-2036
Vietnam Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Agricultural Machinery Market Analytics
Leasing and hire-purchase arrangements for tractors and harvesters is fragmenting the competitive landscape by lowering capital barriers for smallholder farmers. Kubota Corporation leverages its established dealer financing networks to sustain dominance in premium tractor segments across southern provinces. VEAM anchors its position through state-backed manufacturing scale and preferential procurement channels for public agricultural extension programs. THACO competes by extending its automotive supply chain expertise into localized assembly of mid-range equipment for Mekong Delta cooperatives.
Vietnam agricultural machinery encompasses powered and towed equipment engineered for field operations, typically featuring diesel engines rated between 15 and 75 horsepower, hydraulic implement coupling, and steel-frame construction designed for paddy-field traction. This equipment serves the primary commercial purpose of replacing manual labor in soil preparation, crop establishment, and grain harvesting across Vietnam's dual-cropping rice systems and expanding fruit orchards. Tractors and harvesters together constitute the dominant product type category, with harvesters capturing expanding margin pools as labor costs rise and harvest windows compress. Precision agriculture technology represents the fastest-growing segment, though mechanization without digital integration still occupies the majority of unit volume among smallholder end users in northern mountainous provinces.
Vietnam's Ministry of Agriculture and Rural Development coordinates equipment subsidy schemes with technical standards from the country's national quality regulator, while import tariff schedules administered by the General Department of Customs shape competitive access for foreign manufacturers. These frameworks collectively steer demand toward domestically assembled machinery meeting local emission and safety benchmarks. Stakeholders must monitor how subsidy eligibility criteria evolve in relation to precision agriculture technology mandates.
Market Dynamics
Subsidy eligibility criteria from Vietnam's Ministry of Agriculture and Rural Development are redirecting procurement flows toward domestically assembled equipment that meets localized emission and safety benchmarks, compressing import-dependent supply channels.
Growth Catalysts
- MARD Equipment Subsidy Schemes:Preferential financing for domestically manufactured tractors and harvesters lowers capital barriers for Mekong Delta rice cooperatives expanding mechanized fleets.
- Labor Cost Compression:Rising agricultural wages in the Red River Delta's intensive vegetable zones accelerate payback periods for automated soil preparation and grain handling systems.
- Dual-Cropping Intensification:Compressed harvest windows in southern paddy systems create operational urgency for faster field-clearance equipment between rice and winter-spring crop rotations.
Market Restraints
- Steel Price Volatility:Input cost swings for chassis and implement-grade steel constrain margin stability for domestic assembly operations serving price-sensitive smallholder segments.
- Import Tariff Schedules:The General Department of Customs maintains protective duties on fully-built foreign equipment, limiting technology transfer from premium-tier manufacturers.
- Precision Agriculture Skill Gaps:GPS-guided variable-rate application systems face adoption friction where operator training infrastructure remains underdeveloped in northern mountainous provinces.
Strategic Opportunities
- Central Highlands Expansion:Coffee and pepper plantation zones remain underpenetrated by mechanized harvesting equipment relative to Mekong Delta rice systems.
- Telematics-Hydraulics Convergence:Integration of real-time diagnostics with hydraulic implement control creates service-revenue streams beyond equipment sales.
- Leasing Network Proliferation:Hire-purchase arrangements through agricultural cooperative credit unions unlock demand from capital-constrained vegetable producers in Lam Dong province.
Industry Challenges
- Dealer Technician Certification:Hydraulic system diagnostics and diesel engine calibration require specialized training that outpaces vocational program output in rural provinces.
- Subsidy Compliance Documentation:Domestic content verification for MARD preferential procurement creates administrative burden for assemblers sourcing transmissions and engines from ASEAN trading partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Agricultural Machinery Market |
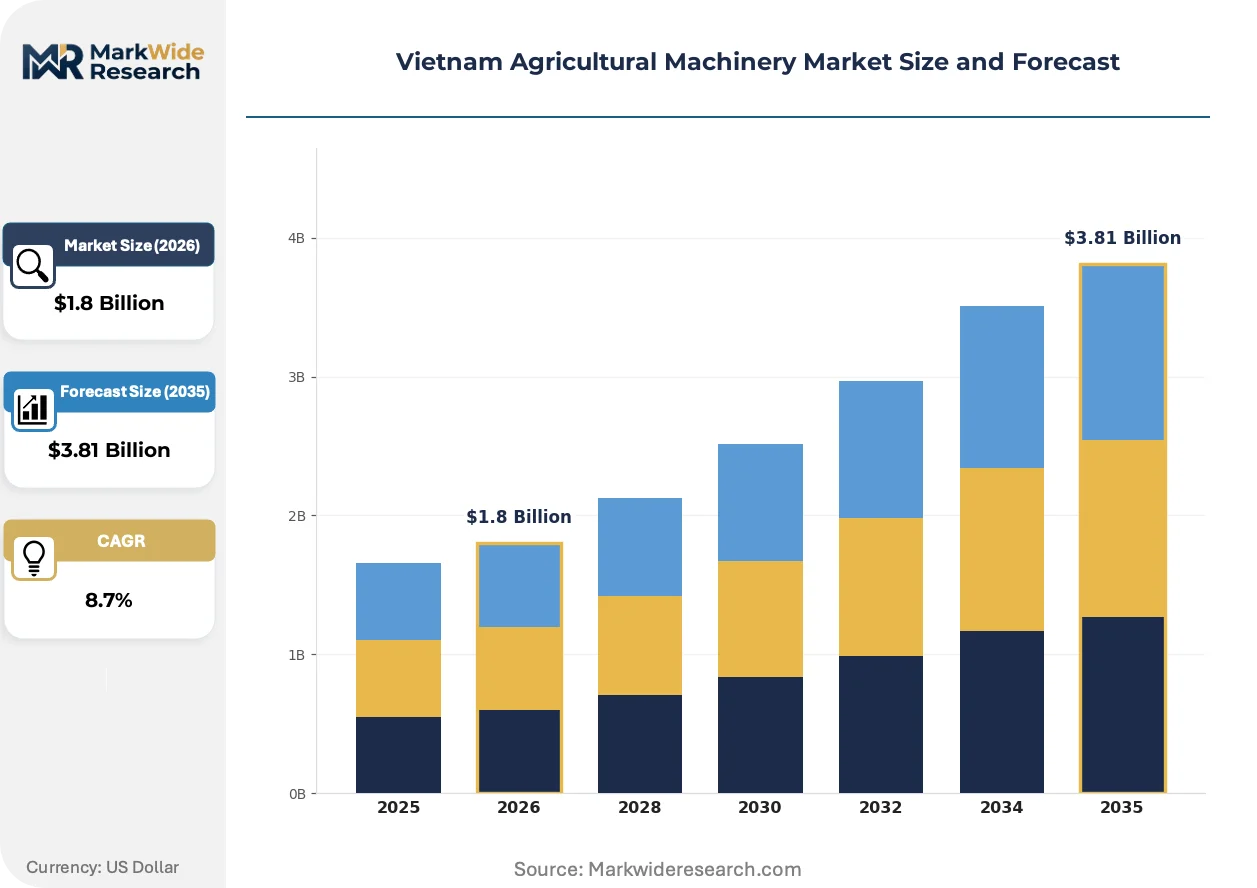
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Ploughs, Harvesters, Seeders Application: Crop Cultivation, Soil Preparation, Harvesting, Irrigation Technology: Precision Agriculture, Automation, IoT, Mechanization End User: Farmers, Cooperatives, Agribusinesses, Agricultural Contractors |
| Companies Covered | Kubota Corporation, Vietnam Engine & Agricultural Machinery Corp (VEAM), Yanmar Holdings Co., Ltd., Truong Hai Group Corporation (THACO), Deere & Company (TTC Bien Hoa), LS Mtron Co., Ltd., Mahindra & Mahindra Ltd., Hanoi Agricultural Machinery and Agricultural Extension Company (HAMCO), CNH Industrial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Agricultural Machinery Market Evolving Landscape
Digital automation layers are migrating onto mechanical platforms faster than operator skill bases can absorb them, creating a bifurcation between equipment capability and field utilization.
GPS-enabled auto-steering and yield-mapping systems are migrating from premium tractor lines toward mid-range platforms as component costs decline. Large-scale cooperatives in An Giang and Can Tho provinces adopt these systems at accelerated replacement cycles. The technology is migrating from positioning accuracy toward integrated prescription agriculture, compressing the value capture window for standalone hardware vendors.
Vietnam's national quality regulator has tightened particulate matter emission thresholds for diesel engines above 37 kilowatts, effective across all subsidized procurement programs. Domestic assemblers must recalibrate engine sourcing to Chinese or Indian suppliers with certified after-treatment systems. The Red River Delta's vegetable mechanization segment faces the steepest compliance timeline, with renewal deadlines clustered in the next equipment replacement cycle.
Cooperative-led equipment pooling is displacing individual smallholder ownership across the Mekong Delta's rice-intensive districts. Member farmers access tractors and combine harvesters through hourly booking systems managed by commune-level agricultural extension offices. This model concentrates most visibly in Dong Thap and Kien Giang provinces, where harvest labor shortages have compressed the viable collection window to under fourteen days per crop cycle.
Vietnam Agricultural Machinery Market Segmentation
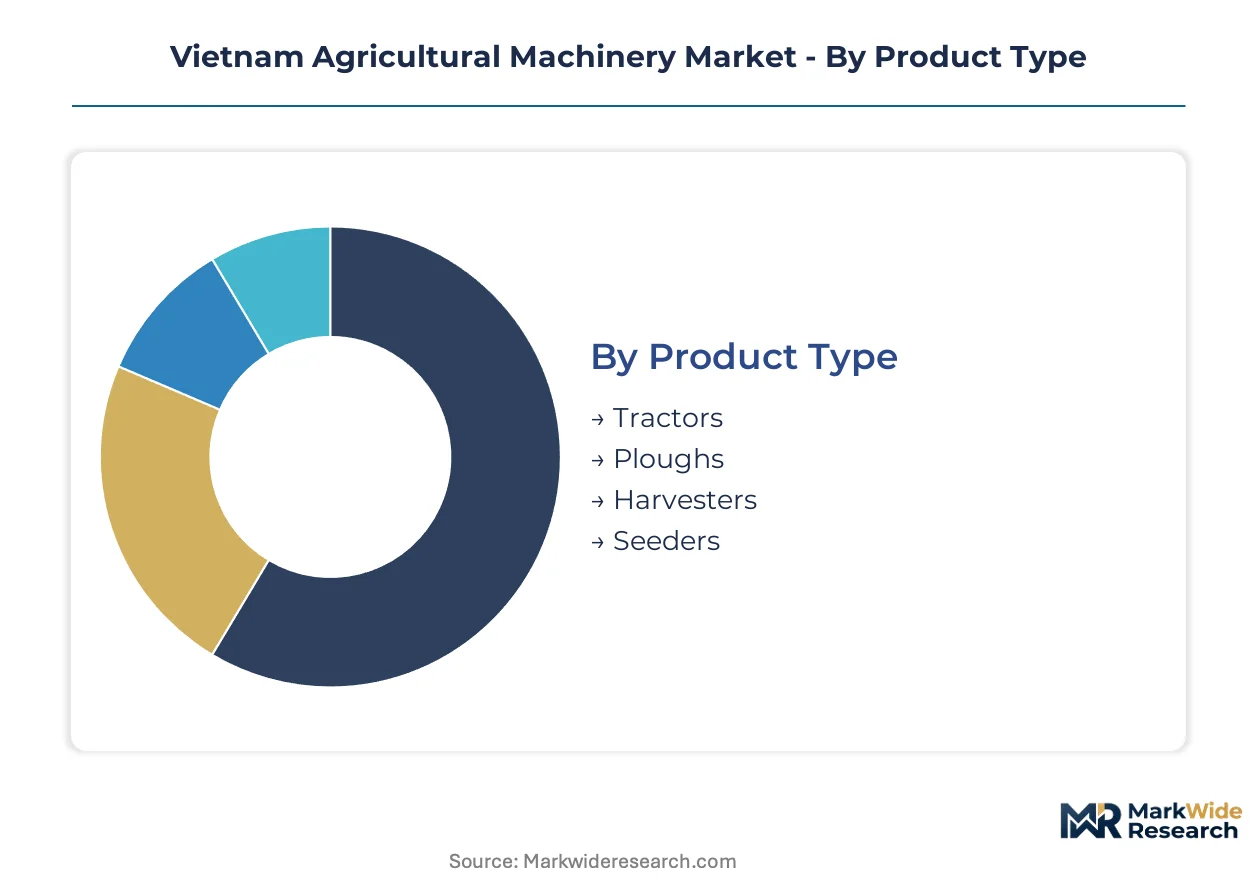
Equipment replacement cycles vary dramatically across Vietnam's agricultural machinery segments, with harvesters turning over every 5-7 years versus 12-15 years for basic tillage implements. Understanding these temporal patterns helps distributors align inventory financing with cooperative procurement calendars and subsidy disbursement schedules.
Product Type:
Harvesters compress replacement cycles to 5-7 years under intensive dual-cropping regimes, while ploughs and seeders extend toward 15-year horizons in smallholder maintenance patterns.
- Tractors:Diesel-powered units rated 15-75 horsepower with hydraulic three-point hitch systems dominate Mekong Delta rice cooperatives. Red River Delta vegetable producers drive demand for compact orchard configurations with narrow wheelbases suited to inter-row cultivation.
- Harvesters:Self-propelled combine systems with axial-flow threshing mechanisms command premium positioning. Dong Thap and An Giang provinces concentrate fleet expansion as labor shortages compress collection windows below fourteen days per crop cycle.
- Ploughs:Moldboard and disc configurations for primary tillage occupy the longest replacement cycles among powered equipment categories.
- Seeders:Mechanical and pneumatic metering systems for direct rice seeding gain traction in winter-spring rotation scheduling.
Tractors dominate installed base across all provinces. Harvesters are where expansion concentrates as cooperative fleets professionalize.
Application:
Margin structures diverge sharply between capital-intensive harvesting operations and recurring soil preparation services sold by the hectare.
- Crop Cultivation:Inter-row cultivation equipment and mechanical weed control systems serve Lam Dong province's year-round vegetable production schedules.
- Soil Preparation:Rotary tillers and subsoilers face the steepest price sensitivity among smallholder segments in northern mountainous provinces.
- Harvesting:Combine harvesters and reaper-binder systems generate the highest hourly revenue rates for Mekong Delta equipment contractors. Kien Giang and Can Tho provinces drive fleet expansion as cooperative pooling models displace individual ownership.
- Irrigation:Center-pivot and drip system components integrate with pumping infrastructure in Central Highlands coffee zones.
Soil preparation commands the largest addressable acreage. Harvesting generates the steepest revenue per machine-hour.
Technology:
Adoption friction separates digitally integrated platforms from basic mechanization, with skill infrastructure lagging hardware capability in peripheral provinces.
- Precision Agriculture:GPS-guided variable-rate application and yield-mapping systems migrate from premium tractors toward mid-range platforms. An Giang cooperatives adopt auto-steering at accelerated replacement cycles as component costs decline.
- Automation:Telematics-integrated hydraulic control enables remote diagnostics and prescription agriculture workflows.
- IoT:Sensor networks for soil moisture and equipment health monitoring face deployment constraints where cellular coverage remains intermittent.
- Mechanization:Diesel-powered equipment without digital integration still occupies majority unit volume among smallholders in northern provinces.
Basic mechanization dominates current installed base. Precision agriculture layers are where technology investment concentrates.
End User:
Capital access and procurement scale create distinct equipment specification preferences across farmer, cooperative, and commercial operator segments.
- Farmers:Individual smallholders in northern mountainous provinces favor compact tractors below 35 horsepower with financing through agricultural credit unions.
- Cooperatives:Commune-level pooling models in Dong Thap and Kien Giang provinces centralize fleet ownership with hourly booking systems for member access.
- Agribusinesses:Large-scale integrated operations in Central Highlands coffee and pepper zones specify premium-tier equipment with telematics integration.
- Agricultural Contractors:Independent harvest service providers in Can Tho and An Giang provinces optimize for field clearance speed and transport logistics between dispersed plots.
Cooperatives dominate medium-horsepower tractor procurement. Agribusinesses are where precision technology adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Agriculture and Rural Development subsidy schemes redirect procurement toward domestically assembled equipment, compressing import channels while elevating local manufacturing scale across distinct agricultural zones.
Mekong Delta
Rice cooperatives in Dong Thap and An Giang provinces expand mechanized harvesting fleets as labor shortages compress collection windows below fourteen days per crop cycle. MARD preferential financing targets domestically manufactured tractors and harvesters for these commune-level pooling models. Can Tho anchors fleet expansion with hourly booking systems displacing individual smallholder ownership.
Red River Delta
Intensive vegetable and fruit production zones in this northern region accelerate payback periods for automated soil preparation systems as agricultural wages rise. The national quality regulator's tightened particulate matter emission thresholds for diesel engines above 37 kilowatts force equipment renewal cycles. Hanoi surrounds drive demand for compact orchard tractors with narrow wheelbases suited to inter-row cultivation.
Central Highlands
Coffee and pepper plantation zones remain underpenetrated by mechanized harvesting equipment relative to rice systems in southern provinces. Lam Dong province's year-round vegetable production schedules sustain demand for mechanical weed control and inter-row cultivation equipment. Provincial agricultural extension offices coordinate leasing arrangements through cooperative credit unions.
Northern Mountainous Provinces
Smallholder farmers in these peripheral regions favor compact tractors below 35 horsepower with financing through agricultural credit unions. Diesel-powered equipment without digital integration occupies majority unit volume where operator training infrastructure remains underdeveloped. Provincial vocational programs lag behind hydraulic system diagnostics and diesel engine calibration requirements.
Vietnam Agricultural Machinery Market Competitive Landscape
On the supply side, the industry is tiered between premium international brands, state-backed domestic assemblers, and mid-range localized manufacturers. Japanese and Korean multinationals anchor premium positioning through established dealer financing networks. Vietnamese state enterprises leverage preferential procurement channels for public agricultural extension programs. Automotive supply chain specialists extend manufacturing expertise into equipment assembly for cooperative segments. Dominant competitive moves include strategic partnerships for localized assembly and portfolio diversification into precision agriculture technology layers.
Among Japanese multinationals, Kubota Corporation and Yanmar Holdings Co., Ltd. exemplify the premium-tier archetype with entrenched dealer financing infrastructure across southern provinces. Vietnam Engine & Agricultural Machinery Corp (VEAM) occupies a position within the state-backed manufacturing tier, while Truong Hai Group Corporation (THACO) represents automotive supply chain extension into mid-range equipment assembly. These three anchors illustrate the competitive structure: international premium brands, domestic state enterprises, and diversified industrial conglomerates each command distinct procurement channels.
| Leading Market Players |
|---|
| Kubota Corporation |
| Vietnam Engine & Agricultural Machinery Corp (VEAM) |
| Yanmar Holdings Co., Ltd. |
| Truong Hai Group Corporation (THACO) |
| Deere & Company (TTC Bien Hoa) |
| LS Mtron Co., Ltd. |
| Mahindra & Mahindra Ltd. |
| Hanoi Agricultural Machinery and Agricultural Extension Company (HAMCO) |
| CNH Industrial |
| Others |
Value Network & Pricing Analysis
Chinese engine and transmission sourcing clusters anchor cost structures for Vietnamese domestic assemblers, concentrating margin capture in downstream distribution and after-sales service networks rather than manufacturing value-add.
Pricing Analysis
Certification level against Vietnam's national quality regulator emission benchmarks creates the primary spread between subsidized domestic equipment and import-dependent premium tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by horsepower rating and telematics integration, with MARD subsidy eligibility compressing mid-range price points. Pricing pressure stems from steel input volatility and compressed dealer margins on smallholder-focused compact tractors. Vegetable cooperatives in Lam Dong province exhibit highest price sensitivity, while Central Highlands agribusinesses absorb premium positioning for precision-capable platforms.
Supply Chain Analysis
Contract manufacturing capacity concentrates with VEAM's state-backed assembly complexes and THACO's automotive-integrated production lines, supplemented by regional component sourcing from Thailand and Indonesia. Diesel engines above 37 kilowatts, hydraulic pump systems, and steel-grade chassis materials draw from Chinese and Indian supplier networks. Single-source vulnerability in certified after-treatment systems for emission compliance poses structural risk as domestic content verification tightens. Distribution runs through commune-level agricultural extension offices and cooperative credit unions, with dealer financing networks from Japanese multinationals serving premium-tier procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cooperative-led equipment pooling creates a platform-economics inflection as hourly booking systems displace individual ownership, with telematics-hydraulics convergence enabling service-revenue streams beyond hardware sales.
For Market Incumbents: Build captive financing moats through deeper integration with agricultural cooperative credit unions, locking in replacement cycle visibility. VEAM should expand emission-certified engine sourcing partnerships before MARD subsidy deadlines compress. Kubota's dealer technician certification infrastructure anchors defensible service revenue against emerging mid-range competitors. For New Entrants and Emerging Players: Central Highlands coffee mechanization represents the most penetrable entry point, with plantation zones currently underserved relative to Mekong Delta rice systems. Lam Dong province's year-round vegetable production sustains demand for compact inter-row cultivation equipment. A leasing-first go-to-market through provincial agricultural extension offices bypasses capital barriers that constrain direct sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with automotive supply chain extenders like THACO that have consolidated mid-range assembly capacity. Long-term viability hinges on precision agriculture technology integration capability rather than pure manufacturing scale. Monitor MARD subsidy eligibility criteria evolution as the inflection signal for portfolio rebalancing toward digitally integrated platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Partnership | Domestic content thresholds unlock MARD preferential financing channels for Mekong Delta cooperatives. |
| Telematics Platform Integration | Real-time diagnostics create recurring service revenue beyond equipment sale margins. |
| Dealer Technician Certification Program | Specialized hydraulic calibration training addresses skill gaps in northern mountainous provinces. |
| Emission Compliance Engine Sourcing | Certified after-treatment systems from Chinese suppliers satisfy tightened particulate matter thresholds. |
| Cooperative Credit Union Financing | Hire-purchase arrangements unlock demand from capital-constrained vegetable producers. |
Research Methodology
Cross-validation between primary interviews with agricultural cooperative managers and secondary trade data anchors the qualitative findings. Equipment distributor executives, MARD subsidy program administrators, diesel engine procurement leads at domestic assemblers, and commune-level extension officers provided operational perspective. Customs records, Vietnam Engine & Agricultural Machinery Corp production disclosures, and provincial agricultural statistical yearbooks supplied quantitative grounding. Bottom-up cooperative fleet inventories and top-down national mechanization rate estimates were reconciled.
Calibration against historical replacement cycle patterns and subsidy disbursement timelines shaped the analytical framework. Segmentation dimensions modeled include product type, application, technology tier, and end-user archetype across the projection horizon. CAGRs were derived from equipment stock turnover rates and cooperative expansion trajectories. Input variables incorporated labor cost compression indices in the Red River Delta and emission compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in agricultural credit availability and steel price volatility would shift the trajectory. Forecasts reflect documented assumptions regarding subsidy continuity and cooperative governance stability. Quarterly review of MARD procurement eligibility updates and provincial vocational program output is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market