
 China Agricultural Tractors Market | 2026-2036
China Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
China Agricultural Tractors Market Outlook
Domestic tractor manufacturing capacity in Shandong and Henan provinces is broadening as local foundries and transmission shops scale output for mid-horsepower platforms. Dongfeng Agricultural Machinery leverages captive engine production to control cost structures across its 40-80 HP range. First Tractor Company Limited anchors the high-horsepower segment with state-backed R&D programs targeting the 120+ HP category. Kubota competes through premium compact tractors designed for specialty crop operations in southern provinces.
Agricultural tractors are self-propelled vehicles engineered to deliver mechanical power through a power take-off shaft and three-point hitch, typically operating at drawbar loads between 15 kN and 75 kN depending on weight class and soil conditions; their primary purpose is to pull or power implements for tillage, planting, harvesting, and transport across arable land. Diesel tractors still occupy the dominant share of unit sales, though electric tractor prototypes from domestic OEMs are advancing toward commercial trials in greenhouse and orchard applications. The 40-80 HP power rating band generates the densest volume as family farms and cooperatives upgrade from hand-me-down equipment, while specialty tractors for hilly terrain in Yunnan and Guizhou sustain premium pricing through limited supplier competition.
China's Ministry of Ecology and Environment enforces GB 20891 emission tiers for non-road mobile machinery, compelling manufacturers to integrate common-rail fuel systems and after-treatment hardware. The Ministry of Agriculture and Rural Affairs manages the national agricultural machinery purchase subsidy catalog, which directs procurement incentives toward higher-efficiency, domestically produced equipment. MIIT's equipment modernization directives push intelligent IoT-enabled tractors into pilot demonstration zones. Stakeholders must monitor how subsidy tier adjustments and emission compliance deadlines reshape product portfolio priorities across the value chain.
Market Dynamics
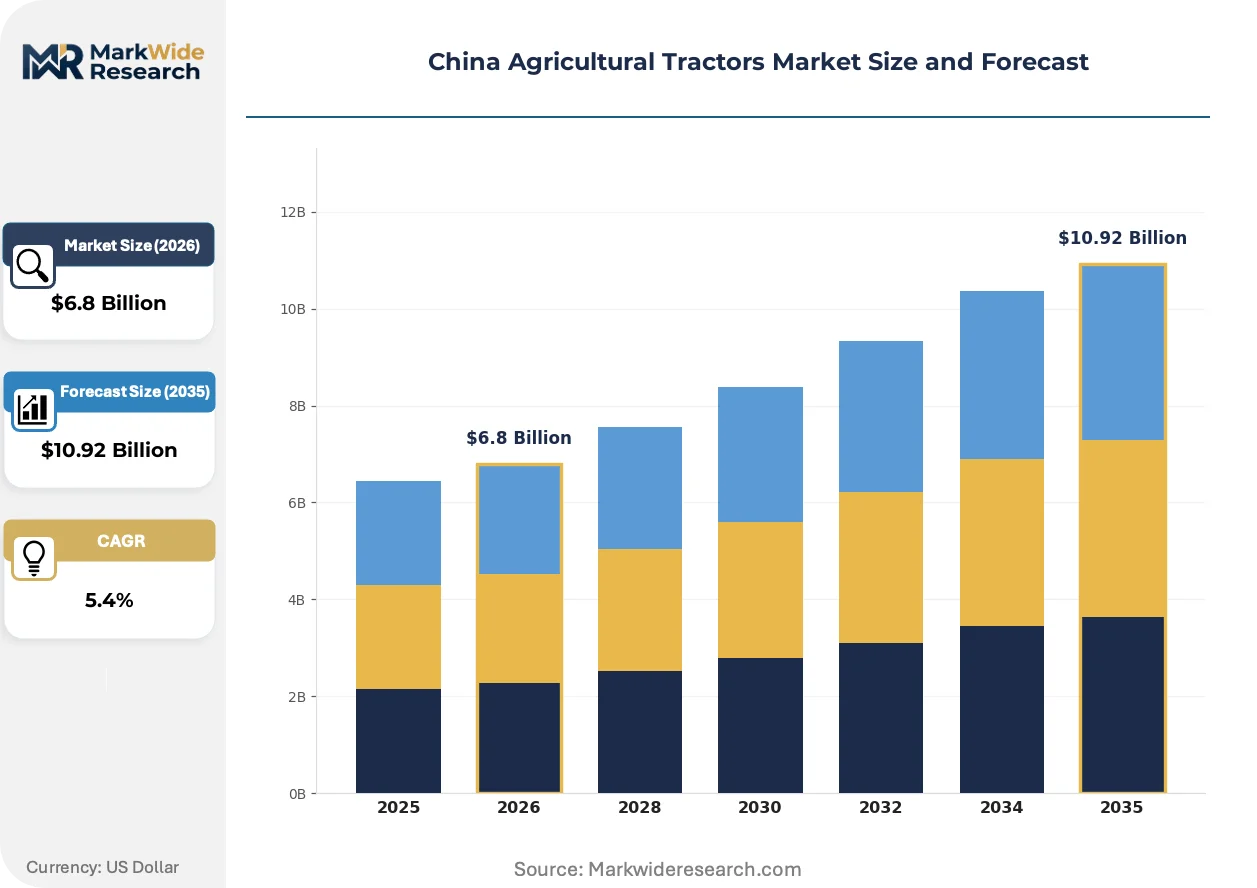
China's agricultural tractor market is being fundamentally restructured by the Ministry of Agriculture and Rural Affairs subsidy catalog, which redirects procurement incentives toward high-horsepower, domestically manufactured equipment and away from aging, lower-efficiency fleets across the North China Plain.
Growth Catalysts
- Subsidy tier escalation:The Ministry of Agriculture and Rural Affairs purchase subsidy catalog prioritizes 80+ HP machinery with higher reimbursement rates, accelerating cooperative fleet replacement cycles in Heilongjiang and Henan provinces.
- Grain cooperative consolidation:Large-scale farming cooperatives are expanding operational scale, generating concentrated demand for heavy-duty tillage and planting equipment across wheat-corn rotation systems.
- Emission compliance hardware integration:GB 20891 Tier IV standards mandate common-rail fuel systems and diesel particulate filters, creating aftermarket upgrade demand and new equipment pull-through.
Market Restraints
- Foundry capacity bottlenecks:Shandong and Henan transmission casting shops face input cost volatility for high-grade steel alloys, constraining mid-horsepower platform output expansion.
- Diesel engine supplier concentration:Captive engine production dominates cost structures for domestic OEMs, limiting third-party sourcing flexibility and competitive pricing pressure.
- Electric platform technical limitations:Battery energy density constraints and charging infrastructure gaps restrict electric tractor commercialization to greenhouse and orchard niche applications.
Strategic Opportunities
- Hilly terrain mechanization gaps:Specialty tractor demand in Yunnan and Guizhou provinces sustains premium pricing through limited supplier competition and topographical complexity.
- IoT-enabled fleet management:MIIT equipment modernization directives push intelligent telemetry systems into pilot demonstration zones, creating service revenue attachment opportunities.
- Orchard electrification trials:Domestic OEM electric prototypes targeting protected cultivation environments offer first-mover positioning ahead of broader commercialization.
Industry Challenges
- After-treatment calibration expertise:Common-rail and selective catalytic reduction system maintenance requires specialized technician training that dealer networks currently lack.
- Subsidy disbursement timeline compression:Provincial-level approval bottlenecks delay equipment procurement cycles, straining manufacturer working capital and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Agricultural Tractors Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Wheel Tractors, 4-Wheel Tractors, Compact Tractors, Specialty Tractors End User: Farms, Cooperatives, Agricultural Contractors, Government Agencies Technology: Electric Tractors, Hybrid Tractors, Diesel Tractors, Internet of Things (IoT) Tractors Power Rating: Below 40 HP, 40-80 HP, 80-120 HP, Above 120 HP |
| Companies Covered | Dongfeng Agricultural Machinery, MINNUO, Foton Lovol, CNH Industrial (New Holland), John Deere, China YTO Group, First Tractor Company Limited, Kubota, Zoomlion, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Agricultural Tractors Market Strategic Shifts
Telematics integration and powertrain electrification are actively redrawing competitive boundaries in Chinese agricultural equipment, while subsidy-linked procurement models reshape how cooperatives evaluate total cost of ownership against upfront capital outlay.
Precision agriculture sensor suites are decentralizing fleet management authority from centralized cooperative offices to individual machine operators. Large grain cooperatives in Heilongjiang are adopting these systems fastest, embedding soil moisture and yield mapping capabilities into 120+ HP units. Real-time data transmission is compressing decision cycles for planting density and fertilizer application, shifting operational control toward field-level execution.
GB 20891 emission tier enforcement from the Ministry of Ecology and Environment is compelling widespread common-rail fuel system adoption across the 40-120 HP product range. Manufacturers must integrate diesel particulate filters and selective catalytic reduction hardware, adding cost and complexity to mid-horsepower platforms. The 80-120 HP segment faces the steepest compliance burden, driving supplier consolidation around emission-certified engine architectures.
Cooperative procurement committees are consolidating vendor relationships around full-lifecycle service agreements rather than discrete equipment transactions. This behavior shift compresses dealer margins on unit sales while expanding multi-year maintenance contract attach rates. The North China Plain exhibits this pattern most visibly, where wheat-corn rotation intensity demands maximum uptime guarantees and rapid parts availability.
China Agricultural Tractors Market Segmentation
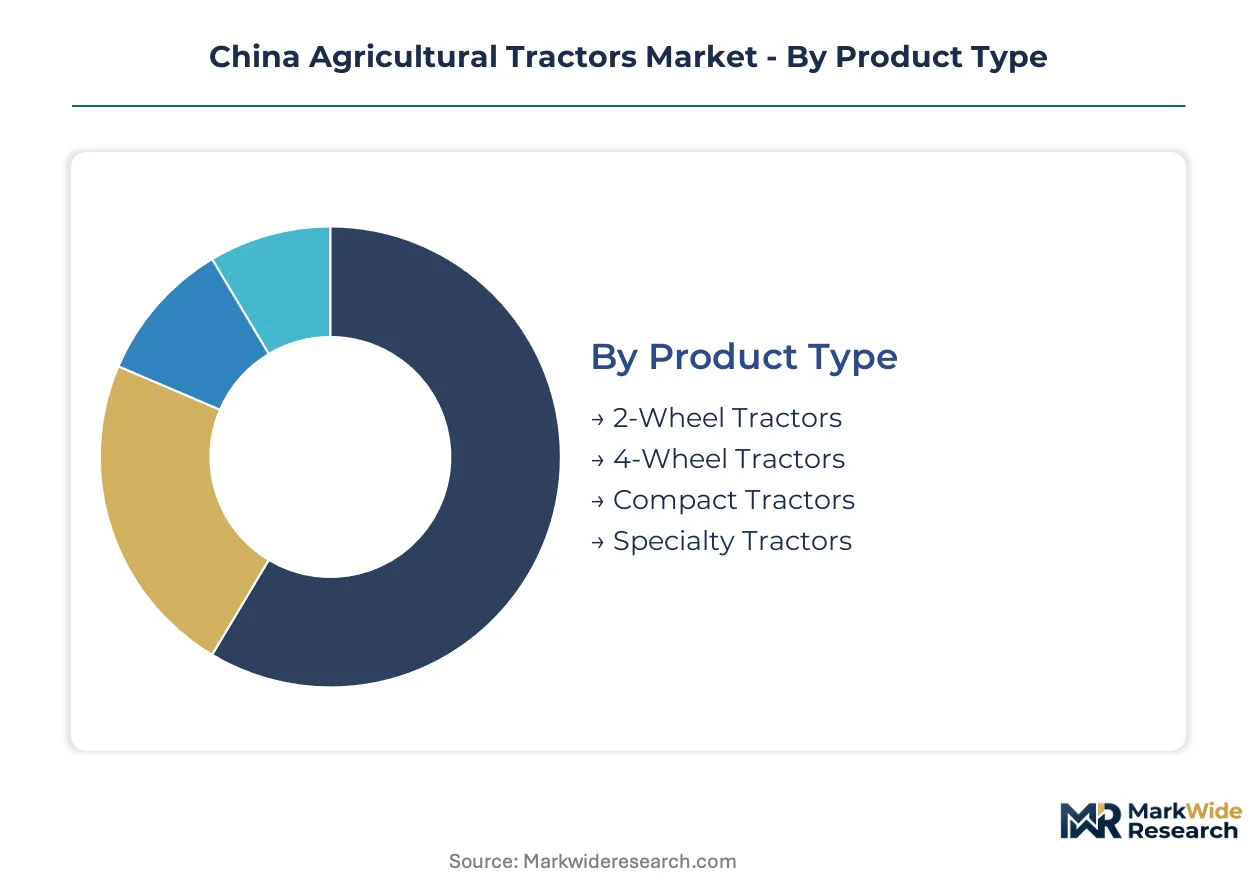
Segmentation in China's agricultural tractor market reveals how subsidy tiers, terrain constraints, and mechanization maturity create divergent equipment requirements across provinces and operator types. Understanding these splits allows manufacturers to align powertrain investments with procurement patterns that vary sharply between the North China Plain and southwestern highlands.
Product Type:
Product architecture determines traction geometry, weight distribution, and implement compatibility across China's varied tillage conditions.
- 4-Wheel Tractors:Standard four-wheel-drive platforms with articulated or rigid frames dominate wheat-corn rotation systems in Heilongjiang and Henan, where drawbar loads exceed 50 kN during deep tillage operations. Provincial cooperatives prioritize these units for fleet standardization under Ministry of Agriculture subsidy catalogs.
- Compact Tractors:Narrow-profile machines with sub-1.5 meter wheelbases navigate greenhouse corridors and orchard rows in Shandong and Jiangsu protected cultivation zones. Electric prototypes from domestic OEMs are concentrating trials in this segment ahead of broader commercialization.
- 2-Wheel Tractors:Lightweight walk-behind units serve smallholder plots in mountainous western provinces where field access limits four-wheel equipment deployment.
- Specialty Tractors:Articulated chassis with hillside stabilizers address topographical complexity in Yunnan and Guizhou tea and tobacco operations.
4-Wheel tractors lead on scale; compact tractors lead on momentum.
End User:
Procurement authority and capital access differentiate equipment specifications across China's agricultural operating structures.
- Cooperatives:Consolidated farming entities with centralized management purchase 80-120 HP fleets through collective tender processes, negotiating multi-year service attachments that compress dealer margins while locking parts availability guarantees.
- Farms:Family operations across the North China Plain concentrate demand in the 40-80 HP band as second-generation operators replace hand-me-down equipment with subsidy-supported upgrades.
- Agricultural Contractors:Seasonal service providers require rapid implement swap capability and telemetry-enabled fleet tracking to optimize equipment utilization across dispersed customer plots.
- Government Agencies:State demonstration farms and agricultural colleges procure high-horsepower units for research plots and technology showcase operations under MIIT modernization directives.
Cooperatives concentrate procurement volume; contractors are expanding most rapidly as outsourced mechanization displaces owned-fleet models.
Technology:
Powertrain architecture and connectivity layers are restructuring compliance costs and operational control in Chinese equipment markets.
- Diesel Tractors:Compression-ignition engines with common-rail fuel injection and selective catalytic reduction after-treatment dominate unit sales across all horsepower bands, though GB 20891 Tier IV compliance adds hardware cost and maintenance complexity.
- Internet of Things (IoT) Tractors:Telemetry-enabled platforms with soil sensors and yield mapping integrate into cooperative fleet management systems, compressing decision cycles for planting density and fertilizer application in Heilongjiang precision agriculture pilots.
- Electric Tractors:Battery-electric prototypes target greenhouse and orchard niches where daily duty cycles fit within charging windows and emission restrictions are tightest.
- Hybrid Tractors:Diesel-electric architectures remain pre-commercial, with domestic OEMs evaluating series-hybrid configurations for high-torque tillage applications.
Diesel platforms anchor current revenue; IoT-enabled units are gaining share fastest as MIIT pushes equipment modernization.
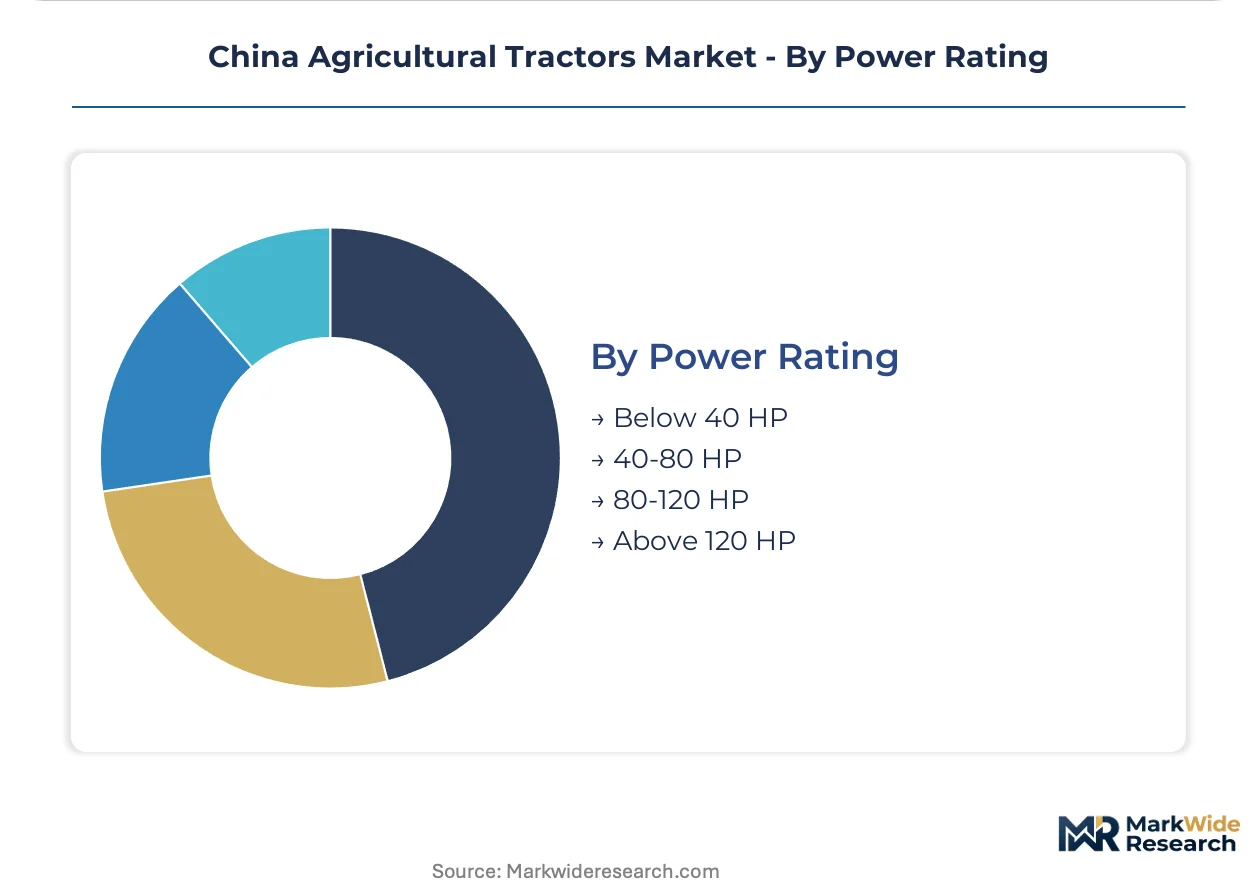
Power Rating:
Engine displacement and hydraulic capacity align with tillage intensity and implement width requirements across China's cropping systems.
- 80-120 HP:Six-cylinder diesels with 12-speed synchronized transmissions handle heavy-duty moldboard plowing and 24-row planters across the North China Plain, facing the steepest GB 20891 compliance burden and subsidy tier escalation pressure.
- 40-80 HP:Four-cylinder platforms with power take-off speeds of 540/1000 RPM serve diversified family farms in Henan and Shandong, generating densest volume as replacement cycles accelerate.
- Below 40 HP:Small-displacement units address vegetable plots and horticultural operations where field size limits equipment scale.
- Above 120 HP:High-horsepower articulated tractors from state-backed R&D programs target Heilongjiang grain cooperatives with ultra-wide implements and autonomous guidance capability.
The 40-80 HP band leads on unit volume; the above-120 HP segment is climbing the fastest on subsidy redirection and cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping tractor production geography as emission compliance costs widen between coastal manufacturing clusters and interior foundry zones. Provincial subsidy disbursement timelines and GB standard enforcement intensity now determine where assembly capacity expands versus contracts.
Heilongjiang
Large-scale grain cooperatives drive concentrated demand for 120+ HP articulated tractors across the Songnen Plain. The Ministry of Agriculture's elevated subsidy tiers for high-horsepower machinery accelerate fleet replacement cycles. Harbin anchors state-backed R&D programs targeting autonomous guidance systems for ultra-wide implements.
Henan
Wheat-corn rotation intensity generates dense procurement of 80-120 HP units for moldboard plowing and 24-row planting operations. Provincial cooperative consolidation redirects collective tender processes toward multi-year service attachments. Zhengzhou transmission foundries scale casting output for synchronized 12-speed platforms.
Shandong
Greenhouse corridor expansion in Weifang and protected cultivation zones sustains compact tractor demand for sub-1.5 meter wheelbase navigation. MIIT equipment modernization directives push IoT-enabled fleet pilots into demonstration farms. Local foundries face input cost volatility for high-grade steel alloys constraining mid-horsepower expansion.
Yunnan
Tea and tobacco operations on hillside terrain sustain premium pricing for specialty tractors with articulated chassis stabilizers. Limited supplier competition protects margin structures against coastal manufacturing cost pressures. Kunming distribution hubs struggle with spare parts logistics across mountainous western corridors.
Guizhou
Topographical complexity restricts four-wheel equipment deployment, preserving niche demand for hillside-stabilized platforms. Provincial subsidy catalog inclusion lags behind North China Plain provinces, delaying mechanization adoption timelines. Guiyang agricultural colleges host MIIT-directed precision agriculture pilot zones testing telemetry-enabled units.
China Agricultural Tractors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrification niches and IoT service attachments. The vendor base stratifies across three tiers: state-backed heavy-horsepower specialists, domestic mid-range volume manufacturers, and premium compact importers. Competitive positioning hardens around captive engine production, dealer network density, and subsidy catalog placement. Dominant moves include cooperative fleet service contract consolidation and common-rail emission system supplier partnerships.
Within the state-backed tier, First Tractor Company Limited anchors high-horsepower R&D programs targeting 120+ HP autonomous platforms. Dongfeng Agricultural Machinery exemplifies integrated cost control through captive engine production across the 40-80 HP band. Kubota occupies a premium position among compact tractor specialists serving southern province specialty crop operations. These three archetypes represent distinct strategic postures: state-directed scale, vertical integration discipline, and import premium positioning.
| Leading Market Players |
|---|
| Dongfeng Agricultural Machinery |
| MINNUO |
| Foton Lovol |
| CNH Industrial (New Holland) |
| John Deere |
| China YTO Group |
| First Tractor Company Limited |
| Kubota |
| Zoomlion |
| Others |
Value Chain & Pricing Dynamics
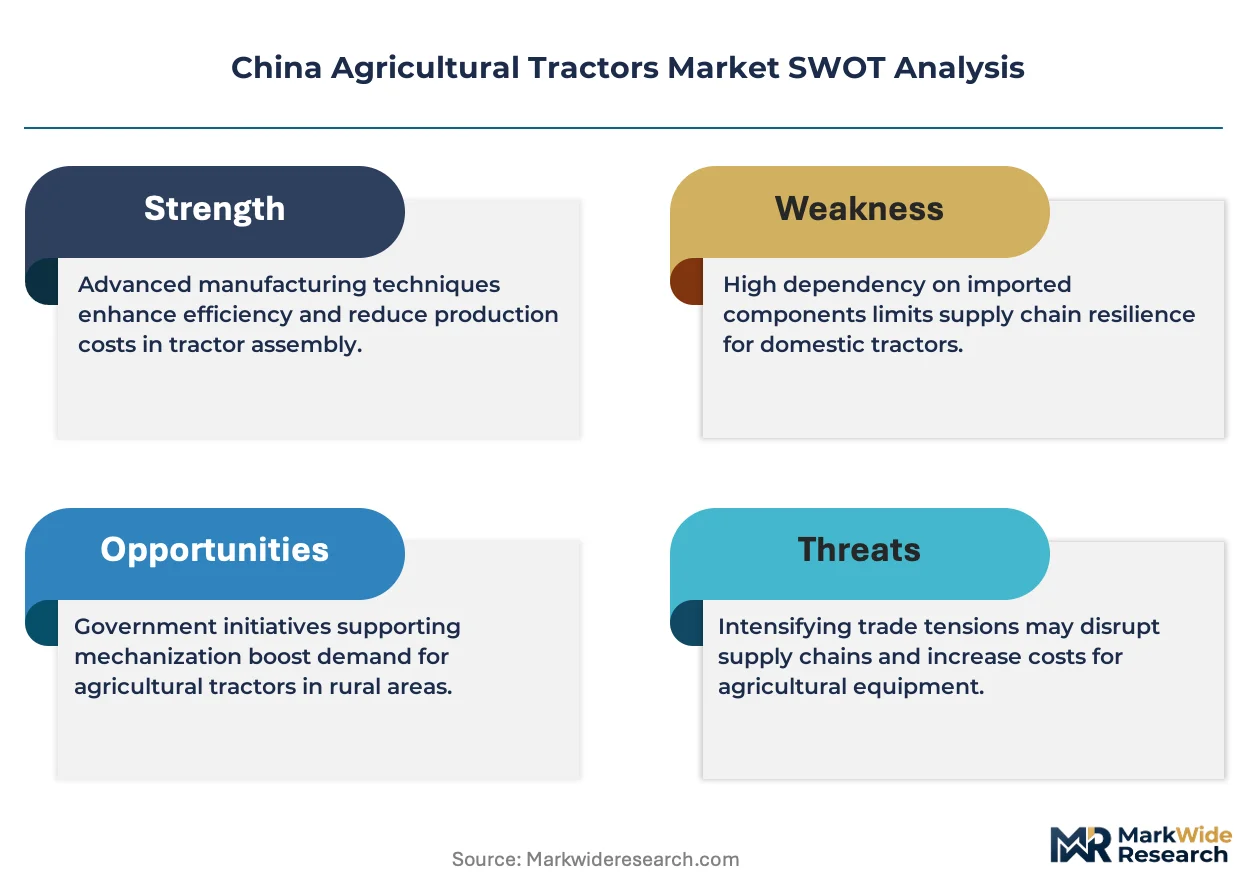
Common-rail fuel system adoption across the 40-120 HP range simultaneously escalates manufacturing cost structures and consolidates supplier power around emission-certified engine architectures. GB 20891 Tier IV compliance hardware integration reshapes both procurement economics and foundry tiering across Shandong and Henan manufacturing clusters.
Pricing Analysis
Distributor margins on unit sales compress as cooperative procurement committees negotiate multi-year service attachments. Three-tier pricing structure across premium, standard, and economy levels separates Kubota's import-positioned compact tractors from Dongfeng's vertically integrated mid-range platforms and local foundry economy units. Cost compression in the 80-120 HP band intensifies because common-rail and selective catalytic reduction hardware adds fixed cost without differentiation. Family farms in the 40-80 HP band exhibit highest price sensitivity; grain cooperatives purchasing 120+ HP fleets prioritize uptime guarantees over upfront capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cooperative demand in Heilongjiang and Henan, while dealer networks serve fragmented family farm procurement. Manufacturing concentrates in China, with transmission casting dependencies in Shandong and engine production anchored in Henan and Hubei. High-grade steel alloy inputs, common-rail injection systems, and diesel particulate filters constitute critical component dependencies. Single-source vulnerability around Tier IV-certified engine architectures poses structural risk. Distribution runs through provincial-level agricultural machinery subsidy catalog approval chains that strain manufacturer working capital.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as Ministry of Agriculture subsidy tier escalation locks in replacement demand across mechanizing provinces. Equipment modernization directives from MIIT sustain upgrade cycles regardless of commodity price volatility.
For Market Incumbents: Extend service contract attach rates beyond basic warranty periods to capture recurring revenue as unit margins tighten. Deepen captive engine production coverage into the 80-120 HP band before emission compliance costs consolidate supplier tiers. Counter emerging electric entrants in greenhouse corridors by pre-empting orchard electrification pilots with hybrid prototypes. For New Entrants and Emerging Players: Agricultural contractors represent the most underserved buyer archetype, with telemetry-enabled fleet management demand outpacing incumbent service capabilities. Specialty tractor gaps in Yunnan and Guizhou tea operations offer protected pricing environments with limited coastal competition. Lead with rapid implement swap capability and usage-based financing rather than competing on horsepower specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic mid-horsepower manufacturers lacking captive engine production but holding strong provincial subsidy catalog placement. Long-term viability hinges on emission compliance hardware integration capability and cooperative relationship depth. Watch for MIIT demonstration zone expansion announcements as inflection signals for IoT-enabled fleet management adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Common-Rail Emission System Partnership | Secures GB 20891 Tier IV certification access for 80-120 HP platform renewal. |
| Cooperative Fleet Service Contract Consolidation | Locks multi-year maintenance revenue as unit sales margins compress under tender pressure. |
| IoT Telemetry Platform Integration | Captures MIIT modernization directive funding in Heilongjiang precision agriculture pilots. |
| Orchard Electrification Prototype Launch | Positions first-mover advantage ahead of broader battery-electric commercialization. |
| Transmission Foundry Capacity Expansion | Alleviates Shandong input cost volatility constraints on mid-horsepower output scaling. |
Study Parameters
Coverage spans Heilongjiang, Henan, Shandong, Yunnan, and Guizhou provinces, with primary inputs from each regional manufacturing cluster. Conversations with cooperative procurement managers, provincial agricultural machinery subsidy administrators, transmission foundry operations heads, and diesel engine R&D directors combined with bottom-up triangulation against customs records, Ministry of Agriculture subsidy disbursement databases, MIIT equipment modernization filings, and GB standards compliance registries.
Rate-of-change decomposition across horsepower bands, technology tiers, and end-user segments structured the analytical framework. Segmentation dimensions modeled include power rating architecture, emission compliance tier, cooperative versus family farm procurement authority, and regional mechanization maturity. CAGRs derived from equipment replacement cycle analysis, subsidy tier redirection timing, and foundry capacity expansion trajectories. Forecast inputs incorporated GB 20891 enforcement phase-in schedules and MIIT demonstration zone rollout patterns.
Inputs from provincial subsidy administrators and foundry operations were available through the study window; gaps in electric tractor commercialization timelines introduce uncertainty bands around battery-electric adoption curves. Forecasts reflect assumptions on cooperative consolidation velocity and emission compliance cost pass-through elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
United States Agricultural Tractor Market