
 Australia Agricultural Machinery Market | 2026-2036
Australia Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Agricultural Machinery Market Outlook
Dealer networks in rural Australia are narrowing as manufacturer-direct service models and regional consolidation redraw how farmers access parts and technical support. Deere & Company anchors its position through vertically integrated precision agriculture ecosystems spanning hardware, software, and subscription analytics. Kubota Corporation competes aggressively in the sub-100 horsepower tractor segment where small-to-midscale producers dominate replacement cycles. CNH Industrial N.V. leverages its Case IH and New Holland brand architecture to sustain dual-channel coverage across broadacre and livestock applications.
Agricultural machinery encompasses self-propelled and towed equipment engineered to execute soil preparation, planting, cultivation, harvesting, and post-harvest processing with specified power outputs, draft forces, and field efficiencies measured in hectares per hour. Tractors constitute the foundational revenue pool given their universal role as prime movers across all farm scales, while harvesters command premium positioning due to seasonal utilization intensity and proprietary threshing technologies. Precision Agriculture and Autonomous Machinery segments attract disproportionate R&D allocation as GPS-guided steering and sensor-based variable-rate application displace manual operator input and reduce overlap waste.
The Australian Pesticides and Veterinary Medicines Authority (APVMA) regulates chemical application equipment standards, while the Australian Competition and Consumer Commission (ACCC) scrutinizes dealer territorial restrictions and aftermarket parts access. State-level WorkSafe authorities mandate rollover protective structures and operator training certifications that filter equipment eligibility for commercial contracting fleets. Stakeholders must monitor evolving carbon accounting methodologies and diesel transition pathways as these frameworks increasingly influence finance availability and resale value trajectories for combustion-dependent machinery platforms.
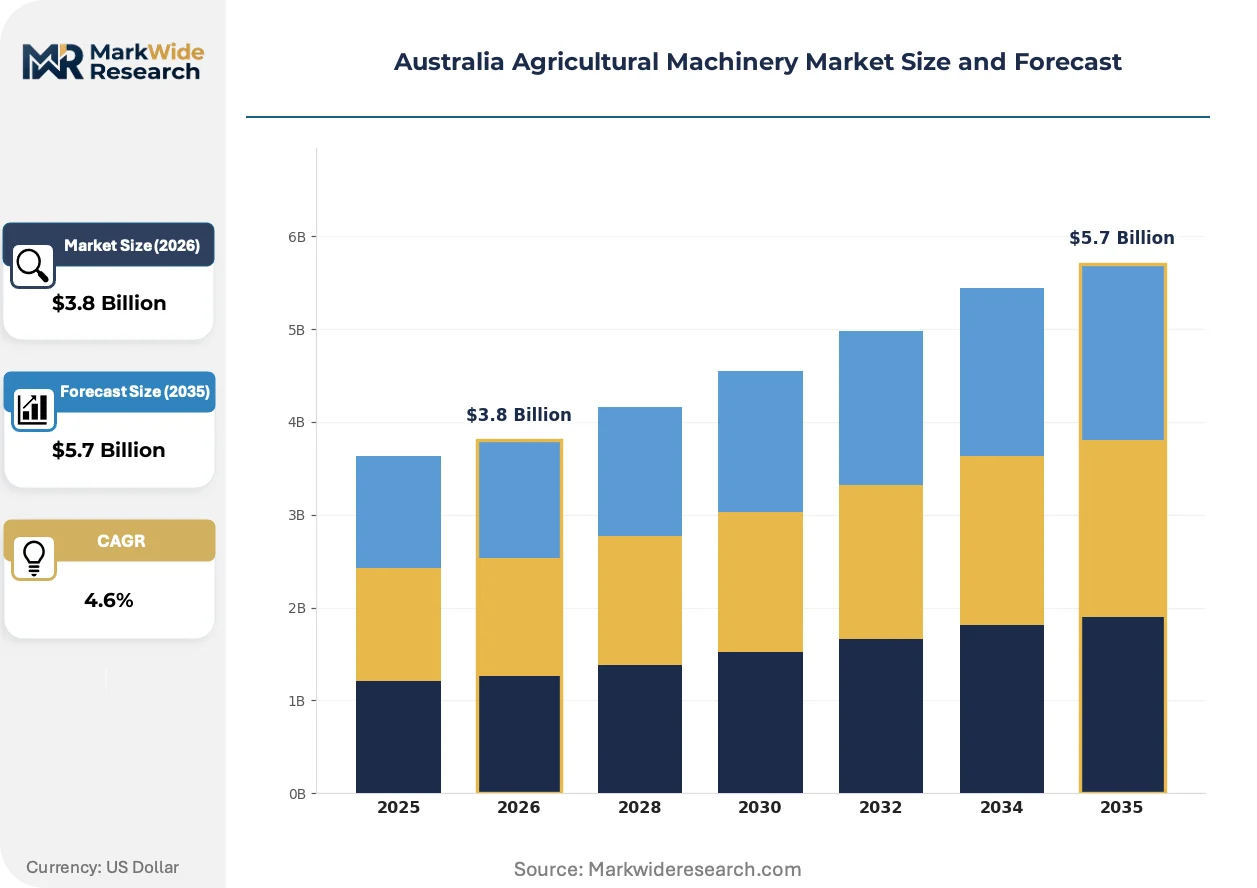
Market Dynamics
Queensland's sugarcane belt and Victoria's dairy corridors are accelerating fleet replacement as irrigation automation and precision planting systems displace legacy tillage methods. The national biosecurity framework and state-level diesel rebate adjustments are compressing procurement timelines and forcing rapid recalibration of fuel efficiency specifications across broadacre operations.
Growth Catalysts
- APVMA Equipment Standards:The Australian Pesticides and Veterinary Medicines Authority's chemical application equipment mandates are compelling upgrades to precision sprayers with drift-reduction nozzles and automated boom controls.
- Western Australia Labor Shortages:Persistent workforce gaps in broadacre cropping operations are accelerating autonomous tractor deployment and GPS-guided cultivation systems across the Wheatbelt region.
- Variable-Rate Application Technology:Sensor-based input modulation is reducing overlap waste and fertilizer runoff, delivering measurable cost savings for grain producers in New South Wales.
Market Restraints
- Diesel Price Volatility:Fluctuations in refined fuel costs are squeezing operating margins for contractors running high-horsepower harvesters and self-propelled sprayers across extended seasonal windows.
- Dealer Network Consolidation:Rural service point closures are extending parts procurement lead times and degrading technical support accessibility for remote Queensland grazing properties.
- Steel and Component Import Dependency:Heavy reliance on Asian-sourced hydraulic systems and precision electronics creates vulnerability to maritime shipping disruptions and tariff fluctuations.
Strategic Opportunities
- Tasmanian Irrigation Expansion:The state's accelerated dam and pipeline infrastructure buildout is generating demand for center-pivot automation and soil moisture monitoring systems in previously rain-fed sectors.
- Carbon Accounting Integration:Emerging farm-level emissions verification protocols are creating attach rates for telemetry-equipped machinery that automates fuel consumption and field activity documentation.
- Subscription Analytics Convergence:Bundled hardware-software-service models are penetrating mid-scale Victorian dairy operations previously priced out of standalone precision agriculture platforms.
Industry Challenges
- Autonomous Systems Integration:Retrofitting legacy fleets with ISO 11783-compliant task controllers and implement electronics requires specialized technician capabilities scarce in regional Australia.
- WorkSafe Certification Timelines:Rollover protective structure compliance verification and operator competency assessments are extending equipment commissioning cycles for commercial contracting fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Agricultural Machinery Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Ploughs, Harvesters, Seeders End User: Farmers, Co-operatives, Agricultural Contractors, Distributors Technology: Precision Agriculture, Autonomous Machinery, GPS Technology, IoT Solutions Application: Crop Cultivation, Soil Preparation, Irrigation, Pest Control |
| Companies Covered | Deere & Company, Kubota Corporation, CNH Industrial N.V., AGCO Corporation, CLAAS KGaA mbH, Mahindra & Mahindra Ltd., Valmont Industries, Inc., Netafim Ltd., KUHN SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Agricultural Machinery Market Strategic Shifts
Telemetry and predictive maintenance architectures are virtualizing how machinery performance is monitored and monetized. The convergence of edge computing and cellular connectivity is compressing the gap between field operations and remote diagnostics.
Telematics platforms embedded in harvesters and tractors are virtualizing equipment uptime management through real-time engine diagnostics, geo-fencing alerts, and automated service scheduling. Grain cooperatives in South Australia are adopting these systems fastest, using aggregated fleet data to negotiate preferential parts pricing and priority technician dispatch. This virtualization is compressing the traditional dealer service model by enabling manufacturer-direct remote troubleshooting and over-the-air software calibration.
The Australian Competition and Consumer Commission's scrutiny of dealer territorial restrictions is reshaping aftermarket parts access and third-party service eligibility. Machinery owners in New South Wales and Queensland are gaining legal pathways to independent repair options previously blocked by proprietary diagnostic tool lockouts. Broadacre operators with mixed-brand fleets are responding by consolidating service contracts with non-dealer technical specialists capable of cross-platform maintenance.
Acquisition patterns among sugarcane and cotton growers are rotating toward machinery-as-a-service arrangements with bundled fuel, maintenance, and seasonal operator provision. Equipment financiers in northern Queensland are structuring harvester leases with utilization-linked payment schedules rather than fixed-term debt obligations. This behavioral shift is most visible in the Burdekin and Ord River irrigation districts where crop price volatility makes capital-intensive ownership increasingly unattractive.
Australia Agricultural Machinery Market Segmentation
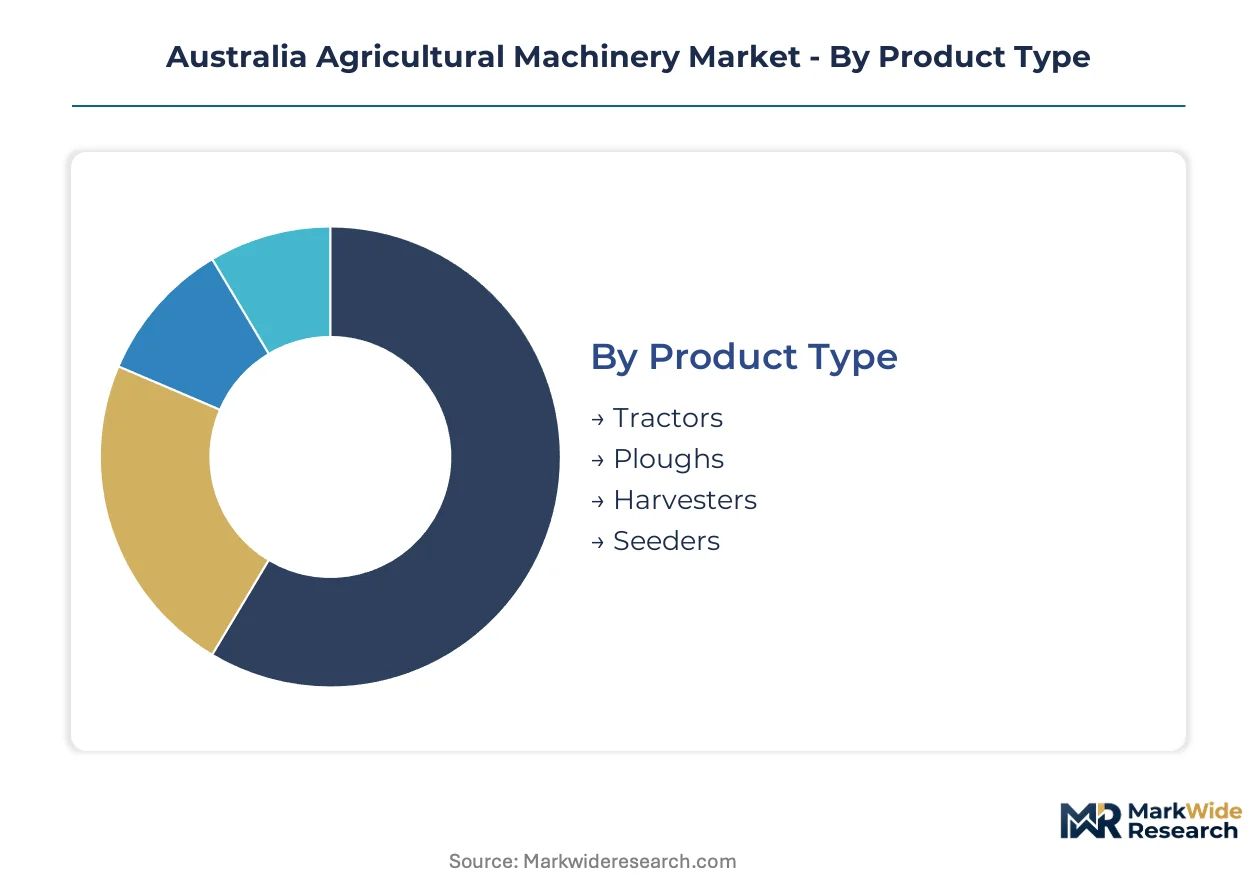
Equipment procurement patterns across Australian agriculture diverge sharply by operational scale, crop type, and capital intensity. Segmentation reveals how technology adoption clusters around labor constraints in broadacre regions versus input optimization in intensive horticulture and dairy.
Product Type:
Mature mechanical platforms anchor revenue stability while emerging precision-enabled categories capture upgrade cycles.
- Tractors:Universal prime movers spanning 25-400 horsepower ratings serve as the mechanical foundation across all farm scales. Demand concentrates in Queensland's sugarcane belt and Western Australia's Wheatbelt where fleet expansion offsets persistent labor shortages.
- Harvesters:Self-propelled combines and specialty cane harvesters command premium positioning through proprietary threshing mechanisms and seasonal utilization intensity. Grain cooperatives in South Australia prioritize telemetry-equipped models for fleet-wide uptime optimization.
- Ploughs:Tillage implements face displacement pressure from minimum-till seeding systems in New South Wales broadacre operations.
- Seeders:Precision planting equipment with variable-rate capability is gaining attach rates in Victorian dairy corridors transitioning to fodder crop intensification.
Tractors retain volume leadership; harvesters hold the steepest expansion curve through precision agriculture integration.
End User:
Customer scale determines technology access tiers and financing sophistication across the procurement landscape.
- Farmers:Owner-operators dominate replacement cycles in the sub-100 horsepower tractor segment where Kubota Corporation competes aggressively for small-to-midscale producers.
- Agricultural Contractors:Commercial service fleets across extended seasonal windows drive demand for high-horsepower harvesters and self-propelled sprayers with rollover protective structures mandated by state-level WorkSafe authorities.
- Co-operatives:Grain handling entities in South Australia aggregate fleet data to negotiate preferential parts pricing and priority technician dispatch through embedded telematics platforms.
- Distributors:Dealer networks in rural Australia are narrowing as manufacturer-direct service models redraw parts accessibility and technical support geography.
Individual farmers retain volume leadership; agricultural contractors hold the steepest expansion curve through machinery-as-a-service adoption.
Technology:
Digital infrastructure investments cluster where cellular connectivity and farm management software maturity converge.
- Precision Agriculture:Sensor-based input modulation and GPS-guided steering reduce overlap waste and fertilizer runoff for grain producers. Deere & Company anchors this segment through vertically integrated hardware-software-subscription ecosystems.
- Autonomous Machinery:Self-driving tractors and implement carriers address workforce gaps in Western Australia's broadacre cropping operations. Retrofitting legacy fleets with ISO 11783-compliant task controllers requires specialized technician capabilities scarce in regional Australia.
- GPS Technology:RTK correction signals and geo-fencing capabilities underpin automated boom controls on precision sprayers meeting APVMA drift-reduction mandates.
- IoT Solutions:Edge computing architectures compress diagnostic latency between field operations and remote support centers.
GPS-enabled equipment retains volume leadership; autonomous systems hold the steepest expansion curve as labor scarcity deepens.
Application:
Task-specific equipment demand tracks crop mix shifts and irrigation infrastructure buildout across state boundaries.
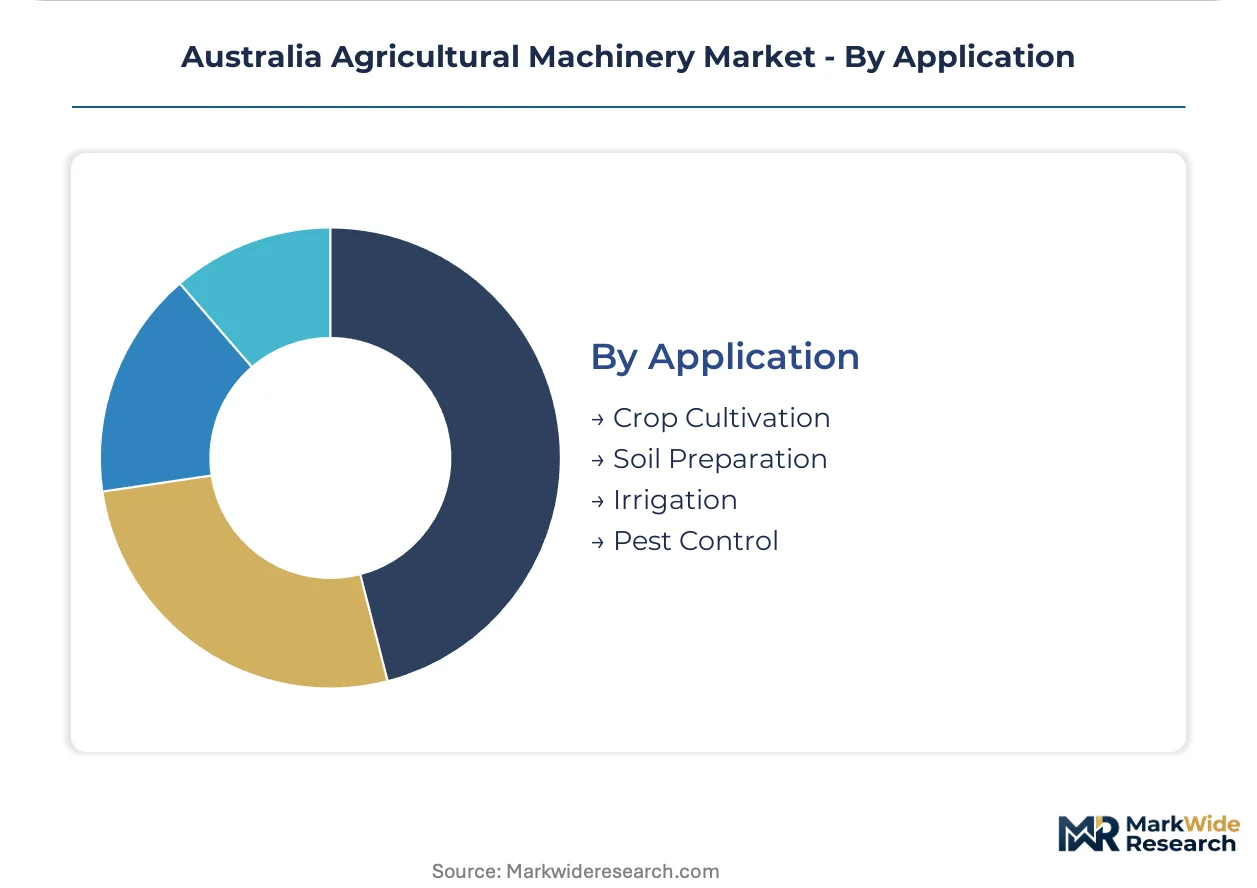
- Crop Cultivation:Precision planting and cultivation systems displace legacy tillage methods in Queensland's sugarcane belt where irrigation automation accelerates fleet replacement.
- Soil Preparation:Minimum-till adoption in New South Wales reduces primary tillage intensity while residue management implements gain attach rates.
- Irrigation:Center-pivot automation and soil moisture monitoring systems penetrate Tasmanian sectors previously rain-fed, driven by accelerated dam and pipeline infrastructure expansion.
- Pest Control:Chemical application equipment faces APVMA-mandated upgrades to precision sprayers with drift-reduction nozzles and automated boom controls.
Soil preparation retains volume leadership; irrigation automation holds the steepest expansion curve through state infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's sugarcane belt commands machinery pricing premiums against South Australia's grain cooperatives, creating procurement asymmetries that reshape dealer network economics across state boundaries. New South Wales and Victoria anchor volume throughput while Western Australia's labor scarcity accelerates technology deployment premiums.
New South Wales
Broadacre cropping operations in the Riverina and Central West are expanding minimum-till seeding fleets to replace legacy tillage implements. The state's WorkSafe authority mandates rollover protective structure compliance verification that extends equipment commissioning cycles for commercial contractors. Grain handling clusters around Wagga Wagga and Dubbo are aggregating telematics data to negotiate priority technician dispatch agreements.
Victoria
Dairy corridors in Gippsland and the Murray Dairy region are driving precision planting attach rates as fodder crop intensification displaces pasture-based systems. The state's environmental regulator enforces chemical runoff standards that compel upgrades to drift-reduction sprayer nozzles. Irrigation automation clusters around Shepparton and Rochester are generating demand for soil moisture monitoring systems.
Queensland
Sugarcane growers in the Burdekin and Ord River irrigation districts are rotating toward machinery-as-a-service arrangements with bundled fuel and maintenance provision. The APVMA regulates chemical application equipment standards that mandate automated boom controls on new sprayer acquisitions. Harvesting contractor fleets around Ayr and Ingham face extended parts procurement lead times from rural dealer network consolidation.
Western Australia
Wheatbelt broadacre operations are deploying autonomous tractors and GPS-guided cultivation systems to offset persistent workforce gaps in cropping programs. The state's diesel rebate adjustments are compressing procurement timelines and forcing rapid recalibration of fuel efficiency specifications across the agricultural sector. Machinery service clusters around Esperance and Geraldton are scarce in ISO 11783-compliant technician capabilities for legacy fleet retrofitting.
South Australia
Grain cooperatives in the Eyre Peninsula and Murray Mallee are adopting telemetry-equipped harvesters fastest for fleet-wide uptime optimization. The state's biosecurity framework shapes equipment procurement timelines through import inspection protocols for Asian-sourced hydraulic components. Precision agriculture adoption concentrates around Port Lincoln and Loxton where cellular connectivity infrastructure supports edge computing architectures.
Australia Agricultural Machinery Market Competitive Environment
Full-line manufacturers and precision technology specialists split the market along capital intensity and software integration vectors. The vendor base concentrates around vertically integrated ecosystems spanning hardware, subscription analytics, and remote diagnostics capabilities. Three archetypes dominate: integrated precision agriculture platforms, sub-100 horsepower tractor specialists, and dual-brand broadacre-livestock coverage players. Competitive moves center on manufacturer-direct service model expansion and bundled hardware-software-service subscription convergence.
Within the integrated ecosystem tier, Deere & Company anchors positioning through vertically integrated precision agriculture architectures. Kubota Corporation occupies the sub-100 horsepower specialist position where small-to-midscale producer replacement cycles concentrate. CNH Industrial N.V. exemplifies dual-brand coverage across broadacre and livestock applications through its Case IH and New Holland brand architecture.
| Leading Market Players |
|---|
| Deere & Company |
| Kubota Corporation |
| CNH Industrial N.V. |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Mahindra & Mahindra Ltd. |
| Valmont Industries, Inc. |
| Netafim Ltd. |
| KUHN SAS |
| Others |
Value Chain & Pricing Dynamics
Freight corridors through Port Botany and Fremantle compress landed costs for Asian-sourced hydraulic systems while amplifying price spreads between configured-to-order precision agriculture platforms and standard tractor configurations. Diesel rebate adjustments by state treasuries force rapid recalibration of procurement timelines, concentrating pricing power with manufacturers who bundle telemetry subscriptions and over-the-air software calibration.
Pricing Analysis
Configured-to-order precision agriculture platforms command substantial premiums over standard tractor configurations, with customization depth and GPS-guided steering tiers as primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies by horsepower rating, after-sales service bundling, and ISO 11783 compliance certification. Cost compression in the sub-100 horsepower segment intensifies as Kubota Corporation and Mahindra & Mahindra Ltd. compete for replacement cycles among small-to-midscale producers. Agricultural contractors running high-horsepower harvesters exhibit lowest price sensitivity due to machinery-as-a-service financing structures, while owner-operators in Victoria's dairy corridors face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for precision electronics concentrates with Taiwanese and South Korean foundries, while hydraulic system assembly anchors in Chinese industrial zones. Australian agricultural machinery draws from Japanese transmission specialists, German engine component suppliers, and Indian casting operations for structural frames. Single-source vulnerability in RTK correction signal hardware and edge computing modules creates exposure to maritime shipping disruptions through the Singapore-Jakarta logistics chokepoint. Distribution runs through consolidating dealer networks in rural Queensland and Western Australia, with manufacturer-direct service models eroding traditional territorial exclusivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
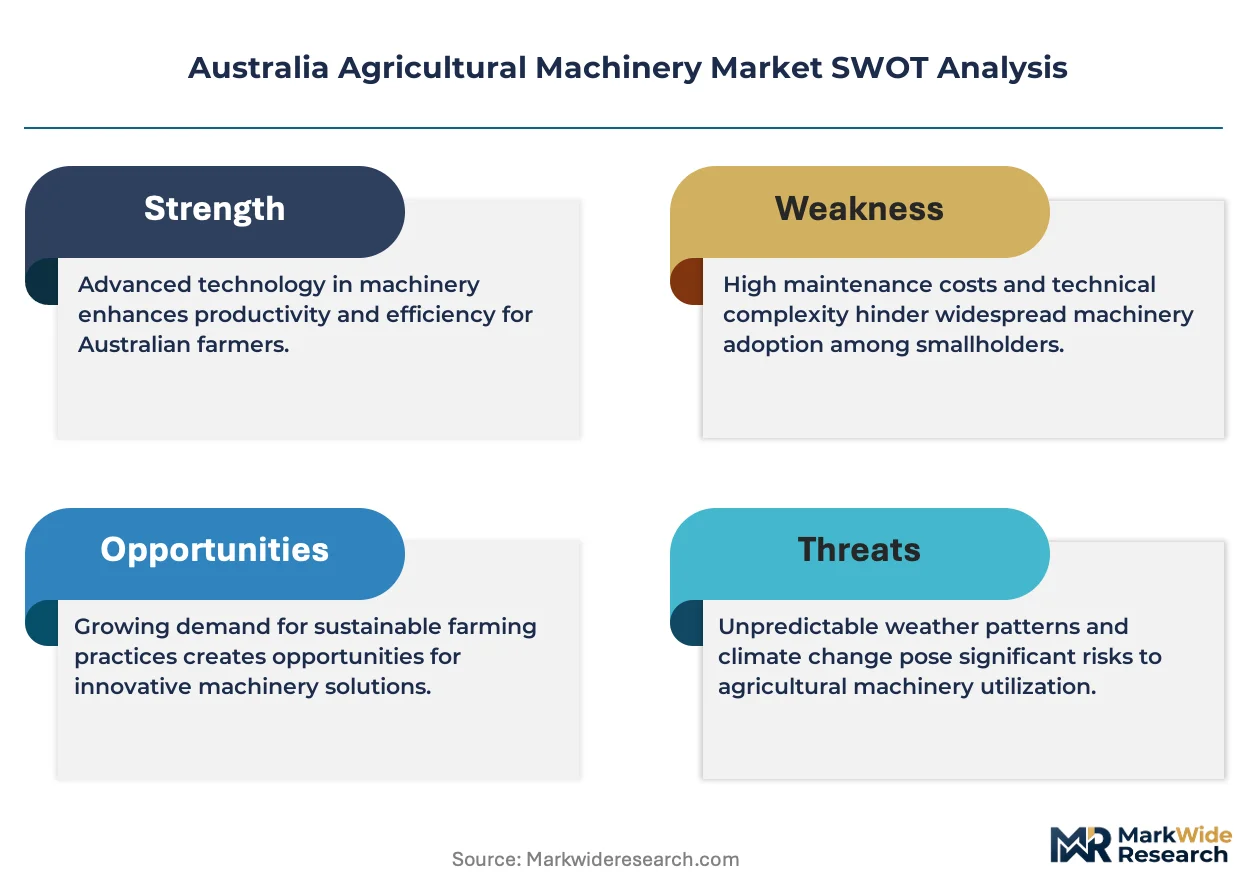
Autonomous tractor deployment and APVMA-mandated precision sprayer upgrades constitute a high-growth disruption, with regulatory inflections in chemical application equipment standards forcing compressed replacement cycles across broadacre operations.
For Market Incumbents: Harden service infrastructure in Western Australia's Wheatbelt against technician scarcity for ISO 11783 retrofitting, while deepening backward integration into telemetry software stacks to defend subscription revenue pools. Lock in multi-year parts procurement agreements with Asian hydraulic suppliers before tariff volatility materializes.
For New Entrants and Emerging Players: Build out machinery-as-a-service platforms targeting Queensland sugarcane contractors facing crop price volatility, with utilization-linked payment schedules replacing fixed-term debt obligations. Penetrate Tasmanian irrigation expansion zones through center-pivot automation partnerships with state infrastructure agencies.
For Investors and Strategic Acquirers: APVMA equipment standard enforcement reshapes the acquisition landscape toward precision sprayer specialists with drift-reduction nozzle portfolios. Long-term viability centers on telemetry-enabled assets that automate carbon accounting documentation for farm-level emissions verification protocols. Watch for consolidation signals among regional dealer networks facing manufacturer-direct competitive pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Deere & Company's vertically bundled hardware-software-subscription ecosystems capture recurring revenue from Victorian dairy corridors. |
| Autonomous Machinery Certification | WorkSafe rollover protective structure mandates extend commissioning cycles, favoring incumbents with compliance expertise. |
| Dealer Network Consolidation | Manufacturer-direct service models degrade traditional territorial exclusivity, compressing parts margins in rural Queensland. |
| Carbon Accounting Telemetry Attachment | Fuel consumption automation aligns with emerging farm-level emissions verification protocols in South Australian grain cooperatives. |
| Asian Component Supply Agreements | Long-term hydraulic system contracts insulate against maritime shipping disruptions and tariff fluctuations. |
Study Parameters
Operator-level perspectives from agricultural contractors, dealer network principals, precision agriculture specialists, and state WorkSafe compliance officers anchored the qualitative base. Primary interviews with farm equipment fleet managers and OEM procurement teams combined with secondary validation through APVMA equipment registration databases, Australian Bureau of Agricultural and Resource Economics trade statistics, and ACCC aftermarket access rulings. Bottom-up equipment shipment aggregation and top-down macroeconomic factor triangulation structured the analytical approach.
Scenario-bracketing across diesel price volatility, labor shortage severity, and biosecurity inspection protocol intensity framed the projection horizon. Segmentation dimensions modeled include product type, end-user scale, technology tier, and application intensity across state-level agricultural zones. CAGRs derived from historical replacement cycle analysis and penetration rate trajectories for precision agriculture and autonomous systems. Industry-specific forecast inputs incorporated APVMA regulatory timeline assumptions and state infrastructure investment commitments.
Stress conditions across refined fuel cost bands, maritime shipping disruption scenarios, and technician availability thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding diesel rebate continuity and cellular connectivity buildout pace. Quarterly review of APVMA equipment standard enforcement intensity and state-level carbon accounting protocol adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
Autonomous Farm Equipment Market