
 South Africa Alfalfa Hay Market | 2026-2036
South Africa Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Alfalfa Hay Market Analytics
Market Context
Teff grass is broadening its displacement of alfalfa in certain rations, yet alfalfa hay retains superior crude protein density that sustains premium pricing for high-performance livestock. Alpha Alfa (Pty) Ltd leverages vertical integration from seed to baled product across the Northern Cape irrigation schemes. NWK Limited anchors its position through extensive grain-and-feed distribution infrastructure that reaches deep into Mpumalanga's dairy belt. Afgri Limited competes by controlling input supply channels and on-farm technical advisory services that lock in grower loyalty.
Product Definition and Segmentation
South Africa alfalfa hay, known locally as lucerne, consists of dried Medicago sativa foliage with crude protein content typically ranging from 15% to 22% on a dry-matter basis, harvested at early bloom to preserve digestible fiber and metabolizable energy for ruminant nutrition. The primary commercial purpose centers on maximizing milk production in dairy herds and supporting weight gain in beef finishing programs. Dehydrated product commands the premium tier due to consistent nutrient retention and lower mold risk, while pelleted formats gain traction among poultry operations seeking reduced feed waste and automated handling compatibility. Dairy farms represent the deepest end-user pool, though equestrian centers in Gauteng and the Western Cape emerge as a specialized growth pocket with exacting quality specifications and low price sensitivity.
Regulatory Environment and Outlook
The Department of Agriculture, Land Reform and Rural Development enforces the Fertilizers, Farm Feeds, Seeds and Remedies Act, which mandates registration and labeling standards that filter out informal hay traders and elevate compliance costs for commercial processors. South African Bureau of Standards (SBS) quality certifications and emerging sustainability protocols from the EU Green Deal exert parallel pressure on export-oriented growers to document water usage and pesticide residues. Stakeholders must monitor whether Pretoria aligns domestic feed safety rules with Codex Alimentarius guidelines, as this alignment would unlock Middle Eastern dairy markets but require costly laboratory verification infrastructure that smaller Free State baling operations lack capital to install.
Market Dynamics
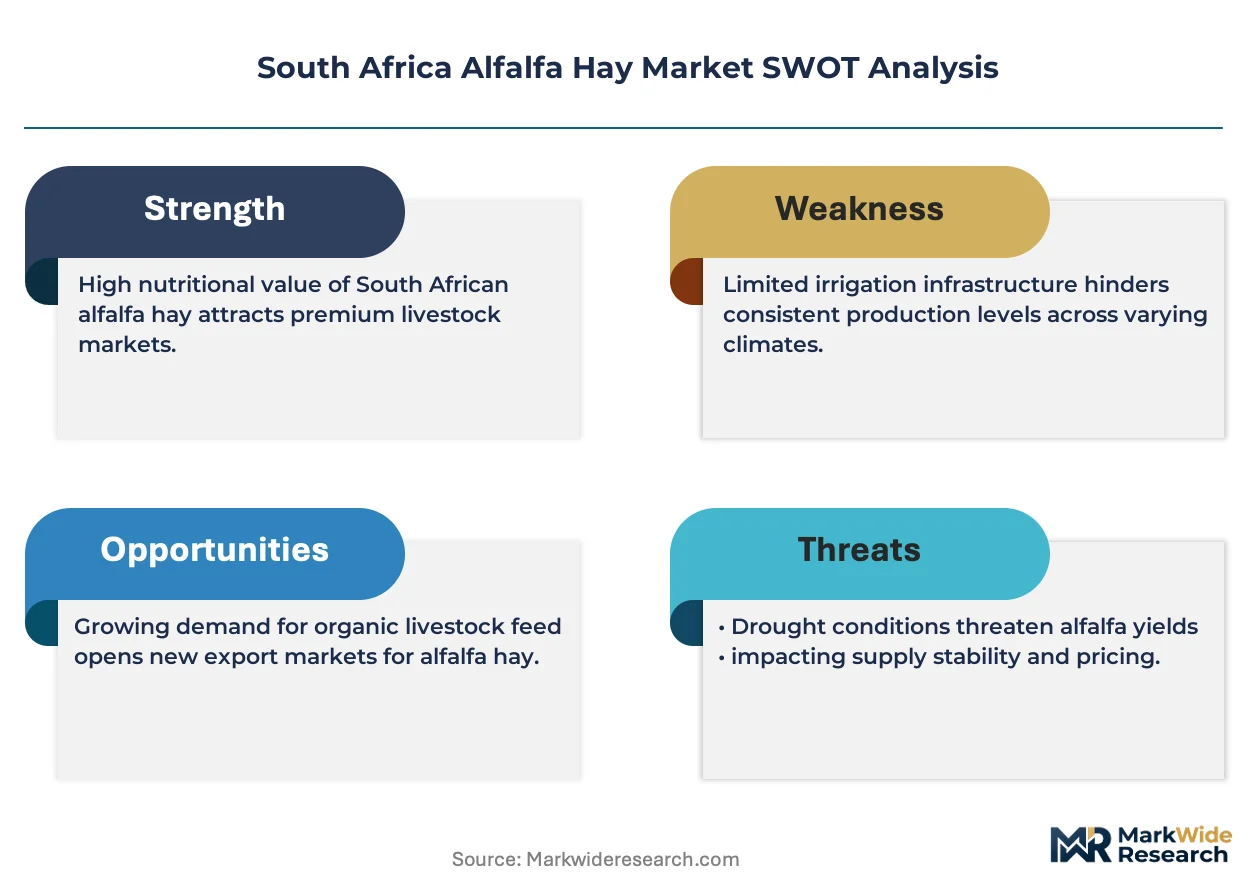
The Fertilizers, Farm Feeds, Seeds and Remedies Act enforcement is compressing informal hay trading channels and elevating capital barriers for baling operations across the Free State and Northern Cape irrigation belts.
Growth Catalysts
- Dairy yield optimization mandates:Western Cape and KwaZulu-Natal milk processors are tightening feed specifications to maximize liters per cow, pulling certified lucerne into contract supply arrangements.
- EU Green Deal sustainability protocols:Export-oriented growers in the Northern Cape are documenting water usage and pesticide residues to access premium Middle Eastern dairy markets.
- Irrigation infrastructure expansion:The Department of Agriculture, Land Reform and Rural Development is channeling capital toward large-scale lucerne cultivation zones in the Free State province.
Market Restraints
- Fuel and fertilizer input volatility:Diesel and urea price swings squeeze margin structures for rain-fed operations in Mpumalanga that lack irrigation buffers.
- Teff grass substitution pressure:Lower-cost teff rations are capturing price-sensitive beef finishing programs in Gauteng feedlots.
- South African Bureau of Standards certification costs:Laboratory verification infrastructure requirements filter out smaller Free State baling operations with limited capital reserves.
Strategic Opportunities
- Equestrian center premium segment:Gauteng and Western Cape equine facilities exhibit low price sensitivity and exacting quality specifications for dust-free, leafy hay.
- Pellet format automation compatibility:Poultry operations are retrofitting handling systems to accommodate densified lucerne products that reduce feed waste.
- Codex Alimentarius alignment pathway:Pretoria's potential harmonization with international feed safety guidelines would unlock Gulf Cooperation Council dairy import channels.
Industry Challenges
- Skilled hay agronomist scarcity:Expertise in cutting timing, moisture management, and bale density optimization is concentrating among legacy operators in the Northern Cape.
- Dehydration equipment capex intensity:Continuous-flow dryers and moisture-controlled storage facilities demand capital outlays that stretch payback periods for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Alfalfa Hay Market |
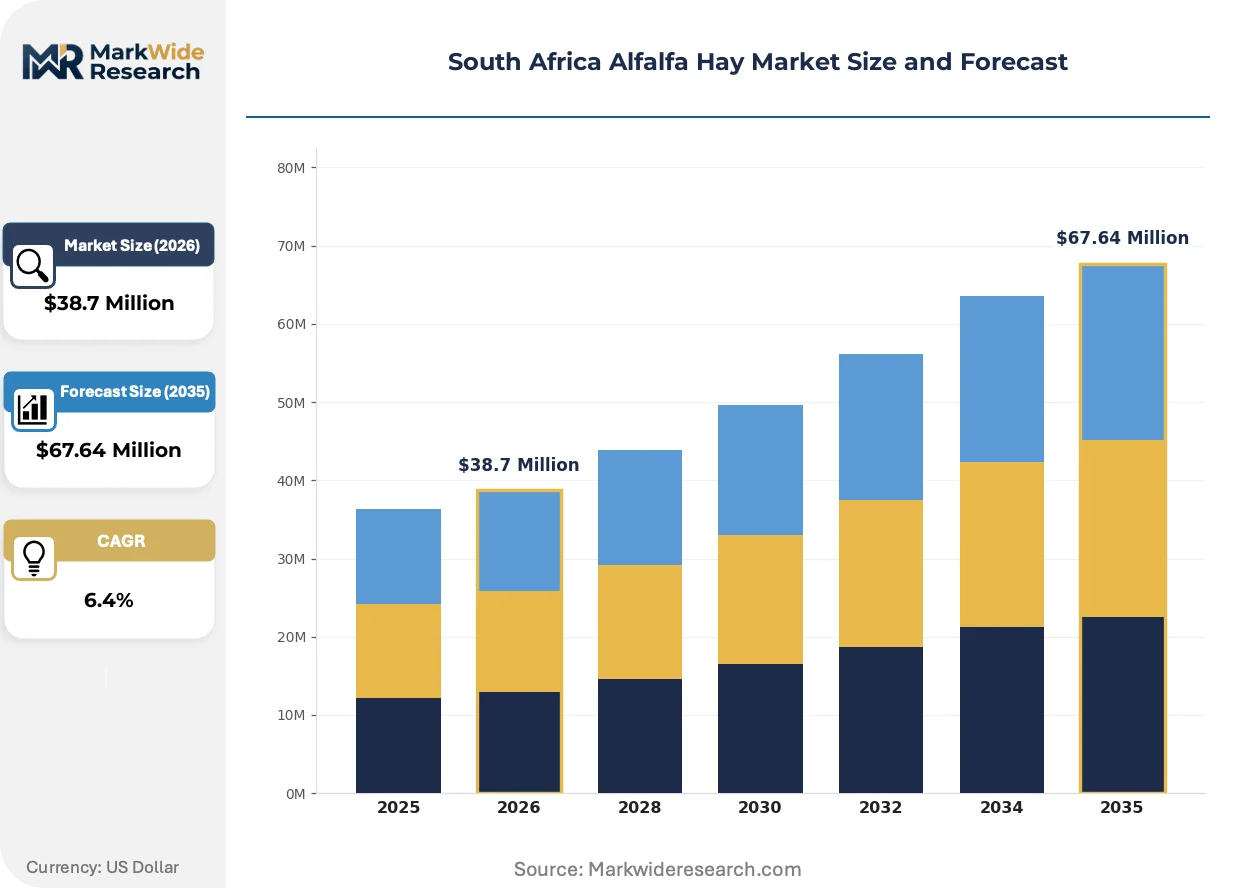
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $67.64 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated, Pelleted, Cubed, Chopped Packaging Type: Bales, Bags, Bulk, Loose End User: Dairy Farms, Livestock Farms, Poultry Operations, Equestrian Centers Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Alpha Alfa (Pty) Ltd, NWK Limited, Afgri Limited, Agritrade Global (Pty) Ltd, Kaap Agri Limited, Senwes Limited, Al Dahra ACX Inc, Grains For Africa (Pty) Ltd, Overberg Agri Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Alfalfa Hay Market Evolving Landscape
Mechanized harvesting and dehydration systems are compressing seasonal labor dependency while regulatory documentation tools are embedding traceability into supply chain transactions.
Precision moisture sensors and automated bale-wrapping systems are absorbing variability in field-cured hay quality. Dairy cooperatives in the Western Cape are deploying these technologies fastest, locking in consistent crude protein retention that underpins premium milk contract pricing. The technology is absorbing price volatility risk for processors who previously rejected variable batches.
The Fertilizers, Farm Feeds, Seeds and Remedies Act labeling mandates are forcing registration compliance that informal traders cannot meet. Commercial processors in the Free State are consolidating documentation systems to satisfy South African Bureau of Standards audits. Dehydrated product tiers face the steepest compliance cost escalation as laboratory verification becomes non-negotiable for registered feed sales.
Contract procurement is replacing spot-market purchasing among large dairy operations. NWK Limited and Afgri Limited are locking growers into multi-season supply agreements with price floors. This pattern concentrates most visibly in Mpumalanga's dairy belt where processor scale justifies dedicated logistics lanes and quality-assured inventory buffers.
South Africa Alfalfa Hay Market Segmentation
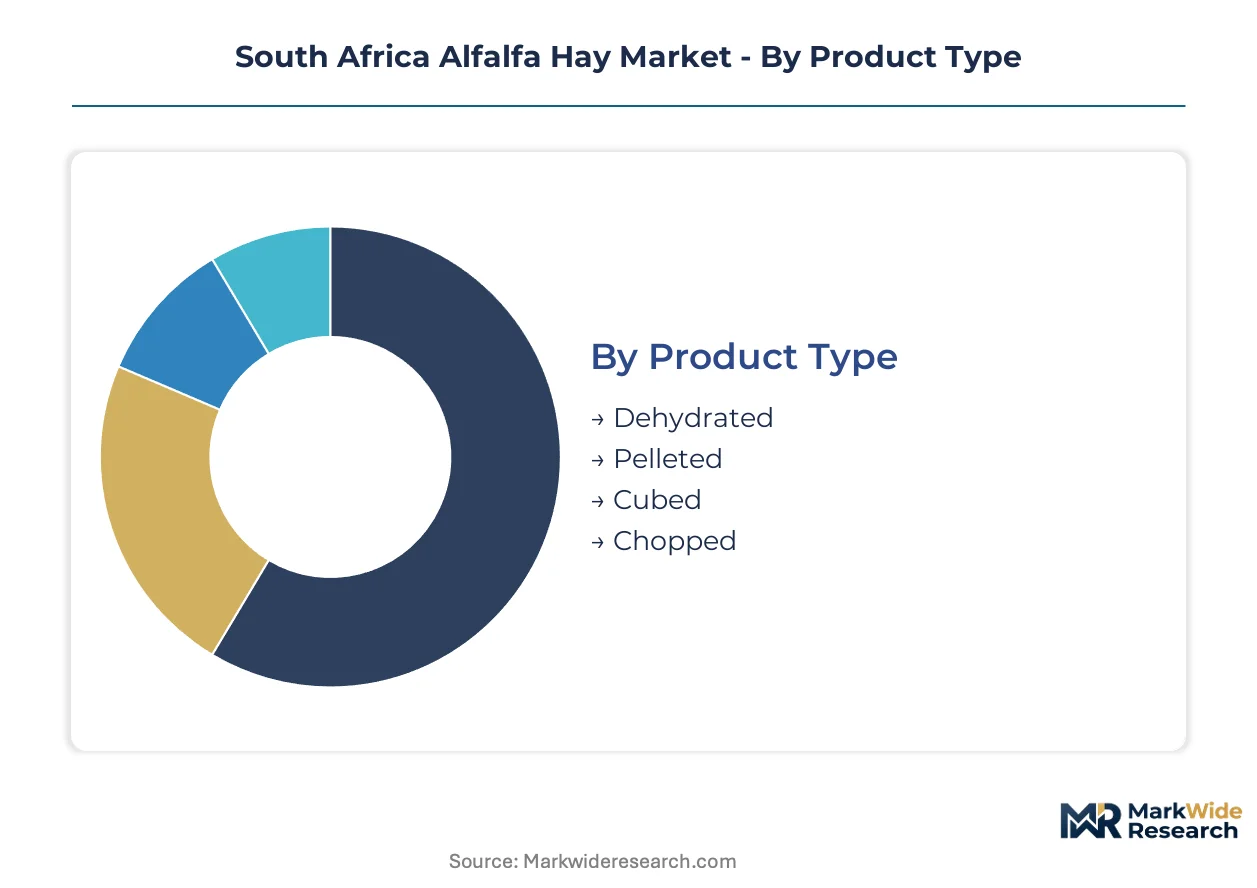
Product format decisions in South Africa's lucerne market hinge on moisture stability, handling automation compatibility, and end-user scale. Dairy processors and feedlot operators select formats based on labor costs, storage constraints, and nutritional consistency requirements.
Product Type:
Processing intensity separates commodity hay from value-added feed products, with dehydration technology determining shelf stability and protein retention.
- Dehydrated:Continuous-flow drying preserves crude protein at 18-22% dry matter while eliminating field-curing weather risk. Western Cape dairy cooperatives specify dehydrated lucerne for milk contract premiums, absorbing higher unit costs for batch consistency.
- Pelleted:Densified 6-8mm cylinders reduce transport volume by 40% and enable automated poultry feeding systems. Gauteng broiler operations are retrofitting handling lines to accommodate pellet formats that cut feed waste.
- Cubed:Compressed 25-50mm blocks suit manual feeding in smaller Mpumalanga beef operations lacking mechanized distribution.
- Chopped:25-50mm cut lengths blend into total mixed rations for Free State feedlot finishing programs.
Mature deployment sits with Dehydrated. Newer deployment is concentrated in Pelleted.
Packaging Type:
Logistics economics and storage infrastructure dictate packaging selection across South Africa's divergent farm scales.
- Bales:Standard 20-25kg rectangular bales dominate commercial dairy procurement in KwaZulu-Natal, where fork-handling equipment is ubiquitous. Weatherproof wrapping and stackability suit on-farm inventory buffers.
- Bulk:Unpackaged loose product moves by pneumatic trailer to large Western Cape feed mills with dedicated receiving hoppers, stripping packaging cost for volume buyers.
- Bags:50kg woven polypropylene suits poultry operations and smallholders in Gauteng requiring moisture protection without bale-handling equipment.
- Loose:Minimal-processing field-cured hay serves price-sensitive Northern Cape sheep farmers with on-site grinding capacity.
Volume concentration rests with Bales. Automation compatibility is climbing fastest in Bulk.
End User:
Species-specific nutritional requirements create distinct quality tiers and pricing power across South African livestock sectors.
- Dairy Farms:High-producing Holstein herds in the Western Cape and KwaZulu-Natal demand 18%+ crude protein with 30% acid detergent fiber for milk yield optimization. Contract procurement with price floors is replacing spot purchasing among processor-aligned operations.
- Equestrian Centers:Gauteng and Western Cape equine facilities specify dust-free, leafy second-cutting hay with low mold counts, accepting 40-60% price premiums over dairy grades. Low price sensitivity and exacting quality standards create a defensible niche.
- Livestock Farms:Free State beef finishing programs balance cost and gain efficiency, with teff grass substituting for lucerne in price-sensitive rations.
- Poultry Operations:Mpumalanga broiler houses incorporate lucerne meal for pigment and fiber, though inclusion rates remain below ruminant applications.
Procurement scale favors Dairy Farms. Margin expansion is steepest in Equestrian Centers.
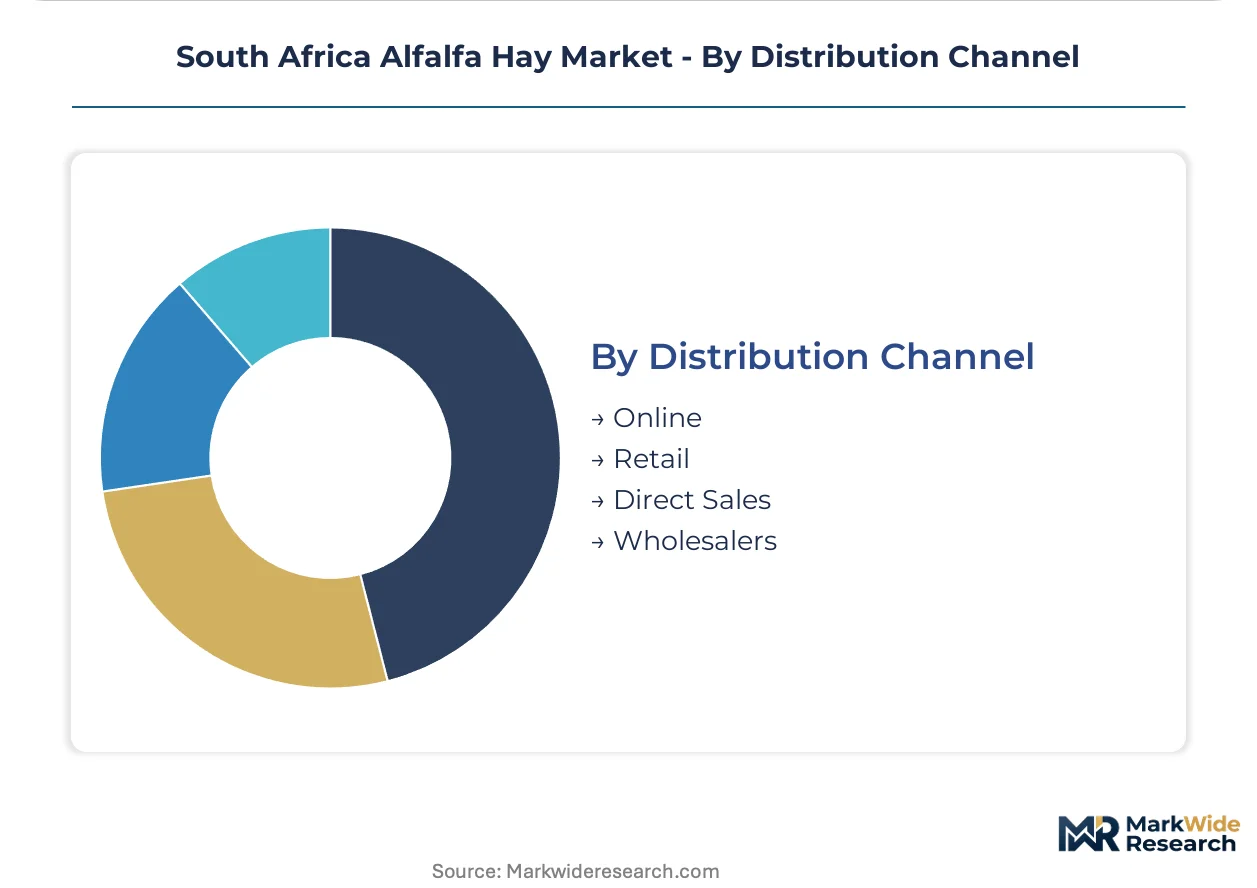
Distribution Channel:
Channel selection reflects buyer scale, geographic isolation, and the Fertilizers, Farm Feeds, Seeds and Remedies Act compliance burden.
- Direct Sales:Large Free State dairy operations source directly from Northern Cape dehydration plants, bypassing margin-stacking intermediaries. Multi-season supply agreements with NWK Limited and Afgri Limited lock in volume and quality specifications.
- Wholesalers:Regional feed merchants aggregate smallholder demand across Mpumalanga and Gauteng, absorbing SABS certification complexity for fragmented buyers.
- Retail:Agri-service stores in peri-urban zones serve hobby farmers and equestrian stables requiring single-bale purchasing flexibility.
- Online:Emerging platforms connect Northern Cape producers with Western Cape buyers, though physical inspection requirements limit penetration for quality-sensitive applications.
Contracted volume flows through Direct Sales. Digital penetration is expanding most quickly in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most heavily in the Free State province, where irrigation infrastructure supports large-scale lucerne cultivation for commercial livestock operations. Dairy processors in the Western Cape and KwaZulu-Natal anchor procurement scale. The Department of Agriculture, Land Reform and Rural Development channels capital toward expanding production zones.
Western Cape
Holstein herds in the Stellenbosch-Paarl corridor drive milk yield optimization mandates that pull certified lucerne into contract supply arrangements. The Department of Agriculture, Land Reform and Rural Development enforces Fertilizers, Farm Feeds, Seeds and Remedies Act labeling standards that filter informal traders. Dehydration plants near Malmesbury supply consistent crude protein batches to processor-aligned cooperatives.
KwaZulu-Natal
Coastal dairy operations in the Midlands region specify 18%+ crude protein hay for high-producing herds. The South African Bureau of Standards certification requirements elevate compliance costs for baling operations entering registered feed channels. Pietermaritzburg-area processors deploy precision moisture sensors to lock in premium milk contract pricing.
Free State
Large-scale beef finishing programs balance lucerne inclusion against teff grass substitution pressure in cost-sensitive rations. The Department of Agriculture, Land Reform and Rural Development irrigation infrastructure expansion targets commercial cultivation zones around Kroonstad and Welkom. Direct procurement from Northern Cape dehydration plants bypasses margin-stacking intermediaries for volume buyers.
Northern Cape
Orange River irrigation schemes enable vertical integration from seed to baled product across controlled cultivation corridors. EU Green Deal sustainability protocols pressure export-oriented growers to document water usage and pesticide residues for Middle Eastern dairy market access. Upington and Kakamas anchor dehydration capacity serving premium dehydrated tiers.
Mpumalanga
Rain-fed operations in the Highveld region face diesel and urea price volatility that squeezes margin structures lacking irrigation buffers. The Fertilizers, Farm Feeds, Seeds and Remedies Act registration mandates filter smaller baling operations with limited laboratory verification capital. Nelspruit-area dairy cooperatives lock growers into multi-season supply agreements with price floors.
South Africa Alfalfa Hay Market Competitive Landscape
Contract procurement dominates the current landscape as large dairy operations replace spot-market purchasing with multi-season supply agreements. The vendor base concentrates around integrated agribusiness groups and regional distribution specialists rather than fragmented independent growers. Three archetypes occupy distinct positions: irrigation-backed vertical integrators controlling seed-to-bale production, grain-and-feed distributors leveraging extensive logistics infrastructure, and input suppliers locking in grower loyalty through technical advisory services. M&A consolidation and geographic expansion through dedicated logistics lanes represent the primary competitive vectors.
Among South Africa-based integrated operators, Alpha Alfa (Pty) Ltd exemplifies the irrigation-backed vertical integrator archetype through its Northern Cape scheme presence. NWK Limited and Afgri Limited occupy positions within the distribution and input supply tiers respectively, with the former anchoring extensive grain-and-feed infrastructure and the latter representing the technical advisory model. These three entities collectively illustrate how scale, integration depth, and service bundling separate sustainable competitors from margin-pressured regional traders.
| Leading Market Players |
|---|
| Alpha Alfa (Pty) Ltd |
| NWK Limited |
| Afgri Limited |
| Agritrade Global (Pty) Ltd |
| Kaap Agri Limited |
| Senwes Limited |
| Al Dahra ACX Inc |
| Grains For Africa (Pty) Ltd |
| Overberg Agri Limited |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainability protocols gate both qualified supply and premium-tier pricing access for South African alfalfa hay exporters, as documentation of water usage and pesticide residues becomes non-negotiable for Middle Eastern dairy market entry while compliant growers command 40-60% premiums over uncertified field-cured product.
Pricing Analysis
The volume-vs-margin split separates commodity field-cured hay from value-added dehydrated tiers, with contract-based long-term offtake dominating large dairy processor procurement. Price differentiation rests on South African Bureau of Standards certification grade and volume scale, with certified dehydrated product capturing premiums while spot-market field-cured product faces cost compression from teff grass substitution. Margins are tightening for rain-fed Mpumalanga operations lacking irrigation buffers. Beef finishing programs exhibit highest price sensitivity; equestrian centers show lowest.
Supply Chain Analysis
Freight economics from Northern Cape dehydration plants to Western Cape dairy cooperatives absorb margin structures, with road transport costs dictating procurement radius. Supply concentrates in South Africa's Northern Cape irrigation schemes and Free State cultivation zones, drawing from diesel, urea, and certified seed inputs. Single-source vulnerability sits with Orange River water allocation dependencies. Distribution runs through direct sales channels for volume buyers and regional wholesalers for fragmented smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fertilizers, Farm Feeds, Seeds and Remedies Act compliance burden creates a barrier-to-entry moat that rewards capitalized processors while filtering informal traders from registered feed channels.
For Market Incumbents: To counter teff grass substitution pressure in price-sensitive beef rations, Alpha Alfa and NWK Limited should deepen backward integration into Northern Cape seed production and expand dehydration capacity near Upington. Locking growers into multi-season supply agreements with price floors secures volume against spot-market volatility. For New Entrants and Emerging Players: Equestrian centers in Gauteng and the Western Cape offer the most penetrable white-space target, with dust-free leafy hay specifications and low price sensitivity supporting premium positioning. A go-to-market angle through specialized agri-service stores serving peri-urban stables bypasses SABS certification complexity absorbed by established distributors. For Investors and Strategic Acquirers: Pretoria's potential Codex Alimentarius alignment is the leading indicator that Gulf Cooperation Council dairy import channels will unlock for compliant South African exporters. Long-term viability favors irrigation-backed vertical integrators with laboratory verification infrastructure already installed. Watch for Department of Agriculture capital allocation signals toward Free State irrigation expansion as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| SABS Certification Investment | Laboratory verification infrastructure filters competitors from registered feed channels under Fertilizers, Farm Feeds, Seeds and Remedies Act enforcement. |
| Backward Integration into Seed Production | Captive supply of certified lucerne genetics secures protein consistency and reduces input cost volatility for dehydration plants. |
| Multi-Season Supply Agreements | Price-floor contracts with Western Cape dairy cooperatives lock in volume and absorb price volatility risk for processor-aligned operations. |
| Equestrian Center Channel Development | Specialized distribution through peri-urban agri-service stores captures 40-60% price premiums with lower certification burden than export tiers. |
| EU Green Deal Compliance Documentation | Water usage and pesticide residue tracking unlocks premium Middle Eastern dairy market access for Northern Cape export-oriented growers. |
Research Methodology
Document review covered South African Bureau of Standards certification records, Department of Agriculture irrigation infrastructure disclosures, and EU Green Deal sustainability protocol documentation, complemented by interviews with dehydration plant operators, dairy cooperative procurement managers, and regional feed distributors. Primary fieldwork with Northern Cape growers and Western Cape processor-aligned cooperatives was validated against customs export data and agricultural input supplier records. Bottom-up volume triangulation against top-down value estimates anchored the analytical framework.
Market size outputs across the projection horizon reflect segmentation by product format, end-user species, and provincial supply cluster, with CAGRs derived from trend extrapolation of dairy herd expansion rates and irrigation infrastructure deployment timelines. Modeled inputs included teff grass substitution elasticities in beef finishing programs and SABS certification cost trajectories for baling operations.
Several conditions sit outside the modeled scope, including drought frequency variations affecting Orange River allocation, rand-dollar exchange volatility impacting export competitiveness, and unannounced amendments to Fertilizers, Farm Feeds, Seeds and Remedies Act enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
North America Bee Products Market