
 Argentina Agricultural Machinery Market | 2026-2036
Argentina Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Agricultural Machinery Market Outlook
The split between premium precision-equipped lines and basic utility models is realigning dealer inventories and manufacturer priorities across Argentina. Deere & Company leverages its integrated precision agriculture platform to capture high-margin contracts with large cooperatives in Córdoba. CNH Industrial N.V. competes through localized assembly and flexible financing terms tailored to mid-scale grain producers. Same Deutz-Fahr anchors its position in the utility tractor segment, sustaining volume through established relationships with family farms in Entre Ríos.
Agricultural machinery encompasses self-propelled and trailed equipment engineered for soil preparation, planting, crop management, and harvesting operations, with power ratings ranging from compact utility tractors below 50 horsepower to combine harvesters exceeding 400 horsepower designed for high-volume grain recovery. Tractors occupy the largest installed base across Argentine farming operations, though autonomous systems and precision agriculture technologies represent the fastest-expanding technology category as GPS-guided auto-steering and variable-rate application systems reduce input waste. Harvesters command concentrated margin pools in the Pampas grain belt, where contractor fleets prioritize throughput capacity and residue management efficiency during narrow seasonal windows.
Argentina's national agricultural technology institute INTA sets field performance protocols that influence equipment specification requirements, while the country's central bank and agricultural secretariat coordinate credit lines that determine machinery acquisition timing for seasonal buyers. The Secretariat of Agriculture, Livestock and Fisheries enforces emission and safety standards that filter imported equipment eligibility, shaping manufacturer product portfolio decisions for the Argentine market. Stakeholders must monitor drought-frequency shifts and corresponding farm-gate income volatility to calibrate fleet investment cycles and inventory exposure.
Market Dynamics
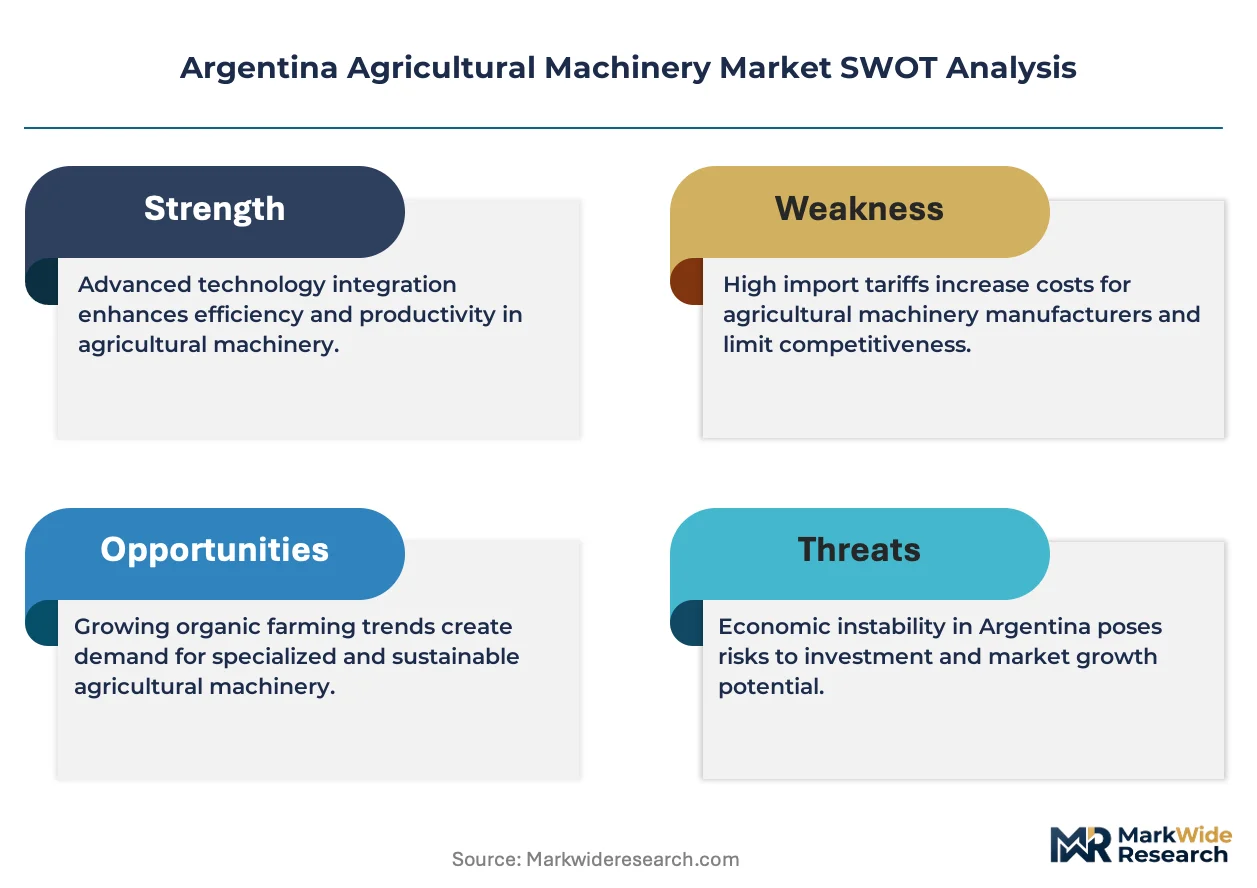
The Argentine agricultural machinery sector pivots on INTA's precision farming mandates, which compel GPS-guided equipment upgrades across the Pampas grain belt and reshape dealer inventory strategies toward telemetry-integrated fleets.
Growth Catalysts
- INTA Precision Protocols:Argentina's national agricultural technology agency mandates field performance standards that accelerate adoption of auto-steering and variable-rate application systems among large-scale soy and corn operations.
- Contractor Fleet Expansion:Corporate farm growth in Buenos Aires and Santa Fe provinces drives concentrated demand for high-horsepower combines and tractors through equipment rental and service providers.
- Central Bank Agricultural Credit Lines:Coordinated financing programs between Argentina's central bank and agricultural secretariat enable seasonal machinery acquisition timing aligned with harvest cash flows.
Market Restraints
- Import Equipment Eligibility Filters:The Secretariat of Agriculture, Livestock and Fisheries enforces emission and safety certification requirements that restrict supplier portfolios and extend product registration timelines.
- Farm-Gate Income Volatility:Drought-frequency shifts in Córdoba and Entre Ríos provinces compress investment cycles and delay fleet renewal decisions among mid-scale grain producers.
- Localized Assembly Dependencies:Flexible financing terms tied to domestic production facilities limit manufacturer pricing autonomy and inventory flexibility during currency fluctuations.
Strategic Opportunities
- Autonomous System Integration:Convergence of GPS-guided auto-steering with telemetry platforms creates white space for equipment-as-a-service models in corporate farming operations.
- Entre Ríos Utility Segment:Family farm consolidation in this underpenetrated province presents volume opportunities for compact tractor and basic implement suppliers.
- Residue Management Efficiency:Narrow seasonal windows in the Pampas grain belt drive demand for advanced harvester technologies that reduce field compaction and improve soil health metrics.
Industry Challenges
- Telemetry Technician Scarcity:Precision agriculture deployment outpaces training infrastructure for GPS calibration and variable-rate system maintenance across dealer networks.
- Legacy Fleet Integration:Retrofitting older tractors with auto-steering compatibility requires complex hydraulic and electronic interface engineering that extends service timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Agricultural Machinery Market |
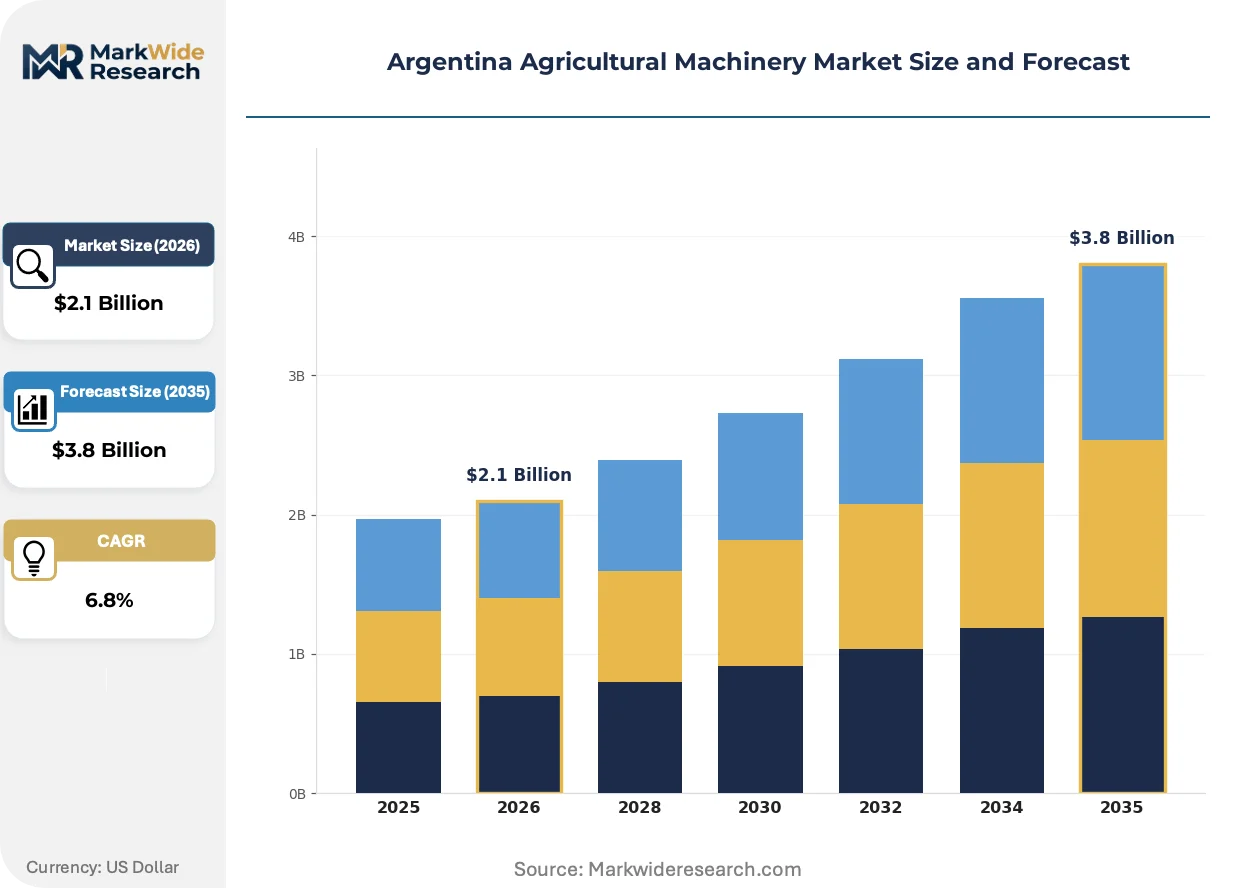
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Technology: Autonomous Systems, Precision Agriculture, GPS, Robotics End User: Farmers, Cooperatives, Agribusinesses, Contractors Application: Crop Production, Soil Preparation, Irrigation, Fertilization |
| Companies Covered | CLAAS KGaA mbH, Agrale S.A., Deere & Company, Yanmar Co. Ltd., Mahindra & Mahindra Limited, CNH Industrial N.V., Kubota Corporation, Same Deutz-Fahr, AGCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Agricultural Machinery Market Strategic Shifts
Telematics platforms are compressing equipment utilization metrics and enabling predictive maintenance models that reshape how Argentine contractors manage seasonal fleet deployment across the Pampas.
Electric drivetrain development for mid-horsepower tractors is electrifying the utility segment, with prototype testing underway among Córdoba-based cooperatives seeking to reduce fuel cost exposure during extended planting windows. Early adopters prioritize battery-swappable architectures that maintain field endurance without charging infrastructure dependency. This electrification is compressing total cost of ownership calculations and forcing recalibration of dealer service training investments.
INTA's field performance protocols now incorporate emission benchmarking that affects imported equipment eligibility determinations under Secretariat of Agriculture enforcement schedules. Manufacturers must submit revised powertrain specifications to maintain market access, with compliance timelines concentrated in the pre-planting procurement season. The grain harvester category faces the steepest certification burden due to engine displacement thresholds and particulate matter standards.
Service unbundling is fragmenting traditional dealer relationships as large Santa Fe contractors negotiate direct parts procurement and third-party maintenance agreements. Equipment manufacturers respond with tiered support packages that separate telemetry access from physical service commitments. This behavioral shift is most pronounced among corporate farming operations with in-house mechanical capabilities and centralized fleet management systems.
Argentina Agricultural Machinery Market Segmentation
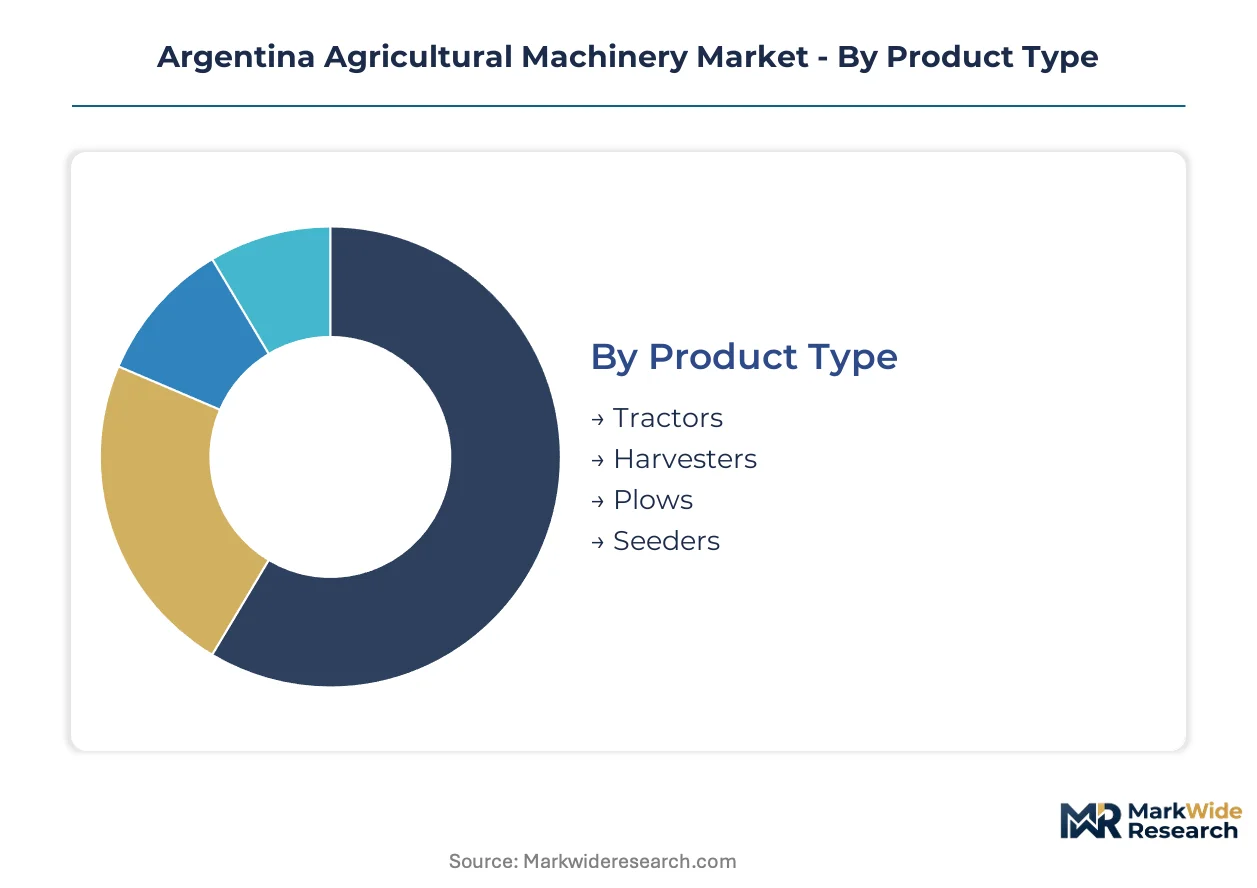
Equipment specification requirements vary sharply across Argentine farming operations, with capital deployment decisions tied directly to farm scale, crop mix, and INTA compliance mandates. Segmentation reveals where precision technology premiums concentrate versus where basic utility models sustain volume.
Product Type:
Tractors and harvesters demand the heaviest capital commitments, with financing structures stretching across multiple harvest cycles to justify acquisition costs.
- Tractors:Power ratings span compact utility units below 50 horsepower to high-horsepower row-crop models exceeding 300 horsepower. Demand concentrates in Buenos Aires and Santa Fe provinces where contractor fleets require versatile traction platforms for multiple implement configurations.
- Harvesters:Self-propelled combines designed for high-volume grain recovery dominate margin pools in the Pampas belt, with throughput capacity and residue management efficiency prioritized during narrow seasonal windows.
- Plows:Trailed implements for primary tillage operations serve soil preparation protocols across Córdoba's expanding soy rotations.
- Seeders:Precision planting equipment aligns with INTA variable-rate mandates, particularly for corn operations requiring population density control.
Tractors absorb the bulk of installed capacity; harvesters are expanding most quickly through contractor fleet upgrades.
Technology:
Technology tiering separates premium-positioned operations from cost-constrained adopters, with retrofit complexity creating stickiness for integrated platform decisions.
- Autonomous Systems:GPS-guided auto-steering platforms with telemetry integration command premium positioning among large cooperatives. Adoption concentrates in corporate farming operations seeking labor efficiency gains during extended planting windows.
- Precision Agriculture:Variable-rate application systems for seed, fertilizer, and crop protection inputs reduce waste and align with INTA field performance protocols.
- GPS:Satellite positioning infrastructure enables auto-steering compatibility across tractor and harvester fleets.
- Robotics:Early-stage deployment targets specialized crop management tasks with limited commercial scale in current Argentine operations.
Precision agriculture platforms anchor current investment cycles; autonomous systems are gaining share fastest through equipment-as-a-service models.
End User:
Customer scale determines financing access, fleet turnover velocity, and sensitivity to farm-gate income volatility across procurement cycles.
- Farmers:Family operations in Entre Ríos and southern Buenos Aires provinces sustain demand for compact tractors and basic implements, with acquisition timing tied to harvest cash flow availability.
- Cooperatives:Córdoba-based grain pools concentrate demand for high-horsepower equipment and integrated precision platforms, leveraging collective bargaining power for favorable financing terms.
- Agribusinesses:Corporate farming operations in the Pampas core prioritize throughput capacity and telemetry-enabled fleet management.
- Contractors:Equipment rental and service providers in Santa Fe maintain seasonal deployment fleets optimized for rapid field coverage.
Farmers represent the deepest installed base; agribusinesses show the steepest expansion trajectory through consolidation-driven fleet standardization.
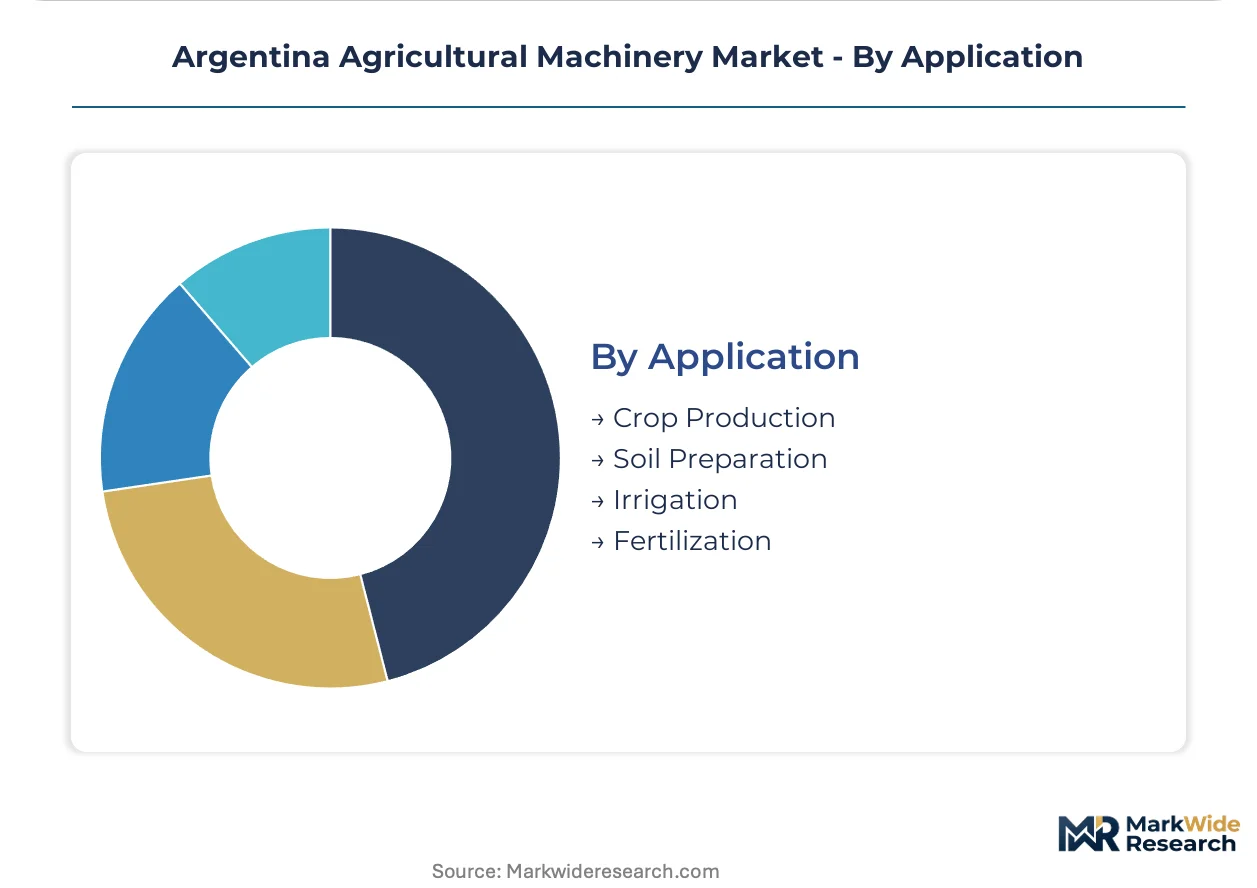
Application:
Operational phase sequencing shapes equipment utilization rates and determines which machinery categories face replacement pressure.
- Crop Production:Harvesting and grain handling operations command concentrated investment in combines and transport equipment, with residue management specifications tightening under INTA soil health protocols.
- Soil Preparation:Tillage and seedbed operations require tractor-implement combinations with hydraulic capacity matched to Pampas soil conditions.
- Irrigation:Center-pivot and drip systems serve specialized crop zones in western Buenos Aires and La Pampa provinces with limited penetration in rain-fed grain belts.
- Fertilization:Variable-rate application equipment aligns with precision agriculture mandates for nutrient management efficiency.
Soil preparation absorbs the bulk of mechanical horsepower deployment; crop production applications are climbing the fastest through precision technology upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pampas grain belt surrounding Buenos Aires anchors Argentina's agricultural machinery deployment, with contractor fleets and corporate operations driving concentrated equipment turnover in this high-productivity corridor.
Buenos Aires Province
Large-scale soy and corn operations dominate machinery procurement cycles, with seasonal planting windows compressing fleet utilization metrics. The Secretariat of Agriculture, Livestock and Fisheries enforces emission certification requirements that filter imported combine harvester eligibility. The Azul-Las Flores corridor concentrates contractor service providers managing high-horsepower equipment pools for corporate farming clients.
Santa Fe Province
Equipment rental and service providers sustain seasonal deployment fleets optimized for rapid field coverage during narrow harvest windows. Central Bank agricultural credit lines coordinate financing availability with harvest cash flow timing. The Rosario hinterland hosts dense networks of machinery dealerships serving expanding grain export operations.
Córdoba Province
Grain cooperatives concentrate demand for integrated precision agriculture platforms and GPS-guided auto-steering systems. INTA field performance protocols mandate telemetry compatibility for equipment operating in government-monitored demonstration zones. The Marcos Juárez-Villa María axis anchors high-horsepower tractor distribution to collective farming enterprises.
Entre Ríos Province
Family farm consolidation sustains volume demand for compact utility tractors below 50 horsepower and basic tillage implements. Farm-gate income volatility from drought-frequency shifts compresses investment cycles among mid-scale producers. The Paraná-Concordia region maintains established dealer relationships with utility-focused equipment suppliers.
La Pampa Province
Expanding irrigation infrastructure in western districts creates specialized demand for center-pivot compatible machinery configurations. Soil health protocols under INTA residue management standards influence harvester specification requirements. The Santa Rosa-San Luis corridor attracts precision equipment trials for semi-arid cropping system adaptations.
Argentina Agricultural Machinery Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a market structure that consolidates around integrated platform providers while fragmenting among specialized implement fabricators. The vendor base stratifies into three tiers: multinational precision-technology leaders, regional assembly specialists leveraging localized production for financing flexibility, and utility-focused family farm suppliers. Dominant competitive moves include portfolio diversification into telemetry-integrated service packages and geographic expansion through contractor fleet partnerships in high-volume grain belts.
Within the precision-technology tier, Deere & Company and CNH Industrial N.V. exemplify multinational platform providers competing for high-margin contracts with large cooperatives and corporate farming operations. Same Deutz-Fahr occupies a position anchoring the utility tractor segment through established distribution relationships with family-scale producers. These three archetypes represent the competitive spectrum from premium integrated systems to volume-driven basic equipment, with each player sitting within distinct financing and service bundling strategies tailored to Argentine procurement cycles.
| Leading Market Players |
|---|
| CLAAS KGaA mbH |
| Agrale S.A. |
| Deere & Company |
| Yanmar Co. Ltd. |
| Mahindra & Mahindra Limited |
| CNH Industrial N.V. |
| Kubota Corporation |
| Same Deutz-Fahr |
| AGCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Contractor fleet concentration in Santa Fe and Buenos Aires provinces anchors value-based pricing models where equipment throughput capacity determines contract rates. This buyer archetype's procurement power compresses margin structures for manufacturers while rewarding telemetry-integrated platforms that demonstrate measurable fuel and labor savings.
Pricing Analysis
Throughput-linked value pricing dominates combine harvester and high-horsepower tractor segments, with Santa Fe contractors paying premiums for verified bushel-per-hour performance. Price differentiation rests on INTA certification tiers and telemetry bundling depth, with GPS-guided auto-steering packages commanding substantial uplifts over basic mechanical configurations. Pricing pressure stems from Central Bank credit line volatility that delays seasonal procurement timing and squeezes dealer working capital. Family farms in Entre Ríos exhibit acute price sensitivity, while Córdoba cooperatives absorb premium positioning for integrated precision platforms.
Supply Chain Analysis
Dual-sourcing requirements for engine and hydraulic component qualification are reshaping supplier relationships across Argentine assembly operations. Manufacturing inputs draw from Brazil, Italy, and China for powertrain assemblies, precision electronics, and structural steel components. Raw material dependencies center on high-grade steel alloys, semiconductor chips for GPS modules, and specialized tires for Pampas soil conditions. Tariff exposure on Brazilian-sourced engines creates margin vulnerability during currency fluctuations. Distribution runs through manufacturer-owned dealerships in Buenos Aires and Santa Fe, with independent agents serving Entre Ríos and La Pampa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into telemetry software and captive financing arms is accelerating as manufacturers seek margin defense against service unbundling trends. Control over data platforms and credit terms represents the decisive upstream-downstream lever in this procurement cycle.
For Market Incumbents: Lock in telemetry platform stickiness through multi-year service contracts that bundle predictive maintenance with equipment leases. Backward integration into precision electronics sourcing reduces exposure to semiconductor supply constraints. Defend against Same Deutz-Fahr's utility segment expansion by capturing Entre Ríos dealer relationships before consolidation accelerates. For New Entrants and Emerging Players: The mid-tier pricing gap between Deere's premium precision platforms and basic utility tractors offers white-space entry through simplified auto-steering retrofit kits. Target underpenetrated La Pampa irrigation districts with semi-arid specialized equipment configurations. Pursue equipment-as-a-service partnerships with emerging corporate farming operations seeking fleet flexibility without capital deployment. For Investors and Strategic Acquirers: The window for entry favors telemetry-integrated mid-cap specialists with established INTA compliance track records. Long-term viability hinges on software-defined service revenue streams displacing transactional equipment sales. Watch drought-frequency indices in Córdoba and Entre Ríos as the signal for fleet renewal cycle timing and credit line availability.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | INTA-mandated GPS protocols create recurring revenue through subscription-based precision agriculture services. |
| Localized Assembly Expansion | Domestic production facilities unlock Central Bank credit line access and reduce import certification timelines. |
| Residue Management Technology | Soil health protocols in the Pampas grain belt drive harvester specification requirements and replacement cycles. |
| Equipment-as-a-Service Models | Corporate farming consolidation favors rental structures that transfer utilization risk to manufacturers. |
| Electric Drivetrain Development | Battery-swappable tractor prototypes address fuel cost volatility for Córdoba cooperative early adopters. |
Study Parameters
Document review covered customs and trade data, SEC filings from listed equipment manufacturers, and INTA technical bulletins, complemented by interviews with machinery dealership principals, fleet managers at Santa Fe contractor operations, and agricultural credit officers at Argentina's Central Bank. Primary fieldwork engaged precision agriculture technicians, cooperative procurement committees in Córdoba, and aftermarket parts distributors. Secondary validation drew from machinery registration databases, harvest yield statistics, and emission certification records. Bottom-up equipment unit economics and top-down sector expenditure estimates were triangulated to anchor market sizing.
Cross-referencing historical procurement patterns against panel input from financing coordinators enabled projection calibration across the analysis window. Segmentation modeling incorporated product type, technology tier, end-user scale, and application phase dimensions. CAGRs were derived from equipment replacement cycle analysis and credit availability trajectories. Forecast inputs included INTA protocol implementation schedules, drought-frequency probability distributions, and contractor fleet expansion plans.
Inputs from Central Bank agricultural credit departments and INTA field stations were available through the study window; gaps in real-time farm-gate income data introduce uncertainty bands around seasonal procurement timing assumptions. Forecasts reflect documented assumptions regarding credit line continuity and emission certification enforcement schedules. Deviation in drought severity or currency volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market